
 Germany Packaging Market | 2026-2036
Germany Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Packaging Market Insights
Multi-source procurement among German brand owners is expanding as sustainability compliance complexity outstrips in-house material science capabilities. Mondi plc leverages its integrated paper and pulp network to anchor supply security for corrugated and kraft-based formats across Central Europe. Smurfit WestRock plc competes through containerboard scale and recycling infrastructure density. Constantia Flexibles GmbH specializes in pharmaceutical blister and strip packaging, sustaining margin pools through barrier film expertise and cleanroom manufacturing standards.
Germany packaging encompasses the design, engineering, and production of protective and promotional enclosures using materials such as polyethylene terephthalate with oxygen transmission rates below 0.1 cc per square meter per day, oriented polypropylene films, and borosilicate glass vials with thermal shock resistance exceeding 160 degrees Celsius, primarily serving product preservation, shelf-life extension, and regulatory compliance for consumer and industrial goods. Flexible packaging leads volume contribution due to lightweighting advantages and e-commerce logistics efficiency, though rigid glass formats command premium positioning in pharmaceutical parenteral applications where Gerresheimer AG maintains technology leadership. Metal packaging, particularly aluminum aerosol and beverage cans produced by Ball Corporation and Crown Holdings, occupies a mature growth trajectory tied to circular economy mandates and deposit-return scheme participation rates.
The EU Packaging and Packaging Waste Regulation, Germany's Verpackungsgesetz implementing extended producer responsibility, and REACH chemical compliance administered by ECHA collectively mandate minimum recycled content thresholds and restrict certain single-use plastic formats, redirecting R&D investment toward mono-material structures and bio-based barrier coatings. KBA transport safety protocols for dangerous goods packaging add a secondary compliance layer for chemical and industrial drum segments where SCHÜTZ GmbH & Co. KGaA dominates intermediate bulk container certification. Stakeholders must monitor how delegated acts under the EU regulation define recyclability performance grades, as these definitions will determine which material platforms qualify for green public procurement preferences and brand owner volume commitments.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing German converters to abandon multi-material laminates in favor of mono-material or fiber-based structures, compressing equipment amortization cycles and redirecting capital toward extrusion coating and dry-molded fiber lines.
Growth Catalysts
- Verpackungsgesetz EPR mandates:Extended producer responsibility obligations require brand owners to fund collection infrastructure, accelerating demand for design-for-recycling formats that simplify post-consumer sorting.
- Pharmaceutical serialization:EU Falsified Medicines Directive compliance drives investment in tamper-evident blister packs and track-and-trace-enabled secondary packaging for prescription drugs.
- Bavaria chemical corridor concentration:BASF and Bayer manufacturing clusters sustain demand for UN-certified intermediate bulk containers and barrier drum formats serving agrochemical and specialty chemical exports.
Market Restraints
- Recycled polymer feedstock scarcity:rPET flake and food-grade rPP availability constraints inflate input costs for converters seeking to meet minimum recycled content thresholds under EU delegated acts.
- Barrier coating technical limitations:Current water-based and bio-based oxygen barrier coatings fail to match metallized film performance for sensitive food applications, restricting material substitution in ambient shelf-stable categories.
- Deposit-return scheme infrastructure lock-in:Germany's DPG Pfandsystem for beverage packaging creates path dependency for reusable glass and aluminum formats, slowing flexible pouch penetration in liquid categories.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Cell and gene therapy logistics demand validated temperature-controlled packaging solutions, opening premium segments for phase-change material shippers and reusable thermal containers.
- E-commerce right-sizing algorithms:Machine learning-driven box optimization reduces void fill consumption and dimensional weight charges, creating software-hardware bundling opportunities for corrugated producers serving omnichannel retailers.
- Bio-based barrier convergence:Algae-derived coatings combined with nanocellulose substrates offer compostable alternatives to conventional plastics for fresh produce applications.
Industry Challenges
- Cleanroom manufacturing talent scarcity:Pharmaceutical packaging expansion requires operators trained in ISO 14644-1 Class 7/8 environments, with technical institutes struggling to graduate sufficient qualified personnel.
- Legacy extrusion asset stranding:Multi-layer coextrusion lines configured for incompatible material combinations face accelerated obsolescence as recyclability performance grades tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Packaging Market |
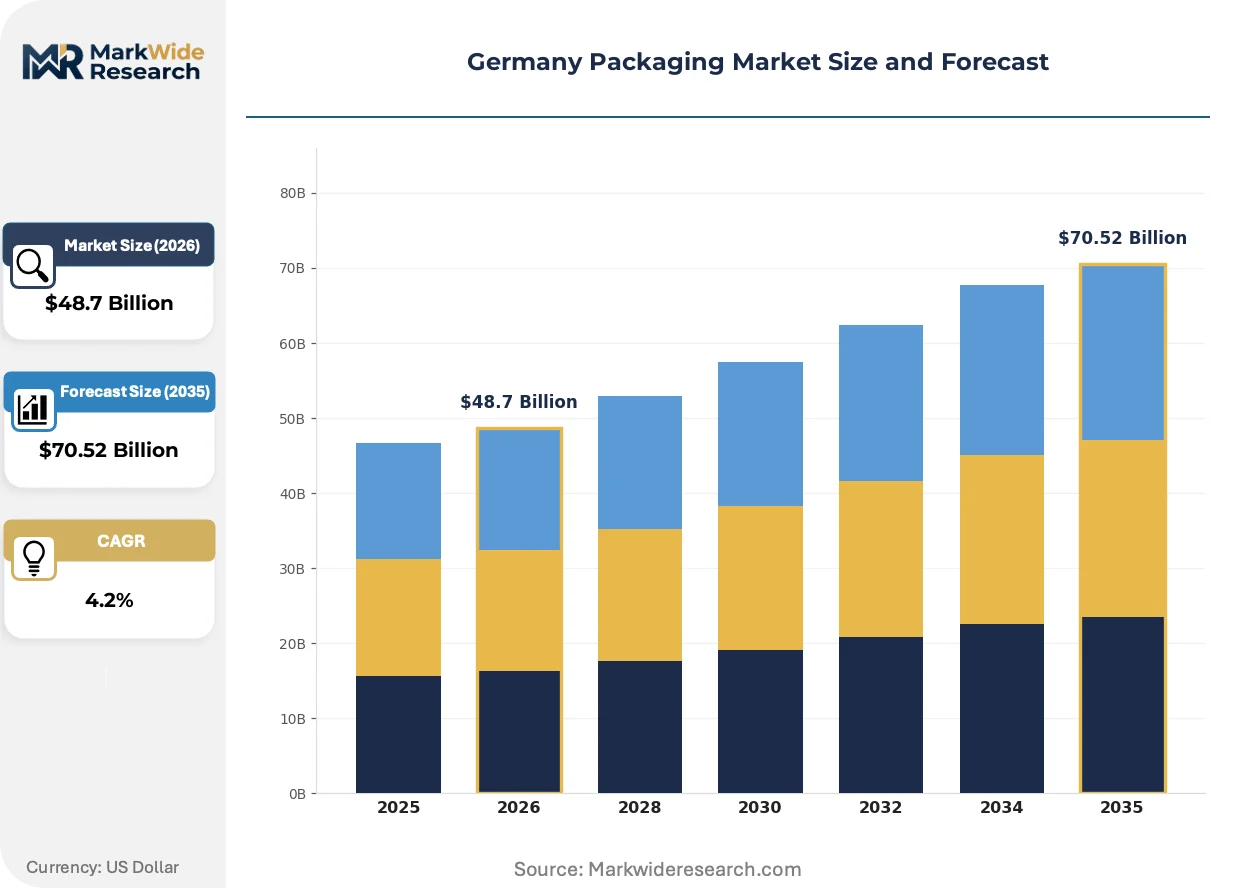
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Rigid Containers, Labels Material: Plastic, Paper, Glass, Metal End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Packaging Type: Bottles, Bags, Boxes, Cartons |
| Companies Covered | Amcor plc, Mondi plc, Smurfit WestRock plc, Ball Corporation, Gerresheimer AG, Ardagh Group S.A., Crown Holdings, Inc., SCHÜTZ GmbH & Co. KGaA, Constantia Flexibles GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Packaging Market Trends and Innovations
Digital printing and artificial intelligence are compressing packaging development timelines while regulatory stringency forces material science breakthroughs. These intersecting pressures favor converters with in-house R&D capabilities and direct brand owner relationships.
Digital flexographic and inkjet systems are automating short-run production changeovers that previously required hours of plate mounting and color matching. Pharmaceutical and craft beverage brand owners now specify lot sizes below five thousand units, rewarding converters with zero-die-change workflows. This technology is automating the economics of versioning and personalization that analog processes could not support profitably.
REACH chemical compliance administered by ECHA now restricts per- and polyfluoroalkyl substances in food contact materials, eliminating oil-and-grease-resistant coatings from paperboard applications. German converters are qualifying silicone-based and bio-wax alternatives for bakery and fast-food packaging. The snack food segment faces the steepest reformulation timeline, with reform deadlines compressing supplier qualification windows.
Brand owners in North Rhine-Westphalia are consolidating supplier panels from fifteen-plus converters to three strategic partners capable of delivering design, material science, and regulatory documentation as integrated service bundles. This concentration displaces transactional spot purchasing for standard corrugated and flexible formats. The food and personal care verticals exhibit the most aggressive panel rationalization, driven by procurement cost benchmarking and ESG reporting consolidation needs.
Germany Packaging Market Segmentation
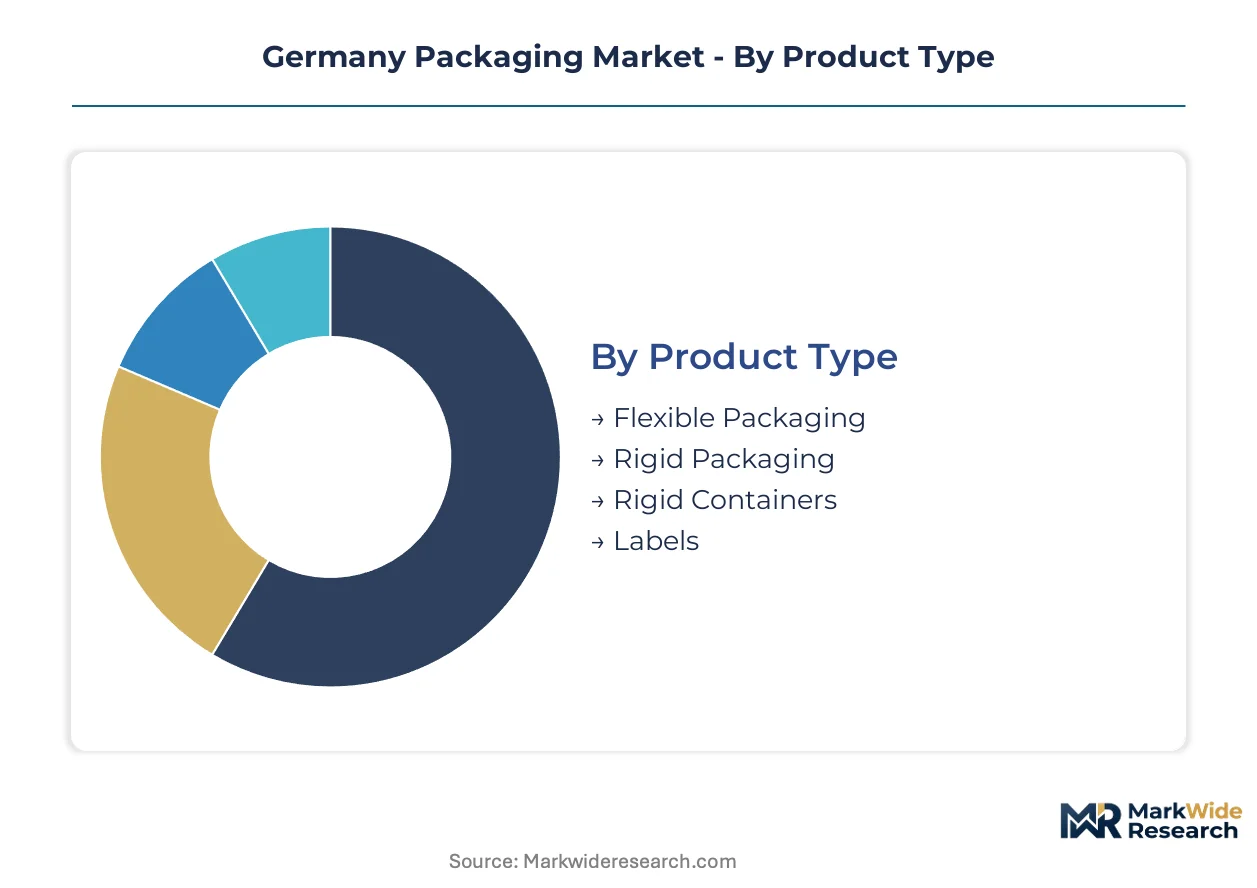
German packaging procurement increasingly segments by recyclability performance grades rather than pure cost optimization. Brand owners now structure supplier panels around material science capabilities that satisfy ECHA REACH compliance and Verpackungsgesetz extended producer responsibility mandates.
Product Type:
Flexible formats dominate volume through lightweighting advantages in e-commerce logistics, while rigid structures command premium positioning in regulated pharmaceutical applications.
- Flexible Packaging:Multi-layer films and pouches constructed from oriented polypropylene and polyethylene terephthalate laminates achieve oxygen transmission rates below 0.1 cc per square meter per day. Demand concentrates in Bavaria's food processing corridor where shelf-life extension drives specification toward high-barrier metallized structures. Verpackungsgesetz mandates are accelerating mono-material substitution that simplifies post-consumer sorting infrastructure.
- Rigid Packaging:Injection-molded and thermoformed containers in polypropylene and polyethylene serve dairy, ready-meal, and personal care segments with dimensional stability exceeding flexible alternatives. North Rhine-Westphalia's chemical industry sustains drum and intermediate bulk container demand certified under KBA transport safety protocols for dangerous goods.
- Rigid Containers:Borosilicate glass vials with thermal shock resistance exceeding 160 degrees Celsius anchor parenteral pharmaceutical applications. Gerresheimer AG maintains technology leadership in this segment through ISO 14644-1 Class 7 cleanroom manufacturing standards.
- Labels:Pressure-sensitive and shrink-sleeve formats incorporate RFID inlays and serialization codes for EU Falsified Medicines Directive compliance. Craft beverage brand owners in Berlin and Hamburg specify short-run digital printing for versioning below five thousand units.
Mature deployment sits with rigid containers in pharmaceutical serialization. Newer deployment is concentrated in flexible packaging's transition toward design-for-recycling formats.
Material:
Cost tier stratification separates premium bio-based barrier coatings from commodity virgin polymers facing recycled content mandates.
- Plastic:rPET flake and food-grade rPP availability constraints inflate input costs for converters seeking EU delegated act compliance. Multi-layer coextrusion lines configured for incompatible material combinations face accelerated obsolescence as recyclability performance grades tighten.
- Paper:Kraft and containerboard formats benefit from Mondi plc's integrated pulp network anchoring supply security across Central Europe. Dry-molded fiber lines are capturing capital allocation previously directed toward plastic extrusion as fiber-based alternatives displace single-use formats.
- Glass:Reusable bottle systems dominate Germany's DPG Pfandsystem deposit-return infrastructure, creating path dependency that slows flexible pouch penetration in beverage categories. Gerresheimer AG's borosilicate technology sustains margin pools in parenteral applications where thermal stability is non-negotiable.
- Metal:Aluminum aerosol and beverage cans produced by Ball Corporation and Crown Holdings occupy mature growth trajectories tied to circular economy mandates. Circular aluminum commands premium positioning through infinite recyclability without property degradation.
Volume leadership belongs to plastic despite regulatory headwinds. Steepest expansion trajectory is concentrated in paper as extrusion coating and dry-molded fiber capacity scales.
End User:
Application-driven specification divergence separates pharmaceutical cleanroom requirements from food contact material compliance.
- Food & Beverage:Snack and bakery segments face the steepest reformulation timeline as ECHA REACH restrictions eliminate per- and polyfluoroalkyl substances from oil-and-grease-resistant paperboard coatings. Silicone-based and bio-wax alternatives are qualifying through compressed supplier windows.
- Pharmaceuticals:EU Falsified Medicines Directive compliance drives tamper-evident blister packs and track-and-trace-enabled secondary packaging. Cell and gene therapy logistics are opening premium segments for phase-change material shippers and reusable thermal containers.
- Cosmetics:Premium positioning in personal care verticals exhibits aggressive supplier panel rationalization from fifteen-plus converters to three strategic partners capable of delivering integrated design and ESG documentation bundles.
- Chemicals:BASF and Bayer manufacturing clusters in Bavaria sustain demand for UN-certified intermediate bulk containers and barrier drum formats serving agrochemical and specialty chemical exports.
Margin concentration sits with pharmaceuticals through barrier film expertise. Fastest volume expansion is occurring in food and beverage as e-commerce right-sizing algorithms reduce void fill consumption.
Packaging Type:
Customer type stratification separates industrial procurement of standardized formats from brand owner demand for versioning and personalization capabilities.
- Bottles:PET and HDPE blow-molded containers serve beverage, personal care, and pharmaceutical liquid applications. Deposit-return scheme infrastructure lock-in preserves reusable glass and aluminum format dominance in German beverage categories.
- Bags:Flexible pouches and stand-up bags achieve logistics efficiency through cube utilization advantages over rigid alternatives. E-commerce penetration is driving demand for mailer-compatible dimensions and tear-resistant constructions.
- Boxes:Corrugated formats from Smurfit WestRock plc compete through containerboard scale and recycling infrastructure density. Machine learning-driven box optimization creates software-hardware bundling opportunities for omnichannel retailers.
- Cartons:Folding carton and liquid board applications face material substitution pressure as fiber-based alternatives capture share from multi-material laminates. Digital flexographic systems automate short-run changeovers for craft beverage versioning.
Supply security concentrates in boxes through integrated paper networks. Emerging specification complexity is concentrated in bags as brand owners demand compostable alternatives for fresh produce applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging demand concentrates in industrial corridors where pharmaceutical, chemical, and food processing clusters anchor regional production capacity. Bavaria's manufacturing belt and North Rhine-Westphalia's chemical corridor sustain disproportionate procurement volumes. Verpackungsgesetz implementation varies across state-level waste management infrastructure.
Bavaria
Pharmaceutical blister packaging and chemical intermediate bulk containers drive specification complexity in this southern industrial belt. KBA transport safety protocols govern UN-certified drum formats serving BASF and Bayer export operations. Munich and Nuremberg anchor cleanroom manufacturing clusters for barrier film production.
North Rhine-Westphalia
Supplier panel consolidation from fifteen-plus converters to three strategic partners accelerates in this western chemical heartland. ECHA REACH compliance documentation requirements reshape procurement relationships. Düsseldorf and Cologne host brand owner headquarters demanding integrated ESG reporting bundles.
Baden-Württemberg
Automotive component packaging and precision engineering formats sustain demand for vacuum-sealed barrier solutions. The state's dual vocational training system feeds technical talent into pharmaceutical cleanroom operations. Stuttgart's industrial periphery concentrates dry-molded fiber equipment investments.
Lower Saxony
Food processing corridors around Hannover drive flexible pouch specifications for meat and dairy applications. Deposit-return scheme infrastructure for beverage packaging creates format lock-in for reusable glass systems. The region's logistics hubs prioritize cube-optimized corrugated formats for e-commerce fulfillment.
Hamburg
Port-centric packaging demand centers on export-oriented chemical drum certification and temperature-controlled pharmaceutical logistics. Northern Germany's recycling infrastructure density supports rPET flake sourcing for converters meeting EU delegated act thresholds. The metropolitan area specializes in short-run digital printing for craft beverage versioning.
Germany Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters redirect capital toward extrusion coating and dry-molded fiber lines. The vendor base exhibits tiered consolidation with integrated pulp-to-packaging networks occupying supply security positions. Three archetypes define competitive positioning: integrated paper producers, pharmaceutical barrier specialists, and metal packaging scale operators. M&A activity and strategic partnerships concentrate around mono-material R&D capabilities and recycling infrastructure access.
Within the integrated paper tier, Mondi plc and Smurfit WestRock plc exemplify supply security strategies through captive pulp networks and containerboard scale. Among pharmaceutical barrier specialists, Gerresheimer AG occupies a position defined by cleanroom manufacturing standards and borosilicate thermal stability expertise. These three entities represent distinct competitive vectors—fiber-based substitution, corrugated logistics optimization, and parenteral pharmaceutical protection—each responding to Verpackungsgesetz and EU Packaging and Packaging Waste Regulation compliance pressures.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi plc |
| Smurfit WestRock plc |
| Ball Corporation |
| Gerresheimer AG |
| Ardagh Group S.A. |
| Crown Holdings, Inc. |
| SCHÜTZ GmbH & Co. KGaA |
| Constantia Flexibles GmbH |
| Others |
Pricing and Supply Chain Analysis
Brand owner consolidation from fifteen-plus converters to three strategic partners in North Rhine-Westphalia anchors contract-based pricing with bundled ESG documentation and regulatory compliance services. This procurement concentration shifts pricing power toward integrated suppliers capable of delivering material science expertise alongside commodity formats.
Pricing Analysis
Warranty and technical service bundling separates premium-tier suppliers from transactional spot vendors in corrugated and flexible formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ISO 14644-1 cleanroom compliance commands substantial premiums in pharmaceutical blister packaging. Cost compression in commodity flexible films intensifies because recycled polymer feedstock scarcity inflates rPET and rPP input costs. Small and mid-size food processors exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize barrier performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Nordic pulp suppliers feeding Mondi plc's integrated Central European network, creating exposure to Nordic energy cost volatility and maritime logistics disruption. Raw material procurement draws from Swedish and Finnish pulp mills, German rPET flake recyclers, and Austrian extrusion coating resin suppliers. Supply chain risk centers on KBA transport safety certification bottlenecks for UN-certified intermediate bulk containers serving Bavaria's chemical exports. Distribution runs through converter-direct relationships with brand owner headquarters clusters in Düsseldorf, Hamburg, and Munich, supplemented by regional logistics hubs serving omnichannel retail fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Packaging Market operates as a cost-of-compliance arena where EU Packaging and Packaging Waste Regulation delegated acts erect substantial barrier-to-entry moats for players with pre-positioned mono-material R&D and recycling infrastructure access.
For Market Incumbents: Lock in brand owner panel consolidation momentum by acquiring dry-molded fiber equipment operators in Baden-Württemberg and Bavaria before capacity scarcity materializes. Defend against emerging bio-based barrier coating specialists by deepening captive pulp network integration and accelerating extrusion coating line commissioning. Prioritize ECHA REACH pre-registration for silicone-based oil-and-grease-resistant formulations to capture snack food segment reformulation demand. For New Entrants and Emerging Players: Launch via digital printing service bureaus serving Berlin and Hamburg craft beverage brand owners demanding sub-five-thousand-unit versioning with zero-die-change workflows. Target pharmaceutical cold chain logistics as the most penetrable premium segment, where cell and gene therapy shippers seek validated phase-change material solutions. Pursue strategic partnerships with existing corrugated converters for software-hardware bundling of machine learning-driven box optimization algorithms. For Investors and Strategic Acquirers: The window for entry favors pharmaceutical barrier specialists with ISO 14644-1 cleanroom certification and existing relationships with Gerresheimer AG's customer base. Long-term viability rests on positioning for EU delegated act recyclability performance grade definitions that will determine green public procurement eligibility. Watch for KBA transport safety certification backlogs as the signal indicating capacity constraints in UN-certified intermediate bulk containers.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material R&D Investment | EU Packaging and Packaging Waste Regulation compliance secures volume commitments from Verpackungsgesetz-obligated brand owners. |
| Dry-Molded Fiber Capacity Expansion | Stuttgart's industrial periphery concentrates equipment investments displacing plastic extrusion lines. |
| Pharmaceutical Cold Chain Partnership | Bavaria's manufacturing belt anchors demand for validated temperature-controlled packaging in cell therapy logistics. |
| Digital Printing Service Bureau Acquisition | Craft beverage versioning below five thousand units rewards zero-die-change workflow capabilities. |
| Recycling Infrastructure Joint Venture | rPET flake sourcing security determines compliance with EU delegated act minimum recycled content thresholds. |
Research Methodology
Multi-period observation of Verpackungsgesetz implementation timelines, EU delegated act progression, and brand owner supplier panel consolidation anchored the trend analysis, supplemented by interviews with packaging procurement directors, ESG compliance officers, converter plant managers, and KBA certification specialists. Secondary validation drew from ECHA REACH substance restriction databases, EU Packaging and Packaging Waste Regulation delegated act drafts, German federal waste management statistics, and industry association technical guidance. Bottom-up capacity assessments triangulated against top-down demand modeling across material platforms and end-use verticals.
Segment-weighting approaches distributed value and volume contributions across flexible formats, rigid containers, paper-based alternatives, and metal packaging, with further disaggregation by pharmaceutical serialization compliance tier, food contact material safety grade, and chemical transport certification status. CAGRs were derived from regression analysis of historical substitution patterns and regulatory acceleration effects. Forecast inputs incorporated ECHA substance restriction timelines, KBA certification capacity constraints, and deposit-return scheme infrastructure lock-in persistence.
Delegated act definitional delays, recycled feedstock availability shocks, and cleanroom manufacturing talent scarcity are the dominant revision risks that could compress or extend projected trajectories. Forecasts reflect documented assumptions regarding regulatory implementation pace and material substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Gift Wrapping Product Market