
 Child Resistant Re-Closable Edible Bags Market | 2026-2036
Child Resistant Re-Closable Edible Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Re-Closable Edible Bags Market Outlook
North American flexible packaging producers is consolidating around child-resistant formats as state cannabis regulations multiply. Amcor plc leverages its pharmaceutical barrier film expertise to anchor premium re-closable formats. Berry Global Inc. sustains broad thermoplastic capacity across multiple closure platforms. Dymapak specializes in smell-proof Mylar constructions with integrated locking mechanisms.
Child resistant re-closable edible bags are multi-layer laminated pouches incorporating press-to-open zipper profiles, tear-notches, and ASTM-certified locking mechanisms designed to prevent access by children under five years while permitting adult resealing. These packages serve dual functions: preserving product freshness through oxygen and moisture barriers while satisfying poison-prevention mandates for regulated ingestibles. Plastic dominates current volume due to cost-efficient extrusion and heat-seal compatibility, though biodegradable substrates are gaining traction where municipal composting infrastructure supports end-of-life claims. The cannabis end-user segment commands premium pricing and drives closure innovation, while pharmaceutical applications impose the most rigorous extractables-testing requirements.
FDA food-contact notification rules, ASTM D3475 child-resistant protocol, and state-level cannabis packaging mandates collectively determine product qualification timelines and regional market access. Compliance costs favor producers with in-house testing laboratories and established regulatory affairs teams. Stakeholders must monitor evolving state cannabis regulations and bioplastic certification standards to anticipate material substitution cycles and qualification bottlenecks.
Market Dynamics
State-level cannabis packaging mandates are fragmenting compliance requirements across jurisdictions, forcing manufacturers to maintain multiple SKUs and certification pathways. This regulatory divergence concentrates production among suppliers with in-house ASTM D3475 testing capabilities and established regulatory affairs infrastructure.
Growth Catalysts
- ASTM D3475 Certification Expansion:Poison-prevention testing protocols now extend beyond pharmaceuticals into cannabis edibles, creating standardized qualification pathways that reduce buyer procurement friction.
- California Cannabis Corridor:The state's stringent child-resistant packaging mandates have established a de facto national benchmark, pulling compliant suppliers into its regulated supply chain.
- Multi-Layer Barrier Films:Oxygen and moisture barrier technologies preserve edible potency and shelf stability, justifying premium pricing for re-closable formats over single-use alternatives.
Market Restraints
- Resin Price Volatility:Polyethylene and polypropylene input costs fluctuate with petrochemical feedstock markets, compressing margins for commodity-grade bag producers.
- Testing Laboratory Bottlenecks:Limited ASTM-certified facilities create qualification queues that delay product launches and lock out smaller manufacturers.
- Bioplastic Performance Gaps:Compostable substrates currently fail moisture barrier requirements for extended shelf-life applications, limiting material substitution.
Strategic Opportunities
- Illinois and New York State Markets:Recent adult-use legalization in these jurisdictions creates first-mover advantages for suppliers establishing compliant distribution networks.
- Pharmaceutical Gummy Applications:OTC pediatric supplements represent an adjacent vertical with overlapping child-resistant requirements and higher extractables-testing standards.
- Smart Closure Integration:Tamper-evident zipper mechanisms combined with QR traceability codes address both compliance and supply chain transparency demands.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Specialists capable of navigating overlapping FDA food-contact rules and state cannabis mandates command premium compensation and lengthen hiring cycles.
- Legacy Equipment Retrofit Costs:Converting standard flexible packaging lines for child-resistant zipper integration requires substantial capital outlay and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Re-Closable Edible Bags Market |
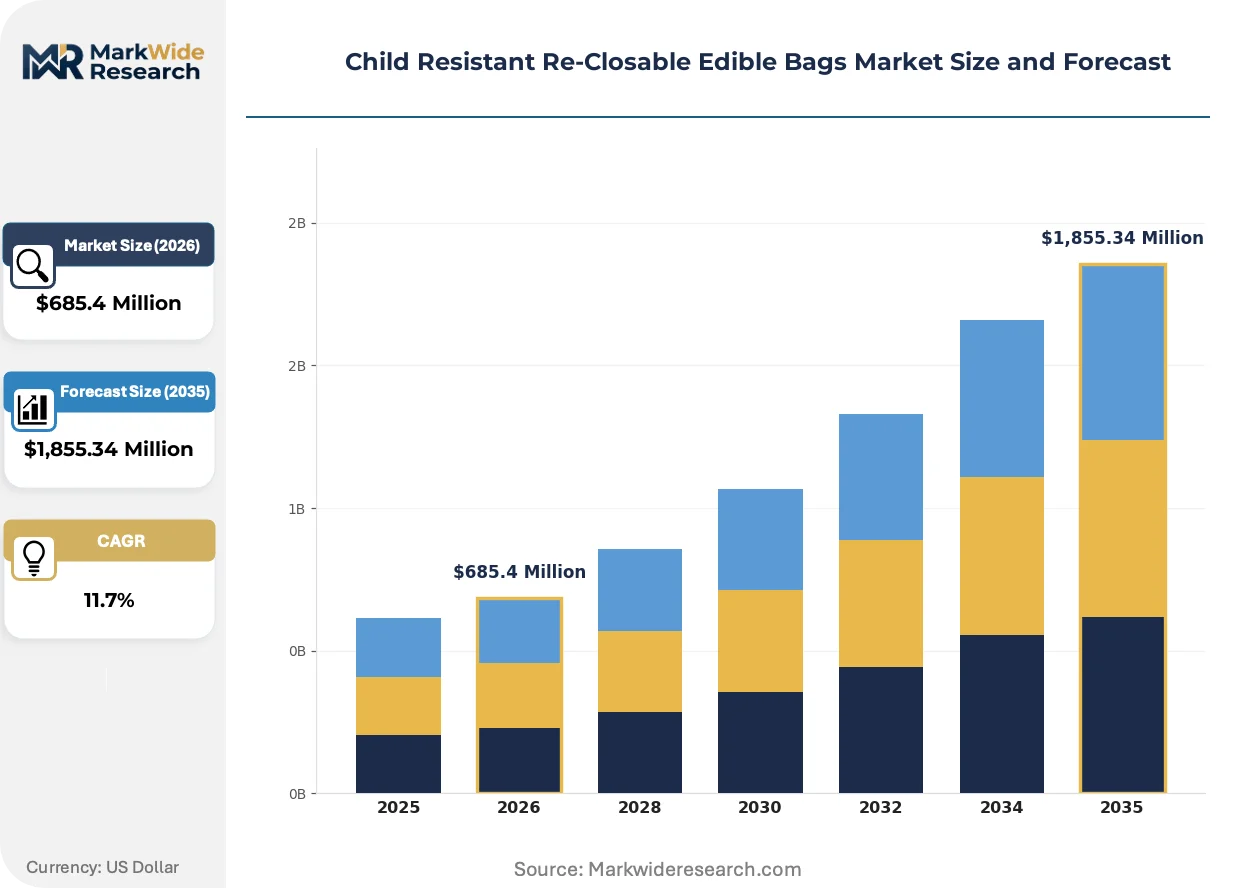
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Biodegradable, Mylar, Paper Size: Small, Medium, Large, Extra Large Closure Type: Zip Lock, Heat Seal, Velcro, Snap End User: Food Industry, Cannabis Industry, Pharmaceuticals, Confectionery |
| Companies Covered | Zip-Pak, Smurfit WestRock, Amcor plc, BSI Group, Constantia Flexibles, Berry Global Inc., AptarGroup, Inc., Sun Grown Packaging, Dymapak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Re-Closable Edible Bags Market Strategic Shifts
Closure engineering and material science are converging to address the dual mandate of child safety and adult accessibility. Manufacturers are reconfiguring production lines around certified locking mechanisms while exploring substrate alternatives that satisfy emerging sustainability claims.
Press-to-open zipper profiles with integrated dual-button locking mechanisms are modularizing production workflows across North American flexible packaging facilities. Cannabis dispensaries and edible processors are specifying these formats for 70% of new SKU introductions. The technology is modularizing supplier capabilities, separating dedicated child-resistant producers from commodity re-closable bag manufacturers.
FDA food-contact notification rules are tightening extractables and leachables documentation requirements for multi-layer laminated structures. Manufacturers must now submit migration testing data for each adhesive and barrier layer combination. Pharmaceutical applications face the most rigorous scrutiny, with some suppliers withdrawing from medical-grade segments rather than absorbing compliance costs.
Direct procurement relationships between edible processors and packaging converters are displacing traditional distributor intermediaries in California and Colorado. Buyers are consolidating vendor lists to three preferred suppliers per closure type, demanding volume commitments in exchange for technical collaboration. This concentration is most visible among vertically integrated cannabis operators with captive manufacturing facilities.
Child Resistant Re-Closable Edible Bags Market Segmentation
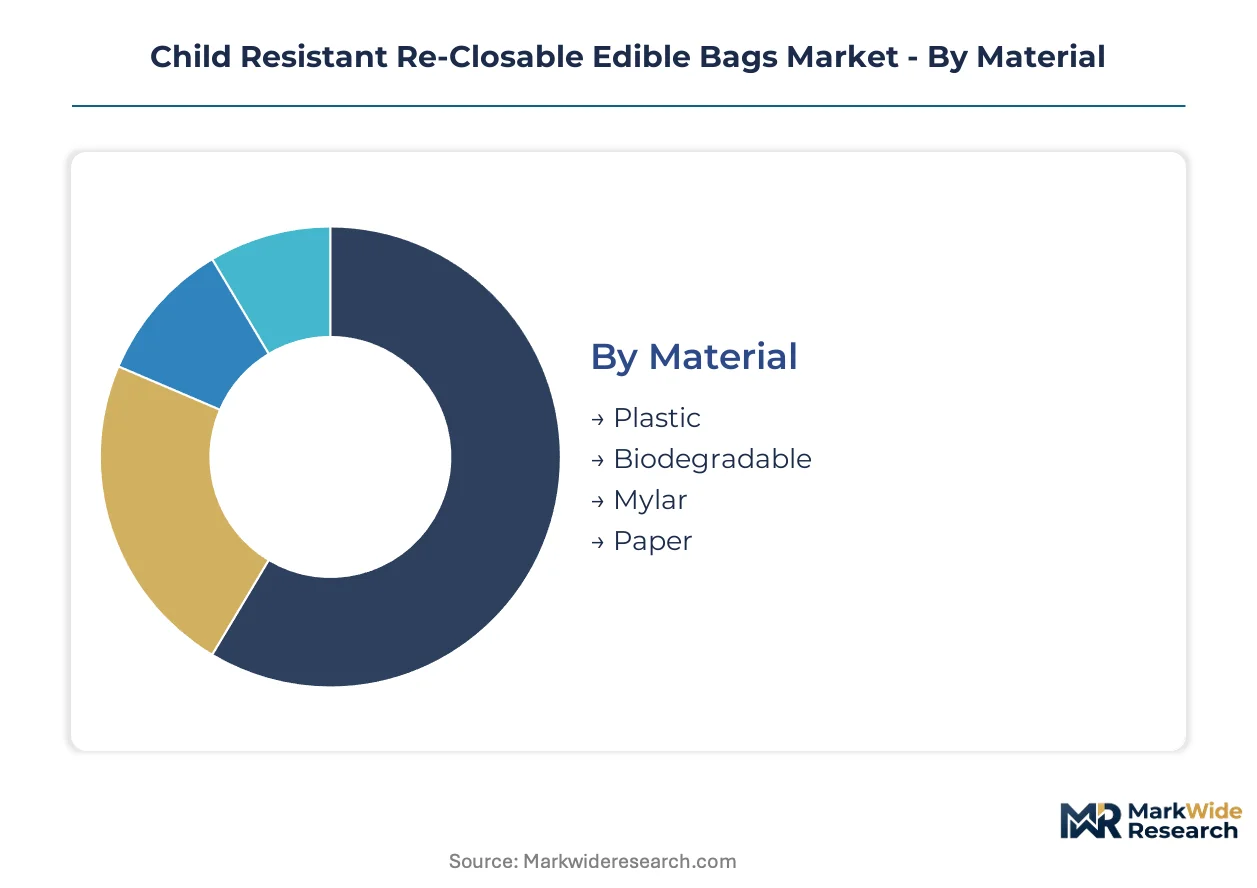
Segmentation in child-resistant re-closable edible bags determines compliance pathways, barrier specifications, and closure engineering investments. Material selection and closure type dictate ASTM D3475 certification requirements, while end-use verticals impose divergent extractables-testing standards.
Material:
Upgrade cycles from conventional plastics to certified compostable substrates are accelerating where municipal composting infrastructure supports end-of-life claims.
- Plastic:Multi-layer polyethylene and polypropylene laminates dominate current volume through cost-efficient extrusion and heat-seal compatibility. California's regulated cannabis corridor pulls the majority of food-grade plastic bag demand due to stringent barrier requirements.
- Mylar:Metallized polyethylene terephthalate films deliver superior oxygen and moisture barriers for extended shelf-life applications. Cannabis edible processors specify Mylar constructions for 60% of premium SKU introductions requiring six-month potency preservation.
- Biodegradable:Polylactic acid and cellulose-based substrates are gaining traction in municipalities with established industrial composting streams. Current formulations fail moisture barrier thresholds for pharmaceutical applications.
- Paper:Fiber-based constructions with polymer barrier coatings serve short-shelf-life confectionery segments. Kraft paper with polyethylene linings satisfies European single-use plastic directive exemptions for certain food-contact applications.
Plastic sits at the top of the volume ranking, with Biodegradable climbing the fastest.
Size:
Volume concentration in medium formats reflects standard edible portion sizing, while large-format demand tracks with bulk dispensary packaging requirements.
- Medium:4x6 inch to 6x9 inch dimensions capture standard single-serving edible portions. Illinois and New York state cannabis markets are standardizing on medium formats for retail compliance.
- Small:Micro-dose and sample-size applications drive sub-4-inch format demand. Pharmaceutical gummy supplements specify small bags for pediatric OTC trial packs.
- Large:Bulk dispensary packaging and multi-unit edible assortments require 8x10 inch and larger constructions. Vertical cannabis operators with captive manufacturing favor large formats for internal inventory transfers.
- Extra Large:Industrial-scale edible processing and wholesale distribution utilize 12x16 inch and above configurations. Limited ASTM-certified closure availability constrains extra large segment expansion.
Medium formats command the highest shipment volumes, with Large formats expanding most quickly as bulk purchasing patterns solidify.
Closure Type:
Press-to-open zipper profiles are modularizing production workflows, separating dedicated child-resistant producers from commodity re-closable bag manufacturers.
- Zip Lock:Dual-button press-to-open mechanisms with integrated locking profiles satisfy ASTM D3475 protocols while permitting adult resealing. California edible processors specify zip lock formats for 70% of new SKU introductions.
- Heat Seal:Permanent fusion closures serve single-use pharmaceutical applications where resealing is prohibited. FDA food-contact notification rules require migration testing documentation for each heat-seal adhesive formulation.
- Velcro:Hook-and-loop fastening systems offer accessibility advantages for elderly and disabled adult users. Limited child-resistance certification restricts velcro to non-regulated food segments.
- Snap:Rigid plastic interlocking mechanisms provide tactile feedback for closure confirmation. Snap closures are gaining traction in medical cannabis markets where dexterity-impaired patients require accessible packaging.
Zip Lock closures dominate the installed base, with Snap mechanisms gaining share fastest in accessibility-focused medical markets.
End User:
Customer procurement patterns are consolidating vendor lists to three preferred suppliers per closure type, demanding volume commitments in exchange for technical collaboration.
- Cannabis Industry:State-licensed dispensaries and edible processors command premium pricing and drive closure innovation. Colorado and California operators are displacing distributor intermediaries through direct converter relationships.
- Pharmaceuticals:OTC pediatric supplements and medical cannabis products impose the most rigorous extractables-testing requirements. Some suppliers withdraw from medical-grade segments rather than absorb compliance documentation costs.
- Food Industry:Specialty and gourmet edible producers require barrier performance without child-resistant certification. Direct procurement relationships are emerging in artisanal chocolate and baked goods segments.
- Confectionery:Gummy and hard candy applications overlap cannabis and pharmaceutical barrier requirements. Confectionery processors prioritize oxygen scavenging films for flavor stability over child-resistant mechanisms.
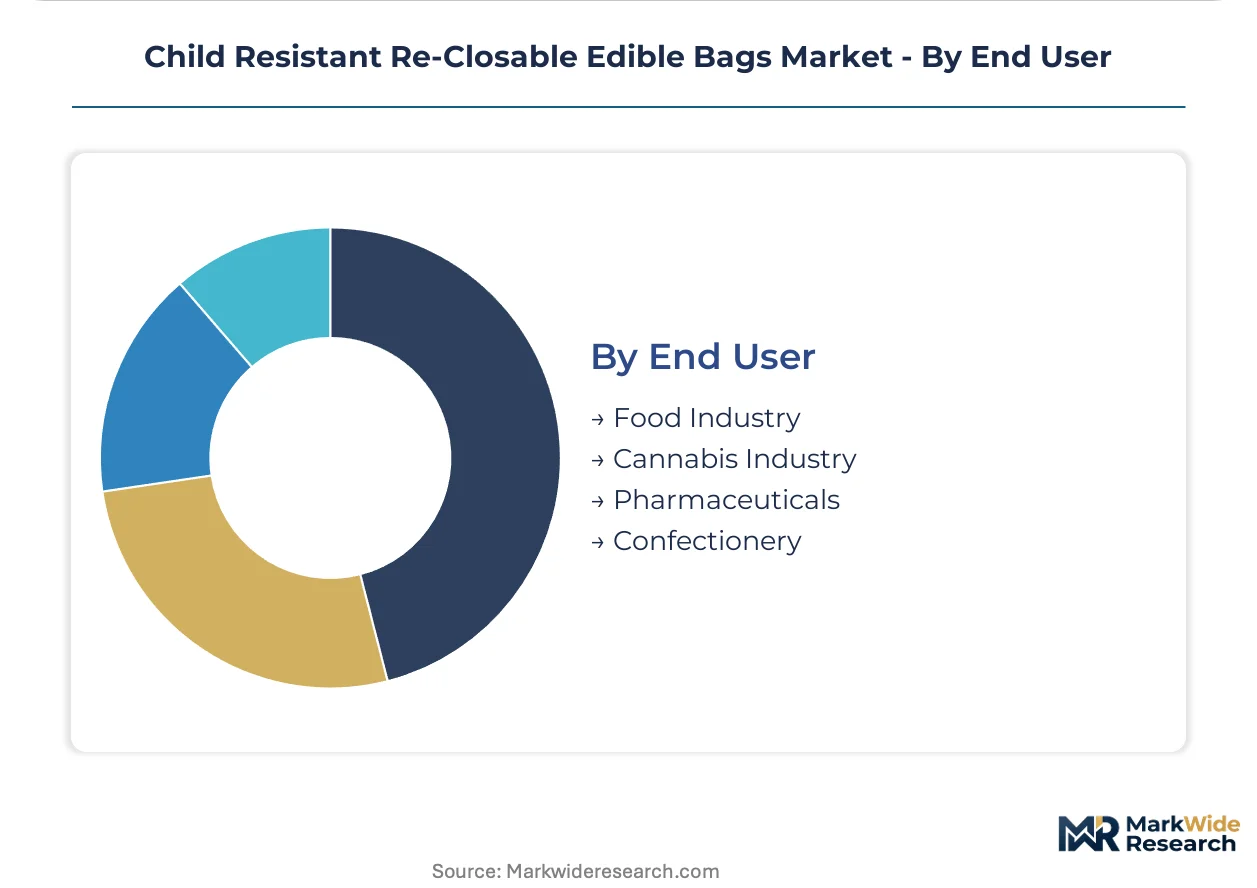
Cannabis Industry sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest as medical-grade certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined ASTM D3475 certification pathways, creating compliance-cost arbitrage between established and emerging cannabis markets. Manufacturers with in-house testing capabilities cluster in states with mature regulatory frameworks, while new entrants target recently legalized territories.
United States
California's cannabis packaging mandates establish the de facto national benchmark for child-resistant specifications. FDA food-contact notification rules and state-level poison-prevention statutes create overlapping compliance requirements. Los Angeles and Oakland host concentrated converter operations serving vertically integrated edible processors.
Canada
Federal cannabis legalization since 2018 generates standardized demand for ASTM-certified re-closable formats across provincial distribution networks. Health Canada packaging regulations mandate child-resistant mechanisms for all ingestible cannabis products. Ontario and British Columbia concentrate flexible packaging conversion capacity near Toronto and Vancouver processing hubs.
Germany
Medical cannabis liberalization drives pharmaceutical-grade barrier film demand from BfArM-licensed producers. EU packaging waste directives accelerate scrutiny of multi-layer laminate recyclability. North Rhine-Westphalia flexible packaging clusters around Düsseldorf and Cologne serve emerging cannabis pharmaceutical supply chains.
Australia
Therapeutic Goods Administration scheduling changes expand medical cannabis patient access, triggering packaging specification updates. TGA child-safety guidelines for scheduled medicines extend to cannabis-derived therapeutics. Melbourne and Sydney converters develop export-oriented capacity for Asia-Pacific cannabis markets.
Netherlands
Office of Medicinal Cannabis tenders require validated child-resistant packaging for domestic and export supply. Dutch flexible packaging expertise in pharmaceutical barrier films transfers to regulated cannabis applications. Eindhoven and Venlo industrial zones concentrate converter operations with established regulatory affairs infrastructure.
Child Resistant Re-Closable Edible Bags Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate differentiation and smart closure integration. Market structure consolidates around suppliers with integrated ASTM D3475 testing laboratories and multi-state regulatory compliance capabilities. Three archetypes dominate: pharmaceutical barrier film specialists, dedicated cannabis packaging converters, and diversified flexible packaging conglomerates. Capacity expansion and strategic partnerships with state-licensed edible processors constitute the primary competitive vectors.
Among North American flexible packaging leaders, Amcor plc, Berry Global Inc., and Dymapak exemplify divergent strategic positioning. Amcor occupies the pharmaceutical-grade tier with barrier film expertise transferable to regulated cannabis applications. Berry Global sits within the diversified conglomerate archetype, sustaining thermoplastic capacity across multiple closure platforms. Dymapak represents the cannabis-specialist vector, anchoring smell-proof Mylar constructions with integrated locking mechanisms for state-compliant dispensary supply chains.
| Leading Market Players |
|---|
| Zip-Pak |
| Smurfit WestRock |
| Amcor plc |
| BSI Group |
| Constantia Flexibles |
| Berry Global Inc. |
| AptarGroup, Inc. |
| Sun Grown Packaging |
| Dymapak |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin price indices cascade through three distinct pricing tiers for child-resistant re-closable edible bags. Input cost volatility compresses margins at the commodity-grade tier while ASTM D3475 certification premiums insulate pharmaceutical-grade suppliers. California's cannabis packaging mandates concentrate buyer procurement power, forcing volume commitments in exchange for technical collaboration.
Pricing Analysis
Distributor margins of 15-25% separate converter ex-works pricing from dispensary shelf placement. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM certification grade and barrier film complexity. Pricing pressure stems from resin cost volatility and testing laboratory bottlenecks that delay premium product launches. Cannabis edible processors exhibit highest price sensitivity due to state-margin compression, while pharmaceutical buyers prioritize extractables documentation over unit cost.
Supply Chain Analysis
Freight cost differentials between Asia-Pacific film suppliers and North American converters determine regional sourcing economics. Manufacturing concentrates in China, South Korea, and domestic United States facilities with integrated zipper profile extrusion. Multi-layer laminate production draws from metallized PET substrates, polyethylene resins, and certified locking mechanism components. Single-source vulnerability exists for ASTM-certified testing capacity. Distribution runs through direct converter relationships displacing traditional distributor channels in California and Colorado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Child-resistant re-closable edible bags function as a regulatory compounder where ASTM D3475 certification expansion generates durable demand premiums. State-level cannabis packaging mandates create compliance-cost moats favoring incumbent producers with established testing infrastructure.
For Market Incumbents: Anticipate bioplastic substrate substitution cycles by securing industrial composting partnerships ahead of municipal infrastructure buildout. Defend margin position through captive ASTM D3475 laboratory capacity and multi-state regulatory affairs teams. Threat from smell-proof Mylar specialists with integrated locking mechanisms demands barrier film R&D acceleration. For New Entrants and Emerging Players: E-commerce direct procurement channels offer white-space entry around Illinois and New York state markets where compliant supplier networks remain underdeveloped. Target pharmaceutical gummy supplement applications with overlapping child-resistant requirements and less consolidated vendor lists. Prioritize smart closure integration with QR traceability as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with cannabis-specialist converters possessing Health Canada and BfArM export qualifications alongside domestic ASTM certification. Long-term viability hinges on regulatory affairs talent depth and backward integration into barrier film extrusion. Watch Illinois and New York state licensing velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D3475 Laboratory Acquisition | In-house testing capacity eliminates qualification queues and accelerates product launch timelines. |
| Bioplastic Substrate Partnership | Industrial composting alliances position suppliers ahead of California packaging waste mandates. |
| Smart Closure Integration | Tamper-evident zipper mechanisms with QR codes address FDA traceability and supply chain transparency demands. |
| Direct Converter Relationships | Bypassing distributor intermediaries captures margin and secures volume commitments from vertically integrated cannabis operators. |
| Pharmaceutical Grade Certification | Extractables-testing documentation opens OTC pediatric supplement adjacent vertical with premium pricing. |
Study Parameters
Multiple input streams — converter production data, state regulatory filings, and resin price benchmarks — were reconciled through bottom-up and top-down triangulation. Primary interviews with flexible packaging plant managers, cannabis edible processors, regulatory affairs specialists, and ASTM-certified testing laboratory directors informed demand-side assumptions. Secondary validation drew from FDA food-contact notification databases, state cannabis packaging mandate texts, SEC 10-K disclosures from listed packaging conglomerates, and trade data on multi-layer laminate imports. Cross-referencing shipment volumes against state licensing counts tested market sizing integrity.
Data-stream reconciliation anchored the forecast framework across material, closure type, size, and end-user segmentation dimensions. CAGRs were derived from regression analysis of historical state market expansion patterns projected against legalization timelines. Industry-specific inputs included ASTM D3475 certification queue lengths, zipper profile equipment lead times, and municipal composting infrastructure development curves.
The model assumes a particular technology adoption path; alternative pathways for biodegradable substrate performance improvement would alter the outlook for plastic volume retention. Forecasts reflect assumptions about state cannabis legalization velocity and FDA extractables-testing rule evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Book Wraps Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
France Packaging Market
Packaging Materials
Thermal Transfer Roll Market