
 Coconut Wraps Market | 2026-2036
Coconut Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Wraps Market Outlook
Subscription-based replenishment programs for coconut wraps is broadening how manufacturers monetize repeat consumption. NUCO Coconut leverages direct-to-consumer channel control to sustain recurring revenue streams. Koko's Kitchen anchors its position through specialized organic certification and clean-label positioning. LettUs Foods competes on flavor innovation, extending its portfolio into spicy and sweetened variants that occupy distinct shelf-space segments.
Coconut wraps are thin, pliable sheets manufactured from dehydrated coconut meat, typically containing one to three ingredients and serving as grain-free alternatives to wheat tortillas or corn shells for wrapping proteins and vegetables. Classic wraps lead volume in mainstream retail channels, while organic variants command premium positioning in health food stores and specialty markets. Ready-to-eat applications represent the fastest-growing use case as convenience-seeking consumers prioritize minimal-preparation meal solutions. Supermarkets remain the dominant distribution channel, though online retailers are capturing incremental share through subscription bundling and targeted digital marketing to gluten-free dieters.
The FDA governs allergen labeling and health claims for coconut-based products in the United States, while the USDA oversees organic certification standards that many premium producers pursue. The European Food Safety Authority and EU organic regulations shape market access for imported coconut wraps across member states, with REACH compliance required for any packaging materials in contact with food. Stakeholders must monitor evolving definitions of "natural" and "clean label" across jurisdictions, as regulatory reinterpretation could force rapid reformulation or relabeling investments without warning.
Market Dynamics
Subscription bundling and direct-to-consumer channel control are compressing traditional wholesale margins while capturing recurring revenue streams from health-conscious households. This structural shift forces incumbent supermarket suppliers to defend shelf space against digitally native entrants.
Growth Catalysts
- Clean-label mandates:The FDA's evolving enforcement of "natural" claims and tightening EU organic regulations under EFSA guidance compel manufacturers toward minimal-ingredient formulations that favor single-source coconut wraps over multi-additive competitors.
- Meal-kit integration:Ready-to-eat applications in prepared meal services are accelerating volume pull-through as convenience-seeking consumers prioritize minimal-preparation solutions for protein and vegetable wrapping.
- Urban dietary clustering:Gluten-free and plant-based consumption concentrates in metropolitan areas across the United States, Germany, and the United Kingdom, creating dense demand pockets that justify specialized distribution infrastructure.
Market Restraints
- Raw material volatility:Coconut meat supply fluctuates with Southeast Asian harvest cycles and climate stress, exposing producers to input cost spikes without long-term procurement hedges.
- Processing concentration:Dehydration and sheet-forming equipment suppliers cluster in Thailand and Indonesia, creating geographic chokepoints that amplify disruption risk from regional logistics constraints.
- Substitution pressure:Cassava-based and cauliflower-derived wraps compete for identical shelf positioning in gluten-free aisles, fragmenting consumer attention and compressing brand loyalty.
Strategic Opportunities
- Underpenetrated European markets:Spain and Italy exhibit nascent adoption of grain-free alternatives, presenting first-mover advantages for brands establishing localized organic certification pathways.
- Foodservice channel expansion:Quick-service restaurants and corporate catering operations represent untapped volume as operators seek allergen-friendly menu items that reduce liability exposure.
- Packaging innovation convergence:Compostable film technologies combined with modified-atmosphere sealing extend shelf stability without synthetic preservatives, opening premium positioning in sustainability-focused retail.
Industry Challenges
- Organic certification timelines:USDA and EU organic approval processes impose multi-year compliance windows that delay product launches and tie up working capital in audit documentation.
- Flavor R&D specialization:Developing shelf-stable spicy and sweetened variants requires food science expertise in natural preservation that remains scarce among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Wraps Market |
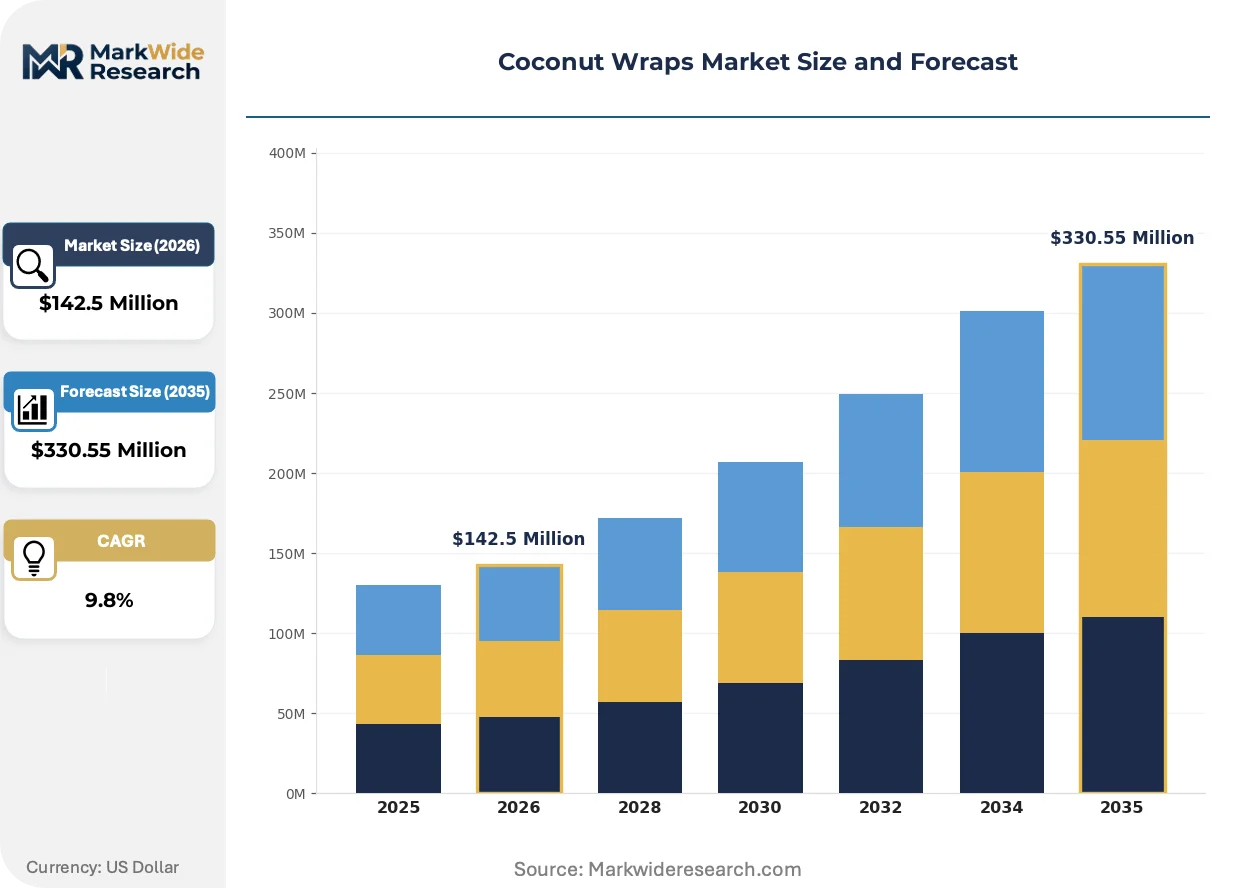
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $330.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Wraps, Spicy Flavored, Sweetened, Organic Use Case: Dietary Alternatives, Snack Foods, Meal Preparation, Ready-to-Eat Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Markets Customer Type: Health Conscious Consumers, Vegans, Diabetics, Gluten-Free Dieters |
| Companies Covered | Coconut Bowls, Koko's Kitchen, LettUs Foods, Suncoco, Cocofit, Cocobella, Coco Delice, NUCO Coconut, Crepini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Wraps Market Strategic Shifts
Dehydration technology advances and regulatory reinterpretation of health claims are simultaneously reshaping production economics and competitive positioning. These forces compress time-to-market for clean-label entrants while raising compliance barriers for legacy formulations.
Continuous belt dehydration systems with precision humidity control are automating the transition from batch to continuous processing in coconut wrap manufacturing. Mid-scale producers in the United States and Germany are adopting these systems to reduce labor dependency and achieve lot-to-lot consistency. This automation is compressing unit economics for regional players previously constrained by manual sheet-forming bottlenecks.
REACH compliance requirements for food-contact packaging materials are tightening across European Union member states, forcing importers to validate substrate safety documentation or face port-of-entry rejection. Manufacturers sourcing from Southeast Asia must now maintain dual certification tracks for EU and US markets. Premium organic variants face the steepest compliance burden, as EFSA scrutiny of "natural" additive exemptions intensifies.
Replenishment subscriptions via direct-to-consumer platforms are displacing intermittent supermarket purchasing among dedicated gluten-free households. Specialty e-commerce channels capture these buyers through bundled pricing and auto-ship convenience that traditional retail cannot replicate. This behavioral shift concentrates most visibly in United States coastal metropolitan markets where digital grocery penetration exceeds national averages.
Coconut Wraps Market Segmentation
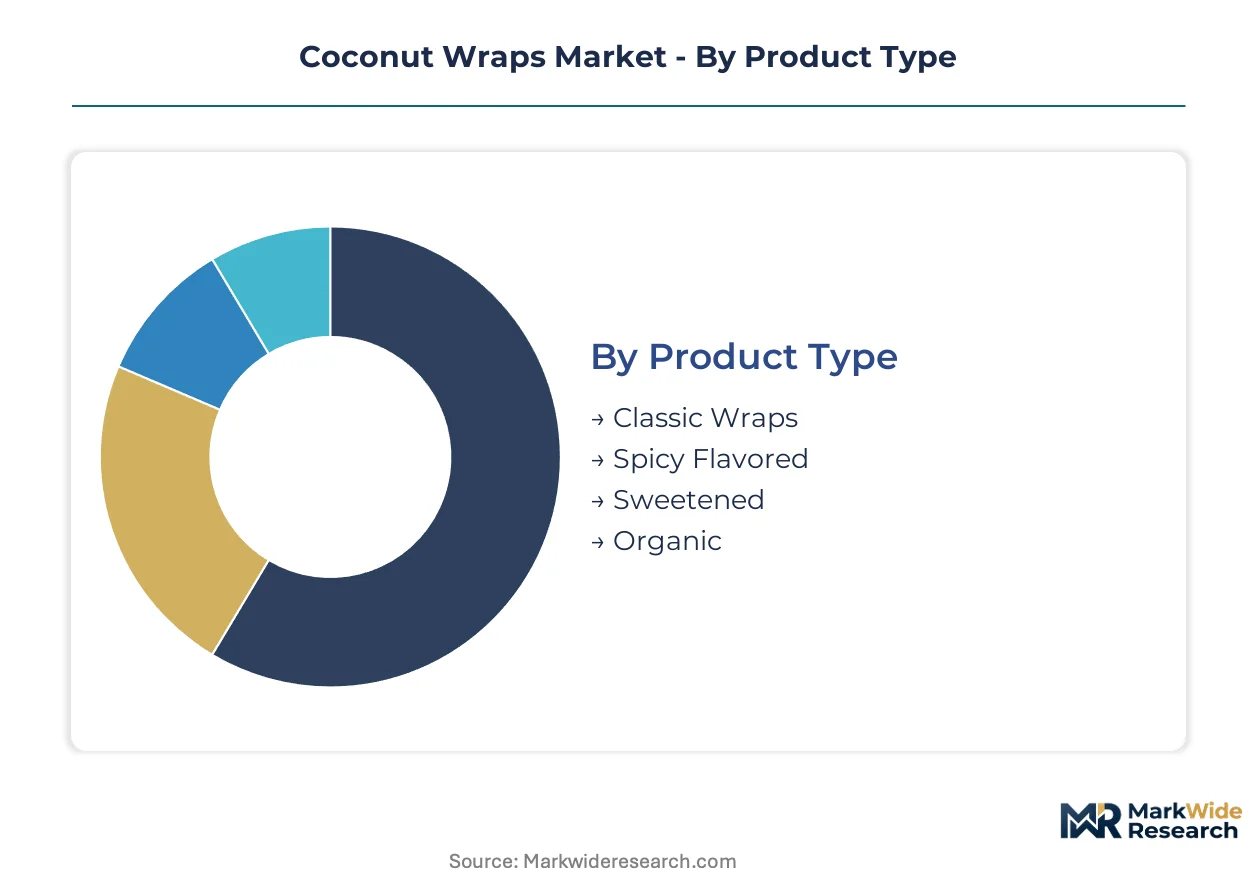
Coconut wraps manufacturers configure production lines around distinct technical specifications and certification tiers. Segmentation discipline separates commodity-grade volume plays from premium positioning that commands shelf-space premiums in regulated channels.
Product Type:
Dehydration equipment suppliers in Thailand and Indonesia concentrate sheet-forming capacity around standardized specifications that favor high-throughput SKUs over artisanal variants.
- Classic Wraps:Unflavored sheets containing coconut meat and salt constitute the baseline formulation for retail distribution. Demand clusters in United States metropolitan supermarkets where gluten-free aisle placement drives impulse purchases among health-conscious households constrained by clean-label mandates.
- Organic:Certified variants pursue USDA and EU organic standards that extend processing timelines but unlock premium shelf positioning in Whole Foods Market and equivalent European chains. German and United Kingdom health food stores absorb disproportionate volume as EFSA labeling scrutiny intensifies.
- Spicy Flavored:Chili-infused variants target Latin American and Southeast Asian diaspora communities in Florida and California.
- Sweetened:Coconut nectar-enhanced sheets serve dessert applications and breakfast wrap formats.
Classic wraps absorb the bulk of installed capacity; organic variants are expanding most quickly.
Use Case:
Application-driven demand splits between home preparation and foodservice channels with divergent margin structures and volume profiles.
- Meal Preparation:Raw ingredient positioning for home assembly of protein-vegetable wraps dominates unit economics in subscription replenishment programs. United States coastal metropolitan households with digital grocery penetration above national averages drive recurring revenue capture through direct-to-consumer platforms.
- Ready-to-Eat:Pre-assembled wraps in modified-atmosphere packaging serve convenience-seeking consumers in corporate catering and airport concessions. Quick-service restaurant trials in Los Angeles and New York City test allergen-friendly menu integration.
- Dietary Alternatives:Medical nutrition positioning targets diabetic and celiac populations with glycemic control claims.
- Snack Foods:Bite-sized formats compete in grab-and-go refrigerated cases against cheese and charcuterie alternatives.
Meal preparation commands the steepest volume share; ready-to-eat applications are climbing the fastest as foodservice procurement shifts toward allergen liability reduction.
Distribution Channel:
Channel control determines margin capture and customer data access, with supermarket incumbents defending shelf space against digitally native entrants.
- Supermarkets:Conventional grocery chains in the United States and Germany maintain dominant volume through established gluten-free aisle infrastructure. Kroger and Albertsons slotting fees favor incumbent suppliers with existing category management relationships.
- Online Retailers:Amazon and Thrive Market capture incremental share through subscription bundling and algorithmic targeting of gluten-free and keto dieters. Auto-ship convenience concentrates in zip codes with above-average household income and digital adoption.
- Health Food Stores:Independent retailers and regional chains like Sprouts Farmers Market prioritize local and organic certification credentials.
- Specialty Markets:Asian grocery stores and gourmet food halls serve ethnic cuisine experimentation and premium gifting occasions.
Supermarkets retain the largest throughput base; online retailers are gaining share fastest through recurring revenue models that traditional wholesale cannot replicate.
Customer Type:
Consumer self-identification with dietary tribes shapes purchasing frequency, price tolerance, and brand loyalty metrics that inform marketing allocation.
- Gluten-Free Dieters:Celiac and non-celiac gluten-sensitive consumers demonstrate highest purchase frequency and willingness to pay certification premiums. United States and United Kingdom markets exhibit entrenched gluten-free aisle infrastructure that reduces search costs.
- Health Conscious Consumers:Broad wellness-oriented buyers respond to clean-label positioning and minimal-ingredient claims without strict dietary adherence. Coastal metropolitan clustering in California, New York, and London creates dense demand pockets.
- Vegans:Plant-based lifestyle adherents prioritize animal-free verification and sustainable sourcing narratives.
- Diabetics:Glycemic management positioning targets medical nutrition needs with carbohydrate-conscious formulations.
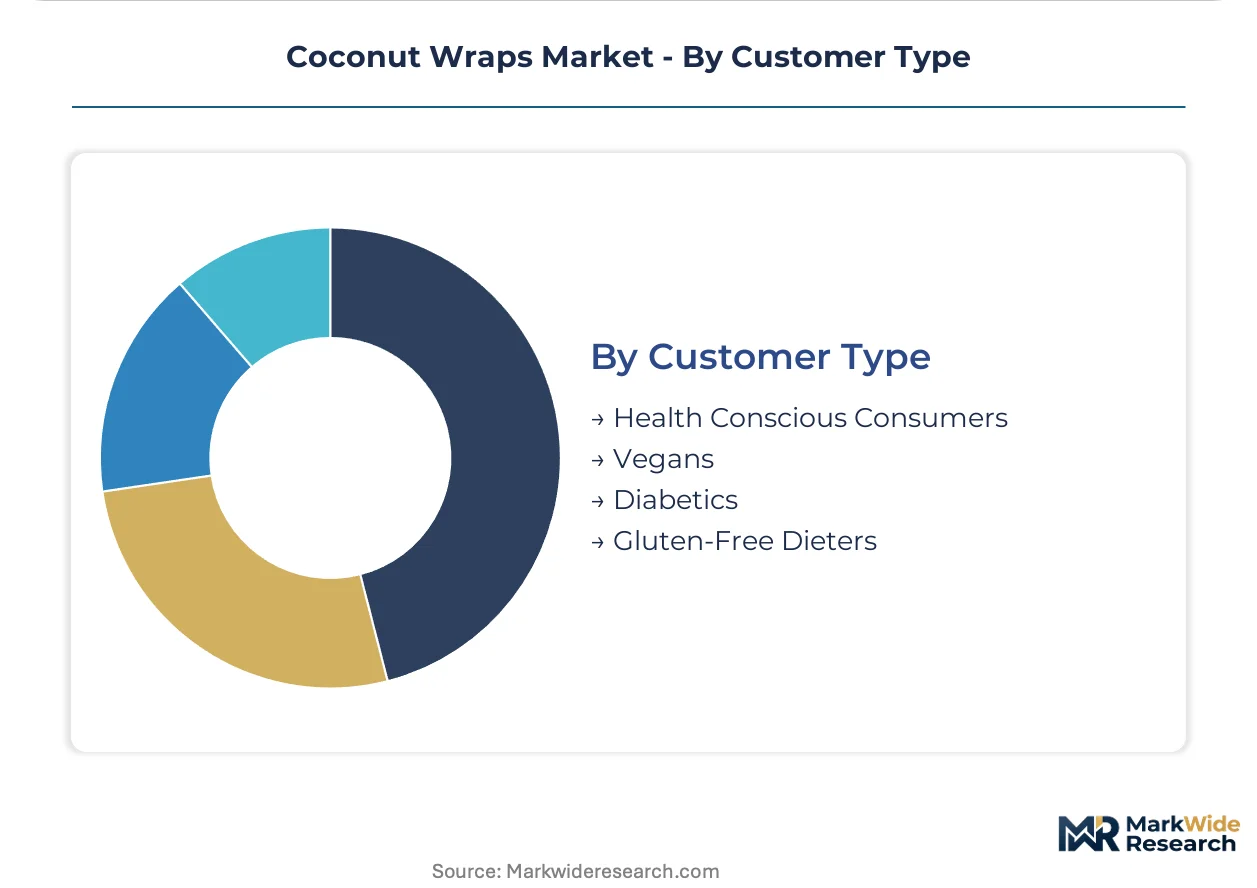
Gluten-free dieters anchor the revenue base; health-conscious consumers are expanding most quickly as clean-label mandates broaden addressable market definition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors coconut wrap demand through its density of health-conscious consumers and proximity to specialty food distribution infrastructure serving the broader Pacific Coast corridor.
United States
Gluten-free dieters and keto adherents in coastal metropolitan areas drive repeat purchases through subscription platforms. FDA allergen labeling requirements and evolving "natural" claim enforcement shape formulation decisions. Brooklyn and Austin clusters test ready-to-eat formats in quick-service restaurant partnerships.
Germany
Organic certification premiums attract clean-label households in Berlin and Munich metropolitan zones. EFSA scrutiny of health claims and EU organic regulations under ECHA guidance impose compliance burdens on importers. Hamburg distribution hubs consolidate Southeast Asian supply for re-export across Central Europe.
United Kingdom
Free-from aisle expansion in London supermarkets and Manchester health food stores sustains volume growth. UK Food Standards Agency allergen protocols align with post-Brexit regulatory divergence from EU frameworks. Bristol and Brighton clusters exhibit highest per-capita adoption of plant-based alternatives.
France
Gourmet positioning in Parisian specialty food halls and Lyon organic retailers commands price premiums. ANSM oversight of novel food notifications intersects with EFSA guidance on coconut-derived product classifications. Marseille port infrastructure handles growing Southeast Asian import volumes.
Australia
Clean-label mandates from Food Standards Australia New Zealand drive minimal-ingredient formulation preferences in Sydney and Melbourne. TGA-equivalent state food authorities enforce strict import documentation for packaged goods. Brisbane distribution networks extend reach into Southeast Asian export markets.
Coconut Wraps Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the coconut wrap sector, with dehydration equipment ownership separating integrated manufacturers from contract-dependent brands. The vendor base clusters around three strategic archetypes: vertically integrated Southeast Asian processors, North American direct-to-consumer specialists, and European organic certification-focused distributors. Capacity expansion and subscription platform development represent the dominant competitive moves as players defend recurring revenue streams against supermarket private-label encroachment.
Within the direct-to-consumer archetype, NUCO Coconut and Koko's Kitchen exemplify channel control strategies that bypass traditional wholesale intermediaries. LettUs Foods occupies a position emphasizing flavor portfolio breadth. Southeast Asian-origin entities including Suncoco and Cocofit represent integrated processing advantages. European-market specialists such as Cocobella and Coco Delice anchor organic certification positioning. Crepini exemplifies diversification beyond core coconut formats into adjacent alternative wrap categories.
| Leading Market Players |
|---|
| Coconut Bowls |
| Koko's Kitchen |
| LettUs Foods |
| Suncoco |
| Cocofit |
| Cocobella |
| Coco Delice |
| NUCO Coconut |
| Crepini |
| Others |
Value Chain & Pricing Dynamics
REACH compliance for food-contact packaging materials gates qualified supply access and premium-tier pricing power across European Union member states. Manufacturers lacking validated substrate safety documentation face port-of-entry rejection, forcing dual certification investments that concentrate margin capture among USDA and EU organic certified producers.
Pricing Analysis
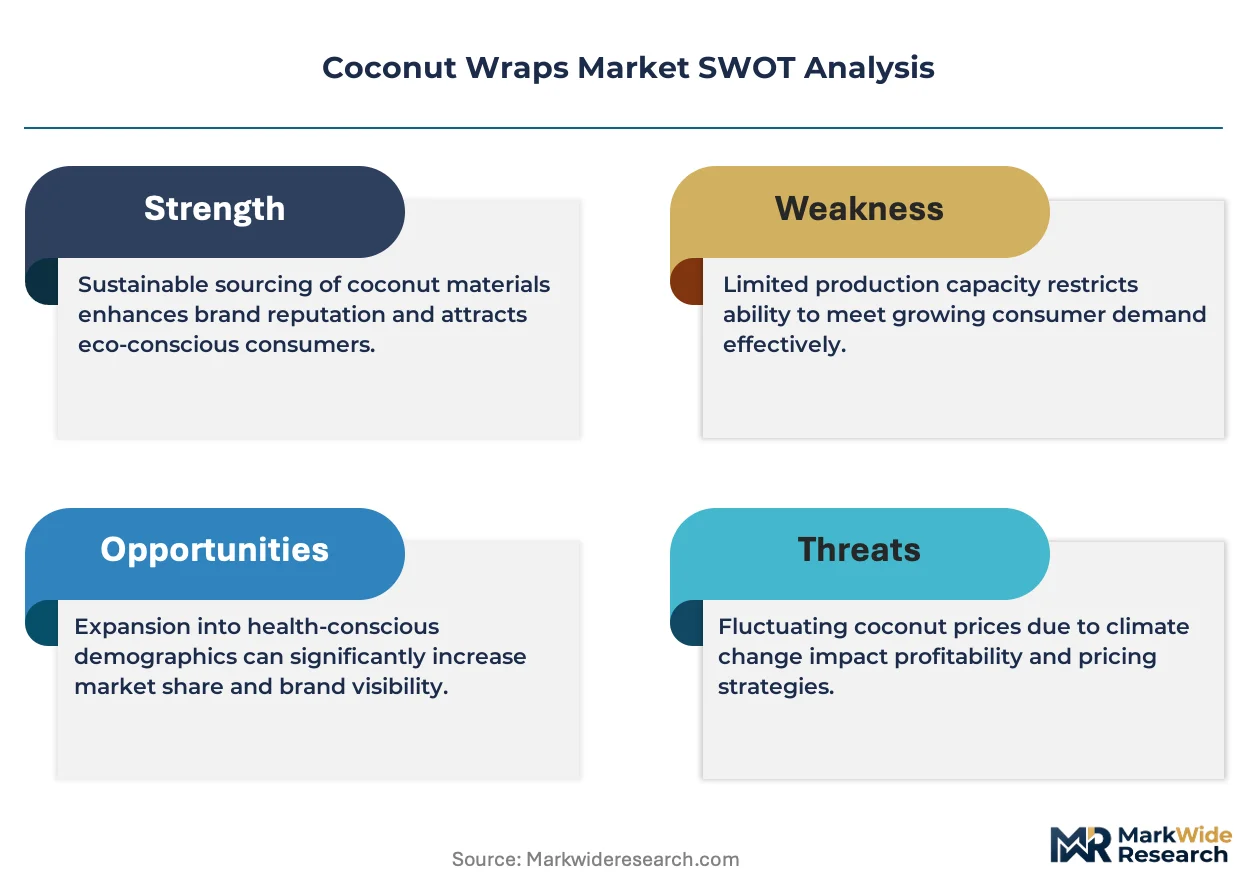
Certification-grade value anchors price stratification across organic, clean-label, and conventional tiers. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic status, EFSA-compliant labeling, and minimal-ingredient formulation depth. Cost compression in conventional tiers intensifies because cassava and cauliflower substitutes fragment shelf-space positioning. Health-conscious households in coastal metropolitan zones exhibit lowest price sensitivity; mass-market gluten-free dieters in conventional supermarkets demonstrate highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised modified-atmosphere packaging remain underdeveloped, constraining ready-to-eat format expansion. Raw coconut meat supply concentrates in Thailand, Indonesia, and the Philippines, drawing from Southeast Asian harvest cycles vulnerable to climate stress. Dehydration and sheet-forming equipment clusters in Thailand and Indonesia create geographic chokepoint exposure. Distribution runs through Hamburg and Los Angeles hub consolidation for re-export across Central Europe and North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous belt dehydration systems are displacing batch processing legacy, compressing unit economics for regional manufacturers previously constrained by manual sheet-forming bottlenecks.
For Market Incumbents: Hedge against private-label encroachment by securing multi-year organic certification pipelines and captive dehydration capacity in Southeast Asia. Channel control through subscription platform investment defends recurring revenue streams from digitally native entrants. Backward integration into coconut meat procurement mitigates raw material volatility from climate-stressed harvest cycles. For New Entrants and Emerging Players: Direct-to-consumer auto-ship platforms offer the lowest customer acquisition cost route into gluten-free household replenishment cycles. Spain and Italy present white-space opportunities for first-mover organic certification establishment. Foodservice channel trials with quick-service restaurant operators in Los Angeles and New York City unlock volume scaling without supermarket slotting fee barriers. For Investors and Strategic Acquirers: USDA organic approval timeline compression is the leading indicator that working capital efficiency is diverging between integrated processors and certification-dependent brands. Mid-scale manufacturers with captive dehydration equipment and dual EU-US certification tracks represent optimal acquisition archetypes over a five-to-ten year viability window. Practitioners should monitor EFSA reinterpretation of "natural" additive exemptions for early margin inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Belt Dehydration Adoption | Automation reduces labor dependency and achieves lot-to-lot consistency for regional producers. |
| Dual Certification Investment | USDA and EU organic tracks unlock premium shelf positioning in Whole Foods Market and equivalent European chains. |
| Direct-to-Consumer Platform Launch | Subscription bundling captures recurring revenue from health-conscious households that traditional wholesale cannot replicate. |
| Foodservice Channel Expansion | Quick-service restaurant partnerships reduce allergen liability exposure while testing ready-to-eat format viability. |
| Compostable Packaging Transition | Modified-atmosphere sealing with sustainable films extends shelf stability without synthetic preservatives for premium positioning. |
Study Parameters
Independent corroboration across dehydration equipment manufacturers, coconut meat processors, and health food retail category managers underwrites the qualitative findings in this study. Primary interviews with plant engineers at Southeast Asian processing facilities, procurement leads at United States supermarket chains, regulatory affairs specialists navigating EFSA notification pathways, and brand managers at direct-to-consumer platforms combined with secondary validation from FDA labeling guidance documents, EFSA scientific opinions, USDA organic certification databases, and customs trade flow records. Bottom-up production capacity assessments and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition across product type, use case, distribution channel, and customer dietary identification dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate continuous processing technology adoption curves and regulatory reinterpretation timelines for "natural" and "clean label" definitions.
The model holds under stable Southeast Asian harvest conditions and current EFSA enforcement intensity; deviation in climate stress severity or REACH packaging material restrictions would shift supply availability and certification cost assumptions. Practitioners should monitor EFSA additive exemption rulings and Thai logistics corridor disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Trifold Packaging Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market