
 Metallized Rollstock Film Market | 2026-2036
Metallized Rollstock Film Market Size, Share, and Industry Trends Forecast 2026-2036
Metallized Rollstock Film Market Foresight
Asian biaxial film producers is realigning capacity toward metallized polyester and polypropylene grades to capture export demand from European snack-food packagers. Toray Plastics leverages integrated resin-to-film operations in Japan and the United States to sustain consistent optical density specifications. Amcor anchors its rollstock supply through long-term toll-metallization agreements with regional converters in Southeast Asia.
Metallized rollstock film comprises polymer substrates—chiefly polyethylene terephthalate and oriented polypropylene—that receive a vacuum-deposited aluminum layer typically measured in optical density units from 2.0 to 3.5, delivering oxygen and moisture barrier performance for sensitive contents. Polyester dominates high-barrier applications where thermal stability and dimensional precision matter, while polypropylene occupies cost-driven snack and confectionery wrapping where flex-crack resistance takes priority. Thickness segmentation clusters demand in the 50-100 micron band for form-fill-seal machinery compatibility, though below-50-micron grades are gaining traction in downgauging programs.
EPA hazardous air pollutant standards for aluminum vapor deposition chambers and EU REACH restrictions on certain adhesion promoters are elevating capital requirements for metallization lines. FDA food-contact notification rules and EFSA migration limits directly determine which substrate-coating combinations qualify for direct food applications. Stakeholders must monitor regulatory divergence between North American and European barrier-test protocols when qualifying unified film specifications across Atlantic supply chains.
Market Dynamics
Metallized rollstock film supply chains are restructuring around REACH compliance deadlines and FDA food-contact notification rules, forcing substrate-coating combinations to undergo costly requalification cycles while Asian biaxial producers capture displaced European converter volume.
Growth Catalysts
- Extended shelf-life mandates:Snack-food packagers in Germany and the United States are specifying higher optical density films to replace multi-layer laminates, pulling metallized polyester demand into form-fill-seal lines.
- REACH substance restrictions:ECHA's evolving adhesion promoter limitations are accelerating migration to compliant coating chemistries, creating first-mover advantage for qualified substrate suppliers.
- Downgauging programs:Below-50-micron metallized grades are penetrating confectionery wrapping as machinery OEMs retrofit sealing jaws for thinner webs.
Market Restraints
- Aluminum spot price volatility:Vapor deposition input costs swing with LME aluminum trading bands, compressing toll-metallization margins during commodity spikes.
- Capital intensity barriers:EPA hazardous air pollutant standards for deposition chambers require scrubber retrofits exceeding mid-converter balance sheet capacity.
- Competing barrier technologies:Silicon oxide-coated films are displacing metallized grades in microwaveable applications where metal detection creates line interference.
Strategic Opportunities
- Indian flexible packaging expansion:Domestic snack consumption growth and FSSAI packaging safety mandates are creating import substitution openings for regional metallizers.
- Pharmaceutical blister lidding:Tropical climate stability requirements in Southeast Asia are pulling metallized cold-form foil alternatives into strip packaging formats.
- Recyclable mono-material designs:EU Green Deal packaging waste directives are incentivizing all-polyester metallized structures that qualify for existing PET recycling streams.
Industry Challenges
- Optical density calibration expertise:Vacuum deposition technicians with precision thickness control skills command premium wages as Asian capacity expansion outpaces training pipelines.
- Cross-Atlantic specification divergence:EFSA migration limits and FDA food-contact notification protocols require dual qualification testing, extending new product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallized Rollstock Film Market |
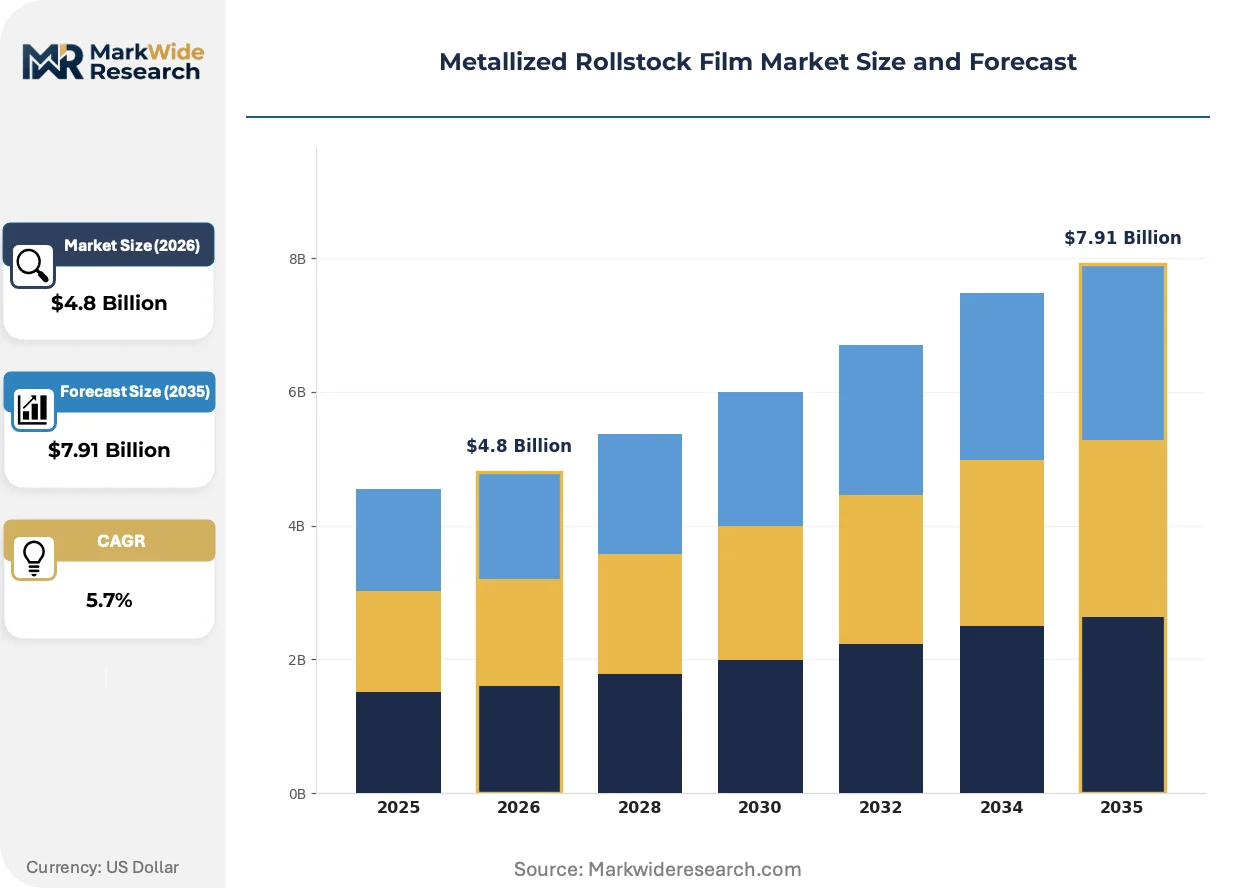
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, Nylon, Paper End Use Industry: Food Packaging, Personal Care, Electronics, Medical Thickness: Below 50 Microns, 50-100 Microns, 100-150 Microns, Above 150 Microns Surface Finish: Glossy, Matte, Metallic, Transparent |
| Companies Covered | Toray Plastics, Sealed Air Corporation, Jindal Poly Films Limited, SRF Limited, Berry Global, Uflex Limited, Amcor, DUNMORE Corporation, Cosmo Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallized Rollstock Film Market Shifts & Advancements
Process control systems and substrate engineering are converging to deliver tighter barrier consistency at reduced metal loadings, reshaping how converters specify and qualify metallized rollstock for sensitive applications.
Plasma-enhanced chemical vapor deposition is automating the application of nanometer-scale ceramic barrier layers atop conventional aluminum coatings. Pharmaceutical blister pack converters in Switzerland and Japan are adopting these hybrid structures to achieve oxygen transmission rates below 0.1 cc/m²/day. The technology is automating quality assurance protocols that previously required batch-wise destructive testing, compressing qualification cycles from months to weeks.
EFSA's tightened specific migration limits for aluminum and chromium (VI) compounds are forcing substrate suppliers to validate coating adhesion promoters against revised positive lists. European snack-food packagers are demanding third-party migration testing certificates as standard procurement documentation. High-barrier polyester grades for retort applications face the steepest compliance burden, with some legacy coating systems failing the 2024 amended thresholds.
Direct mill relationships are replacing distributor intermediation for volume converters above 500-ton annual offtake. German and US-based food packagers are negotiating toll-metallization contracts with biaxial film producers rather than merchant converters, capturing margin and securing optical density priority allocation. This pattern is most pronounced in North American markets where resin-to-film integration creates captive metallization capacity incentives.
Metallized Rollstock Film Market Segmentation
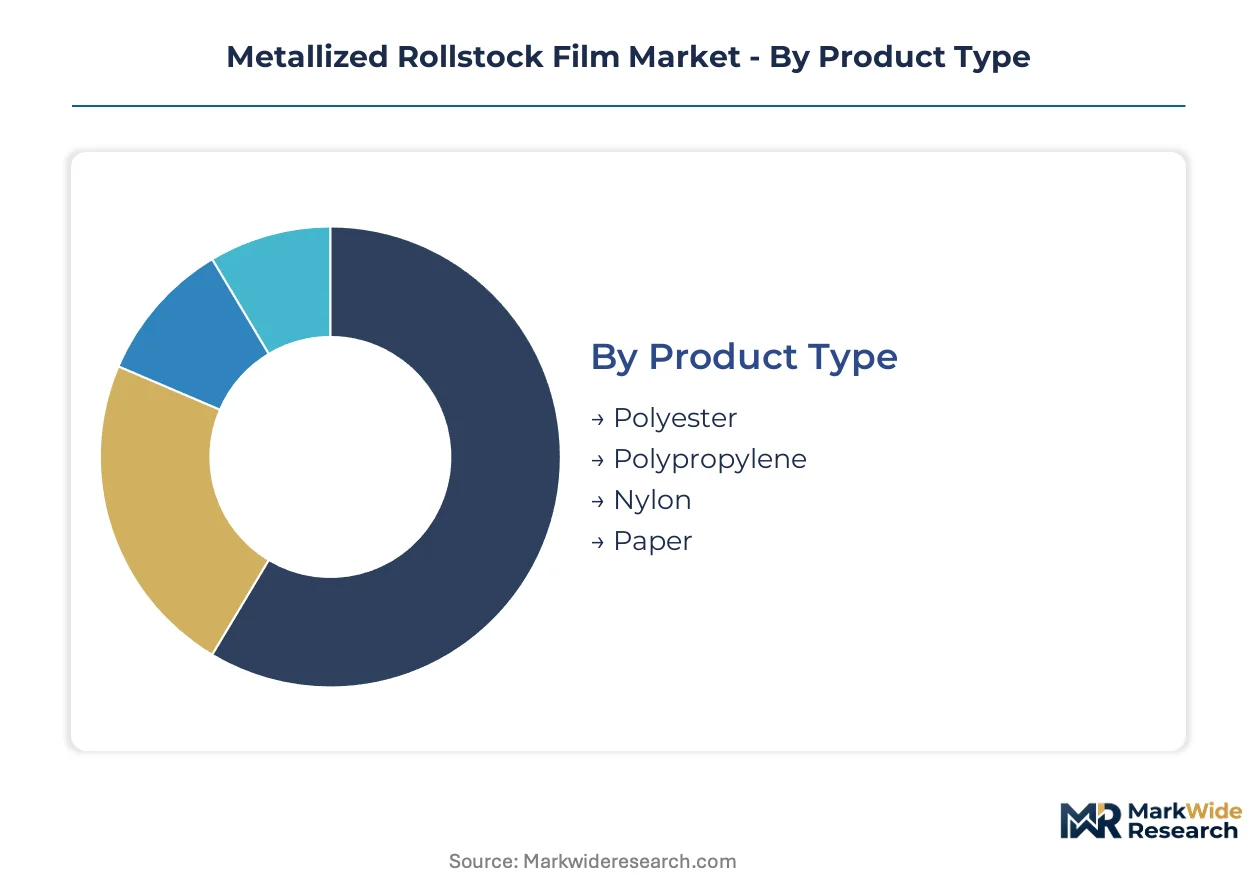
Metallized rollstock film specifications diverge sharply between commodity snack wrapping and precision pharmaceutical barrier applications, forcing converters to maintain parallel qualification tracks across substrate chemistries and thickness bands.
Product Type:
Customization intensity spans from commodity polypropylene grades with standardized optical density ranges to engineered polyester films requiring lot-specific barrier certificates for regulated end-uses.
- Polyester:Biaxially oriented polyethylene terephthalate substrates deliver thermal stability above 200°C and oxygen transmission rates below 0.5 cc/m²/day, concentrating demand in retort pouches and pharmaceutical cold-form alternatives where EFSA migration limits apply. German medical device packagers specify lot-traceable optical density documentation for every roll.
- Polypropylene:Oriented polypropylene dominates flex-crack resistant snack and confectionery wrapping, with Indian flexible packaging converters driving import substitution as FSSAI packaging safety mandates tighten. Toll-metallization agreements in Southeast Asia prioritize PP grade allocation for volume snack-food contracts.
- Nylon:Metallized biaxial nylon films serve thermoformed medical tray lidding requiring puncture resistance and clarity, with Swiss pharmaceutical converters specifying hybrid ceramic-aluminum barrier structures.
- Paper:Metallized paper substrates occupy gift wrap and decorative label niches where surface aesthetics outweigh barrier performance, with Italian luxury goods packagers sourcing from integrated pulp-to-metallization mills.
Leading the category by volume: Polypropylene. Growing fastest: Polyester.
End Use Industry:
Application-driven specification tiers separate food-contact compliance burdens from industrial barrier requirements, with regulatory intensity determining substrate-coating qualification costs.
- Food Packaging:Snack-food packagers in the United States and Germany specify higher optical density films to displace multi-layer laminates, pulling metallized polyester into form-fill-seal lines. FDA food-contact notification rules and REACH adhesion promoter restrictions force dual-track qualification testing.
- Personal Care:Sachet and pouch converters for shampoo and cosmetic samples favor below-50-micron polypropylene grades, with machinery OEMs retrofitting sealing jaws for downgauged webs.
- Electronics:Static-dissipative metallized films serve flexible circuit board packaging and EMI shielding applications, with Japanese electronics assemblers specifying surface resistivity below 10⁶ ohms per square.
- Medical:Tropical climate stability requirements in Southeast Asia pull metallized cold-form foil alternatives into strip packaging formats, with Swiss and Japanese pharmaceutical blister pack converters adopting plasma-enhanced ceramic barrier layers.
Dominant by revenue concentration: Food Packaging. Steepest expansion trajectory: Medical.
Thickness:
Volume scale versus performance premium stratifies procurement patterns, with machinery compatibility constraints locking in legacy specifications while sustainability pressures drive thin-gauge migration.
- Below 50 Microns:Downgauging programs penetrate confectionery wrapping as sealing jaw retrofits enable thinner web handling, with EU Green Deal packaging waste directives incentivizing material reduction.
- 50-100 Microns:Form-fill-seal machinery compatibility clusters demand in this band, with German food packagers negotiating toll-metallization contracts for optical density priority allocation.
- 100-150 Microns:High-barrier retort applications and pharmaceutical blister lidding specify this range, with EFSA's tightened aluminum migration limits forcing coating revalidation.
- Above 150 Microns:Heavy-duty industrial wrapping and insulation facing applications occupy this niche, with US construction material distributors sourcing through direct mill relationships.
Highest shipment volumes: 50-100 Microns. Gaining share fastest: Below 50 Microns.
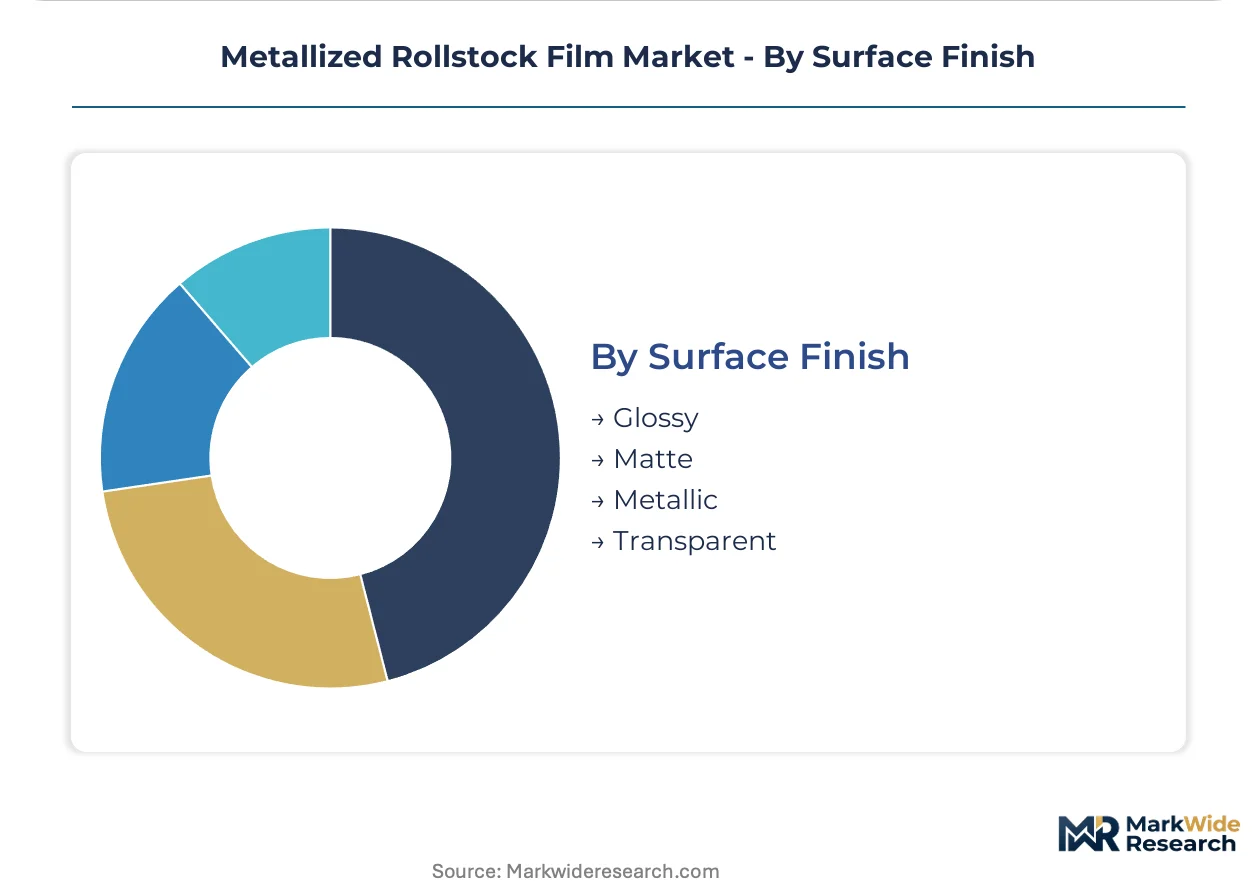
Surface Finish:
Aesthetic differentiation commands premium pricing in consumer-facing applications, while functional finishes serve detection and processing requirements in automated packaging lines.
- Glossy:High-reflectance aluminum deposition dominates premium snack and confectionery presentation, with Swiss chocolate packagers specifying mirror-grade surface quality for shelf impact.
- Matte:Diffused metal layers serve luxury cosmetic and personal care segments where subdued elegance differentiates brand positioning, with French beauty houses sourcing through exclusive converter agreements.
- Metallic:Standard optical density specifications balance barrier performance with cost, occupying the bulk of commodity food packaging volume in India and the United States.
- Transparent:Silicon oxide and aluminum oxide hybrid coatings enable metal-detector-compatible microwaveable packaging, displacing pure metallized grades where line interference creates quality control failures.
Widest application coverage: Metallic. Most rapid specification growth: Transparent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum feedstock availability and polymer substrate manufacturing clusters anchor metallized rollstock film production across four distinct national markets. Vacuum deposition capacity concentrates near biaxial film extrusion sites to minimize web handling damage and optical density variation.
United States
Snack-food packagers in Wisconsin and Pennsylvania specify higher optical density metallized polyester for form-fill-seal lines replacing multi-layer laminates. FDA food-contact notification rules force substrate-coating requalification cycles that favor domestic toll-metallizers with established compliance documentation. Chicago-area flexible packaging converters negotiate direct mill relationships for volume allocation priority.
Germany
Medical device packagers in Bavaria demand lot-traceable optical density certificates for every metallized polyester roll entering pharmaceutical cold-form alternatives. ECHA REACH adhesion promoter restrictions accelerate migration to compliant coating chemistries, creating first-mover advantage for qualified substrate suppliers. The Rhine-Ruhr industrial corridor hosts integrated resin-to-film operations sustaining consistent barrier specifications.
India
Domestic snack consumption growth and FSSAI packaging safety mandates drive import substitution for regional metallizers serving flexible packaging converters in Maharashtra and Gujarat. Toll-metallization agreements prioritize polypropylene grade allocation for volume snack-food contracts. Biaxial film producers in the Delhi-NCR region realign capacity toward metallized grades capturing European export demand.
Japan
Electronics assemblers in the Kanto region specify static-dissipative metallized films with surface resistivity below 10⁶ ohms per square for flexible circuit board packaging. METI industrial standards govern vacuum deposition chamber emissions alongside EPA-equivalent hazardous air pollutant protocols. Toray Plastics leverages integrated operations across Japan and the United States to sustain thermal stability specifications above 200°C.
Switzerland
Pharmaceutical blister pack converters in Basel adopt plasma-enhanced ceramic-aluminum hybrid barrier structures achieving oxygen transmission rates below 0.1 cc/m²/day. Swissmedic pharmaceutical packaging regulations and EFSA migration limits determine qualified substrate-coating combinations for tropical climate stability applications. The Swiss chemical-pharma cluster drives precision barrier specification development for strip packaging formats.
Metallized Rollstock Film Market Competitive Landscape
Global majors compete with regional champions across metallization capacity and substrate integration depth, producing a tiered structure where resin-to-film operators hold specification control. The vendor base splits between integrated polymer producers with captive vacuum deposition lines and merchant toll-metallizers serving flexible packaging converters. Three archetypes dominate: integrated resin-to-film majors, regional biaxial specialists with metallization partnerships, and pure-play toll-metallizers focused on optical density precision. Capacity expansion and toll-metallization contract restructuring constitute the primary competitive moves as converters seek supply security.
Within the integrated resin-to-film tier, Toray Plastics and Amcor exemplify operations spanning multiple continents with captive metallization capacity. Jindal Poly Films Limited and Uflex Limited occupy positions among Asia-Pacific biaxial specialists leveraging regional substrate production for export market penetration. SRF Limited represents the Indian regional champion archetype, positioned to capture domestic flexible packaging expansion under tightening FSSAI mandates.
| Leading Market Players |
|---|
| Toray Plastics |
| Sealed Air Corporation |
| Jindal Poly Films Limited |
| SRF Limited |
| Berry Global |
| Uflex Limited |
| Amcor |
| DUNMORE Corporation |
| Cosmo Films |
| Others |
Supply & Pricing Matrix
Extended shelf-life mandates from German and US snack-food packagers are forcing substrate suppliers to absorb costly REACH and FDA requalification cycles, compressing margins on standardized polypropylene grades while creating premium capture opportunities for qualified polyester suppliers with compliant coating documentation.
Pricing Analysis
Warranty-backed optical density certification now separates premium metallized polyester contracts from commodity polypropylene transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by migration-test documentation depth and lot-traceability granularity. Cost compression in below-50-micron grades is intensifying because toll-metallizers compete for downgauging program volumes. Indian flexible packaging converters exhibit highest price sensitivity, while Swiss pharmaceutical blister pack converters prioritize barrier precision over unit cost.
Supply Chain Analysis
Vacuum deposition technician shortages in Germany, Japan, and the United States are extending optical density calibration training pipelines and inflating wage premiums for precision thickness control skills. Raw material flows draw from biaxial film extrusion clusters in India and China, aluminum ingot suppliers tied to LME trading bands, and REACH-compliant adhesion promoter specialists in the Rhine-Ruhr corridor. Single-source vulnerability concentrates in integrated resin-to-film operations where captive metallization capacity limits third-party access. Distribution runs through direct mill relationships for volume converters above 500-ton annual offtake, bypassing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA hazardous air pollutant scrubber retrofits and REACH compliance burdens are forcing mid-converter exits and concentrating share among integrated majors with balance sheet capacity for capital-intensive qualification cycles.
For Market Incumbents: To counter silicon oxide-coated film displacement in microwaveable applications, Toray Plastics and Amcor should deepen captive metallization capacity in Japan and the United States while accelerating plasma-enhanced ceramic barrier R&D for pharmaceutical hybrid structures. Securing toll-metallization priority allocation through long-term offtake contracts with German medical device packagers anchors high-margin polyester volume. For New Entrants and Emerging Players: Toll-metallization partnerships with Southeast Asian biaxial film producers offer the most penetrable entry vector for serving European snack-food export demand. Targeting Indian domestic flexible packaging expansion under tightening FSSAI mandates provides white-space access with lower qualification overhead than Atlantic markets. A certification-first go-to-market angle emphasizing third-party migration testing documentation differentiates against legacy merchant converters. For Investors and Strategic Acquirers: The window for entry favors regional biaxial specialists with latent metallization capacity and established FDA or REACH compliance documentation. Over the coming decade, substrate-coating integration depth determines competitive viability as specification control migrates upstream. Watch for EFSA migration limit threshold revisions as the inflection signal triggering accelerated coating chemistry replacement cycles and distressed asset opportunities among non-compliant legacy operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive PET and OPP substrate supply secures optical density consistency for Toray Plastics across Japanese and US operations. |
| Plasma-Enhanced CVD Capacity Buildout | Swiss pharmaceutical blister pack converters adopt hybrid ceramic-aluminum barriers achieving sub-0.1 cc/m²/day oxygen transmission rates. |
| REACH-Compliant Coating Chemistry Migration | First-mover substrate suppliers capture displaced European converter volume as ECHA adhesion promoter restrictions tighten. |
| Direct Mill Relationship Structuring | German and US food packagers negotiate toll-metallization contracts bypassing distributor intermediation for margin capture. |
| Below-50-Micron Downgauging Program Investment | Machinery OEM sealing jaw retrofits enable thinner web handling for EU Green Deal packaging waste compliance. |
Research Methodology
Independent corroboration across vacuum deposition technicians, flexible packaging procurement directors, and pharmaceutical quality assurance managers underwrites the qualitative findings in this study. Primary fieldwork encompassed substrate engineers at biaxial film producers, toll-metallization operators, and regulatory affairs specialists navigating FDA food-contact notification protocols. Secondary validation drew from ECHA REACH substance restriction updates, EPA hazardous air pollutant standards documentation, SEC filings of integrated resin-to-film majors, and customs trade data tracking metallized rollstock cross-border flows. Bottom-up volume estimates triangulated against top-down market sizing derived from polymer substrate production capacity and aluminum vapor deposition utilization rates.
Rate-of-change decomposition across the analysis window isolates volume drivers by substrate chemistry, thickness band, and end-use regulatory intensity. Segmentation modeling spans polyester versus polypropylene versus nylon substrate types, food packaging versus pharmaceutical versus electronics end-use industries, and below-50-micron through above-150-micron thickness tiers. CAGRs were derived from fitted growth curves anchored to biaxial film capacity expansion announcements and metallization line commissioning schedules. Forecast inputs incorporate EFSA migration limit amendment trajectories and FSSAI packaging safety mandate implementation pacing.
Caveats apply where aluminum spot price volatility, REACH substance list revisions, or FDA food-contact notification rule amendments could materially shift the outlook for substrate-coating qualification costs and competitive positioning. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Fanfold Market
Packaging Materials
Window Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Packaging Primers Market
Packaging Materials
PET Strap Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Strip Pack Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Europe Airless Packaging Market