
 Brazil Packaging Market | 2026-2036
Brazil Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Packaging Market Outlook
A capital-intensity divergence between integrated resin-to-film producers and standalone converters is redrawing competitive boundaries in Brazilian packaging. Braskem leverages its petrochemical feedstock position to supply captive polyethylene grades to downstream film operations. Sealed Air Corporation anchors the protective and food-segment landscape through automated packaging systems deployed with major protein processors.
Brazil packaging encompasses the design, fabrication, and supply of primary, secondary, and tertiary containment systems using substrates such as polyethylene terephthalate, oriented polypropylene, and molded fiber with specified barrier coefficients against oxygen and moisture transmission. Its commercial purpose centers on product preservation, shelf-life extension, and logistical unitization across manufacturing and retail networks. Flexible packaging leads volume consumption in food and beverage applications where lightweighting and format versatility reduce freight cost per unit. Rigid plastic formats dominate personal care and household chemical segments where dispensing functionality and shelf presence command margin premiums.
ANVISA mandates serialization and tamper-evidence standards for pharmaceutical primary packaging, compelling capital outlays on vision systems and coding equipment. The Brazilian Institute of Metrology, Quality and Technology enforces dimensional and labeling conformity for pre-packaged goods sold through regulated retail channels. IBAMA's extended producer responsibility frameworks for plastic waste are redirecting material choices toward post-consumer recycled content and monomaterial constructions. Stakeholders must monitor how pending federal packaging waste legislation alters cost structures for virgin resin versus recycled feedstock procurement.
Market Dynamics
ANVISA's pharmaceutical serialization mandate is compressing capital deployment timelines across Brazilian packaging converters, forcing simultaneous upgrades to track-and-trace infrastructure while resin volatility squeezes margin structures.
Growth Catalysts
- ANVISA serialization compliance:Pharmaceutical primary packaging lines require vision systems and coding equipment, pulling investment toward high-value security formats.
- Protein processor automation:Major meatpacking facilities are adopting modified-atmosphere barrier films to extend shelf-life for Mercosur export channels.
- São Paulo converter clustering:Dense packaging film production in the state's industrial corridor reduces logistics costs for domestic brands and regional exporters.
Market Restraints
- Ethylene feedstock volatility:Braskem's naphtha-linked pricing transmits petrochemical cost swings directly to polyethylene film converters.
- IBAMA extended producer responsibility:Pending federal packaging waste legislation creates uncertainty in virgin versus recycled resin procurement economics.
- Monomaterial technical ceilings:High-barrier food applications still require multi-layer constructions that complicate mechanical recycling streams.
Strategic Opportunities
- Post-consumer recycled content mandates:IBAMA's evolving frameworks reward early adopters of rPET and rPE film formulations with preferential licensing.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics growth demands insulated shippers and phase-change material integration.
- E-commerce corrugated substitution:Flexible mailer formats are displacing rigid boxes in São Paulo's last-mile delivery networks.
Industry Challenges
- Vision systems integration:Pharmaceutical lines require simultaneous hardware, software, and validation expertise that concentrates among specialized integrators.
- Multi-layer delamination:Separating barrier film polymers for chemical recycling demands solvent-based or enzymatic processes not yet scaled domestically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Packaging Market |
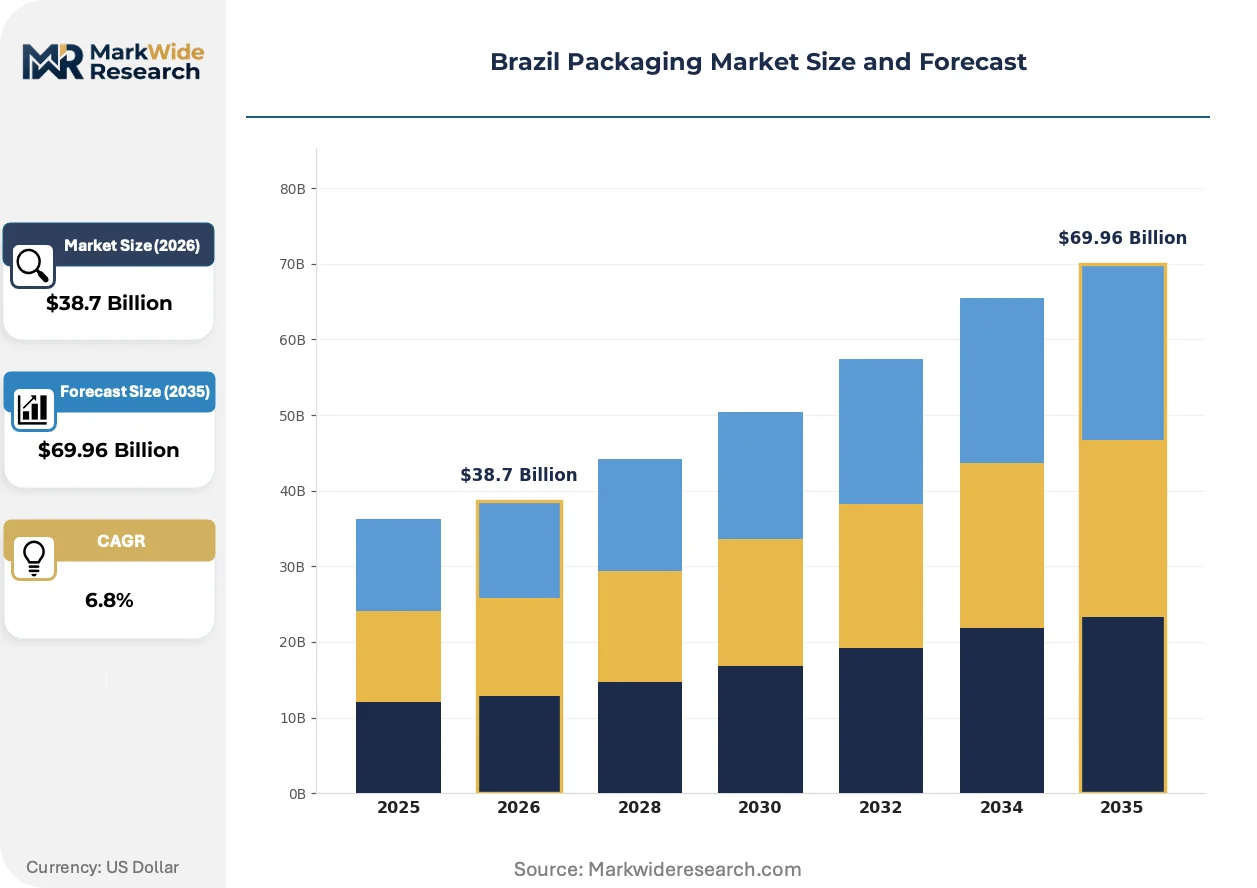
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
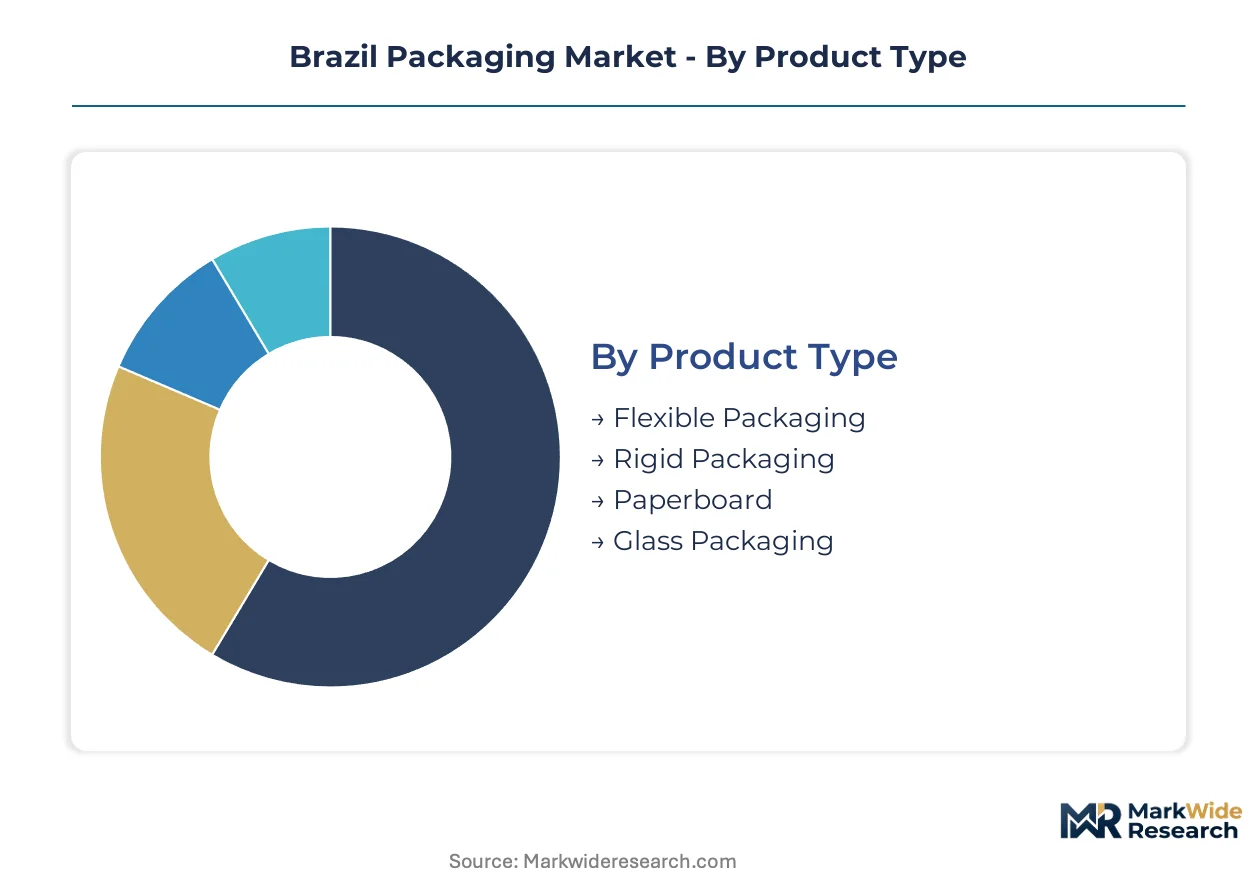
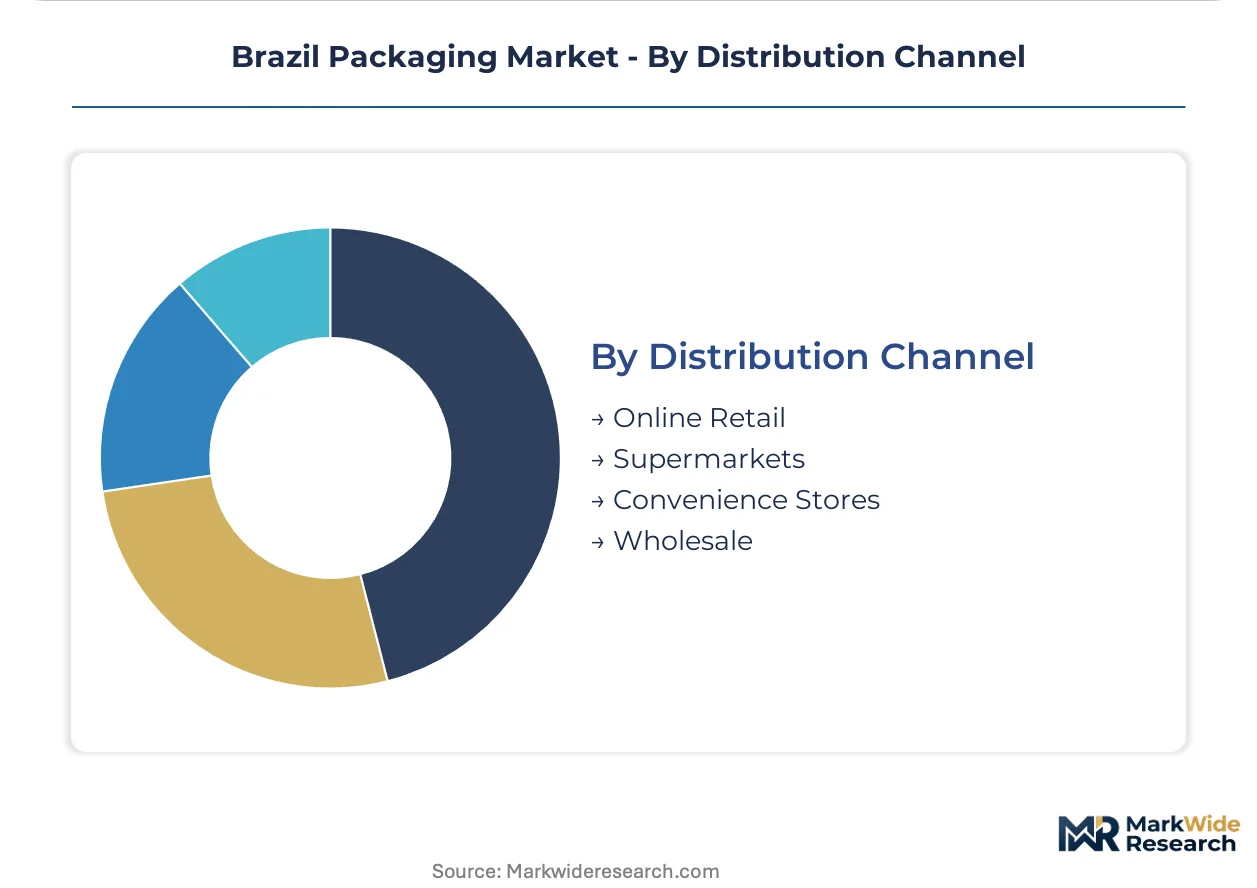
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard, Glass Packaging Material: Plastic, Paper, Metal, Wood End User: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Sealed Air Corporation, Tigre Group, Amcor Group GmbH, Plaszom Industria De Plasticos Ltda, Irani Papel e Embalagem, Sonoco Products Company, Braskem, Parnaplast Industria de Plasticos Ltda, Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Packaging Market Strategic Shifts
Digital printing and smart packaging formats are collapsing minimum order quantities while regulatory pressure on traceability accelerates inline inspection adoption across Brazilian converter floors.
Digital inkjet printing for flexible packaging is miniaturizing run economics, enabling brand owners to execute regional SKU proliferation without plate changeover costs. Mid-sized food processors in Minas Gerais and Paraná are adopting this for seasonal promotional runs. The technology is miniaturizing the traditional volume threshold that justified gravure cylinder investments, compressing converter capacity planning cycles.
ANVISA's updated pharmaceutical serialization rules mandate unique identifier aggregation from primary through tertiary packaging levels. This forces line rebuilds integrating cameras, reject systems, and aggregation software. Injectable and oncology drug manufacturers face the steepest compliance curves given existing manual packaging workflows.
Brand owners are consolidating supplier panels toward converters offering integrated design-to-recyclability services. Retail chains in Brazil's Southeast are demanding monomaterial specifications aligned with store drop-off collection infrastructure. This specification tightening is most visible in personal care and household chemical segments where dispensing closure compatibility with PET bottle recycling streams now dominates procurement scoring.
Brazil Packaging Market Segmentation
Segmentation in Brazilian packaging reveals how substrate choices and channel configurations respond to ANVISA mandates, IBAMA waste frameworks, and São Paulo's industrial clustering. Understanding these divisions exposes where substitution pressure and margin compression concentrate across converter operations.
Product Type:
Flexible formats face the most acute substitution threat from rigid alternatives as brand owners weigh barrier performance against recyclability mandates.
- Flexible Packaging:Multi-layer polyethylene and polypropylene films dominate protein exports through modified-atmosphere configurations. São Paulo's converter corridor supplies Mercosur meatpackers with high-barrier structures that extend shelf-life for refrigerated distribution. ANVISA serialization rules are pulling pharmaceutical blister films toward tamper-evident specifications.
- Rigid Packaging:Injection-molded HDPE and PET containers command premium positioning in personal care dispensing applications. Minas Gerais dairy processors are converting from carton to PET bottle formats for cold-chain distribution. IBAMA's pending EPR legislation is accelerating rPET adoption in rigid formats.
- Paperboard:Folding cartons serve secondary packaging for electronics and processed foods with FSC-certified sourcing increasingly specified by Southeast retail chains.
- Glass Packaging:Amber and flint containers retain pharmaceutical and premium beverage applications where inertness and shelf presence justify freight cost premiums.
Flexible packaging retains volume leadership; rigid packaging holds the steepest expansion curve as recyclability specifications tighten procurement scoring.
Material:
Cost tier stratification separates commodity resin grades from certified recycled feedstocks as IBAMA frameworks reshape procurement economics.
- Plastic:Polyethylene terephthalate and oriented polypropylene films constitute the dominant substrate class across food and pharmaceutical applications. Braskem's captive polyethylene supply chains transmit naphtha-linked pricing volatility directly to converter margin structures. Post-consumer recycled content mandates are forcing rPET and rPE formulation investments.
- Paper:Kraft and bleached board grades serve corrugated shipping containers and retail-ready displays with e-commerce demand driving flute substitution toward lighter basis weights.
- Metal:Aluminum aerosol cans and steel drums retain industrial chemical and personal care propellant applications where pressure resistance is non-negotiable.
- Wood:Pallets and crates support bulk agricultural export logistics with heat-treated certification required for international phytosanitary compliance.
Plastic commands the largest share by tonnage; paper is gaining share fastest in e-commerce secondary packaging applications.
End User:
Application-specific barrier requirements and regulatory exposure create divergent margin profiles across customer verticals.
- Food & Beverage:Protein processors in Paraná and Minas Gerais drive demand for vacuum skin packs and modified-atmosphere trays. Barrier film specifications prioritize oxygen transmission rates below 5 cc/m²/day for refrigerated beef exports.
- Personal Care:Dispensing closure compatibility with PET recycling streams now dominates procurement scoring for shampoo and conditioner bottles.
- Pharmaceuticals:ANVISA serialization mandates are forcing track-and-trace infrastructure investments across primary packaging lines for injectable and oncology drug manufacturers.
- Chemicals:UN-certified drums and intermediate bulk containers serve agrochemical distribution with corrosion-resistant barrier specifications.
Food and beverage retains volume leadership; pharmaceuticals holds the steepest expansion curve driven by serialization compliance and biologics cold-chain growth.
Distribution Channel:
Customer type fragmentation between retail and institutional buyers shapes order quantity economics and format specifications.
- Online Retail:Flexible mailer formats are displacing corrugated boxes in São Paulo's last-mile delivery networks with damage-rate specifications driving padded envelope adoption.
- Supermarkets:Retail-ready display cases and modified-atmosphere produce trays serve Southeast Brazilian chains with shelf-life extension requirements.
- Convenience Stores:Single-serve portion packs and resealable flexible formats address grab-and-go consumption patterns in urban centers.
- Wholesale:Bulk corrugated cases and stretch-wrapped pallet configurations serve cash-and-carry operators with unitization efficiency priorities.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve as e-commerce penetration accelerates format substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's converter corridor commands pricing leverage over Minas Gerais processors due to logistics density and export corridor access. Paraná protein packers face feedstock cost premiums that Rio Grande do Sul converters offset through Mercosur border proximity. This geographic asymmetry shapes procurement patterns across Brazilian packaging demand centers.
São Paulo
Modified-atmosphere barrier films for protein exports and pharmaceutical serialization infrastructure dominate capital deployment. ANVISA's track-and-trace mandates accelerate vision system adoption across primary packaging lines. The state's industrial corridor clusters film converters serving both domestic brands and Mercosur channels with reduced freight cost per unit.
Minas Gerais
Dairy processors convert from carton to PET bottle formats for cold-chain distribution, pulling rigid packaging demand. IBAMA's pending extended producer responsibility frameworks create uncertainty in virgin versus recycled resin procurement economics. Belo Horizonte's converter base serves regional food processors with mid-volume flexible film operations.
Paraná
Meatpacking facilities adopt vacuum skin packs and modified-atmosphere trays with oxygen transmission specifications below 5 cc/m²/day for refrigerated beef exports. The state's national pharmaceutical regulator compliance timelines compress investment windows for track-and-trace upgrades. Curitiba anchors a converter cluster balancing protein export demand with domestic retail format supply.
Rio Grande do Sul
Agrochemical distribution drives UN-certified drum and intermediate bulk container specifications with corrosion-resistant barrier requirements. Mercosur border proximity enables cross-border logistics optimization for export-oriented converters. Porto Alegre's industrial base supplies southern Brazilian chemical processors with rigid packaging formats.
Bahia
Single-serve portion packs and resealable flexible formats address grab-and-go consumption patterns in urban centers. The state's emerging converter capacity serves Northeast Brazilian retail chains with lower volume thresholds than Southeast competitors. Salvador's packaging operations focus on convenience store distribution channels with simplified format specifications.
Brazil Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazilian packaging. Integrated resin-to-film producers leverage captive polyethylene supply chains against standalone converters dependent on spot resin markets. Three archetypes dominate: petrochemical-backed film operations, automated packaging system integrators, and regional flexible format specialists. Competitive moves concentrate on backward integration into resin production and strategic partnerships with protein processor automation programs.
Among Brazil-based industrial groups, Braskem exemplifies the petrochemical-integrated archetype through its naphtha-linked polyethylene supply position. Sealed Air Corporation anchors the automated packaging systems tier with deployment relationships across major protein processors. Amcor Group GmbH occupies a position within the multinational flexible and rigid format specialist tier serving pharmaceutical and food segments. These three represent distinct strategic positions without overlapping core capabilities.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Tigre Group |
| Amcor Group GmbH |
| Plaszom Industria De Plasticos Ltda |
| Irani Papel e Embalagem |
| Sonoco Products Company |
| Braskem |
| Parnaplast Industria de Plasticos Ltda |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
rPET substitution for virgin polyethylene terephthalate in rigid packaging formats is simultaneously redrawing converter geography toward São Paulo's recycling infrastructure clusters and compressing pricing premiums for certified recycled feedstocks. This material transition concentrates procurement leverage among integrated resin-to-film producers while standalone converters absorb spot market volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical serialization lines from standard flexible film operations. Three-tier pricing structure across premium, standard, and economy levels tracks barrier performance specifications and ANVISA compliance certification tiers. Cost compression in standard-grade polyethylene film is intensifying because Braskem's naphtha-linked pricing transmits petrochemical volatility directly to converter margins. Protein processors demonstrate highest price sensitivity due to export margin compression, while pharmaceutical manufacturers absorb premiums for tamper-evident and track-and-trace configurations.
Supply Chain Analysis
Just-in-time resin procurement dominates São Paulo converter operations, while strategic stockpiling of post-consumer recycled flake accumulates in anticipation of IBAMA mandate enforcement. Geographic supply concentration centers on Braskem's Brazilian polyethylene production, Argentine polypropylene imports, and emerging domestic rPET processing capacity. Raw material dependencies include naphtha-derived ethylene, imported propylene monomer, and mechanically recycled PET flake. Single-source vulnerability runs through Braskem's captive supply chains. Distribution runs through converter clusters in São Paulo state's industrial corridor serving Mercosur export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian packaging presents a service-attach opportunity as track-and-trace validation and recycling compliance consulting expand faster than base film and container sales. Recurring revenue from serialization line maintenance and EPR reporting services outpaces hardware growth curves.
For Market Incumbents: Consolidate backward integration into post-consumer recycled flake processing to defend margin position against resin price volatility. Secure long-term offtake agreements with protein processor automation programs. Braskem's feedstock dominance and IBAMA's pending EPR mandates together threaten standalone converters lacking recycled content capabilities. For New Entrants and Emerging Players: ANVISA certification fast-track services for pharmaceutical packaging lines offer immediate white-space access. Target mid-sized food processors in Minas Gerais and Paraná with digital printing-enabled short-run flexible formats. Deploy design-to-recyclability consulting as the primary go-to-market wedge against established converter relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed flexible film specialists lacking pharmaceutical serialization expertise. Long-term viability over the coming decade hinges on regulatory compliance service capabilities rather than commodity film production scale. Monitor IBAMA enforcement timelines as the critical inflection signal for recycled content mandate economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Processing | Captures margin from IBAMA's recycled content mandates while reducing virgin resin exposure. |
| Pharmaceutical Serialization Line Certification | ANVISA compliance creates defensible positioning against commodity converter competition. |
| Protein Processor Automation Partnership | Modified-atmosphere barrier film demand from Mercosur exporters locks in volume commitments. |
| Digital Printing Platform Deployment | Short-run economics for Minas Gerais food processors collapse minimum order quantity thresholds. |
| Design-to-Recyclability Service Launch | Monomaterial specification expertise aligns with Southeast retail chain procurement scoring. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, IBAMA waste framework documentation, and Brazilian Institute of Metrology technical standards. Primary interviews engaged packaging converter operations managers, pharmaceutical regulatory affairs leads, protein processor procurement directors, and retail chain sustainability officers. Secondary sources included Braskem resin pricing disclosures, customs trade data for polyethylene and polypropylene imports, and SEC filings from multinational packaging system integrators. Bottom-up volume modeling triangulated against top-down value estimates across substrate and end-use dimensions.
Segmentation dimensions modeled include product type (flexible, rigid, paperboard, glass), material substrate (plastic, paper, metal, wood), end-user vertical (food and beverage, personal care, pharmaceuticals, chemicals), and distribution channel (online retail, supermarkets, convenience stores, wholesale). CAGRs were derived through trend extrapolation validated against historical elasticity patterns. Forecast inputs incorporated ANVISA serialization compliance timelines, IBAMA extended producer responsibility phase-in schedules, and protein export volume projections through Mercosur channels.
Decision-makers should treat outputs as directional under assumptions of stable petrochemical feedstock pricing and phased IBAMA enforcement; material deviation would warrant model refresh. Forecasts reflect base-case regulatory implementation without anticipating accelerated mandate timelines or trade policy disruptions. Practitioners should keep alternative scenarios live as ANVISA inspection intensity and federal packaging waste legislation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Non-Plastic Punnets Market