
 Standard Liner Market | 2026-2036
Standard Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Standard Liner Market Analytics
Municipal infrastructure buyers are collapsing procurement timelines as aging water management systems force accelerated replacement schedules. Greif leverages its integrated manufacturing footprint to capture bulk municipal contracts across North American utilities. Thrace Group anchors its position through specialized geomembrane production for containment applications. Berry Global competes on material science breadth, extending its polymer portfolio into reinforced liner grades for demanding industrial environments.
A standard liner is a flexible synthetic membrane, typically manufactured from PVC, EPDM, HDPE, or vinyl through calendering or extrusion processes, designed to create impermeable barriers between a contained substance and the surrounding soil or structure. These membranes generally range from 20 mil to 60 mil in thickness and serve primarily to prevent seepage in liquid containment, waste management, and water retention systems. HDPE liners dominate the product type landscape due to their chemical resistance and extended service life in harsh environments, while PVC alternatives sustain demand in swimming pool and decorative water feature installations where flexibility and ease of fabrication matter more than extreme chemical tolerance. The application split reveals municipal and industrial end uses as the margin-rich segments, with residential fish ponds and agricultural tanks occupying lower-price, higher-volume tiers.
The EPA enforces Subtitle D landfill liner standards that mandate minimum thickness and material performance for hazardous and municipal waste containment, directly shaping HDPE specification requirements across North American projects. State-level environmental agencies in California, Texas, and Florida impose additional groundwater protection rules that layer compliance complexity onto liner procurement decisions. ASTM D7176 and GRI GM17 standards govern geomembrane quality testing, creating certification barriers for non-compliant suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as PFAS-free material formulations are becoming a decisive bid qualification criterion in public infrastructure tenders.
Market Dynamics
Municipal infrastructure buyers are collapsing procurement timelines as aging water management systems force accelerated replacement schedules. Greif leverages its integrated manufacturing footprint to capture bulk municipal contracts across North American utilities. Thrace Group anchors its position through specialized geomembrane production for containment applications. Berry Global competes on material science breadth, extending its polymer portfolio into reinforced liner grades for demanding industrial environments.
Growth Catalysts
- EPA Subtitle D mandates:Updated landfill liner standards in the United States tighten material performance thresholds, forcing facility upgrades and replacement cycles.
- Industrial corridor expansion:China's municipal wastewater containment projects around Shanghai and Tianjin are accelerating liner procurement volumes.
- Geomembrane specification convergence:ASTM D7176 and GRI GM17 quality testing standards create certification pull-through for compliant HDPE suppliers.
Market Restraints
- HDPE resin cost volatility:Feedstock price swings in polyethylene production compress margin stability for calendering and extrusion operators.
- PFAS formulation restrictions:State-level environmental agencies in California and Florida impose additional groundwater protection rules that complicate material qualification.
- EPDM substitution pressure:Alternative synthetic rubber membranes compete in decorative water features where chemical resistance requirements are lower.
Strategic Opportunities
- PFAS-free material innovation:PFAS-free formulations are becoming decisive bid qualification criteria in public infrastructure tenders across multiple states.
- Reinforced liner grades:Industrial environments in Texas are demanding polymer portfolio extensions for demanding containment applications.
- Certification-as-differentiation:Third-party verification under GRI GM17 creates pricing power for qualified suppliers against uncertified imports.
Industry Challenges
- Multi-jurisdiction compliance complexity:Municipal buyers must navigate overlapping federal EPA standards with state groundwater protection rules.
- Geomembrane installation skill scarcity:Field welding and seam testing expertise limits deployment velocity for large-scale containment projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standard Liner Market |
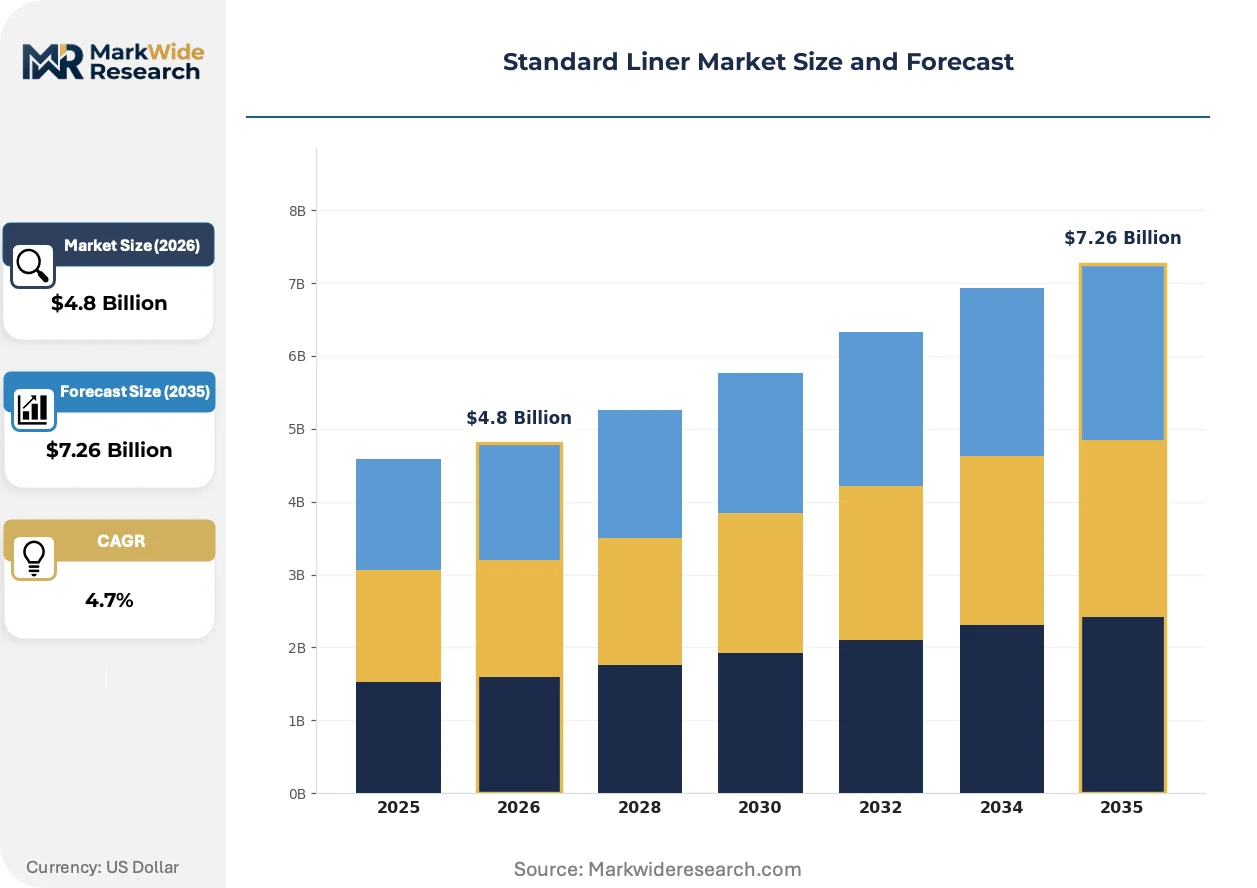
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Liners, EPDM Liners, HDPE Liners, Vinyl Liners Application: Swimming Pools, Water Features, Fish Ponds, Agricultural Tanks Thickness: 20 mil, 30 mil, 40 mil, 60 mil End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Greif, Thrace Group, SIA Flexitanks, Nissei, Amcor, Berry Global, United Bags, Display Pack, CDF Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standard Liner Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape competitive positioning in liner specification. Three forces are actively restructuring how buyers evaluate performance, how suppliers qualify products, and how value distributes across the value chain.
Co-extruded multilayer geomembranes are decomposing the traditional trade-off between chemical resistance and installation flexibility. Municipal wastewater operators in the United States are specifying these structures for anaerobic digester covers and lagoon caps. The technology is decomposing PVC's historical lock on swimming pool and decorative applications by delivering comparable weldability with superior UV stability.
REACH restrictions on persistent organic pollutants are forcing reformulation of plasticizer packages in European PVC liner production. Industrial containment buyers in Germany and France now require full material disclosure documentation upstream of contract award. The policy shift is compressing lead times for qualified suppliers while creating compliance barriers for commodity importers.
Specification authority is migrating from general contractors to owner's engineers in large municipal projects. Engineering firms in China's industrial corridor cities are consolidating liner selection decisions into pre-qualification frameworks. This concentration is elevating certified geomembrane suppliers while marginalizing spot-market traders without testing documentation.
Standard Liner Market Segmentation
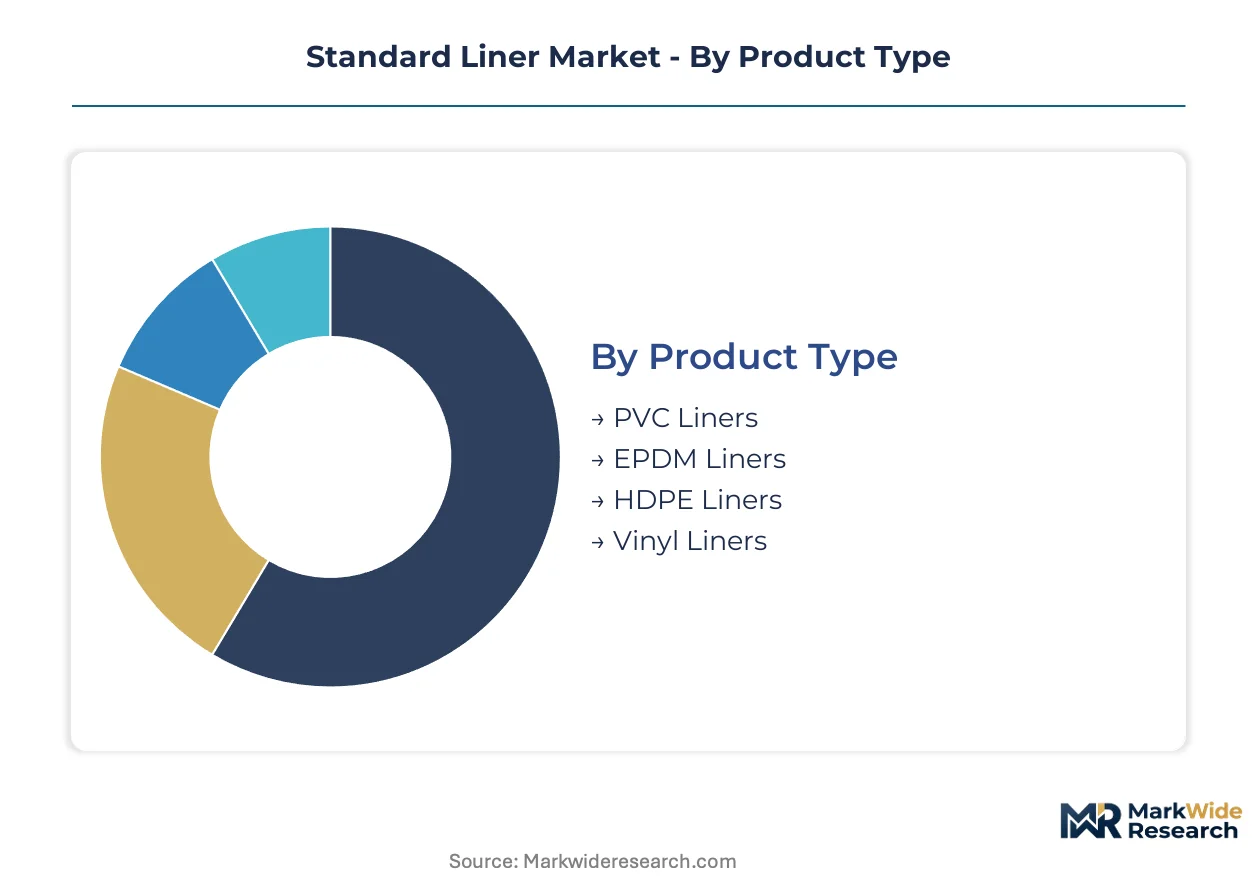
Material specification and application environment drive margin distribution across liner categories. End-user procurement sophistication varies dramatically, with municipal buyers demanding certified geomembranes while residential purchasers prioritize cost efficiency over testing documentation.
Product Type:
Margin pools concentrate in chemically resistant formulations for hazardous containment, while flexible alternatives capture decorative water feature volume at lower unit economics.
- HDPE Liners:High-density polyethylene geomembranes deliver superior chemical resistance and extended service life in harsh environments. Municipal landfill and wastewater containment projects in the United States specify these membranes under EPA Subtitle D mandates, with state agencies in California and Texas layering additional groundwater protection requirements.
- PVC Liners:Polyvinyl chloride membranes offer weldability and installation flexibility through calendered sheet construction. Swimming pool contractors and decorative water feature installers favor these liners where chemical tolerance requirements remain moderate and fabrication speed matters.
- EPDM Liners:Synthetic rubber membranes compete in residential fish ponds and ornamental applications with lower chemical exposure profiles.
- Vinyl Liners:Cost-optimized formulations serve high-volume agricultural tank installations where specification authority rests with equipment manufacturers rather than engineering consultants.
HDPE holds installed capacity. PVC is rotating up the share rankings in decorative applications as co-extruded multilayer structures displace traditional formulations.
Application:
Procurement sophistication escalates from residential hobbyist purchases to municipal engineering specifications, with containment risk dictating margin tier.
- Swimming Pools:Residential and commercial pool builders specify 30 mil to 40 mil PVC or reinforced vinyl liners for watertight vessel construction. REACH restrictions on plasticizer packages in European production are forcing material disclosure documentation upstream of contract award.
- Water Features:Decorative fountain and pond installations demand UV-stable membranes with aesthetic surface finishes. Chinese industrial corridor cities around Shanghai are specifying these for municipal landscape projects alongside wastewater containment infrastructure.
- Fish Ponds:Hobbyist-grade EPDM and PVC alternatives dominate this price-sensitive residential segment with minimal certification requirements.
- Agricultural Tanks:Equipment-integrated liners for irrigation and livestock watering systems prioritize cost efficiency over extended service life specifications.
Water Features is expanding most quickly in municipal procurement. Swimming Pools maintains volume leadership through replacement cycle demand.
Thickness:
Specification minimums from environmental regulators and engineering consultants compress demand into certified thickness tiers, leaving thinner gauges for non-critical applications.
- 60 mil:Maximum thickness grade specified for hazardous waste landfills and industrial containment under ASTM D7176 quality testing standards. Municipal buyers in Florida and Texas require these membranes for groundwater protection compliance.
- 40 mil:Intermediate grade serving municipal wastewater lagoons and anaerobic digester covers where puncture resistance competes with installation flexibility.
- 30 mil:Standard swimming pool and decorative water feature specification balancing cost against durability expectations.
- 20 mil:Entry-level gauge for residential fish ponds and temporary agricultural installations with limited service life requirements.
60 mil holds installed capacity. 40 mil is rotating up the share rankings as co-extruded structures substitute for thicker monolithic membranes.
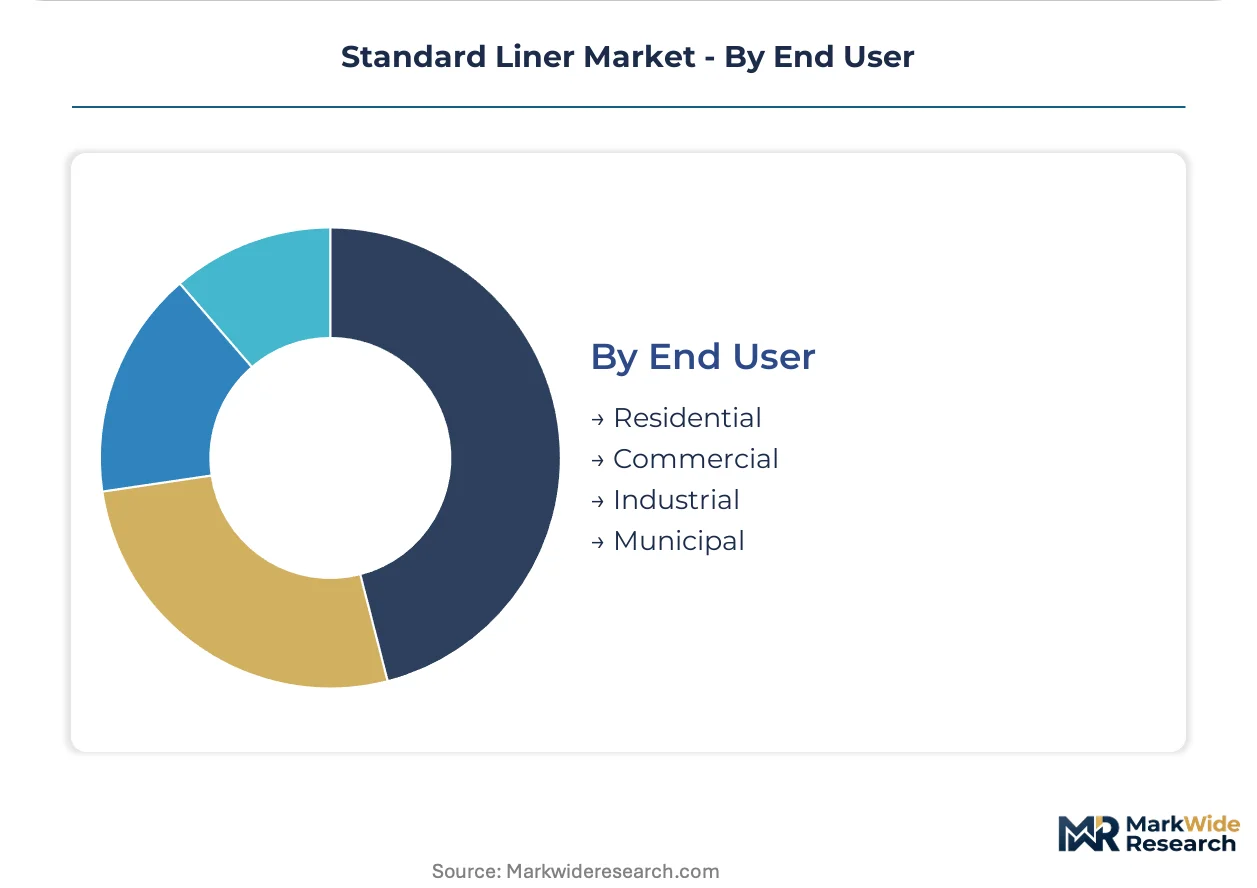
End User:
Contracting authority and compliance burden separate margin tiers, with municipal procurement demanding full certification documentation and residential transactions completing on specification sheets alone.
- Municipal:City and county wastewater authorities specify certified geomembranes under GRI GM17 standards with third-party verification. China's industrial corridor cities are consolidating liner selection into pre-qualification frameworks that elevate certified suppliers.
- Industrial:Manufacturing and energy sector containment buyers demand reinforced liner grades for chemical processing and tank farm applications. Texas petrochemical operators are extending polymer portfolios into specialized formulations for demanding environments.
- Commercial:Pool service companies and landscape contractors purchase on availability and installation support rather than material testing documentation.
- Residential:Individual consumers select from retail-available EPDM and PVC alternatives with minimal technical specification involvement.
Municipal holds installed capacity. Industrial is rotating up the share rankings as PFAS-free formulations become decisive bid qualification criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports geomembrane-grade HDPE resin to liner fabricators in Germany and the United States, establishing the dominant trade-flow corridor for raw material supply. Manufacturing capacity concentrates in Shandong Province and the Yangtze River Delta for domestic consumption and re-export to Southeast Asian containment projects. Municipal procurement in industrial corridor cities drives regional demand differentiation.
United States
EPA Subtitle D mandates force landfill liner upgrades across municipal waste facilities. State environmental agencies in California and Texas impose groundwater protection rules beyond federal minimums. The Permian Basin petrochemical cluster demands reinforced liner grades for tank farm containment and produced water management.
China
Industrial corridor cities around Shanghai and Tianjin accelerate wastewater containment procurement cycles. The Ministry of Ecology and Environment enforces GB standards for hazardous waste landfill construction that mirror ASTM performance thresholds. Shandong Province hosts the densest concentration of calendering and extrusion capacity serving domestic and export markets.
Germany
REACH restrictions on persistent organic pollutants force PVC plasticizer reformulation across liner production. The country's national environmental regulator requires full material disclosure documentation for industrial containment tenders. The Rhine-Ruhr industrial region specifies certified geomembranes for chemical processing and legacy site remediation.
India
Municipal wastewater infrastructure expansion drives liner procurement in Maharashtra and Gujarat industrial zones. The Central Pollution Control Board implements landfill liner standards under Hazardous Waste Management Rules that elevate HDPE specification requirements. The Delhi-Mumbai Industrial Corridor concentrates demand for containment solutions in pharmaceutical and textile processing clusters.
Brazil
Mining tailings dam regulations tighten geomembrane performance requirements following recent catastrophic failures. The national mining regulator mandates independent certification for containment structures above specified volume thresholds. The Minas Gerais iron ore belt generates concentrated demand for high-thickness HDPE installations.
Standard Liner Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and certification depth. The vendor base splits between integrated polymer producers with captive resin supply and independent fabricators sourcing feedstock on spot markets. Three archetypes dominate: multinational packaging conglomerates with geomembrane divisions, regional specialists focused on containment applications, and commodity converters serving price-sensitive residential segments. Capacity expansion and certification acquisition represent the dominant competitive moves as municipal buyers consolidate pre-qualified supplier lists.
Among North American integrated manufacturers, Greif exemplifies the multinational packaging archetype with municipal utility reach. Thrace Group represents European regional specialization in geomembrane production. Berry Global occupies a position bridging material science breadth with industrial containment applications. These three anchors illustrate how certification depth and manufacturing footprint separate margin tiers in public infrastructure procurement.
| Leading Market Players |
|---|
| Greif |
| Thrace Group |
| SIA Flexitanks |
| Nissei |
| Amcor |
| Berry Global |
| United Bags |
| Display Pack |
| CDF Corp |
| Others |
Value Network & Pricing Analysis
ASTM D7176 and GRI GM17 certification regimes gate both supplier qualification and price differentiation simultaneously, compressing uncertified competitors into commodity tiers while elevating third-party-verified manufacturers into premium contracting positions. Municipal buyers in the United States and industrial corridor cities in China now require documentation upstream of award, fragmenting the vendor base into certified and non-certified pricing strata.
Pricing Analysis
Monolithic HDPE geomembranes command substantial premiums over co-extruded multilayer alternatives and legacy PVC formulations, with price differentiation driven by certification depth under GRI GM17 and thickness grade compliance for hazardous containment. Three-tier pricing structure across premium certified, standard industrial, and economy residential levels stratifies the market, with cost compression in economy tiers intensifying due to HDPE resin volatility. Municipal wastewater authorities exhibit lowest price sensitivity, while residential fish pond purchasers drive volume at minimal margin.
Supply Chain Analysis
China anchors global geomembrane-grade HDPE resin production, with Shandong Province and the Yangtze River Delta hosting dense calendering and extrusion capacity for domestic consumption and re-export. Manufacturing draws from polyethylene feedstock, plasticizer packages, and reinforcement textiles, with single-source vulnerability concentrated in resin supply from state-controlled petrochemical complexes. Distribution runs through engineering-procurement-construction contractors for municipal projects and wholesale distributors for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PFAS-free formulation mandates across multiple state environmental agencies are disrupting material qualification protocols, creating acceleration windows for suppliers with advanced polymer science capabilities. This regulatory inflection compresses legacy product cycles while opening premium positioning for compliant innovators.
For Market Incumbents: Consolidate certification depth under GRI GM17 and ASTM D7176 to defend municipal pre-qualification status against emerging Asian competitors. Expand backward integration into HDPE resin supply to buffer margin compression from feedstock volatility. Prioritize PFAS-free R&D investment ahead of anticipated federal harmonization of state-level restrictions.
For New Entrants and Emerging Players: Anchor in decorative water feature applications where co-extruded multilayer technologies displace incumbent PVC formulations with comparable weldability and superior UV stability. Target Chinese industrial corridor cities around Tianjin where municipal landscape projects run parallel to wastewater containment procurement. Pursue engineering-direct sales models that bypass general contractor markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional geomembrane specialists lacking certification depth for municipal infrastructure scaling. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor PFAS restriction harmonization timelines as the decisive inflection for portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Development | EPA and state-level mandates in California and Florida are disqualifying legacy chemistries from public infrastructure tenders. |
| Third-Party Certification Acquisition | GRI GM17 verification creates pricing power against uncertified imports in municipal procurement frameworks. |
| Backward Integration into HDPE Resin | Captive feedstock supply buffers margin compression from polyethylene price volatility in extrusion operations. |
| Co-Extruded Multilayer Capacity Expansion | Municipal wastewater operators in the United States specify these structures for anaerobic digester covers and lagoon caps. |
| Engineering-Direct Channel Development | Specification authority migration from general contractors to owner's engineers demands pre-qualification relationship investment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal wastewater authority procurement managers, geomembrane fabrication plant managers, engineering consultant specification leads, and industrial containment project developers. Secondary validation drew from EPA Subtitle D regulatory filings, ASTM International standards documentation, state environmental agency rulemaking records, and customs trade data for HDPE resin flows. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the analysis window, volume and value outputs reflect modeled projections across material type, application environment, thickness grade, and end-user contracting authority. CAGRs were derived from segment-level growth rate synthesis applied to base-year estimates. Forecast inputs incorporated municipal infrastructure replacement cycle timing, industrial corridor expansion patterns in China, and regulatory adoption trajectories for PFAS restrictions.
Decision-makers should treat outputs as directional under base assumptions of continued EPA enforcement and resin supply stability; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in regulatory harmonization timelines and feedstock cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Reel in Box Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Coconut Wraps Market