
 Environmental Monitoring (Surface Water) Market | 2026-2036
Environmental Monitoring (Surface Water) Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Monitoring (Surface Water) Market Insights
Field hydrologist talent scarcity is rotating procurement priorities toward plug-and-play sensor platforms that reduce deployment complexity. Xylem leverages its vertical integration across sensing hardware and telemetry software to capture recurring service contracts. Danaher sustains R&D intensity in portable analyzers that target utility field crews with limited laboratory access. Thermo Fisher Scientific anchors its position through channel control in North American environmental consulting verticals.
Environmental monitoring of surface water encompasses the systematic measurement of physical, chemical, and biological parameters in rivers, lakes, and wetlands using instruments capable of detecting dissolved oxygen levels to 0.1 mg/L precision and turbidity to 0.1 NTU resolution, serving the primary purpose of protecting aquatic ecosystems and ensuring compliance with discharge permits. Water quality sensors dominate installed base value due to their role as the front-end data capture layer, while IoT solutions represent the fastest-expanding technology segment as utilities replace manual sampling with continuous telemetry. Government agencies occupy the largest end-user share given their statutory responsibility for watershed oversight and public health protection.
The EPA enforces National Pollutant Discharge Elimination System monitoring requirements that mandate specific parameter reporting frequencies, while the EU Water Framework Directive imposes ecological status classifications that drive sensor density in member states. ISO 5667 sampling standards and WMO hydrological monitoring protocols shape product certification requirements and cross-border equipment procurement specifications. Stakeholders must track how emerging contaminant lists expand required detection parameters beyond conventional nutrient and heavy metal suites.
Market Dynamics
The transition from manual sampling to continuous telemetry networks is compressing replacement cycles and forcing vendors to bundle hardware with recurring data services rather than standalone sensor sales.
Growth Catalysts
- EPA Clean Water Act enforcement:Revised discharge monitoring protocols are mandating higher sensor density at municipal outfalls, accelerating capital deployment timelines for utility procurement teams.
- Rhine Basin restoration mandates:Germany's ecological status targets under the EU Water Framework Directive require dissolved oxygen and nutrient load tracking across the entire watershed, creating sustained equipment demand.
- IoT telemetry integration:Utilities are replacing quarterly manual sampling with real-time data streams to catch episodic pollution events that intermittent monitoring misses.
Market Restraints
- Optical sensor component concentration:Precision photodiodes and interference filters rely on a narrow supplier base concentrated in East Asian manufacturing clusters, exposing lead time volatility.
- Field hydrologist scarcity:Specialized technicians capable of calibrating multi-parameter sondes in remote deployments are becoming harder to recruit, slowing installation velocity.
- Legacy analog infrastructure:Older dam and reservoir monitoring stations use proprietary communication protocols that resist integration with modern IP-based telemetry networks.
Strategic Opportunities
- Per- and polyfluoroalkyl substances detection:Emerging contaminant lists are expanding required parameter suites beyond conventional nutrient tracking, opening sensor upgrade cycles.
- Outcome-based service contracting:Utilities are shifting from capital purchase to performance-guaranteed monitoring subscriptions that bundle maintenance and data validation.
- Wetland carbon credit verification:Restoration projects in the Mississippi-Atchafalaya basin require continuous hydrological monitoring to qualify for offset certification, creating new application demand.
Industry Challenges
- Multi-vendor data interoperability:Utilities operating mixed fleets of YSI, Hach, and Campbell Scientific equipment struggle to normalize outputs into unified watershed dashboards without expensive middleware.
- ISO 5667 certification timelines:Third-party validation of automated samplers against manual reference methods extends product launch schedules by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Monitoring (Surface Water) Market |
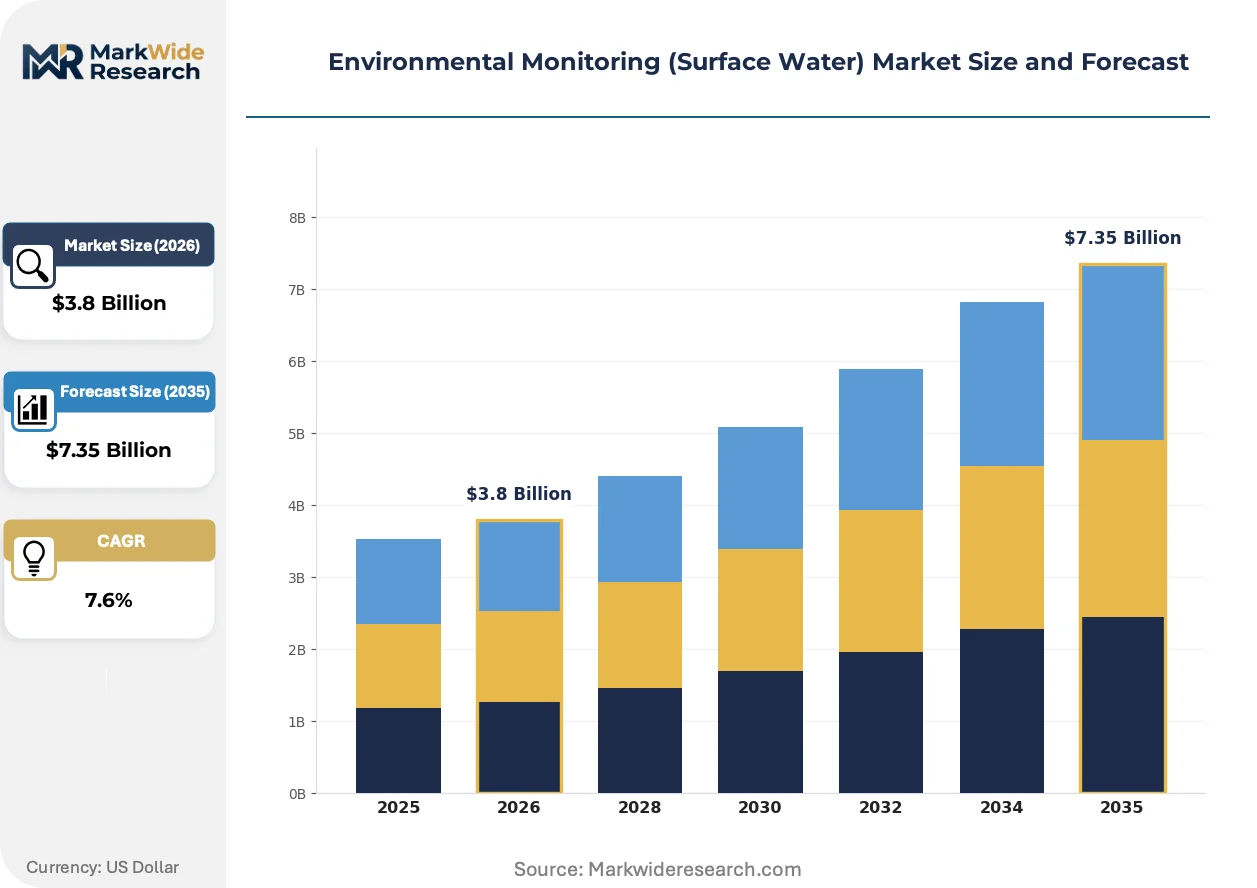
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Quality Sensors, Data Loggers, Turbidity Meters, pH Meters Technology: Remote Sensing, In-Situ Monitoring, Satellite Imagery, IoT Solutions Application: Pollution Detection, Resource Management, Flow Measurement, Recreational Monitoring End User: Government Agencies, Environmental Consultants, Research Institutions, NGOs |
| Companies Covered | Xylem, Danaher, Thermo Fisher Scientific, Endress+Hauser, Hach Company, Horiba, Shimadzu, Agilent Technologies, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Monitoring (Surface Water) Market Trends and Innovations
Sensor miniaturization and edge computing are collapsing the distinction between laboratory-grade precision and field-deployable durability, enabling new deployment geometries that were previously technically infeasible.
Membrane-based dissolved oxygen sensing is fragmenting the installed base of traditional galvanic cell technologies. Municipal utilities in the Ohio River Valley are adopting optical luminescence probes for their zero-consumable maintenance profiles and stability across temperature swings. The technology is fragmenting competitive positioning by decoupling sensor accuracy from frequent calibration labor, compressing the total cost of ownership advantage that incumbent electrochemical suppliers previously held.
The EU Water Framework Directive's ecological status classification system is tightening nutrient load thresholds for transitional and coastal waters. Member states must achieve good ecological status by defined cycle deadlines, forcing sensor density upgrades in the Danube and Elbe catchments. German environmental agencies are responding by procuring multi-parameter sondes with integrated phosphate and nitrate photometers rather than relying on laboratory turnaround.
Consolidated watershed management districts are centralizing procurement authority away from individual municipal utilities. The Susquehanna River Basin Commission now negotiates enterprise telemetry contracts on behalf of member jurisdictions, displacing fragmented spot-buying patterns. Pennsylvania and New York municipalities are surrendering vendor selection autonomy in exchange for volume pricing and standardized data formats that enable interstate water quality trading.
Environmental Monitoring (Surface Water) Market Segmentation
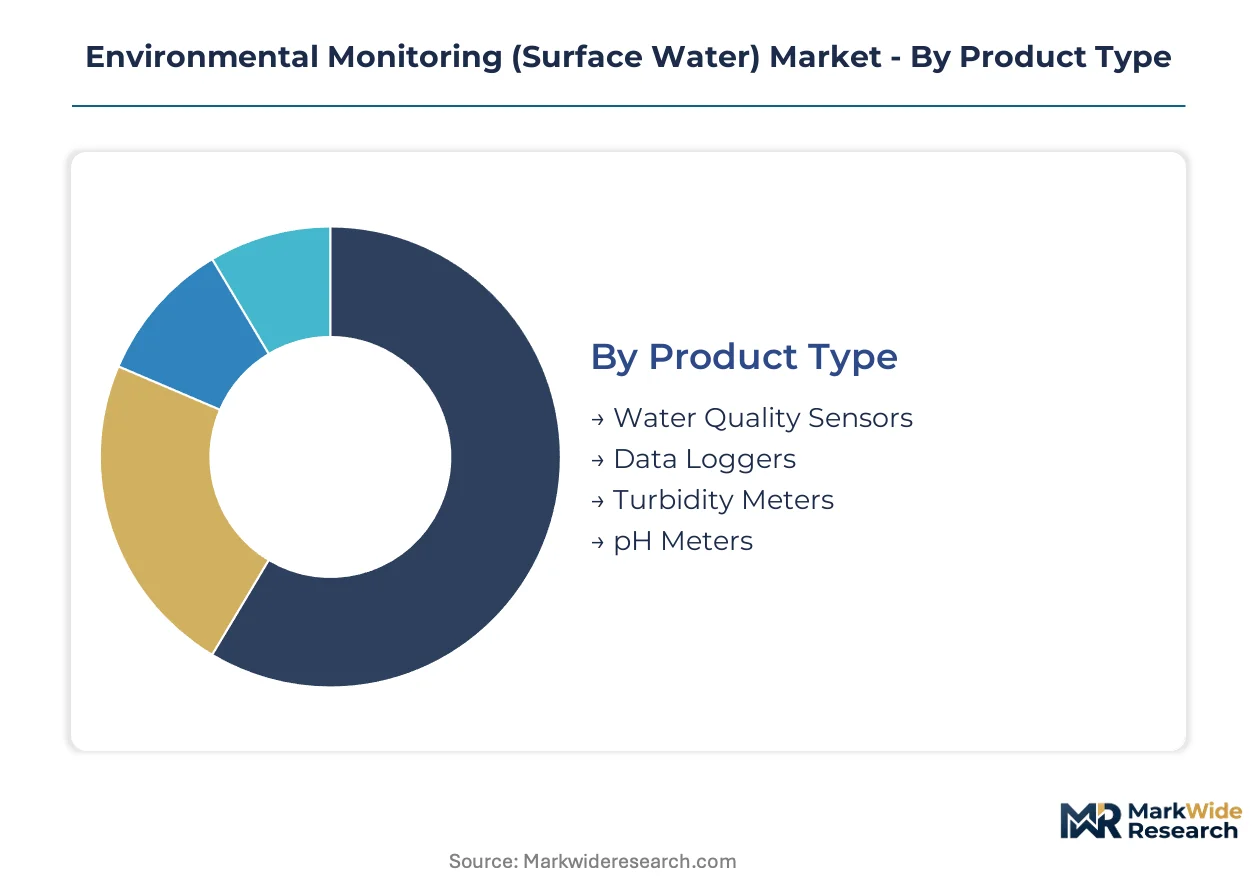
Segmentation in surface water monitoring reveals how procurement authority concentrates across hardware types, telemetry architectures, and institutional buyers. Understanding these divisions exposes where pricing power accumulates and which technology transitions are compressing replacement cycles.
Product Type:
Margin pools concentrate in multi-parameter sensing platforms that bundle dissolved oxygen, turbidity, and nutrient detection into single deployable units, reducing field calibration labor and service contract overhead.
- Water Quality Sensors:Multi-parameter sondes integrate optical dissolved oxygen, conductivity, and nutrient photometry into sealed titanium housings rated for continuous submersion. German Rhine Basin restoration programs are standardizing on these platforms to meet EU Water Framework Directive ecological status deadlines, displacing discrete single-parameter probes.
- Data Loggers:Ruggedized field computers with IP67 enclosures capture sensor outputs at programmable intervals, storing encrypted datasets for batch transmission or edge analytics. Municipal utilities across the Ohio River Valley are adopting Campbell Scientific and NexSens units to retrofit legacy dam monitoring stations with cellular telemetry.
- Turbidity Meters:Optical nephelometers detect suspended solids interference in drinking water intakes and discharge outfalls.
- pH Meters:Combination electrode systems with automatic temperature compensation anchor laboratory validation protocols.
Water Quality Sensors hold installed capacity. Data Loggers are rotating up the share rankings.
Technology:
Application context determines technology selection — episodic event detection demands continuous telemetry while watershed-scale surveillance favors aerial coverage.
- Remote Sensing:Aerial and satellite-mounted multispectral imagers detect chlorophyll-a blooms, sediment plumes, and thermal discharge signatures across thousands of square kilometers. The Susquehanna River Basin Commission deploys Landsat and Sentinel-2 derived products to monitor agricultural runoff across Pennsylvania and New York jurisdictions without maintaining dense ground sensor networks.
- In-Situ Monitoring:Submersible probe arrays anchored at fixed stations deliver laboratory-grade precision for regulatory compliance point sources. EPA National Pollutant Discharge Elimination System enforcement is mandating higher sensor density at municipal outfalls, accelerating capital deployment for permanent installations over portable alternatives.
- Satellite Imagery:Commercial constellations provide revisit frequencies adequate for seasonal algae tracking.
- IoT Solutions:Low-power wide-area networks enable battery-operated deployments in remote catchments lacking grid power.
In-Situ Monitoring dominates compliance-driven procurement. IoT Solutions are climbing the fastest as utilities replace quarterly manual sampling with continuous telemetry.
Application:
Regulatory mandate intensity varies sharply across use cases, with discharge permits commanding capital priority over voluntary stewardship programs.
- Pollution Detection:Continuous monitoring for heavy metals, nutrients, and emerging contaminants at industrial outfalls and combined sewer overflows. EPA Clean Water Act enforcement protocols are mandating real-time reporting for permit exceedances, compressing procurement timelines for sensor networks.
- Resource Management:Allocation modeling for irrigation withdrawals, hydropower operations, and drinking water reservoir optimization. The Colorado River Basin states rely on USGS gauging stations and Bureau of Reclamation telemetry to administer compact obligations across Arizona, California, and Nevada.
- Flow Measurement:Acoustic Doppler velocimetry and pressure transducer stage recording for flood forecasting.
- Recreational Monitoring:Beach advisory systems for fecal indicator bacteria and harmful algal blooms.
Pollution Detection captures regulatory compliance budgets. Resource Management is gaining share fastest as water scarcity intensifies allocation conflicts.
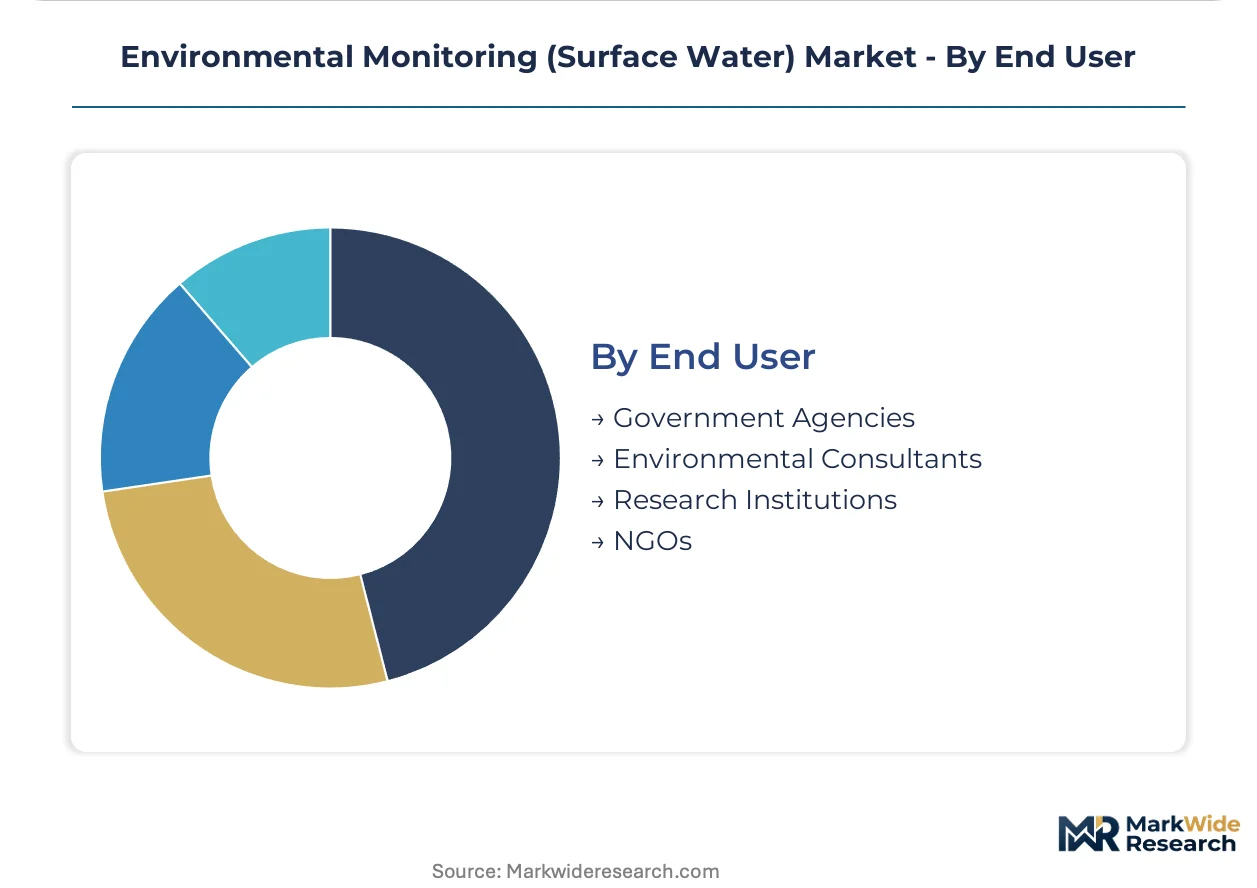
End User:
Procurement sophistication diverges between statutory monitoring obligations and project-based consulting engagements.
- Government Agencies:Federal, state, and watershed district authorities with delegated Clean Water Act and Safe Drinking Water Act enforcement responsibilities. The US Environmental Protection Agency and state environmental departments anchor demand through multi-year capital programs and grants to municipal utilities.
- Environmental Consultants:Engineering firms conducting baseline studies, impact assessments, and remediation verification for private and public clients. AECOM, Jacobs, and Wood Environment & Infrastructure Solutions maintain fleets of portable analyzers for field crews with limited laboratory access.
- Research Institutions:Universities and federal laboratories advancing sensor calibration protocols and contaminant detection methods.
- NGOs:Watershed associations and conservation groups conducting volunteer monitoring and advocacy campaigns.
Government Agencies hold installed capacity. Environmental Consultants are rotating up the share rankings as outcome-based service contracting displaces direct capital purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates procurement in continuous dissolved oxygen and nutrient tracking for Rhine Basin restoration, while the United States distributes demand across municipal compliance, agricultural runoff surveillance, and carbon credit verification in wetland restoration projects.
United States
EPA Clean Water Act enforcement drives sensor density at municipal outfalls and combined sewer overflow points. The National Pollutant Discharge Elimination System mandates real-time reporting for permit exceedances, compressing procurement timelines. The Susquehanna River Basin Commission centralizes enterprise telemetry contracts for Pennsylvania and New York municipalities, standardizing data formats for interstate water quality trading.
Germany
Rhine Basin ecological restoration programs require continuous nutrient load tracking across the entire watershed. The EU Water Framework Directive imposes strict ecological status classifications with defined cycle deadlines for achieving good status. Environmental agencies in the Rhine-Ruhr and Rhine-Main regions procure multi-parameter sondes with integrated phosphate and nitrate photometers, displacing laboratory-dependent sampling.
China
Yangtze River Basin water quality monitoring expansion targets industrial discharge points and drinking water source protection zones. The Ministry of Ecology and Environment enforces surface water quality standards that mandate automated monitoring at key control sections. Municipal utilities in the Yangtze River Delta deploy IoT-enabled sensor networks to replace manual sampling for episodic pollution event detection.
Canada
Great Lakes water quality agreements drive binational monitoring coordination with the United States for phosphorus load reduction targets. Environment and Climate Change Canada administers federal funding for municipal wastewater monitoring infrastructure upgrades. Ontario municipalities around Lake Erie and Lake Ontario deploy continuous nutrient monitoring to track algal bloom triggers and meet binational nutrient management strategy commitments.
Australia
Murray-Darling Basin water resource planning mandates extensive flow and quality monitoring for irrigation allocation and environmental water delivery. The Bureau of Meteorology and state water agencies operate integrated telemetry networks across the basin. New South Wales and Victoria water utilities deploy multi-parameter sensors at major extraction points to enforce sustainable diversion limits under the Murray-Darling Basin Plan.
Environmental Monitoring (Surface Water) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding recurring service contracts through bundled hardware-telemetry offerings. The specialist tier competes on parameter-specific detection capabilities and portable form factors for field crews with limited laboratory access. Two strategic archetypes dominate: vertically integrated platform providers spanning sensing hardware through data analytics software, and focused instrument manufacturers concentrating on laboratory-grade precision for regulatory compliance applications. Competitive moves center on outcome-based service contracting that shifts utility procurement from capital purchase to performance-guaranteed subscriptions, and portfolio diversification into emerging contaminant detection capabilities for per- and polyfluoroalkyl substances monitoring.
Among the integrated platform providers, Xylem and Danaher occupy positions that exemplify the bundled hardware-service model, while Thermo Fisher Scientific anchors the analytical instrumentation tier through channel control in environmental consulting verticals. These three companies represent the concentration of procurement authority in municipal utility and government agency segments, where vendor selection increasingly favors enterprise-scale telemetry contracts over fragmented spot-buying patterns.
| Leading Market Players |
|---|
| Xylem |
| Danaher |
| Thermo Fisher Scientific |
| Endress+Hauser |
| Hach Company |
| Horiba |
| Shimadzu |
| Agilent Technologies |
| Emerson Electric |
| Others |
Pricing and Supply Chain Analysis
Outcome-based service contracts lock in multi-year telemetry subscriptions that guarantee German municipalities predictable per-station costs while securing vendors against component lead time volatility. These arrangements bundle hardware depreciation, cellular data transmission, and calibration labor into fixed annual fees that compress buyer procurement cycles.
Pricing Analysis
Long-term offtake agreements dominate municipal utility procurement, with Rhine Basin restoration programs and Susquehanna River Basin Commission contracts spanning five-to-seven year horizons. Price differentiation rests on certification tier—ISO 5667-validated sondes command substantial premiums over uncertified alternatives—and after-sales service bundling that includes field hydrologist dispatch. Cost compression in mid-tier data loggers is intensifying because Campbell Scientific and NexSens compete for retrofit contracts at legacy dam stations. Environmental consultants show highest price sensitivity due to project-based budgeting, while government agencies prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Strategic stockpiling of precision photodiodes and interference filters is displacing just-in-time procurement as East Asian supplier concentration exposes lead time risk. Component manufacturing concentrates in China, Japan, and South Korea, with optical sensor elements drawing from specialized foundries in Taiwan and South Korea. Single-source vulnerability in luminescent dye supply for dissolved oxygen probes threatens membrane-based sensor production lines. Distribution runs through authorized regional distributors who maintain calibration equipment inventory and field technician certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across mixed vendor fleets creates niche opportunities for middleware providers and calibration specialists as utilities struggle to normalize YSI, Hach, and Campbell Scientific outputs into unified dashboards.
For Market Incumbents: Compound recurring revenue streams by deepening outcome-based service contracts that bundle maintenance with data validation guarantees. Invest in backward integration into optical component supply to reduce exposure to East Asian photodiode lead times. Prioritize ISO 5667 certification investment to defend against emerging portable analyzer competitors targeting consultant field crews. For New Entrants and Emerging Players: Anchor in wetland carbon credit verification services for Mississippi-Atchafalaya basin restoration projects, where continuous hydrological monitoring demand outpaces established vendor coverage. Target environmental consulting verticals with portable multi-parameter sondes optimized for laboratory-grade precision without fixed infrastructure dependency. Pursue direct sales to watershed management districts centralizing procurement authority away from individual municipalities. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors sensor-as-a-service platforms over hardware-centric incumbents. Five-to-ten year viability hinges on per- and polyfluoroalkyl substances detection capability integration. Acquisition targets should demonstrate integrated telemetry software stacks rather than standalone probe manufacturing. Watch for EPA emerging contaminant list expansions as the inflection signal triggering upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contracting | Shifts German utility procurement from capital purchase to performance-guaranteed monitoring subscriptions bundling maintenance and validation. |
| PFAS Detection Capability Investment | Positions vendors for EPA emerging contaminant list expansions that mandate sensor upgrades beyond conventional nutrient tracking. |
| Backward Integration into Optical Components | Reduces lead time exposure from East Asian photodiode and interference filter supplier concentration. |
| Watershed District Enterprise Contracting | Captures volume pricing and standardized data formats through Susquehanna River Basin Commission-style centralized procurement. |
| Edge Computing Sensor Miniaturization | Enables new deployment geometries that collapse distinctions between laboratory-grade precision and field-deployable durability. |
Research Methodology
A spread of perspectives from municipal utility procurement officers, field hydrologist technicians, environmental consulting project managers, and EPA regional enforcement coordinators converged on the working assumptions underlying installed base estimates. Primary interviews with watershed district planning staff and multi-parameter sonde calibration specialists were cross-referenced against secondary validation from EPA NPDES permit databases, EU Water Framework Directive implementation reports, USGS gauging station records, and customs trade data on optical sensor component flows. Bottom-up equipment shipment tallies were reconciled with top-down government capital expenditure disclosures across the analysis window.
Segmentation dimensions modeled include product type hierarchy, telemetry architecture, application regulatory intensity, and end-user procurement sophistication across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical capital deployment cycles and enforcement protocol revision timelines. Forecast inputs incorporated Rhine Basin ecological status deadline schedules, Ohio River Valley optical probe adoption trajectories, and wetland carbon credit verification methodology standardization progress.
Decision-makers should treat outputs as directional under sustained EPA enforcement intensity and EU Water Framework Directive ecological status commitment assumptions; material deviation would warrant model refresh. Revision becomes warranted when optical component supply chain disruption or field hydrologist labor scarcity crosses thresholds that compress installation velocity beyond historical norms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market