
 Environmental Consulting Services Market | 2026-2036
Environmental Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Consulting Services Market Analysis
The gap between premium advisory and commodity compliance work is broadening as clients separate strategic sustainability planning from routine permitting. AECOM leverages its integrated engineering platform to capture large-scale remediation contracts across multiple continents. Jacobs Engineering Group anchors its position through deep relationships with energy sector operators facing decarbonization mandates. Tetra Tech differentiates by specializing in water resource management and climate resilience advisory.
Environmental consulting services encompass professional advisory work that applies environmental science, engineering principles, and regulatory knowledge to assess, manage, and mitigate ecological impacts across industrial, commercial, and public projects. These services typically involve site characterization, contaminant fate and transport modeling, environmental impact assessments, and remediation design governed by technical parameters such as cleanup target levels, risk-based screening concentrations, and institutional control requirements. Compliance services retain the largest revenue share due to perpetual regulatory obligations, while sustainability advisory is expanding fastest as corporations adopt science-based targets and nature-positive frameworks. Remediation commands premium pricing where liability transfer and complex hydrogeology intersect, particularly in the energy and manufacturing sectors.
EPA enforcement actions under CERCLA and RCRA directly shape demand for site investigation and remedial design services in the United States. EMA frameworks and the EU Green Deal's taxonomy requirements are accelerating corporate sustainability reporting obligations across Europe, expanding the addressable market for climate and biodiversity consultants. Stakeholders must monitor how emerging regulations around carbon border adjustments and nature-related financial disclosures reshape service line profitability and talent requirements.
Market Dynamics
EPA enforcement tightening around PFAS contamination is redirecting capital toward specialized remediation capabilities, compressing timelines for site investigation and accelerating liability-driven consulting procurement across industrial portfolios.
Growth Catalysts
- PFAS regulatory enforcement:EPA actions under CERCLA and emerging state-level maximum contaminant levels are forcing manufacturing and defense facilities into accelerated site characterization programs.
- Industrial decarbonization mandates:Energy sector operators facing science-based target commitments are commissioning integrated carbon accounting and abatement strategy services.
- Brownfield redevelopment stimulus:United States infrastructure appropriations are sustaining multi-year project pipelines for environmental due diligence and risk-based remediation design.
Market Restraints
- Specialized labor scarcity:Hydrogeologists and risk assessors with PFAS-specific expertise command premium compensation, elevating project delivery costs.
- Equipment supply concentration:Advanced mass spectrometry instrumentation for ultra-trace contaminant detection depends on limited German and Japanese original equipment manufacturers.
- Regulatory fragmentation:Inconsistent state-level cleanup standards for emerging contaminants create compliance planning complexity and litigation exposure.
Strategic Opportunities
- EU Green Deal taxonomy alignment:Corporate sustainability reporting obligations under CSRD are expanding addressable demand for climate and biodiversity advisory services across European industrial portfolios.
- Digital twin integration:Convergence of subsurface modeling software with real-time sensor networks is enabling predictive contamination management for proactive industrial clients.
- Latin America mining sector:Underpenetrated environmental impact assessment and closure planning markets in Chile and Peru offer expansion vectors for firms with Spanish-language capabilities.
Industry Challenges
- Cross-disciplinary talent synthesis:Projects now require simultaneous expertise in data science, toxicology, and community engagement, stretching traditional hiring profiles.
- Legacy data harmonization:Decades-old site investigation records in non-digital formats impede machine learning applications for predictive risk modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Consulting Services Market |
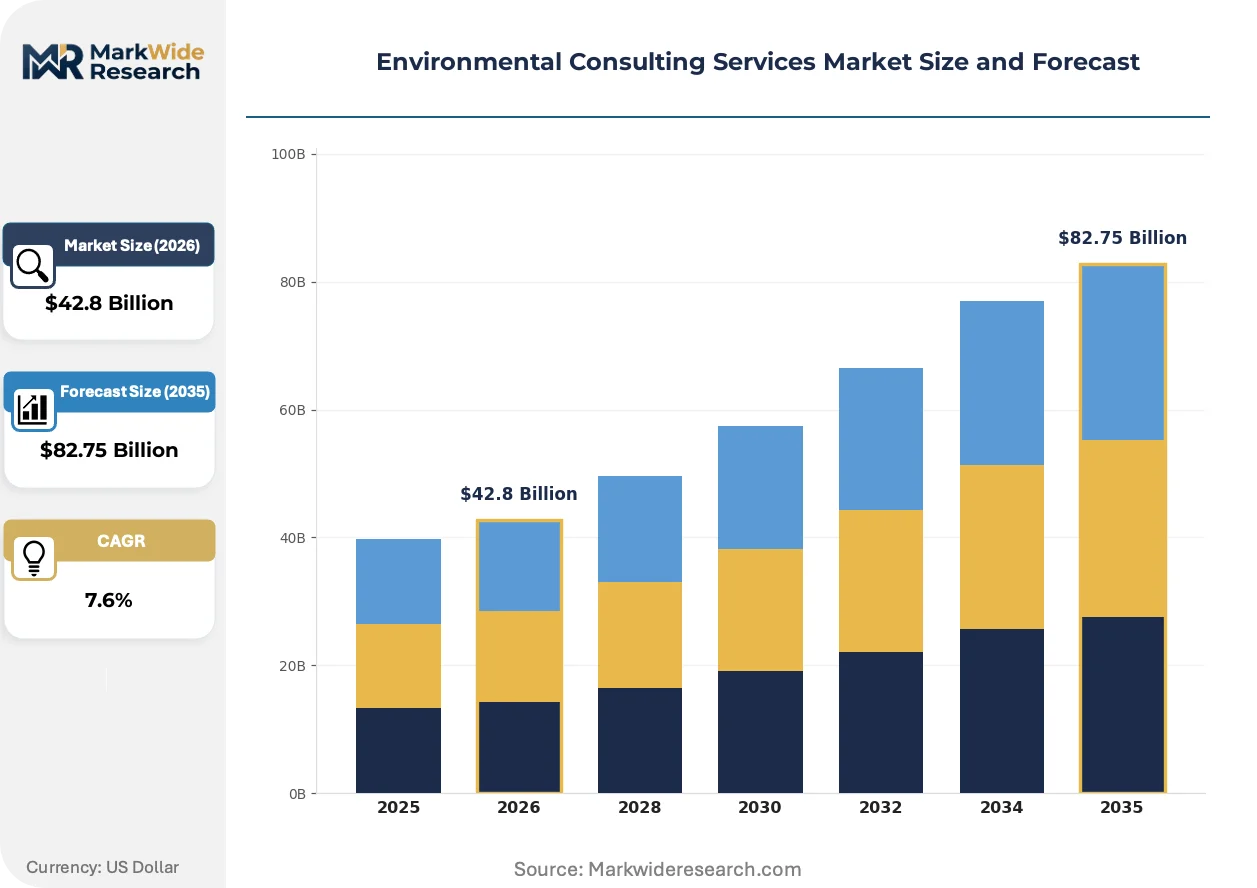
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Compliance, Remediation, Risk Assessment, Sustainability End User: Government Agencies, Industrial Sector, Real Estate, Non-Profits Project Scale: Small Scale, Medium Scale, Large Scale, Multi-Phase Sector: Construction, Energy, Manufacturing, Transportation |
| Companies Covered | AECOM, Jacobs Engineering Group, Tetra Tech, Arcadis, WSP Global, Stantec, ERM (Environmental Resources Management), Ramboll, ICF International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Consulting Services Market Emerging Trajectories
Digital instrumentation and predictive analytics are compressing traditional site investigation timelines while regulatory complexity is elevating the strategic value of integrated advisory platforms over discrete compliance services.
High-resolution mass spectrometry paired with non-targeted analysis algorithms is electrifying contaminant identification workflows for emerging chemical classes. Industrial facilities with legacy solvent and fluorochemical operations are adopting these platforms to preempt regulatory enforcement. The technology is electrifying competitive differentiation among laboratories capable of detecting unknown transformation products ahead of mandated analyte lists.
EU Green Deal taxonomy requirements and CSRD disclosure mandates are accelerating corporate demand for verified nature-positive transition planning. European industrial conglomerates and financial institutions must now quantify biodiversity impacts alongside carbon emissions. Energy and materials sector buyers are responding by embedding environmental consultants into capital allocation committees rather than treating advisory as transactional procurement.
Subscription-based environmental data platforms are displacing project-specific deliverables for portfolio-scale industrial clients. Major manufacturing and real estate investment trusts now demand continuous monitoring dashboards and automated regulatory alert systems. This model shift is most visible in United States markets where institutional investors face escalating climate litigation exposure and require defensible documentation of environmental liability management.
Environmental Consulting Services Market Segmentation
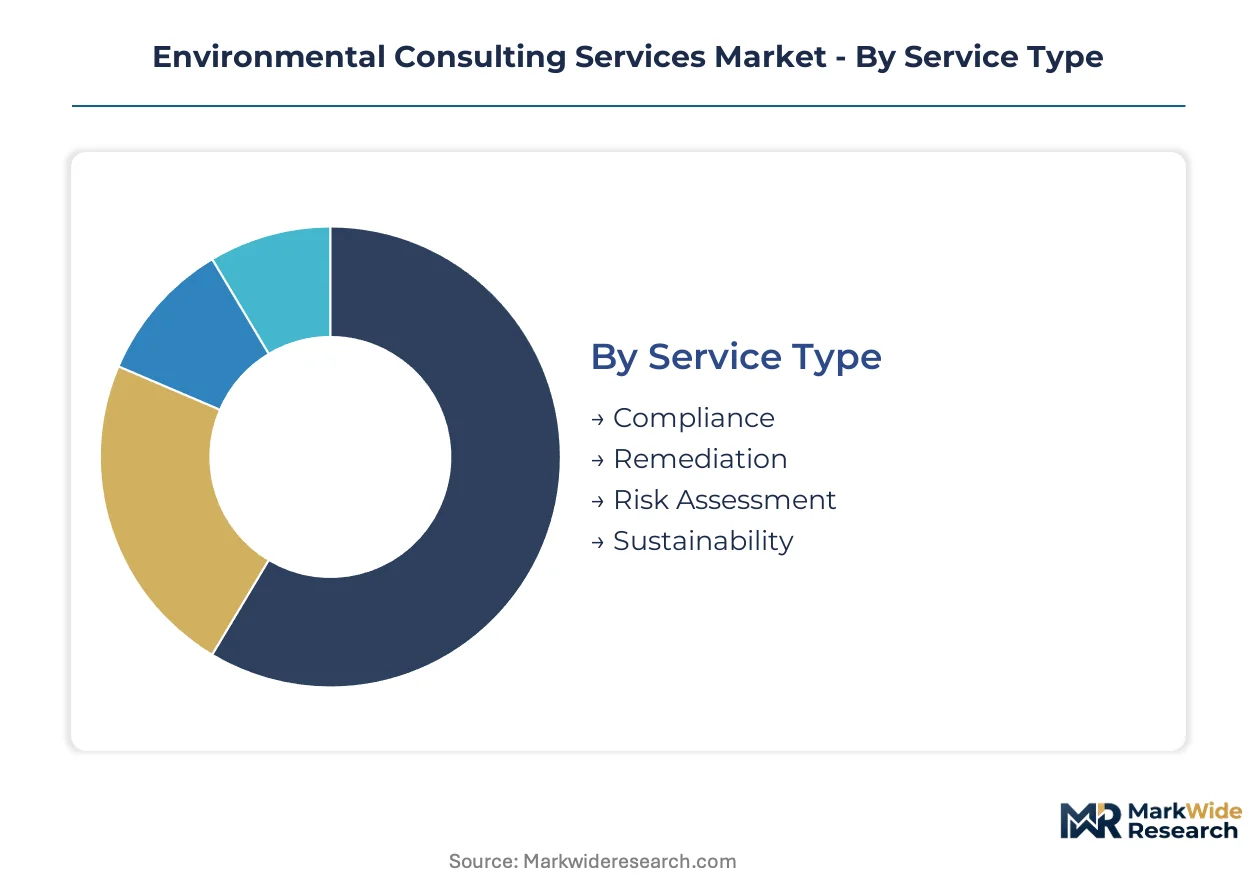
Environmental consulting services fragment across service delivery models, client sophistication, and project complexity. Segmentation reveals where commoditized compliance competes with premium advisory, and which verticals absorb specialized technical capabilities.
Service Type:
Standalone advisory engagements dominate high-margin revenue pools, while embedded compliance services anchor recurring relationships with institutional buyers.
- Compliance:Routine permitting, regulatory filing, and audit support services governed by EPA, ECHA, and state-level environmental agency mandates. Manufacturing facilities in the United States and chemical producers in Germany sustain perpetual demand cycles tied to permit renewal schedules and enforcement inspection calendars.
- Remediation:Site investigation, contaminant fate modeling, and engineered cleanup design for legacy industrial properties. Energy sector operators facing CERCLA liability and defense contractors addressing PFAS plumes commission these services under compressed timelines driven by EPA enforcement actions.
- Risk Assessment:Human health and ecological exposure evaluation using probabilistic modeling and toxicological reference values.
- Sustainability:Science-based target setting, nature-positive transition planning, and CSRD-aligned disclosure preparation.
Volume placements concentrate in Compliance; the faster expansion belongs to Sustainability.
End User:
Public procurement channels favor multi-year framework contracts, while private industrial buyers prioritize liability transfer and speed-to-closure.
- Government Agencies:Federal, state, and municipal environmental departments procuring site investigation, regulatory oversight, and brownfield redevelopment support. United States infrastructure stimulus programs and EU cohesion fund allocations sustain multi-phase project pipelines for site characterization and risk-based remediation design.
- Industrial Sector:Chemical manufacturers, petroleum refiners, and aerospace contractors managing legacy contamination and decarbonization mandates. PFAS enforcement under EPA CERCLA and emerging state maximum contaminant levels are forcing accelerated consulting procurement across defense and manufacturing portfolios.
- Real Estate:Investment trusts and developers conducting environmental due diligence for property transactions and redevelopment financing.
- Non-Profits:Conservation organizations and community groups seeking technical support for environmental impact litigation and habitat restoration planning.
Industrial Sector commands the deepest project backlogs; Non-Profits are climbing the fastest as climate litigation funding expands.
Project Scale:
Fee structures and staffing models diverge sharply between discrete assessments and multi-decade remediation programs.
- Large Scale:Multi-site portfolios and complex hydrogeological settings requiring integrated engineering, toxicology, and community engagement capabilities. United States Superfund sites and European mega-brownfield redevelopments absorb concentrated specialist labor and advanced analytical instrumentation.
- Multi-Phase:Longitudinal remediation programs spanning investigation, design, construction, and long-term monitoring. Energy sector liability management and institutional investor portfolio oversight drive subscription-style advisory relationships with continuous data delivery obligations.
- Medium Scale:Single-facility investigations and standard permit applications with defined deliverables and fixed timelines.
- Small Scale:Rapid due diligence assessments and discrete compliance filings for transactional real estate and small manufacturing operations.
Large Scale engagements absorb the premium talent pool; Multi-Phase contracts are gaining share fastest through subscription platform adoption.
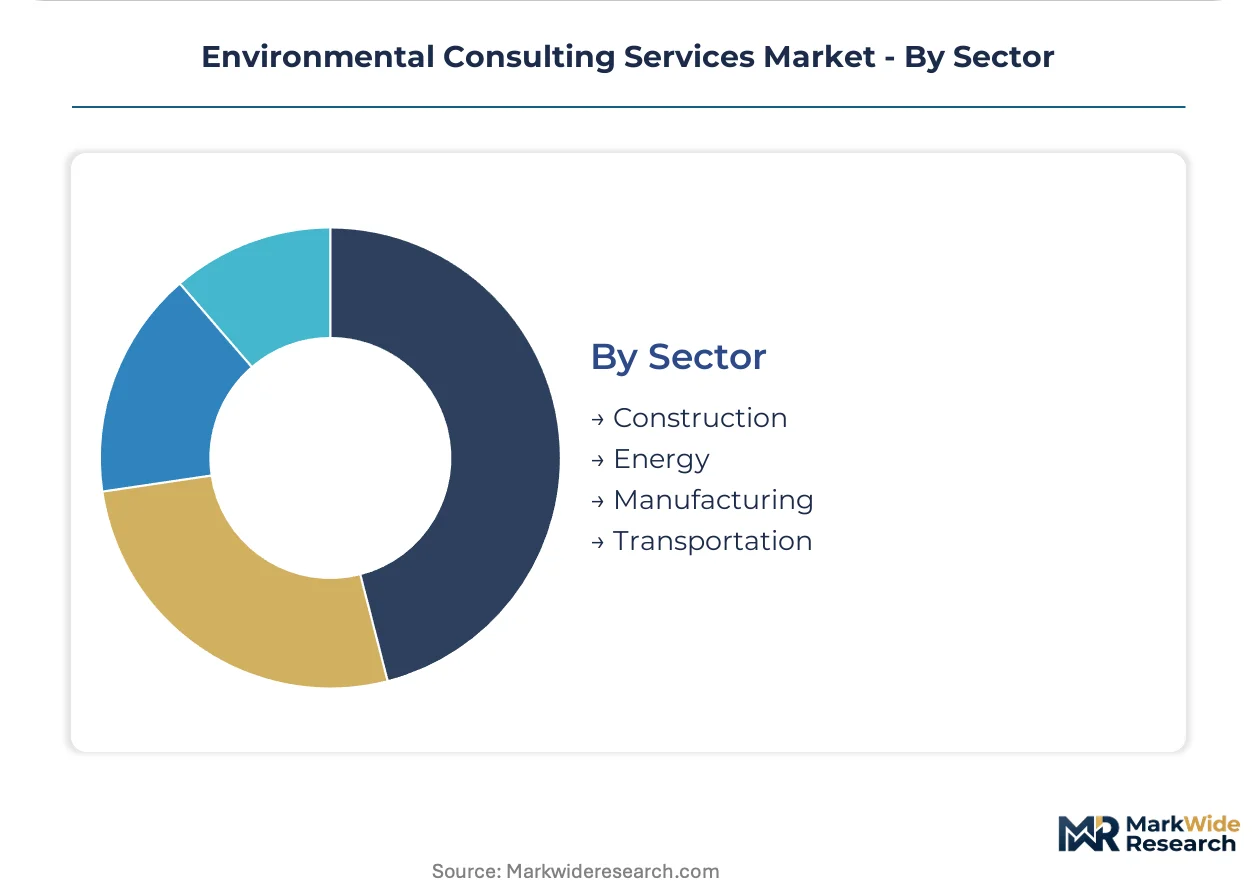
Sector:
Regulatory exposure and capital intensity determine where environmental consulting embeds into operational decision-making versus remaining transactional procurement.
- Energy:Oil and gas producers, utilities, and renewable developers managing decommissioning liabilities, carbon accounting, and methane abatement. North American operators facing science-based target commitments and European utilities navigating EU Green Deal taxonomy requirements commission integrated decarbonization strategy services.
- Manufacturing:Chemical, pharmaceutical, and electronics producers confronting PFAS contamination, solvent legacy issues, and supply chain emissions disclosure. EPA enforcement tightening and emerging carbon border adjustment mechanisms are elevating environmental advisory to C-suite reporting lines.
- Construction:Infrastructure developers and commercial builders requiring environmental impact assessments, wetlands permitting, and erosion control design.
- Transportation:Aviation, maritime, and logistics operators addressing fuel transition planning, port remediation, and emissions verification.
Energy maintains the most concentrated advisory spend; Manufacturing is expanding most quickly as enforcement intensity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the largest concentration of environmental consulting activity worldwide, hosting the headquarters of multiple integrated engineering firms serving energy sector decarbonization mandates. The United States absorbs the deepest project backlogs as EPA enforcement tightens around PFAS contamination and infrastructure stimulus sustains brownfield redevelopment pipelines.
United States
Defense contractors and petroleum refiners drive concentrated demand for site characterization and remedial design services. EPA actions under CERCLA and emerging state maximum contaminant levels for PFAS are compressing procurement timelines across industrial portfolios. The Houston-Gulf Coast corridor and California's Central Valley host the densest clusters of legacy contamination investigations.
Germany
Chemical manufacturers and automotive suppliers commission integrated carbon accounting and supply chain emissions verification services. ECHA REACH compliance obligations and the EU Green Deal taxonomy requirements are elevating sustainability advisory to board-level reporting lines. The Rhine-Ruhr industrial belt and Bavaria's manufacturing corridor sustain multi-year framework contracts for environmental due diligence.
China
State-owned energy enterprises and provincial development authorities procure environmental impact assessments for infrastructure and industrial expansion. MEE enforcement of dual carbon goals and tightening soil contamination standards are expanding the addressable market for remediation design. The Yangtze River Delta and Pearl River Delta concentrate demand for pollution control consulting.
United Kingdom
Real estate investment trusts and infrastructure funds drive demand for brownfield risk assessment and remediation planning. CSRD-aligned disclosure mandates and the Environment Act 2021 biodiversity net gain requirements are accelerating procurement of nature-positive transition advisory. London and the Midlands industrial corridor host the primary consulting firm presences.
Australia
Mining sector operators and port authorities commission closure planning and marine environmental assessments. State-level mine rehabilitation bonds and Commonwealth environmental protection obligations are tightening compliance planning requirements. Western Australia's Pilbara region and Queensland's Bowen Basin concentrate specialized hydrogeological and ecological consulting demand.
Environmental Consulting Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technical specialization depth and integrated engineering capabilities. The vendor base organizes into three tiers: global integrated engineering platforms capturing multi-site remediation portfolios, mid-scale specialists dominating water resource and climate resilience advisory, and regional compliance boutiques serving permit renewal cycles. Consolidation pressure intensifies as clients demand seamless data-to-design workflows spanning investigation, modeling, and construction oversight.
Within the integrated engineering tier, AECOM and Jacobs Engineering Group occupy positions exemplifying scale-driven competitive advantage across continental project portfolios. Tetra Tech represents the specialization archetype, anchoring differentiated positioning through concentrated expertise in water resource management and climate adaptation strategy. These three firms collectively illustrate how technical depth and geographic coverage determine tier placement in procurement decisions for complex multi-phase remediation programs.
| Leading Market Players |
|---|
| AECOM |
| Jacobs Engineering Group |
| Tetra Tech |
| Arcadis |
| WSP Global |
| Stantec |
| ERM (Environmental Resources Management) |
| Ramboll |
| ICF International |
| Others |
Supply Flow & Price Mechanics
Hydrogeologists with PFAS-specific expertise in the Houston-Gulf Coast corridor command premium compensation that compresses margins for commodity compliance work while widening spreads between value-based remediation advisory and routine permitting services. Labor-cost differentials between specialized risk assessors and generalist environmental technicians directly map to pricing-tier stratification across project portfolios.
Pricing Analysis
Outcome-based pricing tied to liability transfer completion anchors premium tiers for complex remediation programs, while subscription models for continuous monitoring dashboards displace transactional project fees for portfolio-scale industrial clients. Three-tier pricing structure across premium, standard, and economy levels separates integrated engineering platforms with multi-site capabilities from regional compliance boutiques. Pricing pressure stems from specialized labor scarcity elevating project delivery costs for emerging contaminant investigations. Manufacturing facilities facing EPA enforcement timelines exhibit lowest price sensitivity; small real estate developers conducting rapid due diligence absorb highest cost compression.
Supply Chain Analysis
Direct-to-industrial channels handle hyperscale energy sector demand for integrated decarbonization strategy, while regional compliance boutiques serve government procurement through framework contract aggregators. Advanced mass spectrometry instrumentation draws from concentrated German and Japanese original equipment manufacturers. PFAS-certified reference materials and ultra-trace analytical standards hinge on limited specialty chemical suppliers. Single-source vulnerability in high-resolution detection equipment creates procurement risk for laboratories scaling emerging contaminant capabilities. Distribution runs through multi-year framework contracts with defense contractors and petroleum refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environmental consulting sector sits in a technology-transition phase where predictive analytics platforms displace legacy site investigation methodologies. Machine learning contamination modeling is replacing manual hydrogeological interpretation.
For Market Incumbents: Acquire specialized PFAS toxicology databases and non-targeted analysis algorithm libraries to defend against boutique laboratories capturing enforcement-driven procurement. Consolidate backward integration into sensor network hardware to control data-to-design workflow margins. Regulatory fragmentation across state maximum contaminant levels threatens commodity compliance profitability.
For New Entrants and Emerging Players: Cloud-based environmental data platforms offer white-space entry points for mid-market manufacturing portfolios underserved by integrated engineering giants. Latin American mining closure planning in Chile and Peru presents the most penetrable geography for Spanish-language capabilities. Subscription pricing for continuous monitoring dashboards provides differentiated go-to-market positioning against project-based incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with water resource management specialists given EU Green Deal taxonomy acceleration of nature-positive transition planning. Long-term viability favors firms embedding climate resilience advisory into capital allocation committees rather than transactional procurement relationships. Watch EPA enforcement action volume against defense contractors as inflection signal for remediation demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of PFAS Specialist Firm | Captures enforcement-driven site characterization demand from EPA CERCLA actions. |
| Digital Twin Platform Integration | Enables predictive contamination management for proactive industrial client retention. |
| Latin America Geographic Expansion | Accesses underpenetrated mining sector environmental impact assessment markets. |
| CSRD-Aligned Disclosure Service Launch | Addresses EU corporate sustainability reporting obligations for industrial conglomerates. |
| Subscription Data Platform Development | Displaces project-specific deliverables with recurring revenue from portfolio-scale clients. |
Methodological Framework
Multi-period observation of EPA enforcement action filings, state-level maximum contaminant level adoptions, and brownfield redevelopment appropriation flows anchored the trend analysis, supplemented by interviews with remediation project managers, hydrogeology laboratory directors, environmental compliance officers at manufacturing facilities, and sustainability strategy leads at energy sector operators. Secondary validation drew from EPA CERCLA site tracking databases, ECHA REACH registration dossiers, EU Green Deal taxonomy technical screening criteria, and infrastructure stimulus appropriation records. Bottom-up project pipeline enumeration triangulated against top-down market sizing from regulatory obligation modeling.
Input-output matrices mapped service line demand to enforcement intensity, decarbonization mandate adoption, and infrastructure spending cycles across the projection horizon. Segmentation dimensions modeled include service type complexity, end-user procurement sophistication, project scale tier, and sector-specific regulatory exposure. CAGRs were derived from enforcement trajectory modeling and capital allocation pattern analysis. Forecast inputs incorporated PFAS regulatory timeline scenarios and EU CSRD disclosure mandate phase-in schedules.
The model holds under sustained EPA enforcement intensity and EU taxonomy implementation; deviation in regulatory rollback or infrastructure appropriation delays would shift demand trajectories. Practitioners should monitor state-level PFAS maximum contaminant level adoption rates and carbon border adjustment mechanism finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Anti-Pollution Mask Market
Environment & Sustainability
Europe Green Carbon Market
Environment & Sustainability
Environmental Remediation Technologies Market
Environment & Sustainability
Aluminum Cans Recycling Market
Environment & Sustainability
Europe Medical Waste Management Market
Environment & Sustainability
Recyclate PET Market
Environment & Sustainability
Europe E-Waste Management Market
Environment & Sustainability
Asia-Pacific Water Sink Market
Environment & Sustainability
Sustainable Air Filter Market
Environment & Sustainability
Release Liner Recycling Market
Environment & Sustainability
Global Waste Management Equipment Market
Environment & Sustainability
Singapore Air Purifier Market
Environment & Sustainability
APAC E-Waste Management Market
Environment & Sustainability
Smart Waste Management Market
Environment & Sustainability
UAE Biomedical Waste Management Market
Environment & Sustainability
Compostable Straws Market