
 Cloud Seeding System Market | 2026-2036
Cloud Seeding System Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Seeding System Market Outlook
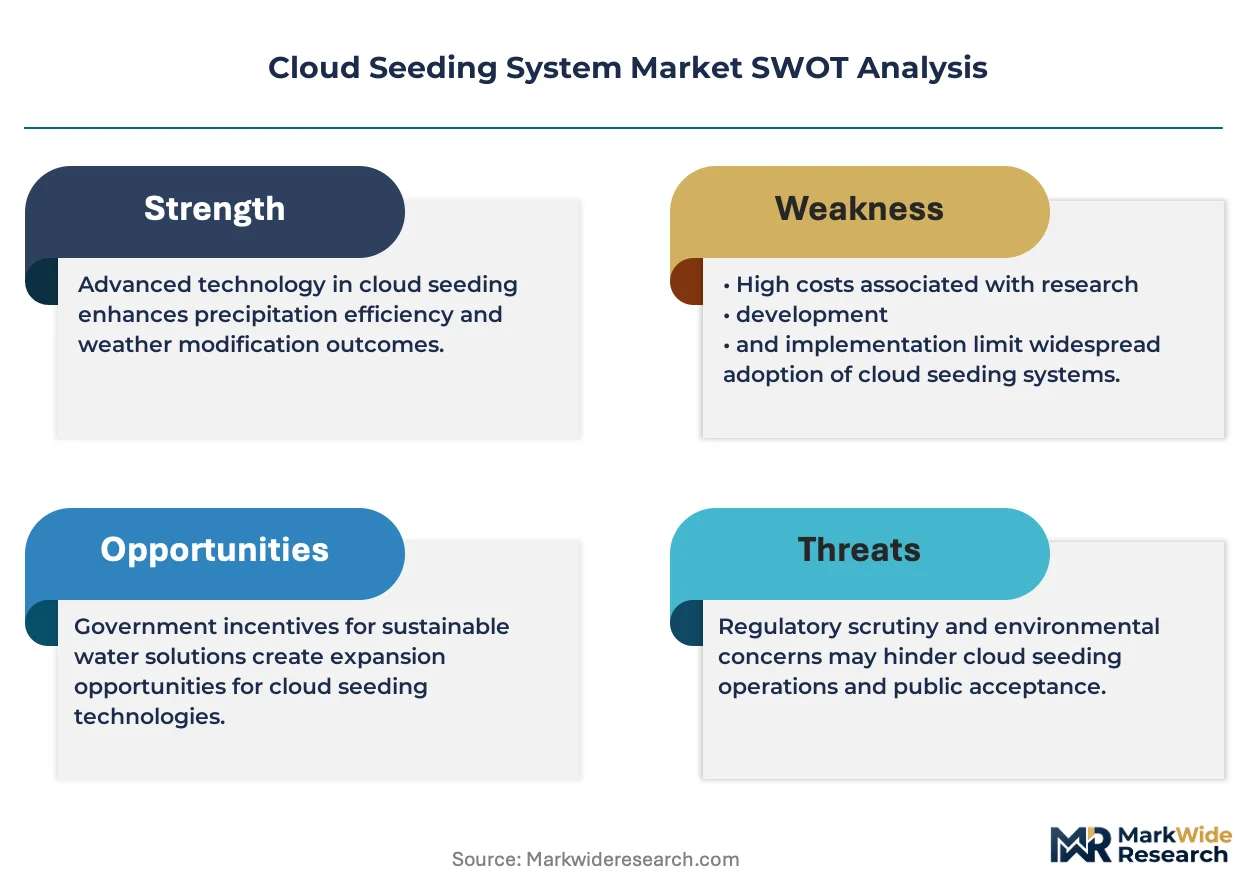
Leasing-based access to aircraft and ground-based generator fleets is reconfiguring capital requirements for new entrants in the cloud seeding system market. Weather Modification Inc. leverages its established aircraft leasing partnerships to sustain operations across multiple state contracts without full fleet ownership. Snowy Hydro Limited anchors its position through vertical integration into hydroelectric catchment management, linking seeding outcomes directly to power generation planning. Rainmaker Technology Corporation differentiates through specialized ice nucleation research, competing on technical efficacy rather than scale alone.
A cloud seed system disperses hygroscopic or glaciogenic agents—typically silver iodide with particle sizes of 0.1 to 1.0 micrometers—into suitable cloud formations to enhance precipitation through ice crystal nucleation or droplet coalescence. These systems operate via ground-based generators, aircraft-mounted flares, or remote-controlled drones, serving primarily to augment water supplies for agriculture, hydroelectric reservoirs, and municipal consumption. Silver iodide technology dominates operational deployments due to decades of proven efficacy and established handling protocols, while liquid nitrogen represents the fastest-growing segment as operators seek alternatives with lower environmental persistence. Government agencies constitute the deepest margin pool among end users, given their multi-year procurement cycles and indemnification structures that reduce vendor risk exposure.
The EPA governs silver compound environmental release thresholds under the Clean Water Act, while the FAA regulates aircraft-based dispersal altitudes and flight corridors over populated areas; state water boards in California and Colorado impose additional permitting requirements that shape operational seasonality and geographic scope. The European Union's REACH framework and ECHA substance evaluations are beginning to constrain silver iodide importation and use, creating compliance costs for operators seeking cross-border contracts. Stakeholders must monitor evolving nucleation material classifications and emerging state-level liability frameworks as liability allocation between seeding operators and water districts becomes a decisive contract negotiation variable.
Market Dynamics
Leasing-based access to aircraft and ground-based generator fleets is reconfiguring capital requirements for new entrants, compressing barriers to participation while fragmenting operational control across multiple vendor tiers.
Growth Catalysts
- Multi-year drought conditions:Persistent water stress across California, Arizona, and Colorado is forcing state water boards to expand cloud seeding procurement cycles for agricultural and municipal supply augmentation.
- Silver iodide efficacy protocols:Decades of operational data validating ice nucleation performance under varied atmospheric conditions reduce technical risk for government agency adopters.
- Hydroelectric reservoir optimization:Power utilities in water-stressed catchments are integrating seeding outcomes directly into generation planning, creating demand pull from energy sector end-users.
Market Restraints
- Silver compound environmental persistence:EPA scrutiny under the Clean Water Act is tightening dispersal thresholds and extending permitting timelines for operational deployments.
- Aircraft fleet concentration:Specialized cloud seeding aviation capacity clusters with a limited number of regional operators, creating supply bottleneck risk during peak seasonal windows.
- Liquid nitrogen cold chain requirements:Alternative nucleation agents demand cryogenic logistics infrastructure that remains underdeveloped outside major metropolitan distribution hubs.
Strategic Opportunities
- Drone-based dispersal platforms:Unmanned aerial systems below FAA-mandated altitude corridors are opening lower-cost entry points for precision targeting of orographic cloud formations.
- EU REACH compliance arbitrage:ECHA substance evaluation constraints on silver iodide importation create first-mover advantage for operators with pre-registered alternative nucleation materials.
- Municipal water district consolidation:Inter-district cost-sharing agreements in Colorado and Utah are aggregating demand into multi-year service contracts with indemnification structures favorable to vendors.
Industry Challenges
- Atmospheric physics modeling talent scarcity:Operational planning requires specialized expertise in mesoscale meteorology that outpaces university pipeline output in relevant geographies.
- Cross-jurisdictional liability allocation:Downstream precipitation claims between seeding operators, water districts, and agricultural insurers remain unresolved in state-level tort frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Seeding System Market |
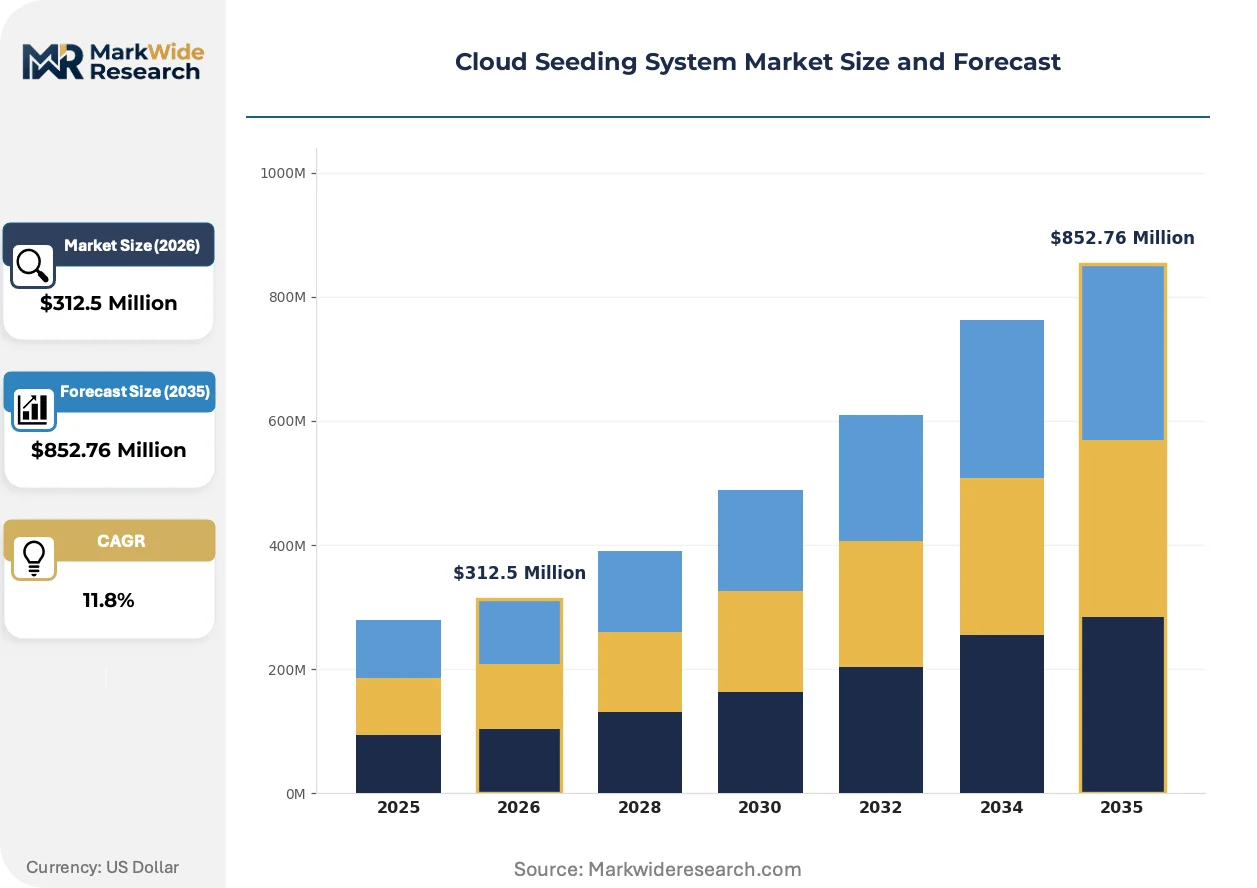
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $852.76 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Silver Iodide, Sodium Chloride, Liquid Nitrogen, Co2 Snow Application: Agricultural Enhancement, Drought Management, Weather Modification, Environmental Protection End User: Government Agencies, Agricultural Associations, Research Institutions, Private Enterprises Service Type: Cloud Seeding Operations, Consulting Services, Research & Development, Training Programs |
| Companies Covered | Snowy Hydro Limited, Mettech S.P.A, Weather Modification Inc., Rainmaker Technology Corporation, 3D S.A, RHS Consulting Inc., Ice Crystal Engineering, Atmospheric Systems Corporation, North American Weather Consultants Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Seeding System Market Strategic Shifts
Technological substitution in nucleation materials, regulatory reclassification of dispersal agents, and procurement model compression are actively restructuring competitive positioning and margin distribution across the value chain.
Remote-controlled drone platforms equipped with precision ice nucleation payload systems are expanding operational access to complex terrain previously unreachable by manned aircraft. Municipal water districts in the western United States are piloting these systems for targeted orographic enhancement. Fixed-wing aviation services for broad-area seeding are rendering obsolete for catchment-specific applications where terrain masking previously required full crewed deployment.
REACH framework substance evaluations by ECHA are reclassifying silver iodide importation requirements across European Union member states. This regulatory friction is redirecting operator investment toward alternative nucleation chemistry qualification programs. Cross-border service providers are responding by establishing captive liquid nitrogen supply chains to circumvent pending substance restriction schedules.
Water district procurement is compressing from annual emergency contracting to multi-year performance-based agreements with indemnification bundling. Equipment vendors and service operators are consolidating previously separate hardware and flight-hour billing into unified outcome-contingent structures. This behavioral shift is most visible in California's Central Valley agricultural water districts, where five-year master service agreements now dominate competitive tender processes.
Cloud Seeding System Market Segmentation
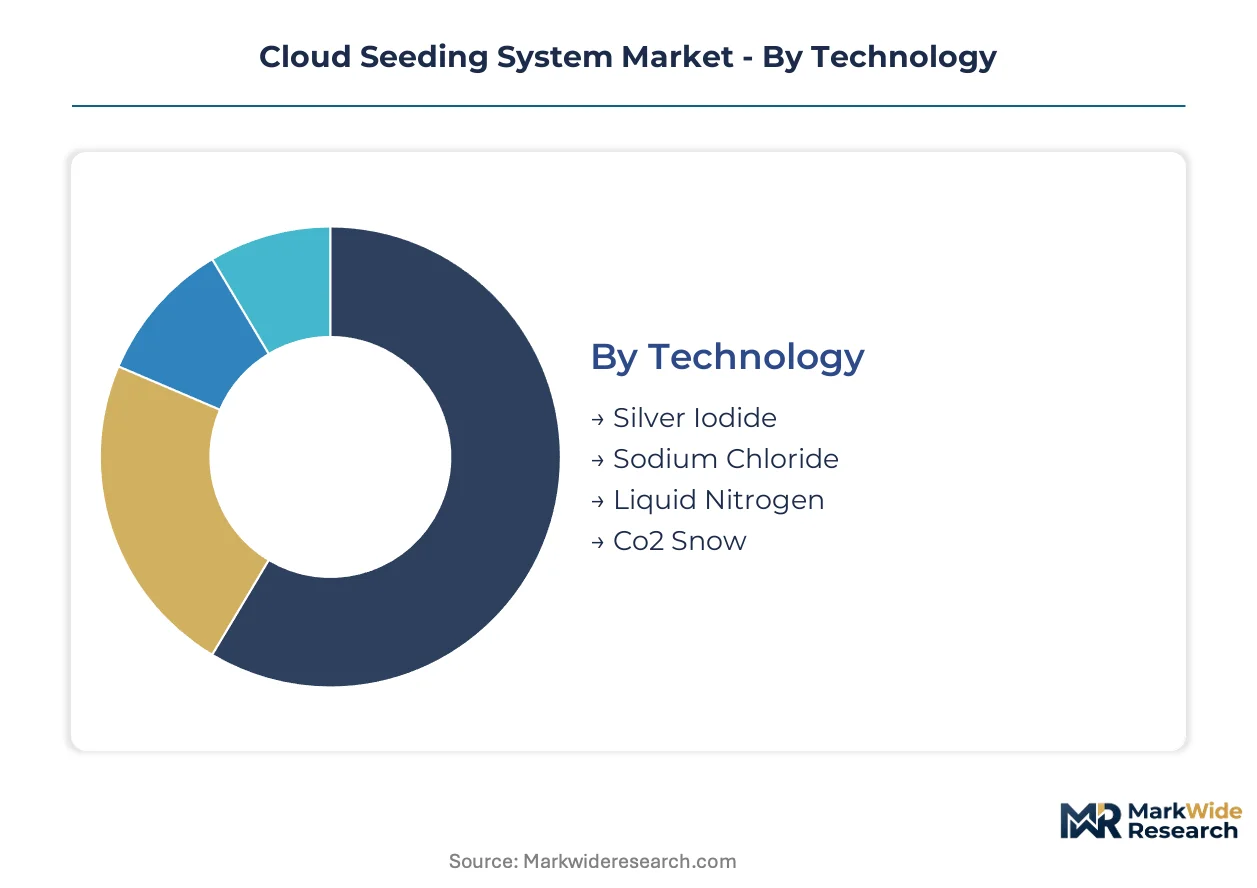
Cloud seeding system procurement varies sharply across technology maturity, regulatory exposure, and operational scale. Understanding these segment boundaries clarifies where capital concentrates and where new entrants face structural barriers.
Technology:
Cost tier differentiation in nucleation materials drives procurement patterns across government and private operators.
- Silver Iodide:The dominant glaciogenic agent with particle sizes calibrated to 0.1-1.0 micrometers for optimal ice crystal nucleation. Demand concentrates in California, Arizona, and Colorado state water board contracts where decades of operational data reduce technical risk assessment burdens for procurement officers.
- Liquid Nitrogen:Cryogenic alternative with minimal environmental persistence and simplified EPA compliance pathways. Adoption is accelerating fastest among municipal water districts seeking to preempt Clean Water Act threshold tightening and secure multi-year permits without silver compound mitigation plans.
- Sodium Chloride:Hygroscopic agent deployed primarily in warm-cloud coalescence applications with lower per-dose material costs.
- CO2 Snow:Solid carbon dioxide pellet systems for specialized high-altitude deployments where rapid sublimation kinetics match specific atmospheric conditions.
Silver Iodide commands the established base. The steepest expansion runs through Liquid Nitrogen.
Application:
Geographic water stress severity determines which application types absorb operational budgets across western United States jurisdictions.
- Agricultural Enhancement:Orographic seeding for snowpack augmentation serving Central Valley irrigation districts and Colorado River basin alfalfa operations. California's agricultural water districts now structure five-year master service agreements with outcome-contingent payment terms.
- Drought Management:Emergency procurement frameworks activated during multi-year precipitation deficits. Arizona and New Mexico state agencies maintain pre-negotiated activation contracts with specified response timeframes and indemnification structures.
- Weather Modification:Hail suppression and fog dispersion services for airport authorities and property insurers in hail-prone corridors.
- Environmental Protection:Wildfire smoke mitigation and air quality intervention programs piloted by municipal air quality management districts.
Agricultural Enhancement anchors procurement volumes. Drought Management is climbing the fastest as climate variability intensifies.
End User:
Customer type shapes contract duration, risk allocation, and technical specification stringency across the value chain.
- Government Agencies:State water boards and federal land management agencies with multi-year procurement cycles and sovereign indemnification. These contracts carry the deepest margin pools and lowest vendor risk exposure through built-in liability shields.
- Agricultural Associations:Irrigation district cooperatives and commodity boards pooling member fees for catchment-scale seeding programs. Colorado and Utah inter-district agreements are consolidating fragmented demand into unified tender processes.
- Research Institutions:University atmospheric science departments and national laboratories conducting controlled efficacy trials with restricted operational scopes.
- Private Enterprises:Hydroelectric utilities and ski resort operators integrating seeding outcomes into revenue planning with direct precipitation-to-revenue modeling.
Government Agencies dominate contract value. Private Enterprises are gaining share fastest as power utilities internalize seeding operations.
Service Type:
Supply concentration varies dramatically between operational execution and knowledge-intensive advisory functions.
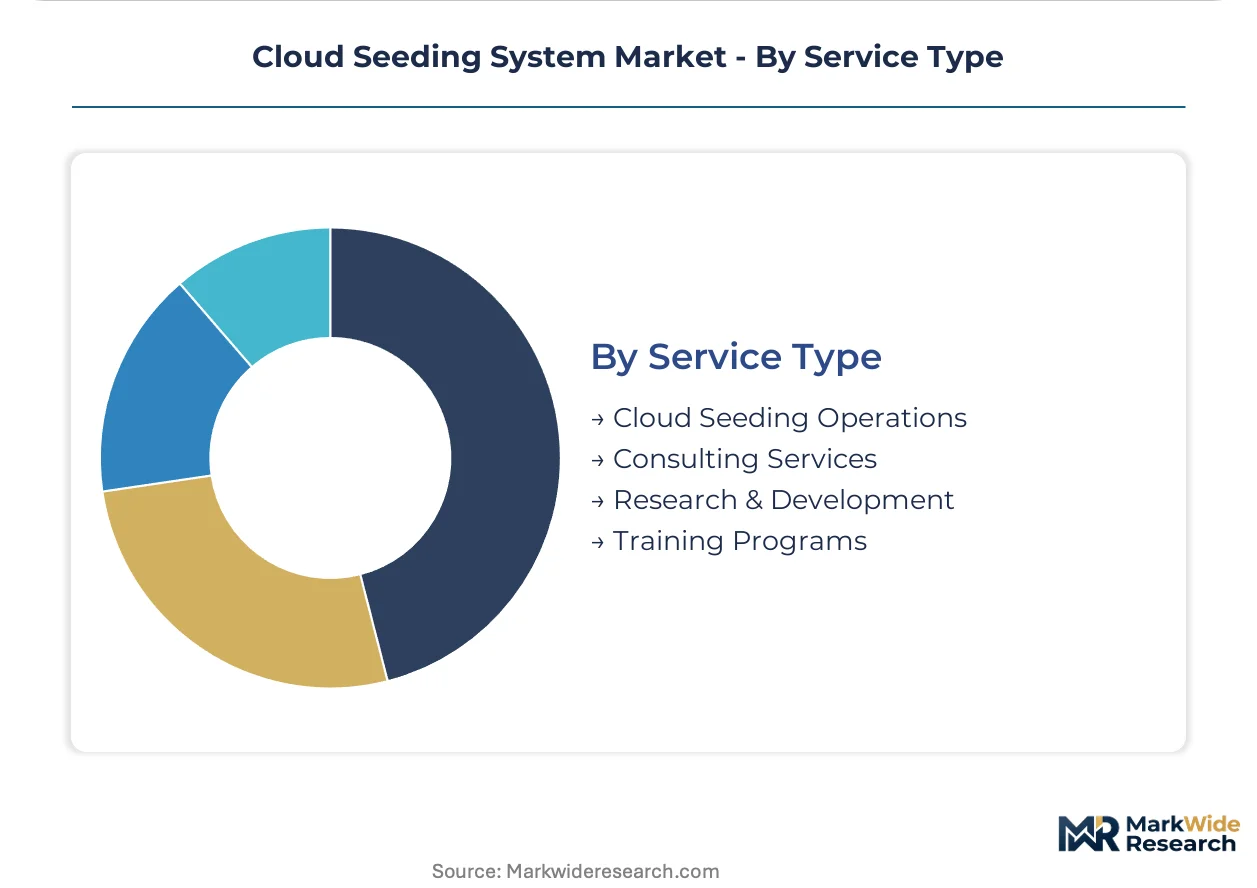
- Cloud Seeding Operations:Aircraft and ground-based generator deployment with flight-hour and material consumption billing. Weather Modification Inc. and regional aviation services cluster specialized cloud seeding fleet capacity, creating supply bottlenecks during peak seasonal windows.
- Consulting Services:Permit navigation, atmospheric assessment, and operational design for water districts lacking in-house meteorological expertise. Demand is concentrating where FAA altitude corridors and EPA dispersal thresholds intersect with complex terrain access challenges.
- Research & Development:Alternative nucleation material qualification and drone platform integration programs. ECHA REACH substance evaluations are redirecting investment toward liquid nitrogen and novel ice nucleation chemistry.
- Training Programs:Pilot certification and ground crew safety protocols for silver iodide handling and cryogenic logistics.
Cloud Seeding Operations capture the revenue base. Research & Development is expanding most quickly as regulatory reclassification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud seeding system trade flows remain domestically oriented, with service provision tightly coupled to watershed geography rather than cross-border equipment commerce. Most international exchange involves nucleation material supply chains rather than operational deployment.
United States
Multi-year drought across California, Arizona, and Colorado drives state water board procurement expansion. The EPA tightens silver iodide dispersal thresholds under Clean Water Act authority while the FAA regulates aircraft altitude corridors. Colorado River basin operators cluster in Denver and Sacramento metro areas where inter-district cost-sharing agreements consolidate demand.
Australia
Snowy Hydro Limited anchors hydroelectric catchment management through vertical integration of seeding outcomes into power generation planning. The country's national environmental regulator evaluates silver compound runoff impacts in alpine regions. New South Wales and Victorian water utilities pilot drone-based orographic enhancement in the Snowy Mountains.
Italy
Alpine hail suppression contracts serve agricultural cooperatives in Piedmont and Lombardy where vineyard and orchard exposure concentrates demand. ECHA REACH substance evaluations constrain silver iodide importation pathways. Mettech S.P.A operates from northern industrial clusters near Turin with established aviation partnerships.
United Arab Emirates
Desert precipitation augmentation programs target groundwater recharge and municipal supply security. The national meteorological authority oversees dispersal permits with altitude restrictions over coastal population centers. Dubai and Abu Dhabi emirates structure performance-based service agreements with sovereign indemnification frameworks.
Argentina
Cordoba and Mendoza provinces deploy hail suppression for soybean and wine grape protection under provincial agricultural ministry programs. The national aviation regulator coordinates flight corridors with commercial traffic management. 3D S.A maintains operational capacity from Buenos Aires with seasonal deployment to Andean foothill catchments.
Cloud Seeding System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with nucleation material and payload engineering. The vendor base clusters around three archetypes: aviation-leasing operators sustaining multi-state contracts without fleet ownership, utility-integrated providers linking seeding outcomes to power generation planning, and research-driven competitors differentiating through ice nucleation efficacy. Consolidation pressure runs through municipal water district procurement compression and multi-year performance-based agreement standardization.
Among utility-integrated operators, Snowy Hydro Limited exemplifies vertical control over catchment-scale deployment with direct precipitation-to-revenue modeling. Weather Modification Inc. and Rainmaker Technology Corporation occupy positions across the aviation-leasing and research-driven tiers respectively, with the former sustaining operations through established aircraft partnerships and the latter competing on technical efficacy rather than scale alone.
| Leading Market Players |
|---|
| Snowy Hydro Limited |
| Mettech S.P.A |
| Weather Modification Inc. |
| Rainmaker Technology Corporation |
| 3D S.A |
| RHS Consulting Inc. |
| Ice Crystal Engineering |
| Atmospheric Systems Corporation |
| North American Weather Consultants Inc. |
| Others |
Value Chain & Pricing Dynamics
Silver iodide importation restrictions under ECHA REACH substance evaluations determine both the pricing tier spreads between established and alternative nucleation agents and the geographic reconfiguration of material sourcing networks. EPA Clean Water Act threshold tightening compounds this dynamic by extending permitting timelines and forcing operators toward cryogenic alternatives with distinct logistics cost structures.
Pricing Analysis
Government agency buyers anchor contract pricing through multi-year master service agreements with sovereign indemnification and performance-contingent payment terms. Three-tier pricing structure across premium, standard, and economy levels separates full-service aviation-leasing operators from ground-based generator specialists and emerging drone platform vendors. Cost compression in liquid nitrogen cold chain logistics is intensifying because cryogenic infrastructure remains underdeveloped outside Denver and Sacramento distribution hubs. Agricultural associations exhibit the highest price sensitivity due to member-fee pooling constraints, while hydroelectric utilities demonstrate the lowest given direct precipitation-to-revenue modeling.
Supply Chain Analysis
Extended payment terms from aircraft leasing partners and supply-chain finance facilities secured through state water board procurement cycles stabilize working capital for operational deployment. Silver iodide production concentrates in the United States, Germany, and Japan; liquid nitrogen sourcing draws from domestic industrial gas distribution networks anchored in major metropolitan hubs. Raw material dependencies include silver nitrate precursor chemicals, aviation fuel for specialized cloud seeding aircraft, and cryogenic storage vessels for alternative nucleation agents. Single-source vulnerability runs through the limited pool of FAA-certified cloud seeding aviation operators concentrated in western states. Distribution runs through state water board procurement offices and inter-district cost-sharing agreements in Colorado and Utah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud seeding system demand is recovering through multi-year drought cycles across California, Arizona, and Colorado that force state water boards into expanded procurement cycles for agricultural and municipal supply augmentation.
For Market Incumbents: Pre-empt regulatory reclassification risk by accelerating liquid nitrogen supply chain qualification programs before ECHA REACH substance evaluations constrain silver iodide importation pathways. Secure captive cryogenic logistics capacity in Denver and Sacramento distribution hubs to defend margin position against emerging drone platform competitors. Deepen backward integration into ice nucleation research to maintain technical efficacy differentiation as procurement compresses toward outcome-contingent structures. For New Entrants and Emerging Players: Build out drone-based dispersal platforms for orographic cloud formations in complex terrain previously unreachable by manned aircraft, targeting municipal water districts in Colorado and Utah with inter-district cost-sharing agreements. The most penetrable segment sits in consulting services for permit navigation where FAA altitude corridors intersect with EPA dispersal thresholds. A direct go-to-market angle through pilot programs with agricultural water districts in California's Central Valley offers lower competitive intensity than established state contracts. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors operators with pre-registered alternative nucleation materials and established aviation-leasing partnerships. Long-term viability hinges on positioning upstream of procurement compression toward multi-year performance-based agreements with indemnification bundling. Acquisition targets should display vertical control over catchment-scale deployment with direct precipitation-to-revenue modeling. The signal to watch is ECHA substance evaluation timelines for silver iodide reclassification across European Union member states.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Nucleation Material Qualification | ECHA REACH compliance arbitrage creates first-mover positioning before silver iodide importation restrictions tighten. |
| Drone Platform Integration | FAA altitude corridor exemptions for unmanned systems open lower-cost entry points for terrain-constrained catchments. |
| Cryogenic Logistics Infrastructure | Liquid nitrogen cold chain buildout preempts EPA Clean Water Act threshold tightening and secures multi-year permits. |
| Inter-District Cost-Sharing Agreements | Colorado and Utah municipal consolidation aggregates fragmented demand into unified multi-year service contracts. |
| Aviation-Leasing Partnership Expansion | Weather Modification Inc.'s established aircraft partnerships demonstrate capital-light scaling without full fleet ownership. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with cloud seeding operators, state water board procurement officers, FAA flight corridor administrators, and atmospheric physics researchers; and secondary validation through EPA Clean Water Act filings, ECHA REACH substance evaluation databases, state water board contract award records, and hydroelectric utility generation planning disclosures. Bottom-up triangulation across nucleation material consumption volumes and top-down reconciliation against state procurement budgets anchored market sizing.
Forecast inputs considered technology substitution trajectories, regulatory reclassification timelines, and procurement model compression across the projection horizon. Segmentation dimensions modeled include nucleation material type, application purpose, end-user category, and service delivery mode. CAGRs derived from historical state contract award patterns and projected drought severity indices. Industry-specific forecast inputs incorporated snowpack augmentation efficacy data from Sierra Nevada and Rocky Mountain catchments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated hydroelectric utilities or drone platform specialists would shift outcomes. Macroeconomic deviation in agricultural commodity prices, regulatory acceleration of silver compound restrictions, or breakthrough ice nucleation chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Environment Monitoring Devices Market