
 Eco Funnel Market | 2026-2036
Eco Funnel Market Size, Share, and Industry Trends Forecast 2026-2036
Eco Funnel Market Foresight
China's manufacturing corridor for food-grade silicone products is narrowing the cost gap with conventional plastic alternatives. Bel-Art (SP Scienceware) leverages its laboratory supply heritage to dominate technical-grade reusable funnel segments. Fisher Scientific sustains channel control through institutional procurement contracts across North American research facilities. CP Lab Safety specializes in closed-system designs that meet stringent chemical handling protocols.
An eco funnel is a conical transfer device, typically molded from food-grade silicone, recycled polyethylene, or compostable paper laminates, engineered to channel liquids or dry goods between containers while minimizing spillage and material waste. Its primary commercial purpose centers on replacing single-use plastic funnels in foodservice, laboratory, and household settings where disposal regulations are tightening. Reusable silicone funnels command premium positioning due to heat resistance and extended service life, while biodegradable paper variants capture event catering contracts where composting infrastructure exists. Plastic funnels retain volume leadership in developing markets where unit economics still override environmental compliance costs.
EPA guidelines on chemical containment influence laboratory funnel specifications in the United States, while REACH restrictions on phthalate additives reshape European material formulations. China's GB standards for food-contact silicone and the EU's Packaging and Packaging Waste Regulation collectively elevate testing burdens for cross-border suppliers. Stakeholders must track evolving extended producer responsibility schemes that shift disposal accountability from end users back to manufacturers.
Market Dynamics
Single-use plastic bans across foodservice and laboratory sectors are forcing rapid material substitution, with silicone and compostable laminates displacing polyethylene as the default funnel substrate. Procurement officers now face dual mandates: compliance with disposal regulations and cost containment against reusable alternatives' higher unit economics.
Growth Catalysts
- REACH phthalate restrictions:European manufacturers reformulate food-contact plastics away from restricted additives, accelerating silicone funnel adoption in Germany's commercial catering sector where sustainability mandates outpace neighboring markets.
- Closed-system chemical handling:Laboratory safety protocols in North American research facilities now specify leak-proof transfer devices, pulling demand toward precision-molded reusable designs with integrated sealing mechanisms.
- China's GB food-contact standards:Stricter domestic testing requirements for silicone products are elevating export-grade manufacturing capabilities, narrowing quality gaps with incumbent European suppliers.
Market Restraints
- Petroleum-based resin volatility:Virgin polyethylene feedstock prices fluctuate with crude oil markets, compressing margins for biodegradable paper-laminate producers dependent on petroleum-derived barrier coatings.
- Guangdong manufacturing concentration:Over half of global food-grade silicone molding capacity clusters in China's Pearl River Delta, exposing supply chains to regional energy rationing and port congestion.
- Composting infrastructure gaps:Paper-laminate funnels require industrial composting facilities absent in most US municipalities, limiting addressable market to coastal states with established organic waste streams.
Strategic Opportunities
- India's FSSAI packaging directives:Pending regulations on single-use plastics in foodservice create first-mover advantage for silicone funnel suppliers establishing distribution through Mumbai and Bangalore hospitality clusters.
- Chemical-resistant fluoropolymer hybrids:Convergence of silicone flexibility with PTFE chemical inertness opens laboratory segments handling aggressive solvents previously excluded from reusable funnel specifications.
- Direct institutional procurement:Bypassing traditional laboratory distributors through GSA schedule contracts and university system purchasing cooperatives captures margin previously allocated to channel intermediaries.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and GB standard compliance testing extends product launch cycles by 8-14 months for cross-border suppliers.
- Legacy equipment retrofitting:Foodservice operators with sunk capital in disposable funnel dispensing systems face integration friction when transitioning to reusable inventory management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco Funnel Market |
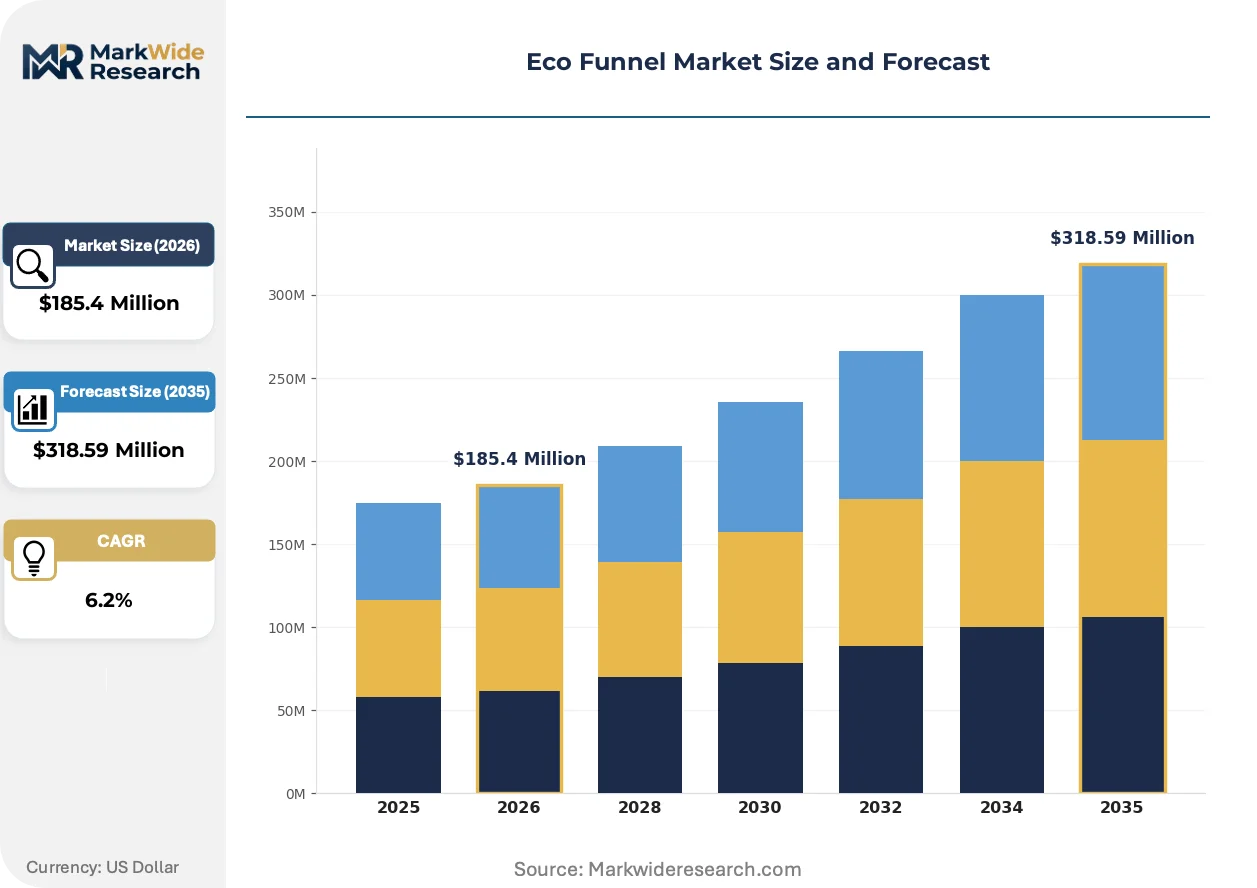
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $318.59 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Biodegradable, Reusable, Disposable End User: Households, Restaurants, Caterers, Event Planners Material: Polyethylene, Silicone, Paper, Glass Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Bel-Art (SP Scienceware), Fisher Scientific, Cole-Parmer, Avantor, Labconco, Chemglass Life Sciences, CP Lab Safety, Merck, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco Funnel Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product lifecycles, with functional performance now table stakes and sustainability credentials becoming the primary procurement discriminator across end-use segments.
Platinum-cured liquid silicone rubber (LSR) injection molding is rendering obsolete traditional compression-molded alternatives in high-precision laboratory applications. North American research universities and pharmaceutical quality-control labs are specifying LSR funnels for their sub-micron particle shedding resistance and autoclave durability. The technology is rendering obsolete mid-tier compression-molded suppliers unable to justify capital equipment upgrades.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating grease-resistant coatings from paper-laminate funnel formulations. European event-catering contractors must now source uncoated cellulose alternatives or shift entirely to silicone for outdoor foodservice applications. Germany's commercial catering sector, already subject to stricter municipal organic waste ordinances, is absorbing the highest compliance costs and accelerating supplier consolidation.
Buyer consolidation through group purchasing organizations is compressing vendor margins while demanding extended service agreements. North American hospital systems and university research clusters now negotiate multi-year funnel supply contracts bundling equipment, sterilization validation, and take-back logistics. The shift is most visible in California's UC system procurement, where sustainability scorecards weight reusable product lifecycles above unit price.
Eco Funnel Market Segmentation
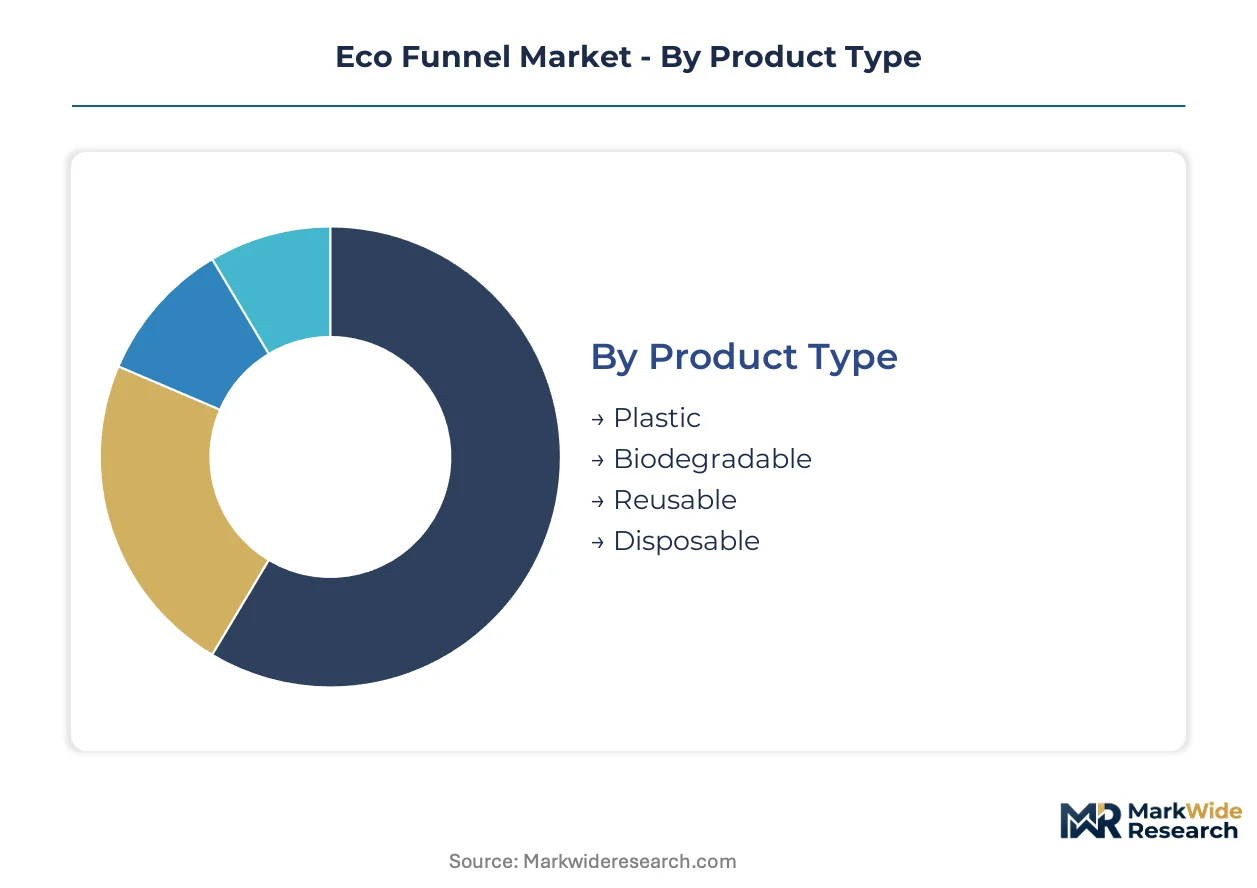
Material substitution mandates and procurement workflow differences fragment the eco funnel landscape into distinct competitive arenas. Each segmentation dimension reveals divergent margin structures, certification burdens, and channel control points that suppliers must navigate simultaneously.
Product Type:
Reusable silicone and single-use alternatives occupy opposite ends of the use-case spectrum, with hybrid formats emerging at regulatory boundaries.
- Reusable:Platinum-cured liquid silicone rubber (LSR) injection molding delivers autoclave durability and sub-micron particle shedding resistance. North American research universities specify these for pharmaceutical quality-control labs where closed-system chemical handling protocols apply.
- Plastic:Virgin polyethylene retains volume leadership in developing markets where unit economics override environmental compliance costs. India's pending FSSAI packaging directives threaten this segment's growth trajectory in foodservice applications.
- Biodegradable:Compostable paper laminates require industrial composting infrastructure absent in most US municipalities, limiting addressable market to coastal states with established organic waste streams.
- Disposable:Single-use formats face accelerating displacement as EU Packaging and Packaging Waste Regulation compliance costs rise across European foodservice procurement.
Established volume favors Plastic; emerging adoption favors Reusable.
End User:
Procurement sophistication and sustainability mandate exposure create four distinct customer tiers with diverging price elasticity and contract structures.
- Restaurants:North American and European operators expanding procurement of reusable formats to meet single-use plastic bans. Germany's commercial catering sector absorbs the highest compliance costs under stricter municipal organic waste ordinances.
- Caterers:European event-catering contractors source uncoated cellulose alternatives or shift to silicone for outdoor foodservice as REACH PFAS restrictions eliminate grease-resistant coatings from paper-laminate formulations.
- Households:Price-sensitive segment concentrated in developing markets where retail channel fragmentation complicates premium reusable product penetration.
- Event Planners:Temporary usage patterns favor disposable formats despite sustainability pressures, creating demand for certified compostable alternatives where waste diversion infrastructure exists.
Contract consolidation concentrates margin in Restaurants; spot purchasing characterizes Event Planners.
Material:
Feedstock volatility and cross-border certification timelines stratify supplier capabilities across four substrate categories.
- Silicone:Food-grade LSR commands premium positioning due to heat resistance and extended service life. China's GB standards for food-contact silicone elevate testing burdens for cross-border suppliers while narrowing quality gaps with European incumbents.
- Polyethylene:Petroleum-based resin price fluctuations compress margins for producers dependent on virgin feedstock, exposing cost structures to crude oil market volatility.
- Paper:Uncoated cellulose variants gain share in European markets as PFAS restrictions advance, though industrial composting infrastructure gaps constrain US penetration.
- Glass:Laboratory-grade borosilicate formats retain niche positioning for high-temperature chemical transfer applications where thermal shock resistance is non-negotiable.
Silicone captures margin expansion; Polyethylene retains shipment volume leadership.
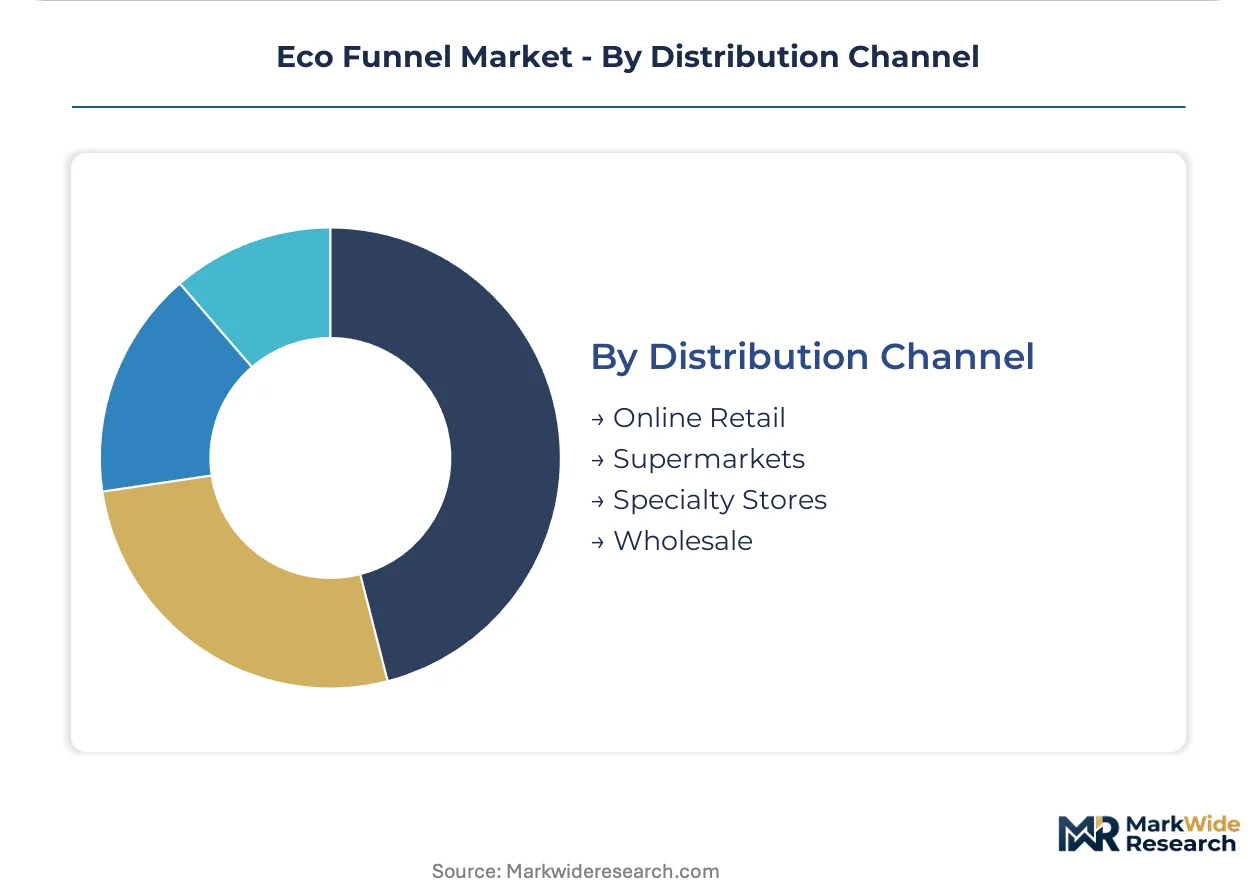
Distribution Channel:
Channel control points diverge between institutional procurement consolidation and retail fragmentation.
- Wholesale:Group purchasing organizations compress vendor margins while demanding extended service agreements bundling equipment, sterilization validation, and take-back logistics across North American hospital systems.
- Online Retail:Direct-to-operator platforms bypass traditional laboratory distributors, capturing margin previously allocated to channel intermediaries in research facility procurement.
- Specialty Stores:Laboratory supply heritage channels dominate technical-grade segments where specification expertise substitutes for price competition.
- Supermarkets:Mass retail penetration remains limited for premium reusable formats, with shelf space allocation favoring lower-unit-cost disposable alternatives.
Wholesale concentrates purchasing power; Online Retail fragments supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA guidelines on chemical containment and the EU's Packaging and Packaging Waste Regulation are reshaping procurement patterns across the dominant geographies for eco funnel demand.
United States
Research universities and pharmaceutical quality-control labs drive silicone funnel specifications under closed-system chemical handling protocols. EPA guidelines on chemical containment influence laboratory funnel specifications nationwide. California's UC system procurement applies sustainability scorecards that weight reusable product lifecycles above unit price.
Germany
Commercial catering operators absorb the highest compliance costs under stricter municipal organic waste ordinances. REACH restrictions on phthalate additives and PFAS reshape material formulations for food-contact applications. The Rhine-Ruhr industrial corridor concentrates demand from institutional foodservice operators transitioning from disposable formats.
China
GB standards for food-contact silicone elevate testing burdens while narrowing quality gaps with European suppliers. The Pearl River Delta hosts over half of global food-grade silicone molding capacity. Guangdong manufacturers face regional energy rationing and port congestion risks that expose supply chain vulnerabilities.
India
Pending FSSAI packaging directives on single-use plastics create first-mover opportunities for silicone funnel suppliers. Foodservice procurement in Mumbai and Bangalore hospitality clusters shows early adoption momentum. Virgin polyethylene funnels retain volume leadership where unit economics still override environmental compliance costs.
United Kingdom
Hospital systems and university research clusters negotiate multi-year supply contracts bundling equipment and sterilization validation. ECHA restrictions on chemical additives align procurement with continental European standards. The Southeast England logistics corridor channels distribution to institutional buyers consolidating through group purchasing organizations.
Eco Funnel Market Competitive Landscape
Laboratory supply heritage players and diversified scientific distributors split the market into distinct competitive arenas. The vendor base concentrates around entities with institutional procurement relationships and closed-system design capabilities. Three archetypes dominate: technical-grade specialists with specification expertise, diversified distributors leveraging channel control, and safety-focused engineers of integrated sealing mechanisms. Competitive moves center on direct institutional procurement contracts and multi-year service agreements bundling validation and logistics.
Among North American laboratory supply incumbents, Bel-Art (SP Scienceware) and Fisher Scientific exemplify the heritage-channel archetype, while CP Lab Safety occupies a position within the safety-engineering tier. These entities anchor competitive positioning through institutional relationships rather than price competition, with each representing distinct pathways for procurement officer engagement across research facilities and commercial catering sectors.
| Leading Market Players |
|---|
| Bel-Art (SP Scienceware) |
| Fisher Scientific |
| Cole-Parmer |
| Avantor |
| Labconco |
| Chemglass Life Sciences |
| CP Lab Safety |
| Merck |
| Medline Industries |
| Others |
Supply & Pricing Matrix
Guangdong energy rationing and port congestion risks determine both the spread between platinum-cured silicone premiums and commodity polyethylene baselines and the geographic shape of supplier networks. Procurement officers face dual exposure: feedstock volatility compressing margins on biodegradable laminates and single-source dependency on Pearl River Delta molding capacity.
Pricing Analysis
Price spreads between Germany and India exceed those within any other corridor, with REACH-compliant silicone funnels in the Rhine-Ruhr cluster commanding substantial premiums over virgin polyethylene alternatives in Mumbai foodservice procurement. Pricing stratifies across premium, standard, and economy tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the biodegradable paper-laminate tier is intensifying because petroleum-derived barrier coatings expose producers to crude oil volatility. Households in developing markets exhibit the highest price sensitivity, while North American research universities demonstrate the lowest due to lifecycle-cost procurement frameworks.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for cross-border silicone suppliers navigating divergent GB standards and FDA compliance pathways. Manufacturing gravity centers on China, Germany, and the United States, with raw material dependencies spanning platinum-cured liquid silicone rubber, food-grade polyethylene resin, and uncoated cellulose pulp. Single-source vulnerability concentrates in Guangdong's Pearl River Delta, where over half of global food-grade silicone molding capacity faces regional energy rationing. Distribution runs through institutional procurement contracts and group purchasing organizations in North America, specialty laboratory supply channels in Europe, and fragmented retail networks in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eco funnel market is entering a cyclical upswing driven by regulatory enforcement waves across the EU Packaging and Packaging Waste Regulation and pending FSSAI directives in India. Recovery sustainability depends on supplier adaptation to material substitution mandates and procurement consolidation trends.
For Market Incumbents: Build certification moats around simultaneous FDA, EFSA, and GB standard compliance to defend against mid-tier compression-molded suppliers unable to justify capital equipment upgrades for platinum-cured LSR injection molding. Prioritize backward integration into platinum-cured liquid silicone rubber feedstock to secure margin against petroleum-based resin volatility. Capture channel control through multi-year service agreements bundling sterilization validation and take-back logistics across North American hospital systems and university research clusters. For New Entrants and Emerging Players: Pursue white-space penetration in India's Mumbai and Bangalore hospitality clusters ahead of FSSAI packaging directive enforcement, where virgin polyethylene incumbents face displacement risk. Target European event-catering contractors forced to abandon PFAS-coated paper laminates under REACH restrictions. Establish direct-to-operator online platforms to bypass traditional laboratory distributors and capture margin previously allocated to channel intermediaries in research facility procurement. For Investors and Strategic Acquirers: REACH phthalate and PFAS restrictions reshaping the acquisition landscape toward safety-engineered specialists with closed-system design capabilities and institutional procurement relationships. Long-term viability favors vertically integrated mid-cap specialists with captive silicone molding capacity and cross-border certification infrastructure. The signal to watch is procurement officer adoption of sustainability scorecards weighting reusable product lifecycles above unit price in California's UC system and comparable institutional clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured LSR Capacity Expansion | Sub-micron particle shedding resistance meets North American pharmaceutical quality-control lab specifications. |
| Backward Integration into Silicone Feedstock | Captive supply of food-grade LSR insulates margins from petroleum-based resin price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EFSA, and GB compliance accelerates product launch cycles for cross-border suppliers. |
| Direct Institutional Procurement Contracts | GSA schedule contracts and university purchasing cooperatives capture margin from channel intermediaries. |
| Closed-System Design Patent Portfolio | Integrated sealing mechanisms differentiate technical-grade offerings for laboratory safety protocols. |
Research Methodology
Initial hypotheses were tested against primary input from procurement officers at North American research universities, commercial catering operators in Germany's Rhine-Ruhr corridor, silicone molding plant managers in Guangdong, laboratory supply distributors, and regulatory affairs specialists navigating REACH and FDA compliance pathways, and refined through secondary validation against customs trade data, EPA chemical containment guidelines, EFSA food-contact material submissions, SEC filings from laboratory supply distributors, and EU Packaging and Packaging Waste Regulation implementation documents. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics across material substitution trajectories and procurement consolidation patterns anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end-user sophistication tier, material substrate category, and distribution channel control structure. CAGRs were derived from trend extrapolation calibrated against regulatory enforcement timelines and feedstock price elasticity assumptions. Forecast inputs incorporated platinum-cured LSR injection molding adoption curves and industrial composting infrastructure penetration rates.
Sensitivities concentrate around REACH PFAS restriction enforcement timing, Guangdong energy rationing severity, and FSSAI directive implementation pace in India. Forecasts reflect assumptions regarding regulatory harmonization and material substitution cost parity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market