
 Environmental Technology Market | 2026-2036
Environmental Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Technology Market Analytics
Multi-source procurement for advanced membrane systems is recalibrating how municipal buyers structure their capital programs. Veolia Environment SA leverages its integrated water-waste-energy platform to anchor long-term service contracts across European utilities. Siemens AG competes through digital twin integration for treatment plant optimization, while Xylem Inc. specializes in smart pumping and sensor networks for leak detection infrastructure.
Environmental technology encompasses engineered systems, processes, and equipment designed to monitor, prevent, or remediate pollution across air, water, and soil media, typically operating within parameters such as 99.9% contaminant removal efficiency or net-zero emission thresholds. These systems serve industrial and commercial end users by ensuring regulatory compliance, reducing resource consumption, and enabling circular material flows. Water Treatment commands the deepest installed base and replacement revenue streams among product types, while Carbon Capture within the technology dimension attracts the steepest venture capital inflows as project developers seek bankable offtake structures. Sustainable Manufacturing applications now pull the fastest tender growth as automotive and electronics OEMs enforce Scope 3 supplier mandates.
The EPA enforces effluent limitation guidelines that directly dictate membrane filtration upgrade cycles for US industrial discharge permits, while the EU Green Deal and REACH compliance frameworks compel European manufacturers to adopt green chemistry substitution pathways. China's MEE implements dual carbon targets that restrict new coal-chemical permits unless paired with carbon capture retrofits. Stakeholders must track how divergent carbon accounting standards between jurisdictions reshape equipment certification requirements and cross-border project finance eligibility.
Market Dynamics
Membrane filtration and carbon capture systems are converging into integrated treatment trains, forcing equipment vendors to redesign their product architectures around modular, multi-pollutant platforms rather than single-media solutions.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening discharge standards for US industrial permits are mandating membrane upgrades at chemical and food processing facilities.
- China's MEE dual carbon targets:New coal-chemical project approvals now require carbon capture retrofits, accelerating capital deployment into post-combustion capture systems.
- India's PLI scheme for clean technology:Production-linked incentives are pulling manufacturing capacity into the country's industrial corridors, creating localized demand for water reuse infrastructure.
Market Restraints
- Specialized ceramic and polymer membrane feedstock concentration:Japanese and German suppliers control critical hollow-fiber substrate supply, exposing buyers to input cost volatility.
- Carbon capture energy penalty:Amine-based absorption systems consume 15-25% of plant output, limiting deployment to facilities with stranded power assets.
- REACH compliance friction for green chemistry substitutes:European manufacturers face extended registration timelines for novel treatment chemistries, delaying product substitution cycles.
Strategic Opportunities
- Brazilian municipal water utilities:Underinvestment in smart metering and leak detection creates white space for sensor network deployment in São Paulo and Rio de Janeiro distribution systems.
- Automotive Scope 3 supplier mandates:OEM enforcement of sustainable manufacturing standards is opening tender opportunities for closed-loop water systems at tier-1 component plants.
- Digital twin convergence with membrane operations:Real-time performance modeling is enabling predictive maintenance contracts that bundle hardware with analytics subscriptions.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Integration of process engineering, data science, and regulatory compliance expertise remains difficult to source for project developers.
- Legacy SCADA system interoperability:Brownfield treatment plants require costly protocol translation layers to connect new sensor networks with existing control architectures.
- Carbon accounting standard divergence:Inconsistent measurement methodologies between EU ETS, California cap-and-trade, and China's ETS complicate equipment certification for multinational projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Technology Market |
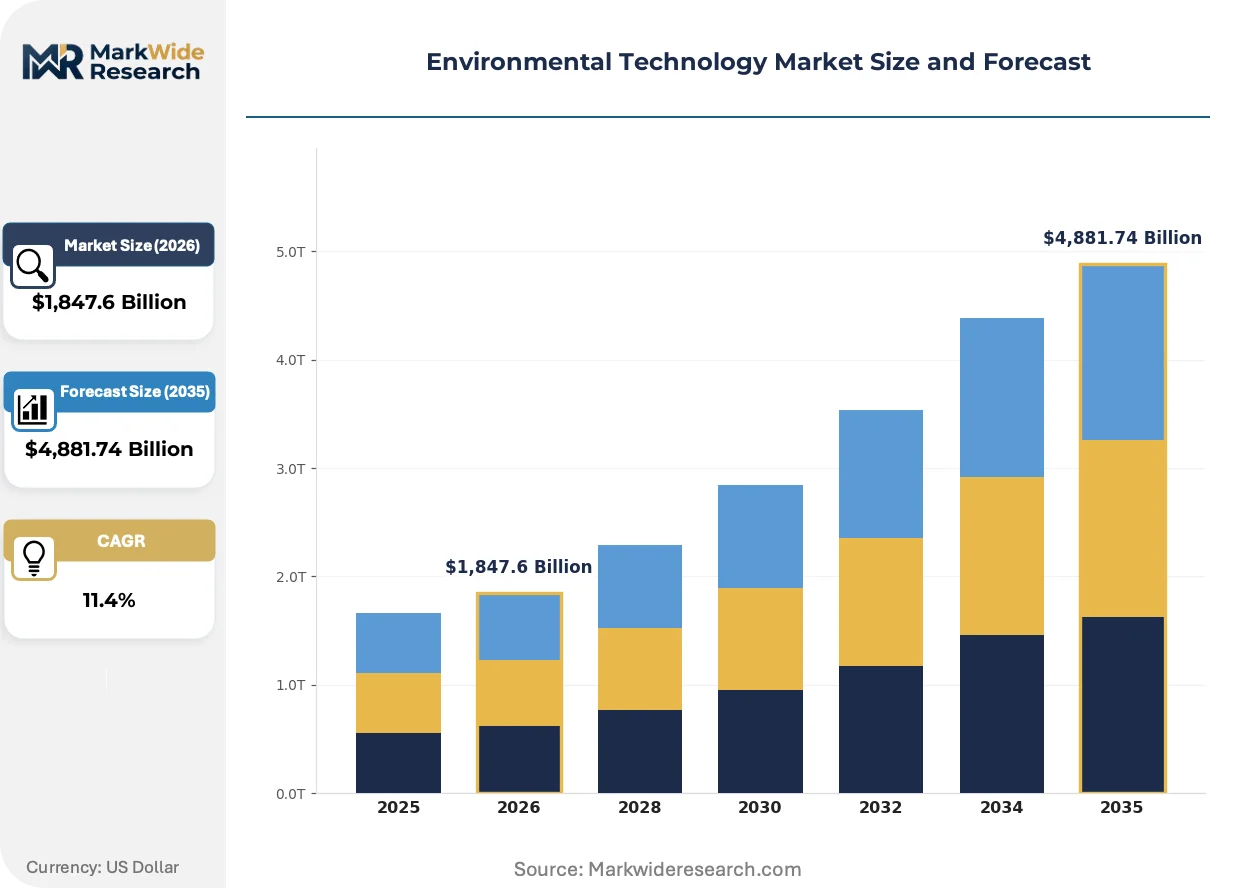
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $4,881.74 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Treatment, Air Purification, Waste Management, Renewable Energy Application: Agricultural Efficiency, Pollution Control, E-Waste Recycling, Sustainable Manufacturing End User: Industrial Sector, Municipalities, Residential Users, Commercial Facilities Technology: Biodegradation, Carbon Capture, Solar Photovoltaics, Green Chemistry |
| Companies Covered | Veolia Environment SA, AECOM, SUEZ, Siemens AG, General Electric, Clean Harbors Inc., Schneider Electric, Xylem Inc., Waste Management Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Technology Market Evolving Landscape
Equipment architectures are collapsing separate air, water, and waste treatment functions into unified platforms, while regulatory frameworks harden around verified emission and effluent performance rather than installed technology type.
Forward osmosis-draw solute systems are unifying water concentration and selective contaminant extraction into single-stage operations. Food and beverage processors in California's Central Valley are piloting these units for high-salinity brine management. The technology is unifying what previously required sequential thermal and membrane steps, compressing both footprint and energy intensity for zero-liquid-discharge targets.
The EU Green Deal's Carbon Border Adjustment Mechanism is restructuring import competitiveness for energy-intensive goods. European steel and cement producers must now document embedded emissions or face tariff adjustments, accelerating demand for on-site carbon capture verification. German industrial clusters are responding by consolidating capture infrastructure across contiguous plant sites to achieve economies of scale.
Buyers are compressing supplier evaluation cycles from multi-year framework agreements to annual technology refresh assessments. Water utilities in Japan's Kansai region now require live pilot demonstrations rather than reference-based selection. Municipal procurement offices in Osaka and Kyoto are running parallel trials of competing membrane configurations before committing to decade-long service contracts.
Environmental Technology Market Segmentation
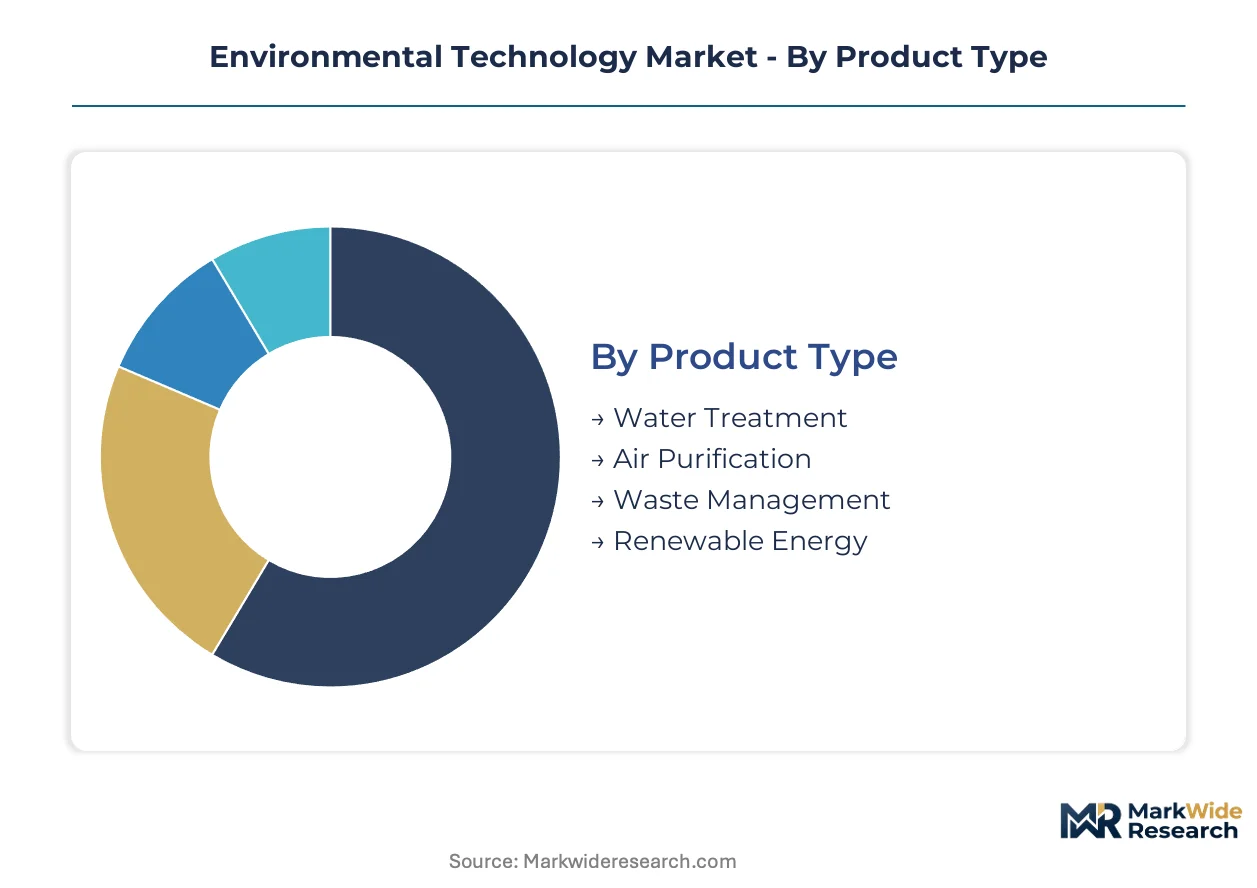
Environmental technology vendors must align R&D roadmaps and distribution channels against distinct performance thresholds, regulatory compliance tiers, and capital cycle timing across product, application, end user, and technology dimensions. Segmentation discipline separates replacement revenue streams from greenfield deployment opportunities.
Product Type:
Water Treatment anchors replacement revenue through membrane degradation cycles, while Carbon Capture commands venture premiums despite limited installed base.
- Water Treatment:Engineered systems including membrane filtration, biological reactors, and advanced oxidation processes achieve effluent standards down to parts-per-billion contaminant thresholds. Municipal utilities in Germany and Japan structure decade-long service contracts around membrane replacement schedules, with EPA effluent guidelines accelerating upgrade cycles at US industrial facilities.
- Air Purification:Scrubbers, electrostatic precipitators, and catalytic oxidation units remove particulate and gaseous emissions from combustion and industrial processes. China's MEE dual carbon targets are mandating retrofit installations at coal-chemical complexes in Shanxi and Inner Mongolia, creating localized procurement surges for multi-pollutant control systems.
- Waste Management:Thermal treatment, anaerobic digestion, and material recovery facilities process municipal and hazardous waste streams.
- Renewable Energy:Distributed generation and storage systems reduce grid dependency for treatment plant operations.
Mature deployment sits with Water Treatment. Newer deployment is concentrated in Carbon Capture.
Application:
Pollution Control absorbs regulatory compliance spending, while Sustainable Manufacturing pulls fastest tender growth from automotive and electronics OEM Scope 3 mandates.
- Sustainable Manufacturing:Closed-loop water systems, solvent recovery units, and process-integrated emission controls enable circular production flows. Tier-1 automotive suppliers in Germany's Baden-Württemberg cluster face BMW and Mercedes-Benz supplier mandates requiring documented water reuse rates above 85%, compressing procurement timelines for integrated treatment trains.
- Pollution Control:End-of-pipe treatment systems ensure discharge permit compliance across air, water, and soil media. India's Central Pollution Control Board enforcement in the Delhi-Mumbai Industrial Corridor is driving membrane bioreactor installations at textile and pharmaceutical plants facing zero-liquid-discharge requirements.
- Agricultural Efficiency:Precision irrigation, nutrient recovery, and livestock waste processing systems reduce water and fertilizer intensity.
- E-Waste Recycling:Hydrometallurgical and pyrometallurgical recovery systems extract rare earth elements and precious metals from discarded electronics.
Compliance-driven procurement dominates Pollution Control. Value-chain pressure is expanding Sustainable Manufacturing fastest.
End User:
Industrial Sector concentrates capital deployment scale, while Municipalities fragment across procurement sophistication tiers from smart infrastructure to basic compliance.
- Industrial Sector:Chemical, food processing, electronics, and energy facilities operate continuous treatment systems with uptime requirements exceeding 99.5%. Brazil's São Paulo industrial belt is seeing concentrated demand for sensor networks and predictive analytics as manufacturers face ANA water stress regulations and pressure from export markets requiring supply chain water risk disclosure.
- Municipalities:Water and wastewater utilities manage distributed infrastructure across collection, treatment, and distribution networks. Japanese municipalities in the Kansai region now mandate live pilot demonstrations before decade-long membrane service contracts, compressing supplier evaluation from reference-based selection to parallel technology trials.
- Residential Users:Point-of-use filtration and decentralized treatment systems serve individual households and small communities.
- Commercial Facilities:Hotels, hospitals, and office complexes install building-scale water reuse and air quality systems.
Industrial Sector deployment leads on technology sophistication. Municipalities are climbing fastest on digital integration.
Technology:
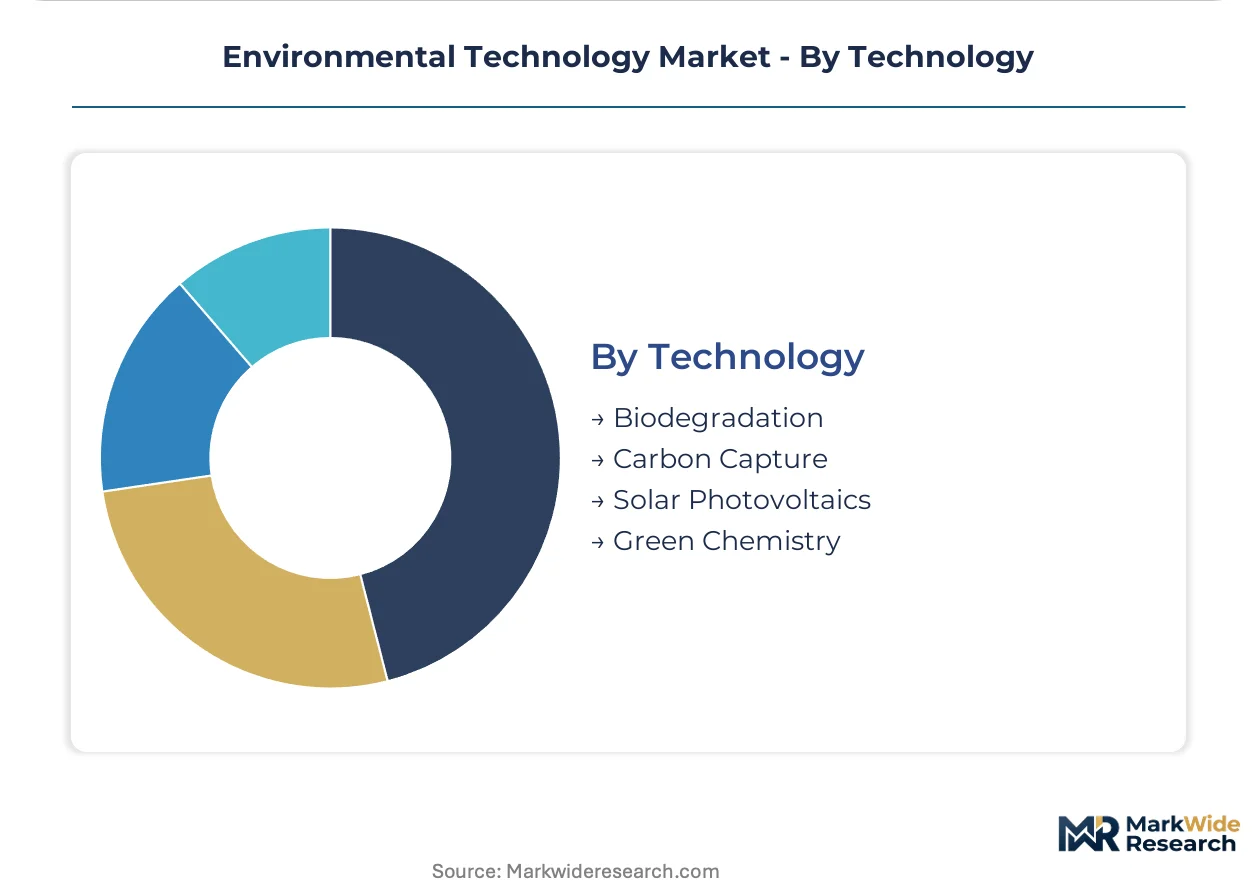
Carbon Capture attracts steepest venture capital inflows as project developers seek bankable offtake structures, while Biodegradation serves established waste processing margins.
- Carbon Capture:Post-combustion amine absorption, pre-combustion gasification, and direct air capture systems separate CO2 for utilization or geological storage. German industrial clusters in the Rhine-Ruhr region are consolidating capture infrastructure across contiguous steel and cement plants to achieve economies of scale under EU ETS price pressure and the Carbon Border Adjustment Mechanism.
- Green Chemistry:Bio-based solvents, catalytic processes, and atom-efficient synthesis routes eliminate hazardous substance use. European manufacturers face extended ECHA registration timelines for novel treatment chemistries, delaying substitution cycles despite REACH compliance pressure.
- Biodegradation:Microbial consortia break down organic contaminants in soil, water, and waste matrices.
- Solar Photovoltaics:Distributed generation reduces grid dependency for remote treatment and monitoring infrastructure.
Biodegradation represents mature, margin-compressed deployment. Carbon Capture and Green Chemistry are gaining share fastest on regulatory and capital inflow momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial procurement concentrates most visibly in Germany, China, and India, where regulatory enforcement and manufacturing incentives are compressing capital deployment timelines for treatment infrastructure.
Germany
Steel and cement producers in the Rhine-Ruhr industrial cluster face mounting pressure from the EU Carbon Border Adjustment Mechanism to document embedded emissions or absorb tariff penalties. The country's national environmental regulator enforces strict effluent standards that mandate membrane filtration upgrades at chemical processing facilities. Bavarian municipalities are consolidating smart water infrastructure contracts around decade-long service agreements with integrated platform providers.
China
Coal-chemical complexes in Shanxi and Inner Mongolia must install carbon capture retrofits to secure new project approvals under MEE dual carbon targets. The Ministry of Ecology and Environment restricts permits unless paired with post-combustion capture systems. Yangtze River Delta manufacturing zones are driving localized demand for multi-pollutant control technologies as export-facing producers face supply chain disclosure requirements.
India
Textile and pharmaceutical plants along the Delhi-Mumbai Industrial Corridor face zero-liquid-discharge mandates from the Central Pollution Control Board. The PLI scheme for clean technology manufacturing is pulling capacity into Gujarat and Tamil Nadu industrial corridors. Maharashtra's automotive component suppliers are procuring closed-loop water systems to meet BMW and Mercedes-Benz Scope 3 supplier mandates.
United States
EPA effluent limitation guidelines are accelerating membrane upgrade cycles at chemical and food processing facilities in the Gulf Coast petrochemical corridor. California's Central Valley food and beverage processors are piloting forward osmosis systems for high-salinity brine management. Texas industrial facilities with stranded power assets represent the primary deployment base for amine-based carbon capture systems.
Brazil
ANA water stress regulations are compelling manufacturers in São Paulo's industrial belt to install sensor networks and predictive analytics for distribution system management. The national water agency enforces supply chain water risk disclosure for export-oriented producers. Rio de Janeiro municipal utilities are expanding procurement of smart metering infrastructure to address chronic underinvestment in leak detection capabilities.
Environmental Technology Market Competitive Landscape
Long-term service contracting dominates the current landscape as equipment vendors reposition from transactional hardware sales to recurring revenue models. The vendor base organizes around three strategic archetypes: integrated water-waste-energy platform operators, digital twin specialists for treatment plant optimization, and smart infrastructure sensor network providers. Consolidation pressure is intensifying through strategic partnerships bundling hardware with analytics subscriptions, while geographic expansion into India's industrial corridors accelerates among players seeking PLI-linked procurement opportunities.
Within the integrated platform tier, Veolia Environment SA and SUEZ exemplify the service-contract archetype anchoring European utility relationships. Siemens AG occupies a position at the digital convergence end, while Xylem Inc. represents the sensor network specialization vector. These three entities collectively illustrate how competitive positioning now depends on bundling hardware deployment with predictive maintenance capabilities rather than standalone equipment specifications.
| Leading Market Players |
|---|
| Veolia Environment SA |
| AECOM |
| SUEZ |
| Siemens AG |
| General Electric |
| Clean Harbors Inc. |
| Schneider Electric |
| Xylem Inc. |
| Waste Management Inc. |
| Others |
Value Network & Pricing Analysis
Modular multi-pollutant platform architectures are collapsing separate treatment functions into unified systems, simultaneously compressing manufacturing cost curves and concentrating procurement power among integrated vendors capable of delivering bundled hardware-analytics packages.
Pricing Analysis
Extended warranty and predictive maintenance bundling now separates premium-tier vendors from unbundled equipment suppliers in municipal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects membrane certification grade and digital twin integration depth. Cost compression in standard-tier membrane systems is intensifying because Japanese and German hollow-fiber substrate suppliers command feedstock pricing power. Municipal utilities exhibit highest price sensitivity due to decade-long contract structures, while industrial facilities with Scope 3 compliance mandates show lowest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for carbon capture skids, while distributor networks serve fragmented municipal procurement offices. Ceramic and polymer membrane substrate manufacturing concentrates in Japan, Germany, and South Korea. Supply chains draw from specialized hollow-fiber polymers, amine solvents for absorption systems, and rare-earth catalysts for oxidation units. Single-source vulnerability in hollow-fiber substrate supply exposes buyers to input cost volatility. Distribution runs through regional system integrators who bundle installation with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated membrane-carbon capture treatment trains are displacing legacy single-media installations, compressing upgrade cycles and recalibrating vendor competitive moats around predictive analytics capabilities.
For Market Incumbents: To counter digital-native entrants with pure-play analytics platforms, anchor long-term service contracts through backward integration into membrane substrate manufacturing and accelerate certification investment for EU Green Deal compliance tiers. Prioritize captive supply of ceramic hollow-fiber materials to defend margin position against Japanese and German feedstock suppliers.
For New Entrants and Emerging Players: Cloud-based digital twin marketplaces offer the lowest barrier-to-entry vector for penetrating Brazil's underinvested municipal water utilities and India's PLI-linked industrial corridors. Target São Paulo and Rio de Janeiro distribution system retrofits with sensor-as-a-service subscription models bypassing capital-intensive membrane manufacturing.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated platform operators seeking predictive maintenance capabilities. Five-to-ten year viability hinges on bankable carbon capture offtake structures materializing. Monitor EPA effluent guideline enforcement intensity as the primary inflection signal for membrane replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Captive supply of hollow-fiber materials insulates margin pressure from Japanese and German feedstock concentration. |
| Predictive Maintenance Platform Launch | Real-time performance modeling enables recurring revenue contracts bundling hardware with analytics subscriptions. |
| Joint Venture for Carbon Capture Infrastructure | Rhine-Ruhr industrial cluster partnerships achieve economies of scale under EU Carbon Border Adjustment Mechanism pressure. |
| Geographic Expansion into Indian Industrial Corridors | PLI scheme procurement in Gujarat and Tamil Nadu creates localized demand for closed-loop water systems. |
| Green Chemistry Certification Program | REACH compliance acceleration reduces registration timeline friction for novel treatment chemistries in European markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving membrane plant engineers, municipal procurement directors, carbon capture project developers, and aftermarket service heads. EPA effluent databases, EU ETS transaction registries, China's MEE permit disclosures, and India PLI scheme beneficiary lists supplied quantitative anchors. Bottom-up equipment shipment analysis and top-down regulatory spend estimates were triangulated to constrain forecast variance.
Segment-level modeling tracked membrane replacement cycles, carbon capture retrofit deployment rates, and digital twin adoption curves across the projection horizon. Product dimensions included water treatment, air purification, waste management, and renewable energy systems. Application splits covered sustainable manufacturing, pollution control, agricultural efficiency, and e-waste recycling. Technology trajectories modeled carbon capture, green chemistry, biodegradation, and solar photovoltaic integration. CAGRs were derived from regression analysis against regulatory enforcement intensity and capital deployment timelines.
The model holds under stable regulatory enforcement and continued carbon pricing mechanism expansion; deviation in EPA guideline timing or EU ETS price collapse would shift replacement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Emission Monitoring Systems Market