
 Industrial Site Carbon Footprint Verification and Metering Test Equipment Market | 2026-2036
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market Insights
Market Context
Class A certification for continuous emissions monitoring systems is reorganizing procurement priorities across heavy industry. SGS leverages its accredited laboratory network to dominate third-party verification contracts in European metallurgy. Bureau Veritas anchors its position through backward integration into sensor calibration services. Intertek competes on multi-site audit efficiency, reducing plant downtime during compliance assessments.
Technical Definition and Segment Structure
Industrial site carbon footprint verification and metering test equipment comprises calibrated instrumentation for quantifying greenhouse gas fluxes, including nondispersive infrared spectroscopy gas analyzers with detection thresholds below one ppm and ultrasonic flow meters rated for stack temperatures exceeding 300 degrees Celsius. These systems enable regulatory compliance, carbon credit certification, and Scope 1 emissions disclosure for facility operators. Gas analyzers and emission monitors capture the dominant share of installed value, while data loggers represent the fastest-expanding category as facilities retrofit legacy point-source monitors with networked, time-stamped recording architectures. Infrared spectroscopy leads technology adoption for CO2 and methane quantification, though electrochemical sensors gain traction in distributed, low-concentration monitoring applications where capital cost sensitivity shapes procurement decisions.
Regulatory Frame and Outlook
The EU Green Deal's Carbon Border Adjustment Mechanism and the EPA's Greenhouse Gas Reporting Program create dual compliance obligations for multinational facility operators, directly stimulating equipment refresh cycles. China's MEE enforces GB 13271 emission standards with escalating penalties for data falsification, tightening sensor accuracy requirements. Stakeholders must monitor divergence between ISO 14064-3 verification protocols and emerging national carbon accounting standards to anticipate recertification costs and equipment obsolescence risks.
Market Dynamics
The EU Green Deal's Carbon Border Adjustment Mechanism is compressing compliance timelines for heavy industry operators, forcing simultaneous upgrades to verification protocols and metering infrastructure across multiple facility tiers.
Growth Catalysts
- Steel sector decarbonization mandates:German metallurgical plants now require ISO 14064-1 compliant verification protocols to qualify for transition credits under EU Green Deal frameworks.
- China's MEE enforcement escalation:Provincial environmental bureaus in the Yangtze River Delta mandate continuous emissions monitoring for facilities exceeding 26,000 tons CO2 equivalent annual output.
- Ultrasonic flow meter adoption:Stack temperature ratings above 300 degrees Celsius are driving replacement of thermal-based systems in cement and petrochemical operations.
Market Restraints
- Sensor calibration supply concentration:Accredited laboratory networks for NDIR analyzer certification concentrate in Germany and Switzerland, creating bottleneck risks for Asian deployments.
- Rare earth magnet volatility:Neodymium price swings directly impact electrochemical sensor manufacturing costs, compressing margins for distributed monitoring equipment.
- ISO 14064-3 divergence friction:Emerging national carbon accounting standards in India and Brazil are creating recertification uncertainty for multinational equipment vendors.
Strategic Opportunities
- India's PLI scheme for green technology:Domestic manufacturing incentives for emissions monitoring equipment are opening captive supply opportunities for sensor assembly operations.
- Data logger retrofit wave:Legacy point-source monitor replacement with networked, time-stamped recording architectures represents underpenetrated upgrade potential in North American pulp and paper facilities.
- CSRD-aligned verification services:Corporate Sustainability Reporting Directive scope expansion is creating bundled demand for calibration-plus-disclosure service models in European chemicals.
Industry Challenges
- NDIR spectroscopy technician scarcity:Specialized calibration expertise for sub-ppm detection thresholds remains concentrated among accredited European laboratory personnel.
- Multi-site audit coordination complexity:Synchronized compliance assessments across dispersed facility networks require sophisticated logistics to minimize production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Site Carbon Footprint Verification and Metering Test Equipment Market |
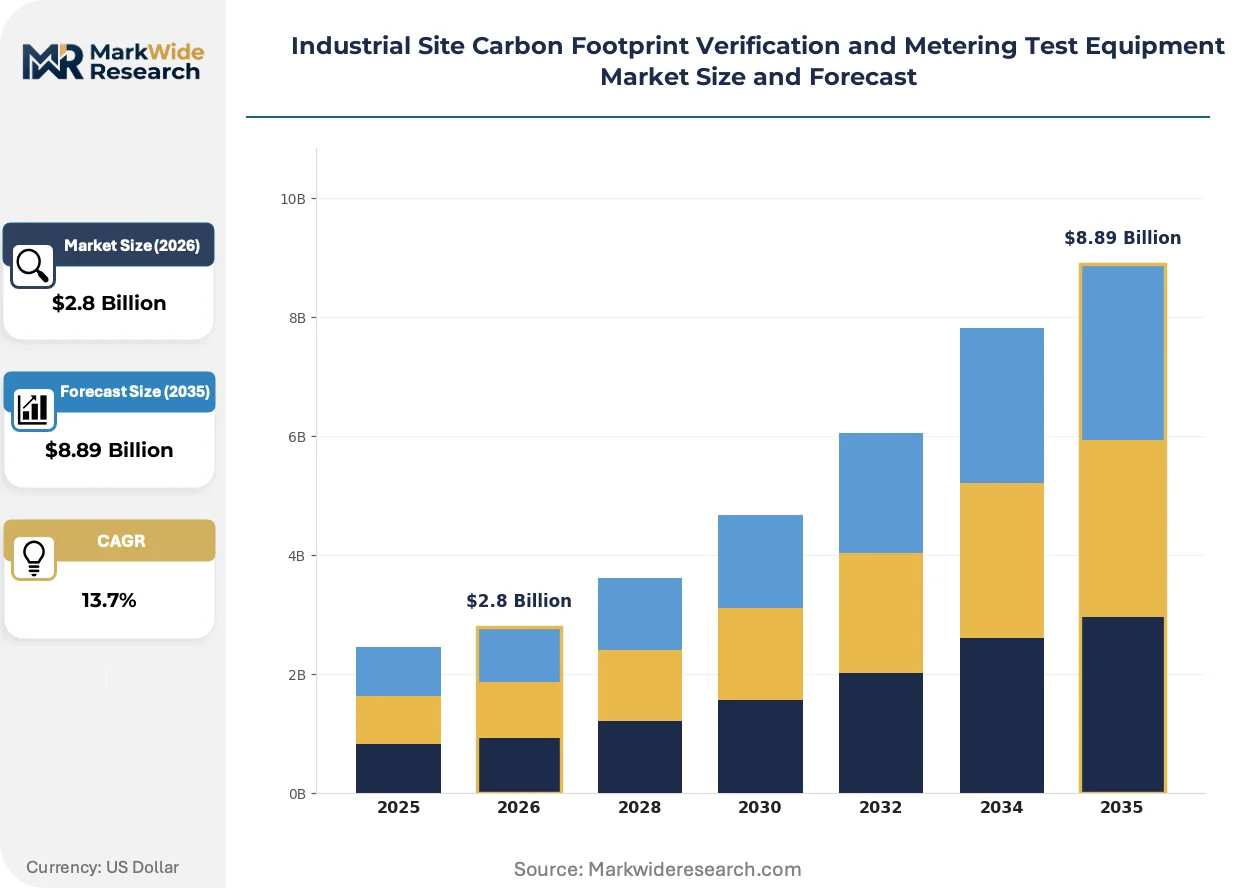
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Flow Meters, Data Loggers, Emission Monitors, Particulate Counters Technology: Infrared Spectroscopy, Ultrasonic, Electrochemical Sensors, Paramagnetic, Catalytic Bead Application: Power Generation, Waste Management Facilities, Manufacturing Plants, Mining Operations, Food Processing Units End User: Environmental Consultants, Industrial Equipment Suppliers, Energy Auditors, Laboratory Service Providers |
| Companies Covered | SGS, Bureau Veritas, Intertek, DNV, TÜV SÜD, UL Solutions, DEKRA, RINA, BSI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market Trends and Innovations
Continuous emissions monitoring architectures are fragmenting between high-precision centralized systems and distributed low-cost sensor networks, with procurement criteria diverging sharply by facility size and regulatory exposure.
Photonic integrated circuit gas analyzers are bifurcating the market for CO2 quantification equipment. Large integrated steel producers in Germany and Japan are adopting these systems for real-time stack monitoring. The technology is bifurcating vendor revenue pools between premium photonic platforms and legacy NDIR maintenance contracts.
China's MEE is escalating penalties for emissions data falsification under GB 13271 standards, compelling facility operators to deploy redundant sensor arrays with blockchain-anchored timestamping. Cement manufacturers in Shandong Province are responding fastest, integrating tamper-evident data loggers directly into provincial environmental bureau reporting systems.
Steel producers are unbundling calibration services from original equipment purchases, preferring third-party accredited laboratories over manufacturer-captive service contracts. This pattern disrupts traditional vendor lock-in models. German metallurgical clusters exhibit the most pronounced shift toward independent verification providers.
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market Segmentation
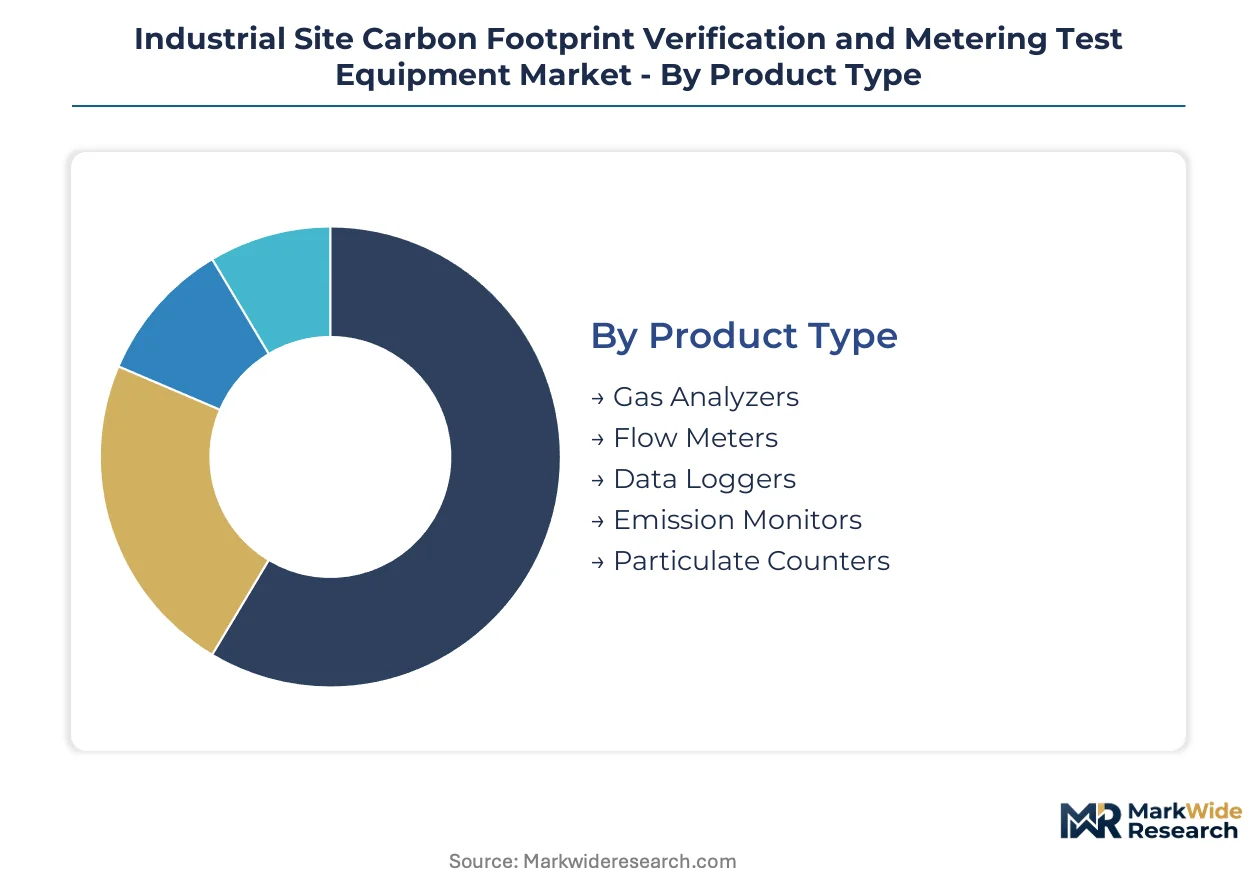
Equipment specification tiers diverge sharply between export-oriented heavy industry clusters and domestic compliance-driven procurement. Segmentation reveals how regulatory stringency in Germany, China, and India reshapes product mix priorities across supplier portfolios.
Product Type:
Export-led demand concentrates in high-precision gas analyzers and emission monitors for multinational steel and cement operators, while domestic procurement favors data loggers and flow meters for provincial compliance retrofit programs.
- Gas Analyzers:Nondispersive infrared spectroscopy systems with sub-ppm detection thresholds dominate German metallurgical verification protocols. Steel producers in the Ruhr Valley specify these units for ISO 14064-1 compliant stack monitoring under EU Green Deal transition credit frameworks.
- Flow Meters:Ultrasonic designs rated above 300 degrees Celsius are displacing thermal-based systems in cement and petrochemical stacks. Yangtze River Delta facilities mandate these units for continuous emissions monitoring above 26,000 tons CO2 equivalent annual output.
- Data Loggers:Networked, time-stamped recording architectures are expanding fastest in North American pulp and paper retrofits.
- Emission Monitors:Integrated sensor arrays serve Shandong Province cement manufacturers under GB 13271 enforcement escalation.
- Particulate Counters:Optical scattering instruments support mining dust management in Australian iron ore operations.
Gas analyzers hold the largest share; momentum sits with data loggers.
Technology:
Cost tiers separate premium photonic platforms from maintenance-dependent legacy systems, with electrochemical sensors occupying a mid-market position for distributed low-concentration applications.
- Infrared Spectroscopy:Standard for CO2 and methane quantification in European metallurgy. SGS-accredited laboratories calibrate these systems for third-party verification contracts.
- Ultrasonic:Stack temperature resilience drives adoption in Japanese integrated steel production.
- Electrochemical Sensors:Capital cost sensitivity shapes procurement for distributed monitoring where detection thresholds exceed one ppm.
- Paramagnetic:Oxygen measurement precision suits power generation flue gas analysis.
- Catalytic Bead:Combustible gas detection in mining ventilation systems.
Infrared spectroscopy commands premium pricing; electrochemical sensors are climbing the fastest on volume scale.
Application:
Customer type determines specification intensity, with power generation and manufacturing plants requiring continuous monitoring while waste management and mining favor periodic audit-grade equipment.
- Power Generation:Flue gas monitoring at coal and gas-fired plants drives demand for multi-gas analyzer arrays. Indian thermal power stations under CEA emission norms represent emerging volume.
- Manufacturing Plants:Steel, cement, and chemicals facilities in Germany and China anchor installed base for Class A certified continuous emissions monitoring systems.
- Waste Management Facilities:Landfill gas capture verification requires portable methane detection for environmental consultant audits.
- Mining Operations:Ventilation and fugitive emission monitoring in Australian and South African coal extraction.
- Food Processing Units:Biogas and refrigeration leak detection for Scope 1 disclosure.
Manufacturing plants anchor revenue; power generation offers steepest expansion trajectory.
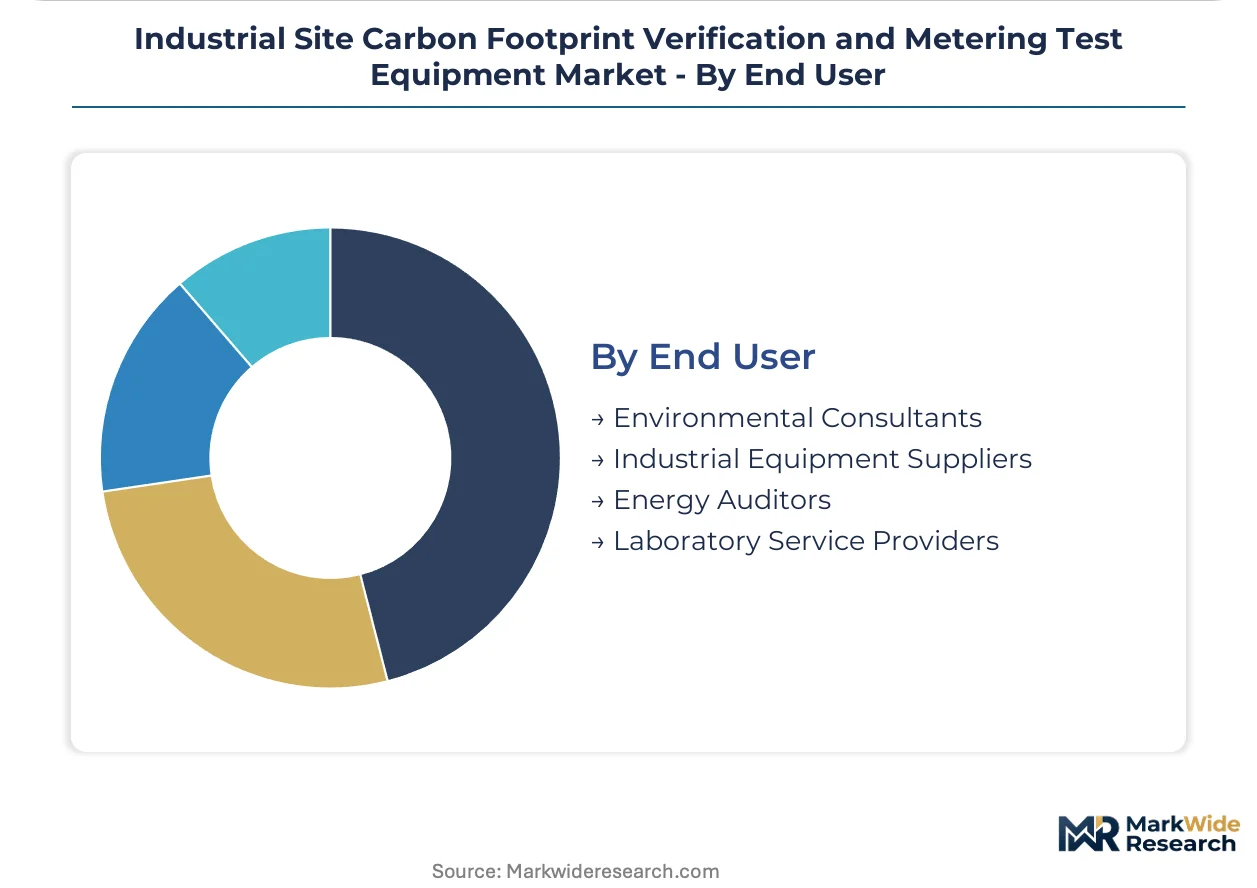
End User:
Procurement authority is fragmenting between in-house environmental teams and external service providers, with laboratory accreditation status becoming a decisive vendor selection filter.
- Environmental Consultants:Multi-site audit efficiency requirements favor portable, calibration-traceable equipment bundles. Intertek competes on reduced plant downtime during compliance assessments.
- Laboratory Service Providers:Backward integration into sensor calibration services anchors Bureau Veritas positioning in European third-party verification.
- Industrial Equipment Suppliers:Bundled sales of monitoring hardware with maintenance contracts.
- Energy Auditors:CSRD-aligned verification service demand in European chemicals.
Environmental consultants capture the largest engagement volume; laboratory service providers are gaining share fastest on CSRD scope expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Yangtze River Delta industrial corridor show the lowest price sensitivity, absorbing premium equipment for continuous emissions monitoring compliance. Indian steel producers under the PLI scheme for green technology exhibit acute capital cost sensitivity, driving electrochemical sensor procurement. German metallurgical clusters occupy the middle ground, prioritizing ISO 14064-1 certification over absolute cost minimization.
Germany
Ruhr Valley steel producers mandate Class A certified continuous emissions monitoring systems for EU Green Deal transition credit eligibility. The KBA and federal environmental regulators enforce ISO 14064-1 verification protocols through accredited laboratory networks. Bavarian chemical clusters are deploying redundant sensor arrays to preempt CBAM compliance penalties.
China
Provincial environmental bureaus in the Yangtze River Delta enforce GB 13271 standards with escalating penalties for data falsification. The MEE mandates continuous emissions monitoring for facilities exceeding 26,000 tons CO2 equivalent annual output. Shandong Province cement manufacturers integrate blockchain-anchored data loggers directly into provincial reporting systems.
United States
EPA Greenhouse Gas Reporting Program obligations force simultaneous compliance upgrades across multinational facility networks. The IRA's industrial decarbonization incentives accelerate equipment refresh cycles in Gulf Coast petrochemical corridors. Texas and Louisiana refineries are replacing thermal-based flow meters with ultrasonic designs rated above 300 degrees Celsius.
India
Steel producers under the PLI scheme for green technology drive domestic manufacturing incentives for emissions monitoring equipment. The CEA enforces emission norms at thermal power stations, creating emerging volume for multi-gas analyzer arrays. Gujarat and Maharashtra industrial corridors favor distributed electrochemical sensors where capital cost sensitivity shapes procurement.
Japan
METI industrial decarbonization roadmaps push integrated steel producers toward real-time stack monitoring architectures. JIS standards certification requirements filter vendor selection for precision instrumentation. Chubu and Kansai manufacturing belts adopt photonic integrated circuit gas analyzers for premium CO2 quantification applications.
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with accredited verification laboratories commanding premium positioning while Asian sensor manufacturers compete on unit economics. The market structures around three tiers: multinational testing-inspection-certification conglomerates with captive calibration networks, specialized emissions monitoring equipment fabricators, and regional system integrators serving provincial compliance programs. Dominant competitive moves include backward integration into sensor calibration services and multi-site audit efficiency optimization to reduce plant downtime.
Among European-based testing-inspection-certification conglomerates, SGS, Bureau Veritas, and Intertek exemplify distinct strategic positioning archetypes. SGS occupies the accredited laboratory network tier, leveraging third-party verification contracts to anchor presence in metallurgical clusters. Bureau Veritas sits within the backward integration archetype, controlling sensor calibration services to tighten service bundling. Intertek represents the audit efficiency optimization tier, competing on reduced production downtime during multi-site compliance assessments. These three entities collectively illustrate how certification authority, service integration depth, and operational logistics differentiate positioning in verification-dependent procurement.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Intertek |
| DNV |
| TÜV SÜD |
| UL Solutions |
| DEKRA |
| RINA |
| BSI Group |
| Others |
Pricing and Supply Chain Analysis
ISO 14064-1 certification requirements gate both supplier qualification and price differentiation simultaneously, as only accredited laboratory networks in Germany and Switzerland can calibrate sub-ppm NDIR analyzers for EU Green Deal compliance. This dual-gating mechanism compresses margins for non-accredited Asian manufacturers while enabling European verification conglomerates to command service premiums through backward integration into sensor calibration.
Pricing Analysis
After-sales calibration contracts and extended verification service agreements drive lifetime value more than equipment sales alone. Three-tier pricing structure across premium photonic platforms, standard NDIR systems, and economy electrochemical sensors reflects certification grade and detection threshold differentiation. Cost compression in the electrochemical tier is intensifying because neodymium magnet price volatility feeds directly into distributed sensor manufacturing. Indian steel producers under the PLI scheme exhibit the highest price sensitivity, while Yangtze River Delta facilities absorb premium equipment for MEE-mandated compliance.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for German and Swiss laboratory equipment destined for Asian deployment. Manufacturing concentration centers on Germany, Switzerland, and China, with sensor fabrication drawing from rare earth processing in China and precision optics in Japan. Single-source vulnerability in accredited calibration laboratory capacity creates bottleneck risks for NDIR analyzer certification. Distribution runs through regional system integrators serving provincial environmental bureaus, with direct procurement by multinational testing-inspection-certification conglomerates for metallurgical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic integrated circuit gas analyzers threaten incumbent NDIR maintenance revenue streams, forcing established players to defend substitution through service bundling and certification authority. Incumbents must navigate this technology transition while preserving calibration contract retention.
For Market Incumbents: Secure accredited laboratory network expansion in Asia to relieve calibration bottlenecks and defend against regional sensor manufacturers. Deepen backward integration into blockchain-anchored data logger architectures to capture Shandong Province cement manufacturer demand under GB 13271 enforcement escalation.
For New Entrants and Emerging Players: Lead with portable methane detection bundles for environmental consultants serving waste management audit contracts, the least penetrated application tier. Target North American pulp and paper data logger retrofits where legacy point-source monitor replacement demand runs ahead of established vendor capacity.
For Investors and Strategic Acquirers: EU Green Deal CBAM implementation reshapes the acquisition landscape toward verification service providers with multi-site audit logistics capabilities. Long-term viability hinges on CSRD-aligned disclosure service bundling. Acquire laboratory service providers with SGS-equivalent accreditation density. Watch for MEE penalties escalation in China as the signal for redundant sensor array deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Services | Bureau Veritas anchors European metallurgical positioning through sensor certification control. |
| Photonic Platform Adoption | German and Japanese steel producers deploy real-time stack monitoring for premium CO2 quantification. |
| Blockchain-Anchored Data Logger Deployment | Shandong cement manufacturers integrate tamper-evident architectures into MEE reporting systems. |
| Multi-Site Audit Efficiency Optimization | Intertek reduces plant downtime during synchronized compliance assessments across dispersed networks. |
| Regional System Integrator Partnership | Yangtze River Delta provincial bureaus mandate continuous monitoring through local deployment channels. |
Research Methodology
Cross-validation between primary interviews with plant engineers, environmental compliance officers, aftermarket service heads, and OEM procurement teams anchors the qualitative findings against secondary validation through EPA Greenhouse Gas Reporting Program filings, EU ETS registry data, China MEE enforcement bulletins, and SEC 10-K disclosures from testing-inspection-certification conglomerates. Bottom-up equipment shipment tracking and top-down regulatory mandate sizing triangulate market scope across the analysis window.
Sensitivity analysis on enforcement intensity and technology substitution rates shapes the analytical framework across product type, technology tier, application intensity, and end-user procurement authority dimensions throughout the forecast period. CAGRs derive from segment-level equipment refresh cycle modeling and compliance deadline clustering. Industry-specific inputs include GB 13271 penalty escalation schedules and EU CBAM phase-in timelines.
Forecasts assume regulatory continuity in EU Green Deal frameworks, EPA reporting obligations, and China MEE enforcement; material policy shifts would require re-modeling. Neodymium price volatility and ISO 14064-3 divergence in India and Brazil represent specific revision risks. Practitioners should keep alternative scenarios live as national carbon accounting standard fragmentation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Latin America Cloud Seeding Market