
 US Cloud Seeding Market | 2026-2036
US Cloud Seeding Market Size, Share, and Industry Trends Forecast 2026-2036
US Cloud Seeding Market Insights
Subscription-based flight-hour contracts for aircraft-based seeding operations is recalibrating how water agencies procure atmospheric modification services. Weather Modification Inc. leverages its fleet of dedicated seeding aircraft to dominate the Mountain West corridor. North America Weather Consultants Inc. anchors its position through long-term service agreements with municipal water districts. Cloud Seeding Technologies differentiates by integrating real-time radar analytics into its operational platforms.
Cloud seeding deploys hygroscopic flares or silver iodide generators to induce precipitation from supercooled cloud formations, typically operating at altitudes between 15,000 and 25,000 feet to optimize ice nucleation efficiency. The technology serves primarily to augment surface water supplies in arid and semi-arid watersheds where conventional reservoir management proves inadequate. Aircraft-based delivery systems command the largest operational share due to their mobility across complex terrain and ability to target specific storm cells. Snowpack augmentation applications are expanding fastest as ski resort operators and water utilities jointly fund winter storm interception programs. Ground-based generator networks retain relevance in fixed watershed protection zones where continuous operation outweighs mobility requirements.
The Bureau of Reclamation and individual state environmental quality agencies shape operational permitting, while FAA regulations govern flight corridors and cloud-base minimums for seeding aircraft. EPA oversight of silver iodide deposition thresholds influences material selection and post-operation monitoring protocols. Stakeholders must track evolving state-level atmospheric water rights frameworks and their intersection with existing prior-appropriation doctrine.
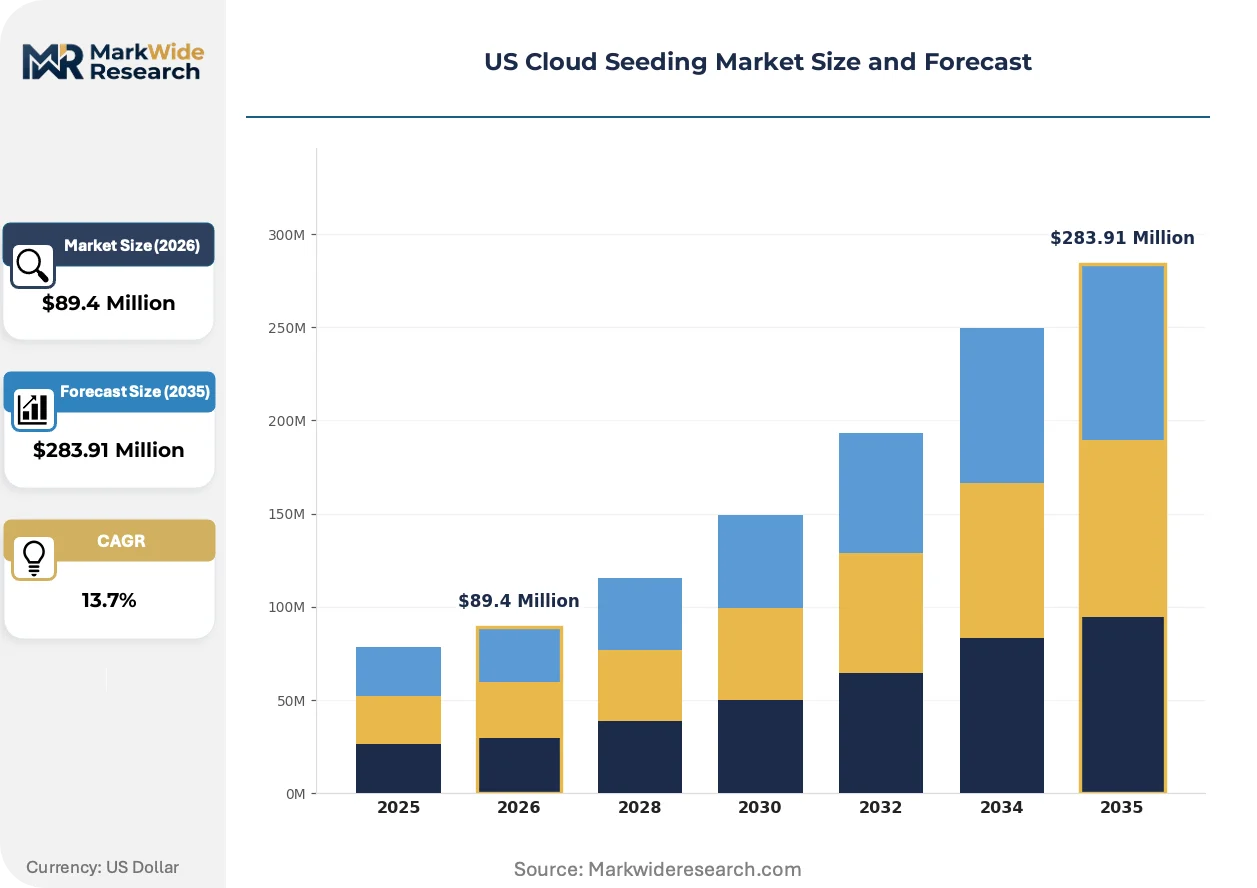
Market Dynamics
Subscription-based flight-hour contracts for aircraft-based seeding operations are recalibrating how water agencies procure atmospheric modification services, shifting capital expenditure to operational expenditure models.
Growth Catalysts
- Bureau of Reclamation Drought Response Programs:Federal funding mechanisms accelerate adoption across Western watersheds facing chronic snowpack deficits.
- California Agricultural Irrigation Stress:Permanent crop operators in the Central Valley fund winter storm interception to secure summer surface water allocations.
- Hygroscopic Flare Technology:Next-generation combustion systems improve ice nucleation efficiency at warmer cloud temperatures than legacy silver iodide generators.
Market Restraints
- Silver Iodide Cost Volatility:Precursor chemical supply concentrates among specialty iodine processors, exposing operators to input price swings.
- Prior-Appropriation Doctrine Friction:State-level atmospheric water rights frameworks remain unsettled, creating legal uncertainty for cross-basin seeding operations.
- Ground-Based Generator Substitution:Fixed-site systems in protected watershed zones compete for municipal contracts at lower per-acre operational cost.
Strategic Opportunities
- Idaho Backcountry Snowpack Augmentation:Underpenetrated mountain drainage districts present expansion targets for joint utility-ski resort funding models.
- Real-Time Radar Analytics Convergence:Integration of dual-polarization weather radar with automated flare-dispersion systems enables precision targeting of supercooled liquid water layers.
- Colorado State Atmospheric Water Management Policies:Legislative mandates for drought contingency planning create procurement tailwinds for multi-year service agreements.
Industry Challenges
- Ice Nucleation Physicist Talent Scarcity:Specialized atmospheric science expertise required for operational forecasting and seeding efficacy assessment outpaces academic pipeline output.
- FAA Flight Corridor Certification Timelines:Extended approval processes for new cloud-base minimums and terrain-following routes delay contract commencement in complex topography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cloud Seeding Market |
| Market Size in 2026 | $89.4 Million |
| Market Size in 2035 | $283.91 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ground-Based, Aircraft-Based, Laser, Rocket-Delivered Application: Agricultural Enhancement, Drought Mitigation, Snowpack Augmentation, Water Resource Management End User: Agricultural Sector, Government Agencies, Utilities, Environmental Organizations Deployment Model: On-Demand, Pre-Planned, Pilot Programs, Experimental Trials |
| Companies Covered | Weather Modification Inc., RHS Consulting Inc., North America Weather Consultants Inc., Cloud Seeding Technologies, Ice Crystal Engineering LLC, Seeding Operations and Atmospheric Research (SOAR), Aquiess Inc., Atmospherics Inc., AFJets Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cloud Seeding Market Trends and Innovations
Operational platforms are embedding predictive analytics to transform cloud seeding from reactive storm interception into pre-positioned atmospheric water harvesting.
Dual-polarization weather radar systems are overtaking single-polarization legacy installations as the standard for seeding operations. Water utilities in the Colorado River basin deploy these systems to identify supercooled liquid water depth and horizontal extent before aircraft launch. This capability compresses decision-to-dispersion timelines from hours to minutes.
EPA oversight of silver iodide deposition thresholds is tightening material selection protocols. Operators face expanded post-operation monitoring requirements for soil and surface water silver concentrations. Agricultural irrigation districts in California are responding by piloting hygroscopic salt-based alternatives to reduce regulatory exposure.
Joint-funding consortiums between municipal water districts and ski resort operators are displacing single-payer contracts as the dominant procurement structure. These arrangements distribute operational risk across multiple beneficiaries with divergent seasonal water needs. The model is most visible in the Mountain West corridor where summer irrigation and winter recreation interests overlap geographically.
US Cloud Seeding Market Segmentation
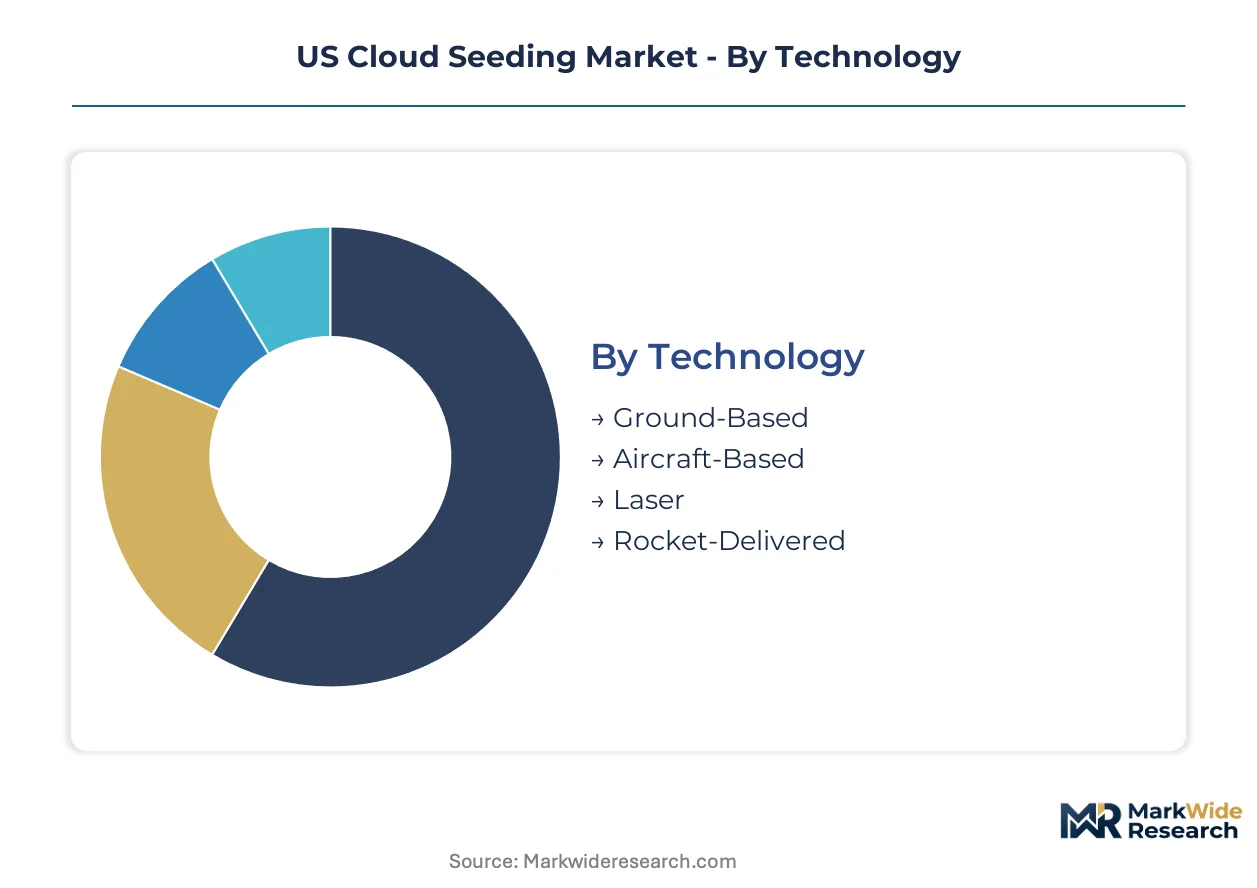
Technology choice in cloud seeding determines capital intensity, operational flexibility, and regulatory exposure for water agencies across the Western states. Segmentation reveals how delivery mechanisms and deployment models align with specific drought response budgets and watershed geometries.
Technology:
Supply concentration in aircraft-based systems has concentrated vendor capabilities among specialized aviation operators with FAA-certified seeding fleets.
- Aircraft-Based:Fixed-wing and rotary platforms deploy hygroscopic flares or silver iodide generators at altitudes between 15,000 and 25,000 feet, targeting supercooled cloud layers with precision mobility. Demand clusters in California's Sierra Nevada and Colorado's Continental Divide where complex terrain demands storm-cell tracking across multiple watersheds. FAA flight corridor certifications and extended terrain-following route approvals create operational bottlenecks that favor incumbent operators with established airspace relationships.
- Ground-Based:Fixed-site generator networks burn silver iodide solution or acetone-based formulations, releasing nucleating particles into orographic cloud systems via prevailing wind transport. Idaho's backcountry drainage districts and protected watershed zones in the Mountain West favor these systems for continuous operation at lower per-acre cost than aircraft alternatives. Ground installations face fewer FAA constraints but require extensive land access agreements and face substitution pressure from mobile platforms.
- Laser:Directed energy systems ionize air channels to promote condensation without chemical dispersants, eliminating EPA silver deposition monitoring requirements.
- Rocket-Delivered:Artillery-launched payloads carry seeding agents into convective cloud formations, restricted primarily to experimental trials and military-coordinated operations.
Today's leader: Aircraft-Based. Tomorrow's challenger: Laser.
Application:
Cost tier differentiation separates capital-intensive snowpack programs from lower-budget agricultural enhancement contracts.
- Snowpack Augmentation:Winter storm interception targets orographic precipitation enhancement to build reservoir inflows and ski resort viability, commanding the highest operational expenditure per treated acre. Joint-funding consortiums between municipal water districts and ski resort operators in Colorado and California concentrate demand here, with multi-year service agreements replacing single-payer structures. Dual-polarization radar integration enables real-time supercooled liquid water identification, compressing decision-to-dispersion timelines.
- Agricultural Enhancement:Central Valley permanent crop operators fund winter cloud seeding to secure summer surface water allocations for almond, pistachio, and grape irrigation. California Agricultural Irrigation Stress programs channel drought response funding toward these operations, though EPA silver iodide deposition thresholds are driving pilot adoption of hygroscopic salt-based alternatives.
- Drought Mitigation:Emergency-triggered seeding operations activate during declared water shortage emergencies.
- Water Resource Management:Systematic atmospheric water harvesting integrates with reservoir operations and aquifer recharge planning.
Expanding most quickly: Snowpack Augmentation. Consolidating share: Agricultural Enhancement.
End User:
Customer type determines contract duration, risk allocation, and regulatory compliance burden.
- Utilities:Municipal water districts and regional water authorities anchor procurement volume with multi-year atmospheric water management agreements. Colorado State legislative mandates for drought contingency planning create procurement tailwinds, while Bureau of Reclamation funding mechanisms accelerate adoption across Western watersheds.
- Government Agencies:Federal and state drought response programs provide capital subsidies and operational grants.
- Agricultural Sector:Irrigation districts and permanent crop operators fund targeted storm interception.
- Environmental Organizations:Conservation groups underwrite experimental trials and efficacy monitoring.
Primary volume anchor: Utilities. Emerging contract source: Environmental Organizations.
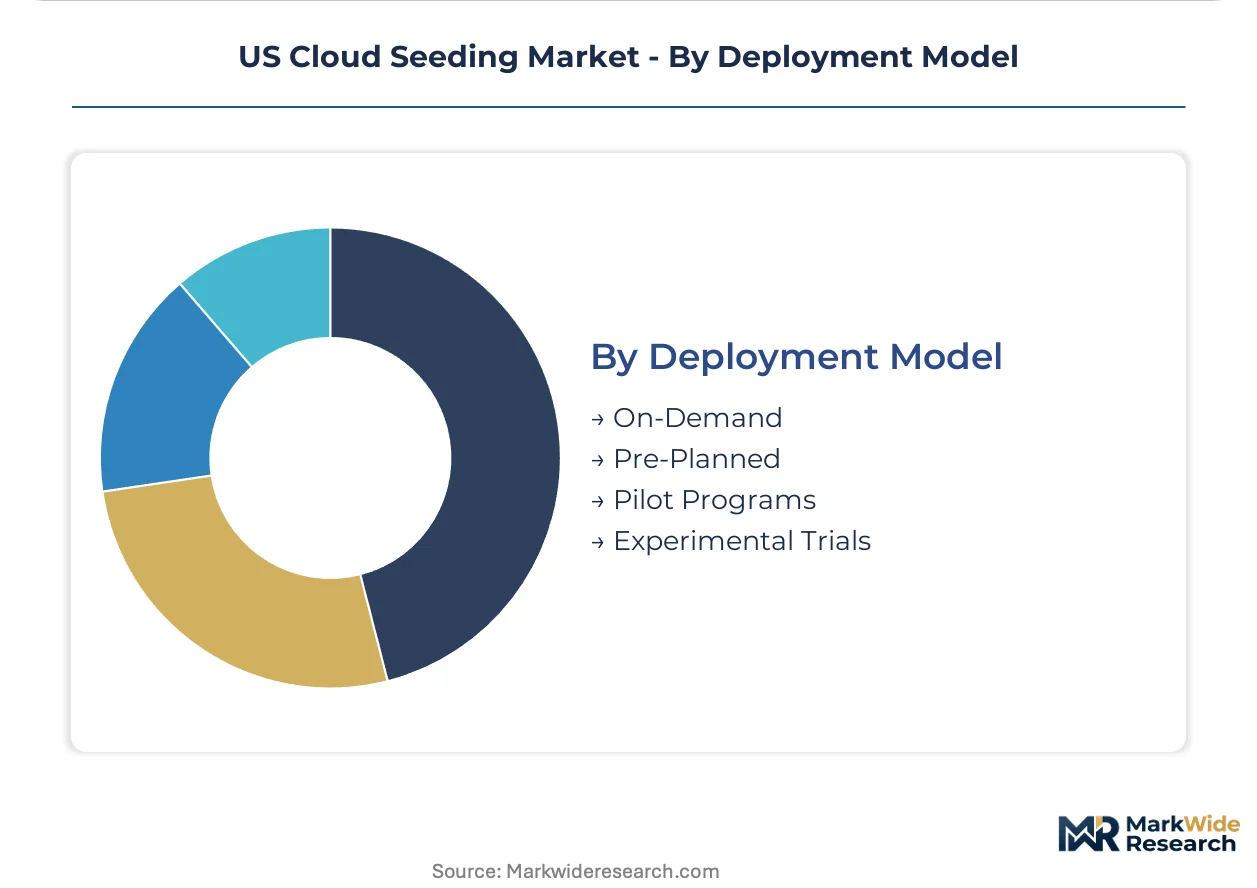
Deployment Model:
Maturity gradients separate established pre-planned programs from experimental validation efforts.
- Pre-Planned:Annual subscription contracts with fixed flight-hour minimums and ground generator maintenance schedules dominate the Mountain West corridor. Weather Modification Inc. and North America Weather Consultants Inc. structure these arrangements to shift water agency capital expenditure to operational expenditure models.
- On-Demand:Storm-triggered activation without annual commitments serves smaller districts with irregular precipitation patterns.
- Pilot Programs:Limited-duration trials validate seeding efficacy in new watersheds before scaling.
- Experimental Trials:Research-oriented operations test novel delivery mechanisms or nucleating agents.
Contract standard: Pre-Planned. Innovation pathway: Experimental Trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California deploys aircraft-based seeding fleets across the Sierra Nevada while Colorado concentrates on Continental Divide snowpack programs, revealing how terrain complexity shapes operational priorities across Western states.
California
Central Valley permanent crop operators and municipal water districts jointly fund winter storm interception to secure summer surface water allocations. The State Water Resources Control Board coordinates with Bureau of Reclamation drought response programs to channel federal funding into atmospheric water management. Los Angeles Department of Water and Power and agricultural irrigation districts in the San Joaquin Valley anchor procurement volume for multi-year service agreements.
Colorado
Ski resort operators and Front Range water utilities share operational costs for snowpack augmentation targeting reservoir inflows. State legislative mandates for drought contingency planning create procurement tailwinds for atmospheric modification services. Denver Water and Colorado River basin districts concentrate demand in the Continental Divide region where complex terrain demands storm-cell tracking across multiple watersheds.
Idaho
Backcountry drainage districts present expansion targets for joint utility-recreation funding models in underpenetrated mountain watersheds. The Idaho Department of Water Resources oversees permitting for ground-based generator networks in protected zones. Boise-based water utilities and Sawtooth Mountain irrigation districts favor fixed-site systems for continuous operation at lower per-acre cost than aircraft alternatives.
Nevada
Lake Tahoe basin water agencies and Truckee Meadows utilities fund seeding operations to augment dwindling snowpack reserves feeding the Colorado River system. Nevada Division of Environmental Protection monitors silver iodide deposition thresholds under EPA oversight. Reno-area atmospheric water management programs concentrate in the eastern Sierra watershed where orographic enhancement targets critical reservoir inflows.
US Cloud Seeding Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dedicated aviation operators commanding premium positioning in complex terrain markets while ground-based system integrators compete on operational cost. The vendor landscape concentrates around FAA-certified fleet operators and long-term service agreement specialists. Three archetypes dominate: aircraft-based seeding fleet operators, ground-based generator network providers, and radar-analytics platform integrators. Competitive moves center on multi-year municipal contract capture and dual-polarization weather radar technology licensing.
Among Mountain West aviation specialists, Weather Modification Inc. and North America Weather Consultants Inc. exemplify the dedicated fleet operator archetype, anchoring positions through established airspace relationships and terrain-following route certifications. Cloud Seeding Technologies occupies a position within the analytics-integrated tier, representing vendors that converge real-time radar capabilities with automated dispersion systems. These three entities illustrate how operational specialization—aviation certification depth versus sensor platform development—determines competitive positioning in atmospheric water procurement.
| Leading Market Players |
|---|
| Weather Modification Inc. |
| RHS Consulting Inc. |
| North America Weather Consultants Inc. |
| Cloud Seeding Technologies |
| Ice Crystal Engineering LLC |
| Seeding Operations and Atmospheric Research (SOAR) |
| Aquiess Inc. |
| Atmospherics Inc. |
| AFJets Sdn Bhd |
| Others |
Pricing and Supply Chain Analysis
Backward integration into dedicated aviation fleets anchors both operational capacity and pricing power for established cloud seeding operators, creating barriers that subscription-based contracts reinforce through multi-year municipal commitments.
Pricing Analysis
Capacity additions in Idaho and Nevada are reshaping price floors as new ground-based generator networks compete for municipal contracts against incumbent aircraft operators. Three-tier pricing structure across premium flight-hour subscriptions, standard ground-generator leases, and economy on-demand activations reflects FAA certification depth and radar analytics bundling. Pricing pressure stems from silver iodide precursor volatility and hygroscopic flare technology substitution. Agricultural irrigation districts exhibit highest price sensitivity due to seasonal cash flow constraints, while ski resort-water utility consortiums absorb premium tiers for snowpack reliability.
Supply Chain Analysis
Regional distribution centers in Denver and Boise orchestrate hub-and-spoke patterns for hygroscopic flares and silver iodide acetone solutions, feeding both mobile aircraft operations and fixed generator installations. Supply concentrates among Japanese and Chilean iodine processors for silver iodide precursors, with domestic flare combustion system fabrication anchored in Texas and Arizona manufacturing clusters. Raw material dependencies span specialty iodine chemicals, aircraft-grade acetone formulations, and dual-polarization radar components. Single-source vulnerability in iodine precursor supply creates exposure to commodity price swings. Distribution runs through Bureau of Reclamation procurement channels and state atmospheric water management programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
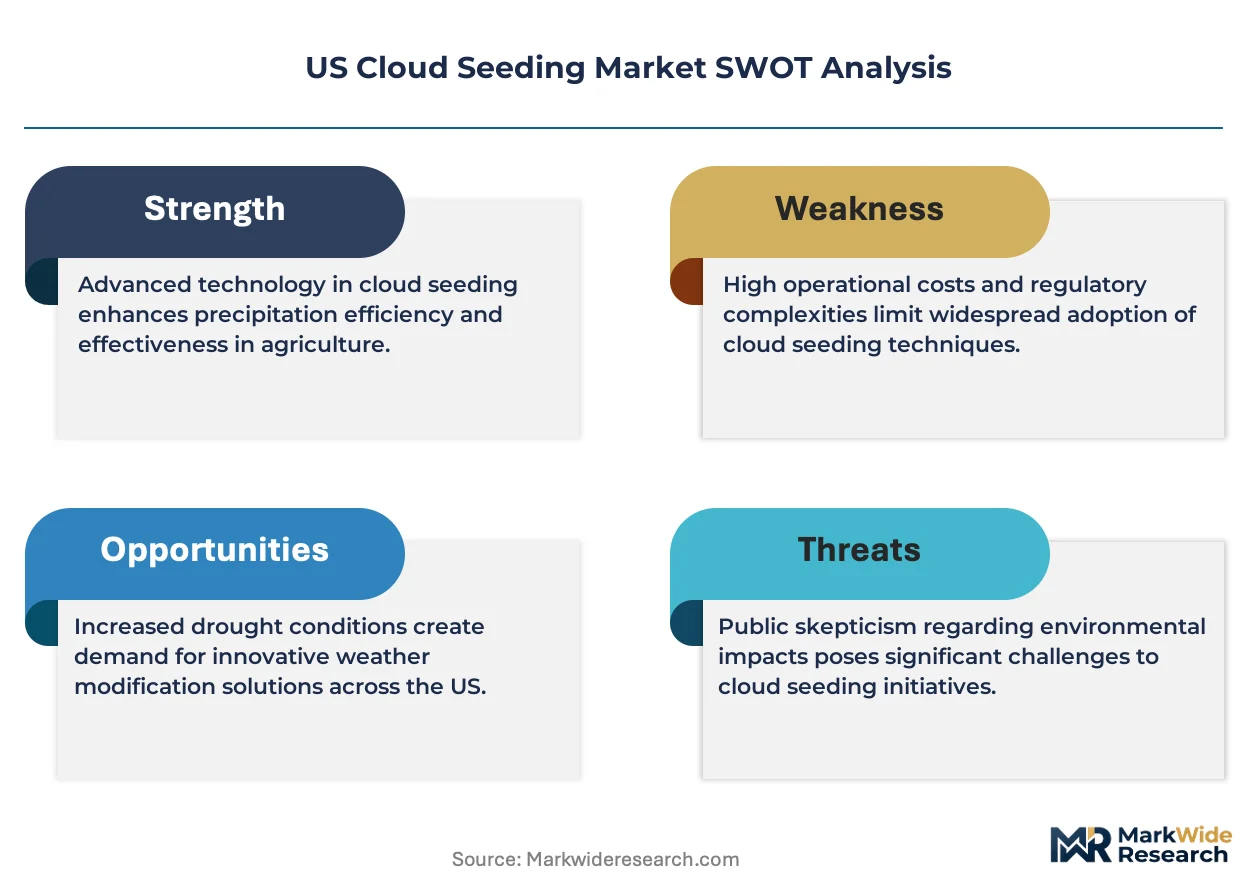
Margin expansion in cloud seeding rests on technology substitution toward hygroscopic salt-based alternatives that reduce EPA compliance costs while commanding premium positioning in California agricultural districts.
For Market Incumbents: Deploy dual-polarization radar licensing as a defensive moat against analytics-integrated challengers, while deepening captive aviation maintenance capabilities to compress flight-hour delivery costs. Laser-based seeding technology from experimental trials threatens silver iodide incumbents with elimination of deposition monitoring burdens. FAA terrain-following route certifications constitute a lever that entrenched operators can weaponize to delay contract commencement for new entrants. For New Entrants and Emerging Players: Launch via joint-funding consortium structures that distribute operational risk across municipal water districts and ski resort operators, bypassing incumbent airspace relationships. Idaho backcountry drainage districts and Nevada eastern Sierra watersheds represent the most penetrable geographies due to underdeveloped ground-based generator networks. Precision targeting of supercooled liquid water layers through automated flare-dispersion systems offers a go-to-market angle that differentiates against legacy manual operations. For Investors and Strategic Acquirers: Roll-up economics work for analytics-integrated regional specialists because FAA certification backlogs and ice nucleation physicist scarcity prevent rapid organic scaling by national platforms. Five-to-ten year viability hinges on state atmospheric water rights framework consolidation that clarifies cross-basin operational legality. Acquisition targets should display established Bureau of Reclamation contract relationships and dual-use ski resort-municipal funding structures. Colorado legislative mandate expansion serves as the signal to watch for inflection in multi-year service agreement procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aviation Maintenance | Captive MRO capabilities compress flight-hour costs and accelerate FAA certification timelines. |
| Dual-Polarization Radar Platform Licensing | Real-time supercooled liquid water identification differentiates precision targeting against legacy operators. |
| Hygroscopic Salt-Based Technology Transition | EPA silver deposition threshold avoidance reduces regulatory exposure in California agricultural districts. |
| Joint-Funding Consortium Structuring | Risk distribution across ski resort and municipal beneficiaries expands addressable contract value per watershed. |
| Idaho-Nevada Geographic Expansion | Underpenetrated backcountry drainage districts offer first-mover positioning before incumbent airspace saturation. |
Research Methodology
Multiple input streams — operational flight-hour databases, Bureau of Reclamation drought program disbursement records, and state atmospheric water management policy filings — were reconciled against primary interviews with water utility planning officers, FAA flight operations inspectors, agricultural irrigation district managers, and cloud seeding program meteorologists. Secondary validation drew from EPA silver deposition monitoring reports, Colorado River basin hydrological surveys, and Sierra Nevada snowpack telemetry archives. Bottom-up contract value aggregation and top-down atmospheric water management budget allocation triangulation anchored market size estimation.
Cross-referencing historical seeding operation efficacy studies against panel input from ice nucleation physicists and radar systems engineers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery technology, application purpose, end-user type, and deployment maturity tier, with geographic watershed complexity and FAA regulatory cluster as industry-specific stratifiers. CAGRs were derived through elasticity analysis of drought contingency funding against snowpack deficit severity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prior-appropriation doctrine litigation and silver iodide supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Food Security Technology Market