
 Hemoglobin Testing Devices Market | 2026-2036
Hemoglobin Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobin Testing Devices Market Analysis
China is reconfiguring hemoglobin testing device supply chains through expanded domestic manufacturing of optical and electrochemical components. Abbott leverages its channel density in hospital systems to sustain installed-base expansion across North American acute care settings. Thermo Fisher Scientific Inc. anchors its position through R&D intensity in spectrophotometric platforms for centralized laboratory workflows. Siemens Healthineers AG competes by integrating hemoglobin modules into broader hematology automation lines, reducing footprint and technician handling steps.
Hemoglobin testing devices quantify hemoglobin concentration in whole blood through colorimetric, electrochemical, spectrophotometric, or optical detection principles, typically reporting results in grams per deciliter with precision thresholds governed by Clinical and Laboratory Standards Institute protocols. These instruments serve diagnostic screening, chronic disease monitoring, transfusion trigger verification, and clinical research endpoints where rapid hematocrit proxy data supports therapeutic decisions. Point-of-care analyzers command the largest revenue pool due to emergency department throughput demands, while handheld devices represent the fastest-expanding category as homecare and remote monitoring protocols gain reimbursement traction. Laboratory analyzers retain margin concentration in high-volume reference settings where throughput and multi-parameter integration justify capital intensity.
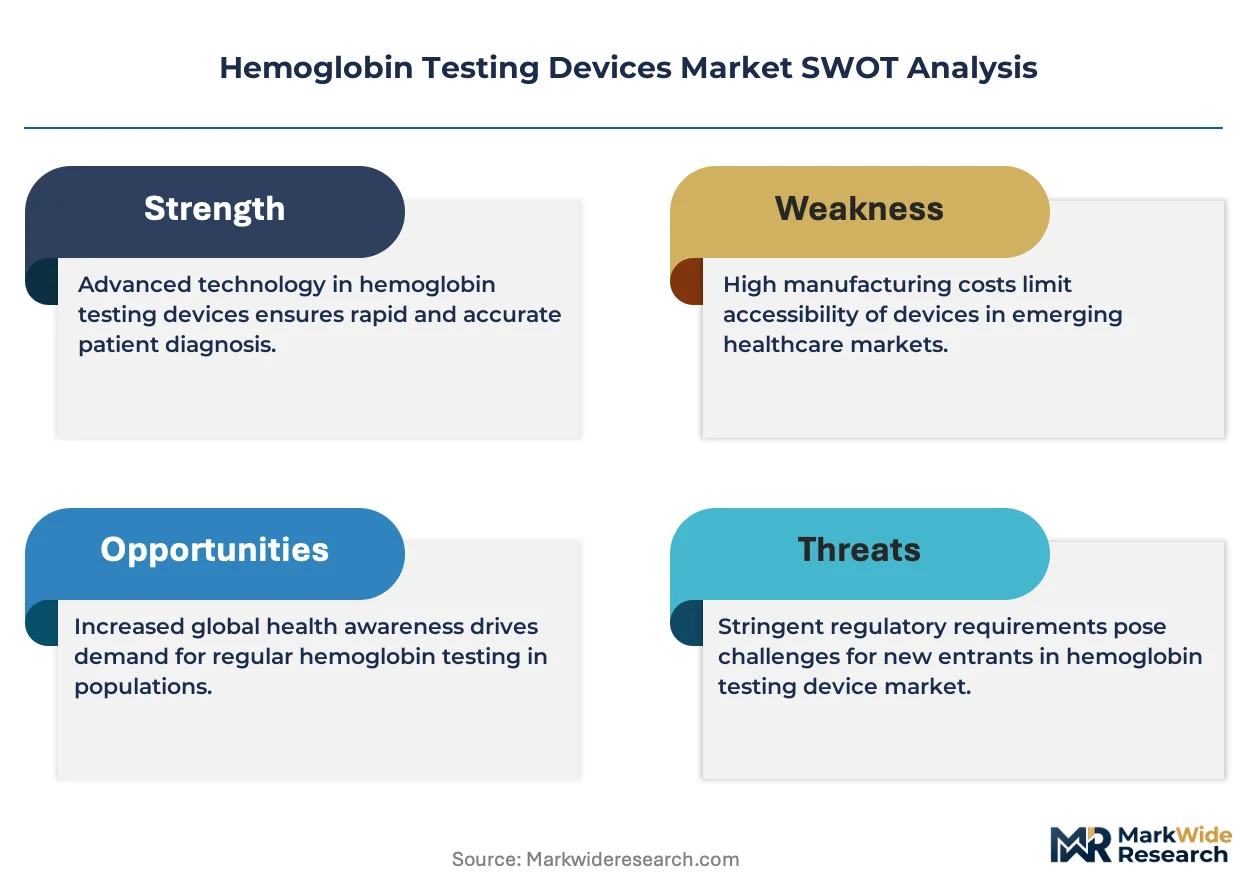
The FDA's In Vitro Diagnostics regulatory framework and Clinical Laboratory Improvement Amendments shape product development timelines and analytical performance claims for devices entering the US market. ISO 15189 accreditation requirements and EU In Vitro Diagnostic Regulation conformity assessments in Europe add compliance layers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving homecare reimbursement codes and decentralized testing liability frameworks as care delivery shifts beyond traditional laboratory walls.
Market Dynamics
Point-of-care testing migration from centralized laboratories to emergency departments and ambulatory settings is compressing turnaround times and rewiring procurement authority toward clinical department budgets rather than laboratory capital committees.
Growth Catalysts
- CLIA-waived test expansion:The FDA's Clinical Laboratory Improvement Amendments waiver pathway accelerates point-of-care hemoglobin analyzer deployment in physician offices and community health centers across the United States.
- Electrochemical sensor miniaturization:Solid-state electrode fabrication advances enable handheld device manufacturers to achieve laboratory-grade precision without optical component complexity.
- Anemia screening protocols:WHO maternal health guidelines mandate universal hemoglobin screening in antenatal care, institutionalizing demand in low-resource clinic networks.
Market Restraints
- Optical component supply concentration:Precision photodiode and filter manufacturing concentrates in East Asian foundries, exposing device assemblers to single-source fragility.
- Reimbursement code fragmentation:CMS and private payor coding inconsistencies across point-of-care versus laboratory settings create revenue recognition uncertainty for hospital procurement committees.
- Whole blood viscosity variability:Capillary sampling technique inconsistency introduces measurement error that spectrophotometric methods cannot algorithmically correct.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled handheld analyzers connect to chronic kidney disease management platforms, opening subscription revenue streams beyond device sales.
- Indian diagnostic network expansion:Ayushman Bharat health and wellness centers require village-level anemia screening infrastructure at price points below current import tariffs.
- Spectrophotometric-AI convergence:Machine learning interpretation of full absorbance spectra enables multi-analyte panels from single hemoglobin cuvettes, differentiating premium platform offerings.
Industry Challenges
- CLIA compliance staffing:Point-of-care operators require documented proficiency testing that hospital laboratory directors struggle to administer across decentralized device fleets.
- Legacy hematology line integration:Automated cell counter manufacturers resist open connectivity protocols that would allow third-party hemoglobin modules to displace their integrated chemistry stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobin Testing Devices Market |
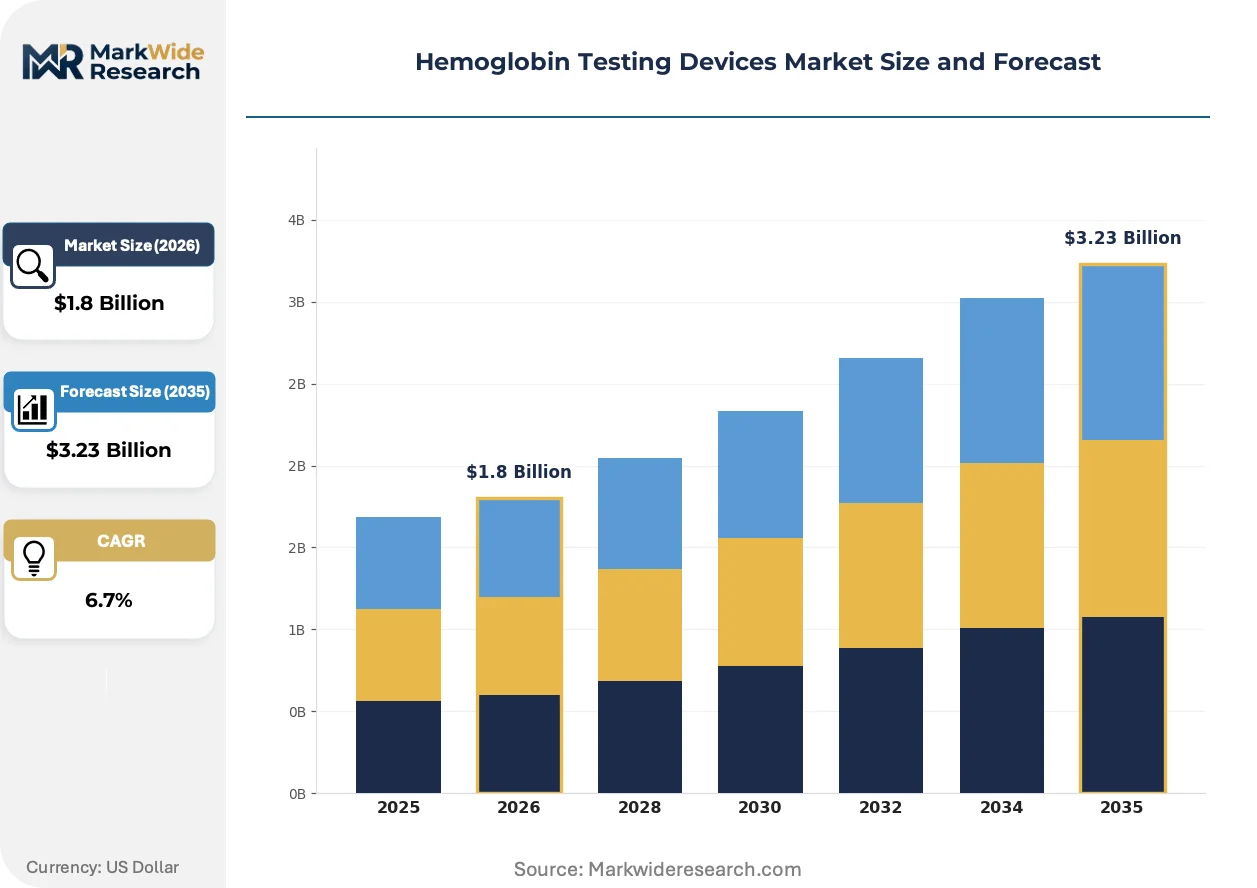
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Point-of-Care Analyzers, Laboratory Analyzers, Handheld Devices, Portable Devices Technology: Colorimetric Methods, Electrochemical Methods, Spectrophotometric Methods, Optical Methods End User: Hospitals, Diagnostic Laboratories, Homecare, Blood Banks Application: Screening, Monitoring, Diagnosis, Research |
| Companies Covered | Bio-Rad Laboratories, Inc., Trinity Biotech, Abbott, Thermo Fisher Scientific Inc., HemoCue, F. Hoffmann-La Roche Ltd, Beckman Coulter, Inc., Mindray, Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobin Testing Devices Market Emerging Trajectories
Non-invasive hemoglobin monitoring is crossing the threshold from research novelty to clinical viability, altering competitive boundaries between optical device manufacturers and traditional in vitro diagnostic incumbents.
Microfluidic cartridge architectures are rendering obsolete benchtop spectrophotometers in emergency department triage workflows. Hospital systems in Texas and Florida are deploying palm-sized analyzers that deliver results in ninety seconds from fifty microliter samples. This compression is rendering obsolete the thirty-minute send-out model that previously dominated acute anemia assessment.
The EU In Vitro Diagnostic Regulation's 2022 implementation is forcing recertification of legacy hemoglobin assays under stricter clinical evidence requirements. Manufacturers with established notified body relationships are accelerating MDR technical documentation submissions. High-throughput laboratory analyzers face the steepest compliance burden, while point-of-care devices with simpler intended use claims navigate streamlined conformity pathways.
Integrated delivery networks are consolidating point-of-care device procurement under centralized value analysis committees, displacing the department-level purchasing autonomy that previously governed emergency and operating room acquisitions. Health systems in California and Illinois now mandate enterprise-wide hemoglobin testing contracts that span twenty-plus facility networks. This concentration is most visible in Medicare Advantage contracting environments where capitated payment structures reward standardization over site-specific device preferences.
Hemoglobin Testing Devices Market Segmentation
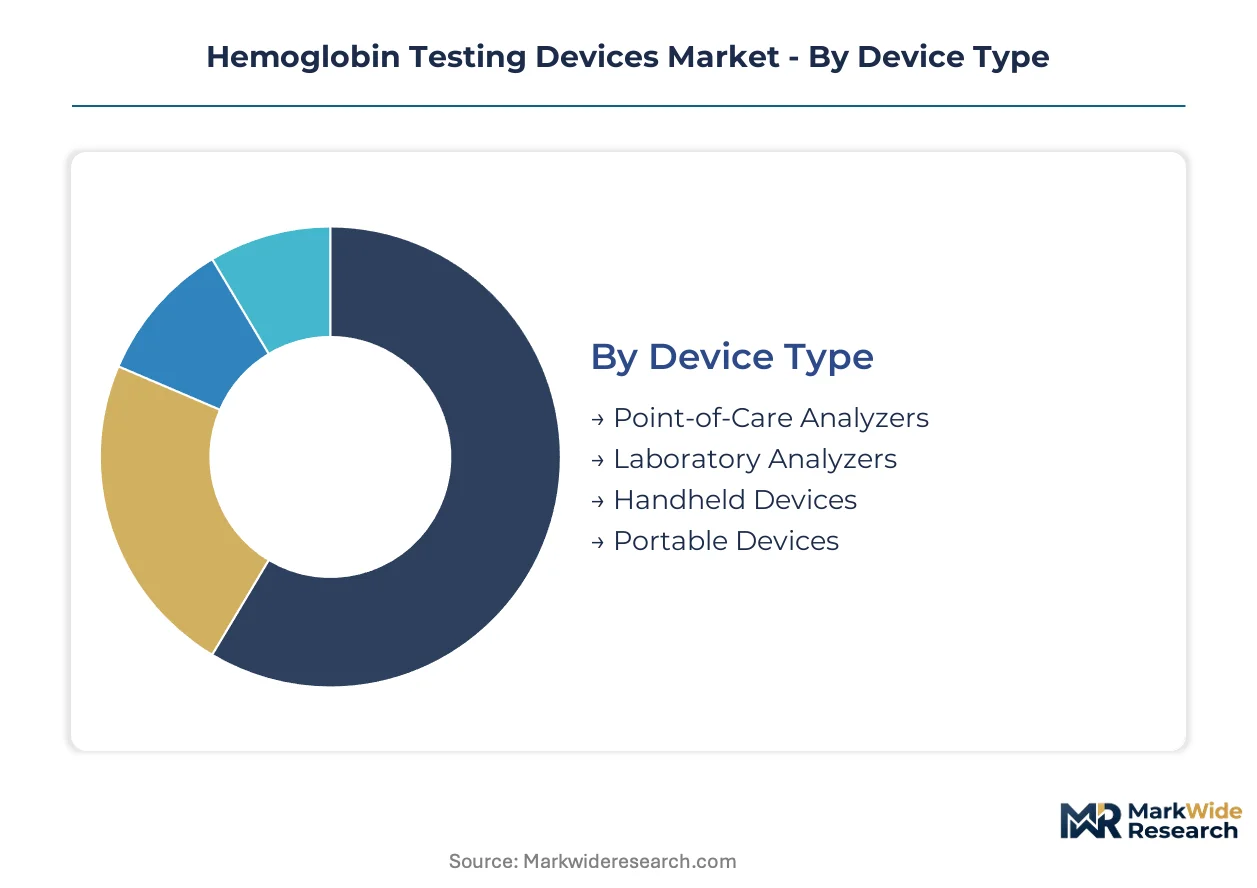
Hemoglobin testing devices fragment across four intersecting dimensions that determine procurement authority, service intensity, and margin structure. Device type and technology choices cascade through reimbursement codes, while end-user concentration and application urgency dictate after-sales support requirements.
Device Type:
After-sales service intensity varies sharply across device categories, with emergency department deployments demanding 24-hour response SLAs and laboratory installations requiring multi-year calibration contracts.
- Point-of-Care Analyzers:Benchtop units integrate electrochemical or optical detection modules for rapid turnaround in emergency departments and surgical suites. Texas and Florida health systems deploy palm-sized variants that compress anemia assessment from thirty minutes to ninety seconds. Abbott sustains installed-base expansion through channel density in hospital systems.
- Handheld Devices:Battery-operated units leverage solid-state electrode miniaturization to achieve laboratory-grade precision without optical complexity. Bluetooth-enabled models connect to chronic kidney disease management platforms, opening subscription revenue streams in United States homecare settings. These units are expanding most quickly as remote monitoring protocols gain reimbursement traction.
- Laboratory Analyzers:High-throughput spectrophotometric platforms anchor centralized reference laboratory workflows. Thermo Fisher Scientific anchors position through R&D intensity in multi-parameter integration.
- Portable Devices:Mid-size units bridge point-of-care and laboratory performance tiers for ambulatory surgery centers and community health networks.
Point-of-Care Analyzers hold the largest share; momentum sits with Handheld Devices.
Technology:
Technology selection determines component supply exposure, with precision photodiode and filter manufacturing concentrating in East Asian foundries.
- Electrochemical Methods:Solid-state electrode fabrication enables miniaturization without optical component complexity. Solid-state architectures reduce single-source fragility from photodiode supply concentration.
- Spectrophotometric Methods:Full absorbance spectrum analysis supports multi-analyte panels through machine learning interpretation. Siemens Healthineers integrates these modules into hematology automation lines to reduce technician handling steps.
- Colorimetric Methods:Chemical reagent-based detection dominates low-resource clinic networks under WHO maternal health screening protocols.
- Optical Methods:Non-invasive monitoring variants cross from research novelty toward clinical viability, altering competitive boundaries between device manufacturers.
Spectrophotometric Methods retain margin concentration in reference settings; Electrochemical Methods are gaining share fastest through miniaturization advances.
End User:
End-user concentration shapes procurement consolidation patterns, with integrated delivery networks in California and Illinois mandating enterprise-wide contracts spanning twenty-plus facilities.
- Hospitals:Emergency departments and operating rooms drive point-of-care migration, compressing turnaround times and rewiring procurement authority toward clinical department budgets. CLIA-waived test expansion accelerates deployment in physician offices.
- Diagnostic Laboratories:High-volume reference settings justify capital intensity through throughput and multi-parameter integration. ISO 15189 accreditation requirements favor established manufacturers with dedicated regulatory affairs infrastructure.
- Homecare:Remote patient monitoring integration opens subscription revenue streams beyond device sales as chronic disease management platforms expand.
- Blood Banks:Transfusion trigger verification demands precision thresholds governed by Clinical and Laboratory Standards Institute protocols.
Hospitals command the largest revenue pool; Homecare shows the steepest expansion trajectory as reimbursement codes evolve.
Application:
Application urgency determines regulatory pathway complexity, with diagnostic claims facing stricter FDA evidence requirements than screening protocols.
- Screening:WHO maternal health guidelines mandate universal hemoglobin assessment in antenatal care, institutionalizing demand in low-resource clinic networks. Ayushman Bharat health and wellness centers in India require village-level infrastructure at price points below current import tariffs.
- Monitoring:Chronic kidney disease and anemia management protocols drive recurring testing volume in Medicare Advantage capitated environments.
- Diagnosis:Acute hemorrhage triage in emergency departments demands CLIA-waived status for rapid deployment.
- Research:Clinical trial endpoints require documented analytical performance under CLSI protocols.
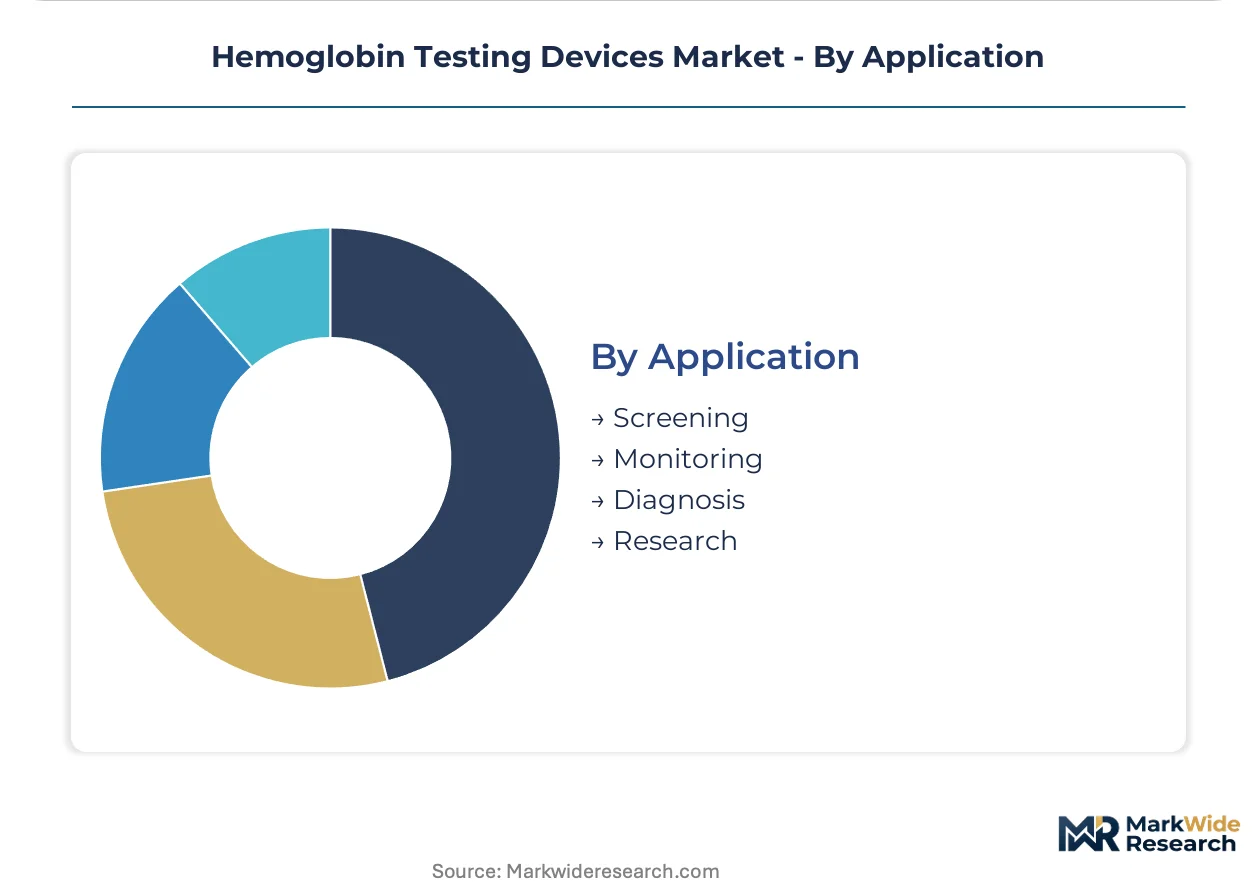
Screening holds the largest share; Monitoring is climbing the fastest as chronic disease platforms expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's strengthened Clinical Laboratory Improvement Amendments are pushing hemoglobin testing device manufacturers toward higher analytical performance standards in the United States. Integrated delivery networks in California and Illinois now mandate enterprise-wide contracts spanning twenty-plus facilities. This regulatory and procurement concentration is reshaping competitive positioning across North American acute care settings.
United States
Emergency departments in Texas and Florida health systems deploy palm-sized analyzers that compress anemia assessment from thirty minutes to ninety seconds. CMS reimbursement code fragmentation between point-of-care and laboratory settings creates revenue recognition uncertainty for hospital procurement committees. Abbott leverages its channel density in hospital systems to sustain installed-base expansion across acute care settings.
China
Domestic manufacturing of optical and electrochemical components is reconfiguring hemoglobin testing device supply chains toward self-sufficiency. NMPA regulatory pathways for in vitro diagnostics are converging with international standards under GB certification harmonization efforts. Precision photodiode and filter manufacturing concentrates in East Asian foundries, exposing device assemblers to single-source fragility.
Germany
Siemens Healthineers AG competes by integrating hemoglobin modules into broader hematology automation lines, reducing footprint and technician handling steps. EU In Vitro Diagnostic Regulation's 2022 implementation forces recertification of legacy assays under stricter clinical evidence requirements. Bavaria-based laboratory equipment manufacturers face the steepest MDR compliance burden for high-throughput analyzers.
India
Ayushman Bharat health and wellness centers require village-level anemia screening infrastructure at price points below current import tariffs. CDSCO regulatory frameworks for point-of-care devices are streamlining approval pathways for CLIA-equivalent waived tests. Maharashtra and Gujarat diagnostic networks are expanding procurement of handheld electrochemical units for maternal health screening protocols.
Japan
PMDA oversight of spectrophotometric platforms maintains rigorous analytical performance thresholds for centralized laboratory workflows. METI industrial policy supports domestic production of precision optical components for hematology instrumentation. Tokyo-Osaka medical device clusters concentrate R&D intensity in multi-parameter integration technologies.
Hemoglobin Testing Devices Market Vendor Landscape
Capability concentration sits with laboratory-grade precision specialists; scale advantage sits with channel-dense hospital system suppliers. The vendor base organizes around three strategic archetypes: integrated diagnostics conglomerates with hematology automation lines, point-of-care specialists with electrochemical miniaturization expertise, and centralized laboratory platform providers with spectrophotometric R&D depth. Dominant competitive moves include M&A to secure optical component supply chains and strategic partnerships with integrated delivery networks for enterprise-wide procurement contracts.
Among United States-based diagnostics conglomerates, Abbott and Thermo Fisher Scientific Inc. occupy positions at opposite ends of the care continuum archetype spectrum. Abbott represents the channel-density model for acute care point-of-care expansion, while Thermo Fisher Scientific Inc. anchors the centralized laboratory platform tier. Siemens Healthineers AG, a German AG-structured conglomerate, exemplifies the hematology automation integration archetype that reduces technician handling steps through modular system design.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Trinity Biotech |
| Abbott |
| Thermo Fisher Scientific Inc. |
| HemoCue |
| F. Hoffmann-La Roche Ltd |
| Beckman Coulter, Inc. |
| Mindray |
| Siemens Healthineers AG |
| Others |
Supply Flow & Price Mechanics
Single-source photodiode dependency in East Asian foundries compresses margin structures across pricing tiers while simultaneously forcing device assemblers toward captive electrode production or alternative optical sourcing. This concentration dynamic widens spreads between premium spectrophotometric platforms and economy electrochemical units as manufacturers pass through component scarcity premiums or absorb costs to defend reference-laboratory contracts.
Pricing Analysis
Price spreads between German-manufactured laboratory analyzers and Chinese-assembled handheld units exceed three-to-one at wholesale, reflecting CE-MDR certification premiums and optical component grade differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical precision thresholds and after-sales bundling intensity. Cost compression in the handheld tier is intensifying because solid-state electrode fabrication achieves laboratory-grade performance without photodiode exposure. Community health centers under India's Ayushman Bharat program exhibit highest price sensitivity, while United States integrated delivery networks prioritize standardization over unit cost minimization.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Suzhou electronics clusters for optical module assembly, with Bavaria-based precision machining houses handling spectrophotometer mechanical chassis. Component sourcing draws from Japanese photodiode foundries, South Korean solid-state electrode suppliers, and domestic Chinese PCB fabrication. Single-source vulnerability in precision filter manufacturing exposes device assemblers to allocation risk during semiconductor cycle upturns. Distribution runs through hospital group purchasing organizations in North America, regional diagnostic distributors in Europe, and government procurement hubs in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care test expansion under CLIA-waiver pathways positions this market for early-cycle penetration gains as emergency departments displace centralized laboratory workflows. Hemoglobin testing devices benefit from institutionalization of rapid anemia screening protocols across maternal health networks.
For Market Incumbents: Insulate reference-laboratory margins by accelerating spectrophotometric-AI convergence for multi-analyte panels that handheld electrochemical units cannot replicate. Secure captive supply of precision optical components through backward integration into photodiode sourcing or long-term offtake agreements with East Asian foundries. Defend against emerging non-invasive optical monitoring substitutes by embedding hemoglobin modules into broader hematology automation lines that reduce technician handling steps. For New Entrants and Emerging Players: Pursue village-level anemia screening infrastructure under India's Ayushman Bharat program, where import tariff exposure creates pricing headroom for locally assembled electrochemical units. Target Bluetooth-enabled handheld integration with chronic kidney disease management platforms in United States homecare settings, where reimbursement code evolution opens subscription revenue streams beyond device sales. Lead with CLIA-waived certification to bypass laboratory director proficiency testing requirements that constrain incumbent point-of-care fleets. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape by forcing smaller manufacturers toward exit as notified body backlogs extend compliance timelines. Five-to-ten year viability favors platforms with demonstrated MDR technical documentation capabilities and established relationships with European reference laboratories. Target acquisition candidates with electrochemical miniaturization expertise and existing CLIA-waiver status. Monitor FDA guidance document releases on homecare hemoglobin testing as signal for reimbursement inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waiver Pathway Acceleration | FDA streamlined review compresses point-of-care deployment timelines in emergency departments. |
| Optical Component Supply Security | Captive photodiode sourcing insulates margin structures against East Asian foundry allocation risk. |
| Bluetooth-Enabled RPM Integration | Chronic kidney disease platform connectivity opens recurring subscription revenue beyond hardware sales. |
| EU MDR Technical Documentation | Notified body relationship density determines recertification speed for legacy assay portfolios. |
| Ayushman Bharat Contracting | Village-level anemia screening procurement in Maharashtra and Gujarat expands addressable volume. |
Methodological Framework
A spread of perspectives from hospital laboratory directors, point-of-care device operators, GPO contracts managers, and regulatory affairs leads converged on the working assumptions through structured primary interviews. Secondary validation drew from FDA 510(k) filings, CMS reimbursement code databases, EU MDR technical documentation submissions, and hospital procurement contract disclosures. Bottom-up unit demand estimates triangulated against top-down market sizing from installed-base expansion rates and replacement cycle assumptions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across device type, detection technology, end-user concentration, and application urgency. CAGRs were derived from weighted average of historical adoption curves and penetration ceiling analysis. Forecast inputs incorporated CLIA-waiver expansion trajectories, integrated delivery network consolidation patterns, and WHO maternal health screening protocol institutionalization rates.
Sensitivities concentrate around FDA guidance timeline shifts, EU notified body capacity constraints, and photodiode supply allocation disruptions. Forecasts reflect assumptions on reimbursement code harmonization and point-of-care operator proficiency testing compliance rates. Quarterly review of CLIA-waiver submission volumes, MDR certificate issuance rates, and East Asian optical component lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
US Breath Analyzers Market