
 MRI Compatible Biopsy Devices Market | 2026-2036
MRI Compatible Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Compatible Biopsy Devices Market Foresight
Radiologist-interventionalist training pipelines is redrawing competitive boundaries across the MRI compatible biopsy devices landscape. Siemens AG leverages its installed base of MRI scanners to bundle navigation hardware with proprietary biopsy guidance software. Medtronic plc sustains a focused portfolio in electromagnetic navigation platforms that integrate with third-party imaging systems. Cook Group anchors its position through specialized needle sets engineered for high-field-strength magnet environments.
MRI compatible biopsy devices comprise instrument sets fabricated from non-ferromagnetic alloys—typically titanium, nickel-titanium, or specialized polymers—that function within static magnetic fields exceeding 1.5 Tesla without torque, heating, or image artifact, enabling real-time tissue acquisition under direct MR visualization. Core biopsy systems command the largest revenue share among product types due to their diagnostic yield in breast and prostate workflows, while vacuum-assisted platforms are gaining traction in musculoskeletal applications where larger tissue volumes improve pathological certainty. Robotic-assisted technology segments attract disproportionate R&D investment as hospitals seek to standardize needle placement accuracy and reduce operator-dependent variability in interventional MRI suites.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development cycles, with both frameworks demanding extensive electromagnetic compatibility and biocompatibility validation for devices entering clinical service. ISO 13485 quality management certification has become a baseline qualification for supplier relationships with integrated delivery networks in North America and Western Europe. Stakeholders must weigh capital deployment toward robotic navigation platforms against the operational flexibility of manual systems as reimbursement pathways for MRI-guided interventions continue to evolve across public and private payor landscapes.
Market Dynamics
Robotic navigation platforms are compressing operator-dependent variability in interventional MRI suites, forcing capital allocation decisions between automated precision and manual flexibility as reimbursement pathways for image-guided biopsies mature.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's premarket notification pathway for Class II surgical devices accelerates electromagnetic compatibility validation timelines, enabling faster commercialization of titanium-alloy instrument sets.
- Academic medical center expansion:Oncology departments in the United States, Germany, and Japan are establishing integrated MRI-interventional suites as standard infrastructure for prostate and breast lesion characterization.
- High-field-strength magnet proliferation:3 Tesla and 7 Tesla MRI installations are creating demand for nickel-titanium needle systems engineered to eliminate torque artifacts during real-time tissue acquisition.
Market Restraints
- Specialized alloy supply concentration:Non-ferromagnetic titanium and nitinol feedstocks face pricing volatility due to limited smelter capacity in aerospace-dominated supply chains.
- EU MDR technical documentation burdens:The European Union Medical Device Regulation's expanded biocompatibility validation requirements extend product development cycles by 12-18 months for CE marking.
- Electromagnetic navigation substitution:CT-guided biopsy systems with lower capital requirements compete for hospital budget allocation in cost-constrained environments.
Strategic Opportunities
- Musculoskeletal application white space:Vacuum-assisted biopsy platforms targeting orthopedic lesion diagnosis represent underpenetrated clinical workflows beyond oncology.
- Japan's aging population infrastructure:METI hospital modernization incentives support capital investment in integrated MRI-interventional suites for elderly patient populations.
- AI-enhanced needle tracking convergence:Machine learning algorithms fused with electromagnetic navigation are enabling sub-millimeter placement accuracy in soft tissue environments.
Industry Challenges
- Radiologist-interventionalist training pipelines:Specialized credentialing programs for MRI-guided procedures face capacity constraints at academic medical centers.
- ISO 13485 certification timelines:Quality management system audits for supplier qualification with integrated delivery networks create 6-9 month vendor onboarding delays.
- Legacy PACS integration complexity:Proprietary biopsy guidance software from MRI manufacturers requires custom interoperability engineering with hospital imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Compatible Biopsy Devices Market |
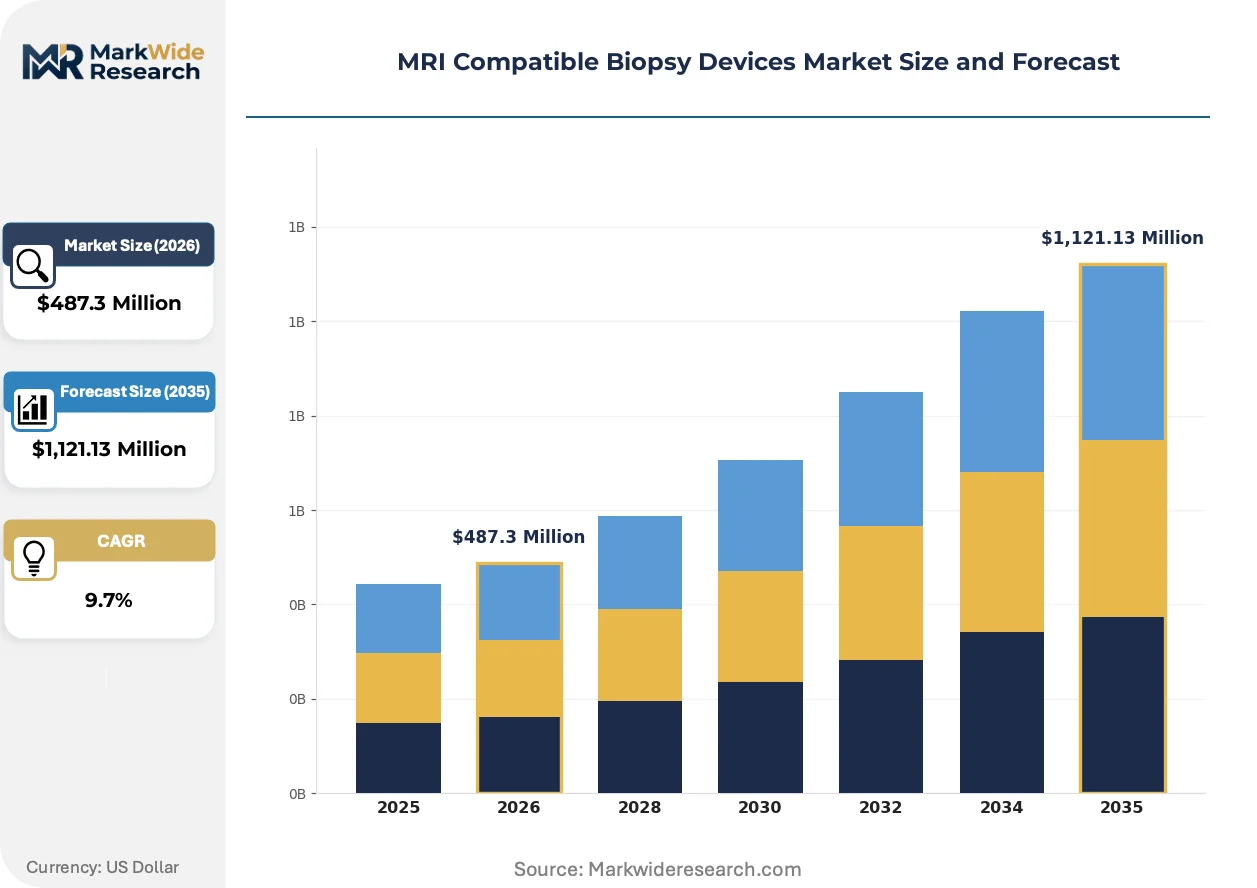
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Core Biopsy, Vacuum-Assisted Biopsy, Fine Needle Aspiration Technology: Electromagnetic Navigation, Ultrasound Guidance, Optical Imaging, Robotic-Assisted End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics Application: Cancer Detection, Tissue Sampling, Lesion Monitoring, Research Studies |
| Companies Covered | Danaher Corporation, Medtronic plc, Becton, Dickinson and Company, Siemens AG, Cook Group, Argon Medical Devices Inc, Sterylab S.R.L, Scion Medical Technologies LLC, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Compatible Biopsy Devices Market Shifts & Advancements
Convergence between robotic navigation, advanced materials science, and AI-enhanced imaging is restructuring how interventional suites deploy precision tissue acquisition. These developments are compressing the gap between diagnostic imaging and therapeutic intervention.
Carbon-fiber reinforced polymer needle guides are decomposing traditional stainless-steel instrument sets in high-field-strength environments. Academic medical centers in Germany and Japan are adopting these platforms for breast biopsy workflows. The technology is decomposing capital equipment refresh cycles by enabling compatibility across 1.5 Tesla to 7 Tesla magnet configurations without hardware replacement.
The EU MDR's post-market surveillance requirements are mandating electromagnetic compatibility traceability across device lifecycles. Manufacturers must now maintain technical documentation for biocompatibility validation beyond initial CE marking. Vacuum-assisted biopsy systems face the steepest compliance burden due to their multi-component architecture and polymer-sleeve material complexity.
Hospital procurement committees are consolidating vendor relationships around single-source navigation platforms rather than maintaining fragmented instrument inventories. Integrated delivery networks in the United States are negotiating enterprise contracts with MRI manufacturers for bundled hardware-software-needle agreements. This concentration is most visible in prostate biopsy programs where standardization across multi-site health systems reduces training overhead and disposable inventory complexity.
MRI Compatible Biopsy Devices Market Segmentation
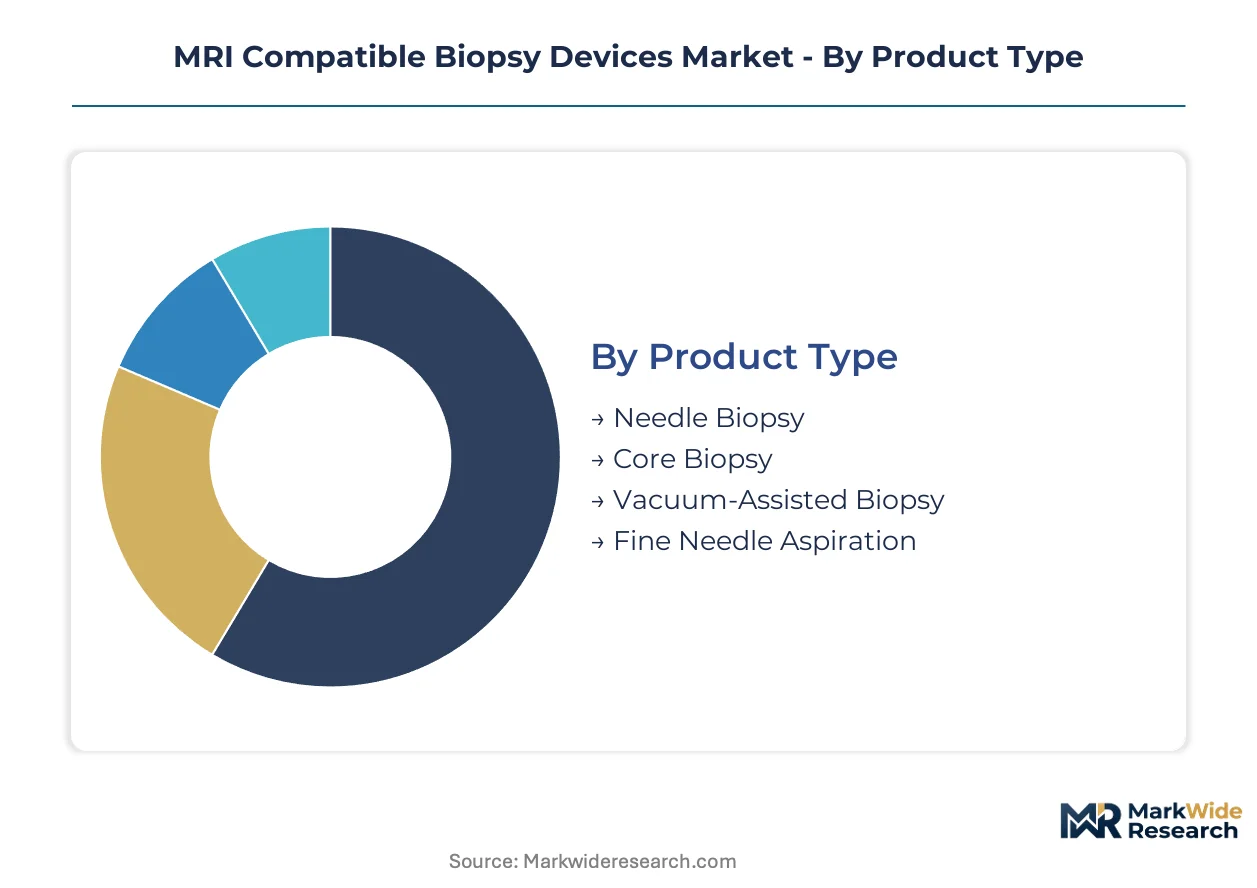
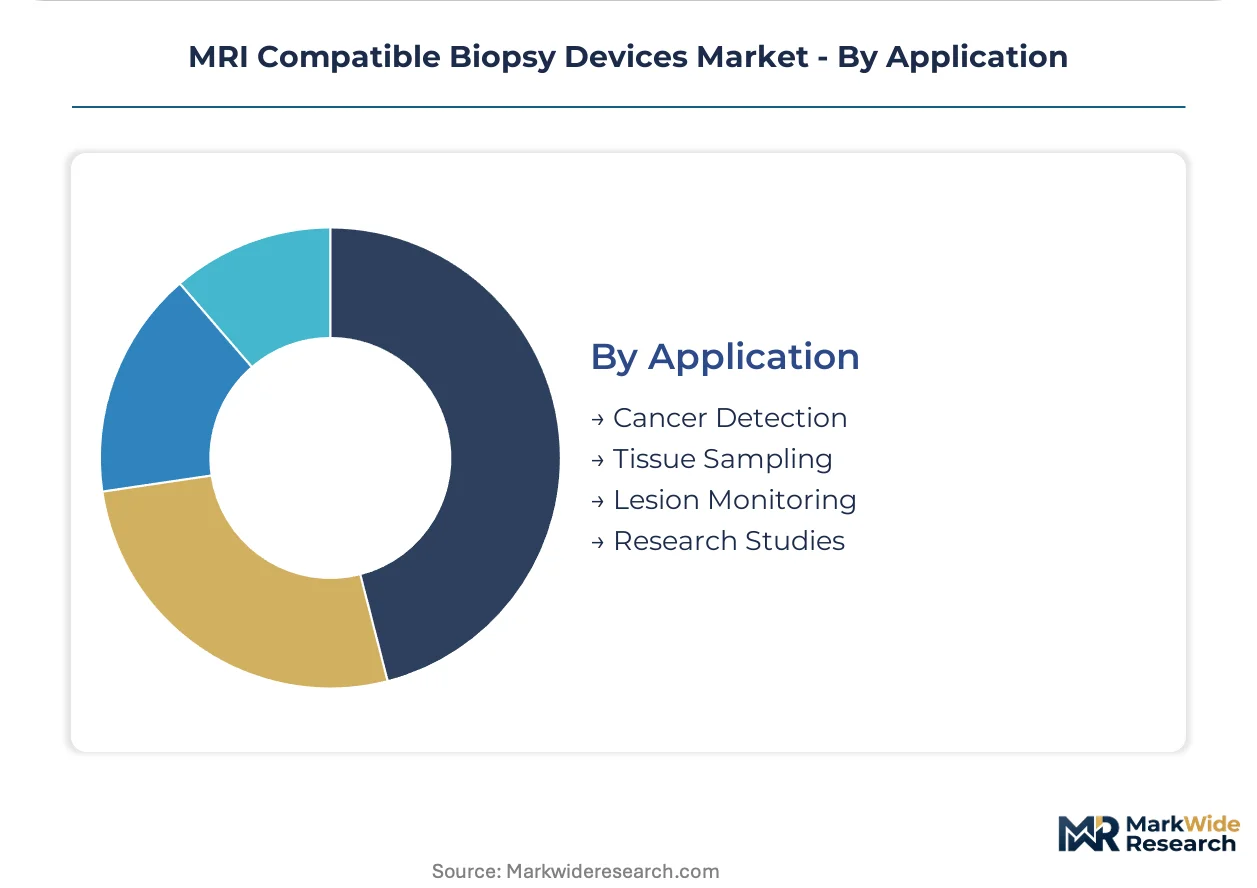
Segmentation in MRI compatible biopsy devices reveals how procurement committees balance diagnostic precision against capital constraints. Product architecture, navigation technology, and clinical setting each impose distinct electromagnetic compatibility requirements that shape vendor selection criteria.
Product Type:
Substitution pressure from CT-guided alternatives weighs heaviest on needle biopsy systems, forcing manufacturers to differentiate through magnet-safe material engineering.
- Core Biopsy:Titanium-alloy instrument sets with coaxial needle architecture extract cylindrical tissue specimens under direct MR visualization. Academic medical centers in the United States and Germany standardize these systems for prostate and breast lesion characterization due to diagnostic yield advantages over fine needle alternatives.
- Vacuum-Assisted Biopsy:Nickel-titanium cannula systems with integrated suction mechanisms acquire larger tissue volumes through single insertion points. Demand concentrates in musculoskeletal applications at orthopedic specialty centers where pathological certainty requires substantial sample volumes.
- Needle Biopsy:Basic aspiration systems face margin compression from CT-guided substitutes in cost-constrained environments.
- Fine Needle Aspiration:Smaller-gauge systems serve rapid cytological assessment workflows in outpatient settings with limited capital budgets.
Core biopsy anchors the volume base while vacuum-assisted platforms gain share at the steepest rate.
Technology:
Cost tier stratification separates navigation platforms by capital intensity and integration complexity with existing MRI infrastructure.
- Electromagnetic Navigation:Sensor arrays track instrument position within the magnet bore through low-frequency field detection. Third-party compatibility with Siemens, GE, and Philips scanner platforms drives adoption at mid-tier hospitals seeking vendor flexibility.
- Robotic-Assisted:Motorized needle drivers with sub-millimeter positioning accuracy reduce operator-dependent variability in interventional MRI suites. METI modernization grants in Japan accelerate deployment at academic centers serving elderly populations.
- Ultrasound Guidance:Lower-cost optical tracking systems compete for budget allocation in diagnostic centers without dedicated interventional MRI infrastructure.
- Optical Imaging:Camera-based navigation offers the lowest capital entry point for facilities prioritizing disposable instrument economics over precision automation.
Electromagnetic navigation dominates installed base while robotic-assisted configurations expand most quickly among new suite constructions.
End User:
Customer type determines procurement authority structure and reimbursement pathway complexity for MRI-guided interventions.
- Hospitals:Integrated delivery networks negotiate enterprise contracts bundling navigation hardware, proprietary software, and disposable needle sets. Capital budgets for interventional MRI suites concentrate at academic medical centers in the United States, Germany, and Japan.
- Diagnostic Centers:Freestanding imaging facilities prioritize electromagnetic navigation platforms compatible across multiple MRI manufacturer installed bases.
- Research Laboratories:7 Tesla experimental systems drive demand for specialized nitinol instruments engineered for ultra-high-field environments.
- Outpatient Clinics:Limited procedure volumes favor manual systems with lower per-case overhead and reduced training requirements.
Hospitals command the revenue base while diagnostic centers emerge as the volume growth engine.
Application:
Maturity gradients separate established oncology workflows from emerging research applications with distinct validation requirements.
- Cancer Detection:Prostate and breast lesion characterization protocols at academic medical centers generate recurring demand for core biopsy disposable sets. FDA 510(k) clearance pathways standardize electromagnetic compatibility validation for these high-volume indications.
- Tissue Sampling:Musculoskeletal biopsy workflows at orthopedic centers require vacuum-assisted platforms with larger-gauge cannula systems.
- Lesion Monitoring:Serial biopsy protocols for treatment response assessment favor fine needle systems minimizing patient trauma.
- Research Studies:Experimental protocols at 7 Tesla facilities drive specialized instrument development outside standard regulatory pathways.
Cancer detection underpins commercial volume while research studies exhibit the most rapid expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, with academic medical centers in Germany and Japan expanding interventional MRI infrastructure through distinct regulatory frameworks. Hospital capital deployment concentrates in metropolitan clusters where integrated delivery networks negotiate bundled procurement contracts.
United States
Oncology departments at academic medical centers in Boston and Houston are establishing MRI-guided biopsy programs as standard infrastructure for prostate lesion characterization. FDA premarket notification requirements for Class II surgical devices compress electromagnetic compatibility validation timelines. The Texas Medical Center cluster anchors demand for robotic-assisted navigation platforms serving elderly patient populations.
Germany
University hospitals in Munich and Heidelberg are deploying vacuum-assisted biopsy systems for musculoskeletal applications requiring substantial tissue volumes. EU MDR technical documentation obligations extend product development cycles but accelerate post-market surveillance standardization. The Baden-Württemberg medical technology corridor concentrates nitinol instrument manufacturing for high-field-strength magnet environments.
Japan
METI hospital modernization grants support capital investment in integrated MRI-interventional suites across Tokyo and Osaka metropolitan areas. PMDA regulatory harmonization with FDA electromagnetic compatibility standards reduces dual-certification burdens for titanium-alloy instrument sets. The Kansai region anchors demand for 7 Tesla experimental systems driving specialized needle development.
United Kingdom
NHS England procurement frameworks prioritize electromagnetic navigation platforms compatible across multiple MRI manufacturer installed bases. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements maintains CE marking equivalence for market access. The Cambridge-Oxford-London triangle concentrates research laboratory demand for experimental biopsy protocols.
Switzerland
Swissmedic streamlined approval pathways for Class IIa surgical devices attract European headquarters relocation from manufacturers seeking regulatory efficiency. University hospitals in Zurich and Geneva standardize core biopsy workflows for breast lesion characterization. The Basel pharmaceutical-industrial cluster drives demand for tissue sampling systems supporting drug development pipelines.
MRI Compatible Biopsy Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the MRI compatible biopsy devices market. Siemens AG leverages its installed base of MRI scanners to bundle navigation hardware with proprietary guidance software, while Medtronic plc sustains electromagnetic navigation platforms integrating with third-party imaging systems. Three strategic archetypes dominate: diversified imaging conglomerates bundling hardware-software-needle agreements, focused navigation technology specialists, and precision instrument fabricators engineering non-ferromagnetic alloys. Competitive moves concentrate on strategic partnerships with academic medical centers and portfolio diversification into robotic-assisted configurations.
Within the diversified imaging tier, Siemens AG exemplifies vertical integration from magnet manufacturing through interventional guidance software. Among precision instrument specialists, Cook Group anchors positioning through specialized needle sets engineered for high-field-strength environments. Medtronic plc occupies a position representing third-party navigation compatibility across heterogeneous MRI installed bases. These three companies collectively illustrate how vendor selection criteria vary between hospitals prioritizing bundled procurement and diagnostic centers seeking cross-platform flexibility.
| Leading Market Players |
|---|
| Danaher Corporation |
| Medtronic plc |
| Becton, Dickinson and Company |
| Siemens AG |
| Cook Group |
| Argon Medical Devices Inc |
| Sterylab S.R.L |
| Scion Medical Technologies LLC |
| Boston Scientific |
| Others |
Supply & Pricing Matrix
Capacity utilization at nitinol smelters serving aerospace and medical device demand simultaneously sets price floors for MRI compatible biopsy needle sets, concentrating supply-side leverage among titanium alloy processors in Germany and Japan while forcing hospital procurement committees toward multi-year disposable inventory contracts.
Pricing Analysis
Price spreads between the United States and Western Europe reach 15-20% for equivalent electromagnetic navigation platforms, reflecting differential FDA 510(k) versus EU MDR certification cost recovery. Three-tier pricing structure across premium robotic-assisted, standard electromagnetic, and economy manual guidance tiers anchors the market, with ISO 13485 certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy manual tiers is intensifying because CT-guided biopsy substitutes compete for capital-constrained diagnostic center budgets. Outpatient clinics exhibit highest price sensitivity, while academic medical centers prioritize precision automation over per-unit economics.
Supply Chain Analysis
Germany and Japan anchor precision nitinol and titanium alloy fabrication for high-field-strength needle systems, while the United States concentrates electromagnetic sensor array manufacturing and proprietary navigation software development. Raw material dependencies rest on nickel-titanium feedstock from specialized aerospace-certified smelters, rare earth elements for magnetic field sensors, and medical-grade polymers for vacuum-assisted cannula sleeves. Single-source vulnerability in nitinol supply creates exposure when aerospace demand spikes divert capacity. Distribution runs through integrated delivery network enterprise contracts in North America and hospital procurement consortiums in Western Europe, with direct manufacturer-to-facility logistics for robotic platform installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable needle set replenishment and software maintenance subscriptions expand faster than capital hardware sales, transforming vendor economics toward recurring revenue models with higher lifetime value per installed interventional MRI suite.
For Market Incumbents: Fortify position through backward integration into nitinol alloy processing to secure feedstock against aerospace demand competition, while expanding proprietary software companion development for AI-enhanced needle tracking to defend against third-party navigation substitutes. CE marking investment under EU MDR technical documentation requirements creates defensive moats against mid-tier competitors lacking quality management infrastructure. For New Entrants and Emerging Players: Aftermarket service coverage gaps in diagnostic centers without dedicated biomedical engineering staff present the most penetrable entry vector, particularly for electromagnetic navigation platforms compatible across Siemens, GE, and Philips installed bases. Target musculoskeletal biopsy workflows at orthopedic specialty centers with vacuum-assisted platforms requiring lower capital commitment than robotic systems. Go-to-market through GPO contracts with regional hospital networks avoids direct competition with bundled enterprise agreements at academic medical centers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument fabricators with captive alloy supply and ISO 13485 certification infrastructure over pure-play navigation software developers facing platform commoditization. Long-term viability hinges on robotics integration capabilities and recurring disposable revenue attachment rates. Watch FDA 510(k) clearance velocity for robotic-assisted platforms as inflection indicator for capital deployment timing toward automation-heavy configurations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation compliance accelerates market access across German and Swiss hospital procurement frameworks. |
| Hospital System Partnership | Enterprise contracts with Texas Medical Center and Boston academic clusters secure multi-year disposable needle commitments. |
| Software Companion Development | AI-enhanced needle tracking algorithms differentiate electromagnetic navigation platforms against manual guidance alternatives. |
| Backward Integration into Alloys | Captive nitinol processing insulates margin structure from aerospace demand volatility in Japanese supply chains. |
| Reimbursement Strategy | CPT code alignment for MRI-guided prostate biopsy procedures determines capital budget approval velocity at U.S. oncology departments. |
Research Methodology
Cross-validation between primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data anchors the qualitative findings. Bottom-up triangulation from instrument shipment volumes and top-down validation from capital expenditure disclosures at integrated delivery networks ensure segmentation accuracy across product type, navigation technology, and end-user categories.
Sensitivity analysis around nitinol feedstock pricing, FDA clearance timelines, and METI hospital modernization grant disbursement rates tests forecast robustness across the projection horizon. Segmentation modeling incorporates product architecture, electromagnetic compatibility tier, clinical application workflow, and regional regulatory cluster dimensions. CAGRs derive from installed base expansion rates for interventional MRI suites and per-procedure disposable consumption patterns, with robotic-assisted platform adoption curves and vacuum-assisted musculoskeletal application penetration as key demand drivers.
Forecasts assume regulatory continuity in FDA 510(k) premarket notification pathways and EU MDR post-market surveillance requirements; material policy shifts toward stricter electromagnetic compatibility validation or accelerated CE marking timelines would require re-modeling. Specific risks include nitinol supply disruption from aerospace demand spikes, PMDA-FDA harmonization reversals affecting Japanese market entry, and reimbursement code consolidation for image-guided biopsy procedures. Recalibration cycles align with material shifts in hospital capital budget allocations, regulatory clearance velocity, and AI navigation algorithm clinical validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Biopsy Devices Market