
 PCR and Real-Time PCR Molecular Diagnostics Market | 2026-2036
PCR and Real-Time PCR Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
PCR and Real-Time PCR Molecular Diagnostics Market Analytics
China is fragmenting as domestic manufacturers scale PCR instrument production for hospital procurement tenders. Thermo Fisher Scientific leverages its reagent-instrument bundling strategy to defend installed-base positions across Asia-Pacific clinical accounts. Abbott anchors its infectious disease franchise with integrated sample-to-answer platforms that reduce laboratory technician training burdens. QIAGEN competes through specialized assay content partnerships with national reference laboratories.
PCR and real-time PCR molecular diagnostics encompass nucleic acid amplification technologies that detect and quantify target DNA or RNA sequences through thermal cycling with fluorescent reporter monitoring, typically achieving analytical sensitivity down to single-copy detection. These systems serve primarily to identify pathogenic organisms, genetic mutations, and oncogenic markers for clinical treatment decisions. Reagents capture the dominant margin pool given recurring consumption tied to test volumes, while real-time PCR technology leads instrument placements due to its balance of throughput, cost, and regulatory validation depth. Digital PCR represents the fastest-expanding technology segment as oncology liquid biopsy applications demand absolute quantification without standard curve dependency.
FDA premarket review under the In Vitro Diagnostics Regulation shapes assay commercialization pathways and clinical claim substantiation requirements for US market entrants. EMA oversight through the In Vitro Diagnostic Medical Devices Regulation enforces post-market surveillance and performance documentation standards across European Economic Area states. China's NMPA implements domestic clinical trial requirements that extend registration timelines for imported PCR platforms. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on companion diagnostic co-development frameworks to align portfolio investments with synchronized approval opportunities.
Market Dynamics
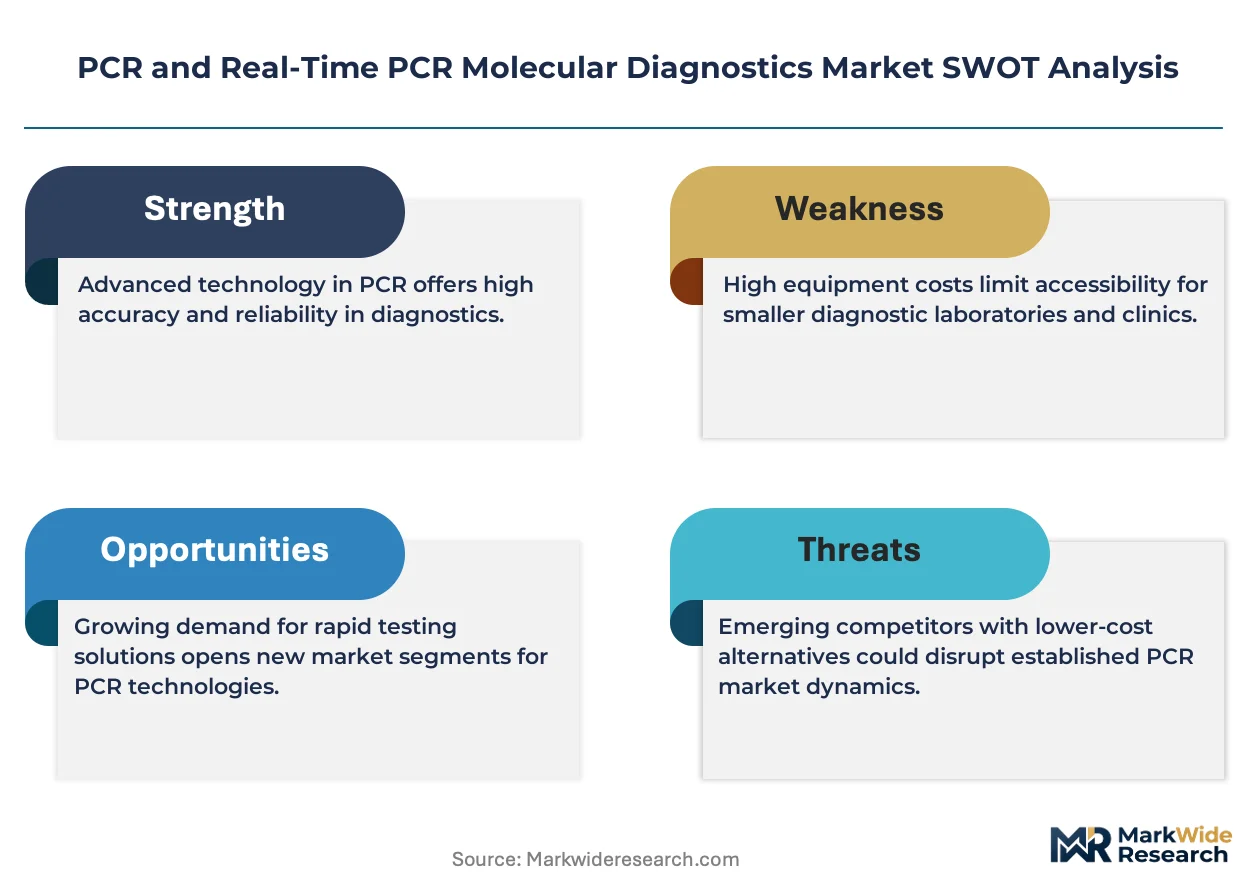
Hospital laboratory consolidation is compressing procurement timelines and favoring integrated platform vendors who bundle reagent supply contracts with multi-year instrument placements.
Growth Catalysts
- Companion diagnostic co-development:FDA's streamlined premarket review pathways for oncology companion assays are accelerating pharmaceutical partnerships and expanding reimbursable test menus in US cancer centers.
- China's hospital tier reform:NMPA mandates for centralized laboratory accreditation are driving procurement of high-throughput real-time PCR systems in provincial hospital networks.
- Digital PCR migration:Absolute quantification capabilities for liquid biopsy applications are displacing relative quantification methods in precision oncology workflows.
Market Restraints
- Reagent cost volatility:Enzyme and oligonucleotide supply concentration among specialized biochemical suppliers creates margin pressure for assay manufacturers.
- NMPA clinical trial requirements:Extended domestic validation timelines for imported PCR platforms delay market entry and compress revenue recognition windows for foreign manufacturers.
- Isothermal amplification substitution:LAMP and CRISPR-based diagnostic methods are gaining traction in point-of-care infectious disease testing where thermal cycling infrastructure is absent.
Strategic Opportunities
- Latin American laboratory networks:Underpenetrated molecular diagnostics infrastructure in Brazil and Mexico presents instrument placement opportunities as national health systems expand cancer screening programs.
- AI-assisted assay design:Machine learning convergence with primer optimization software is compressing development timelines for multiplexed infectious disease panels.
- EU IVDR performance documentation:EMA's post-market surveillance requirements for Class C devices create service revenue streams for compliance consulting and clinical evidence generation.
Industry Challenges
- Bioinformatics pipeline integration:Laboratory information management system compatibility gaps complicate deployment of cloud-connected PCR instruments in hospital networks with legacy IT infrastructure.
- Multiplex assay validation:Cross-reactivity testing for respiratory pathogen panels extends analytical validation timelines and strains regulatory affairs capacity at mid-sized assay developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR and Real-Time PCR Molecular Diagnostics Market |
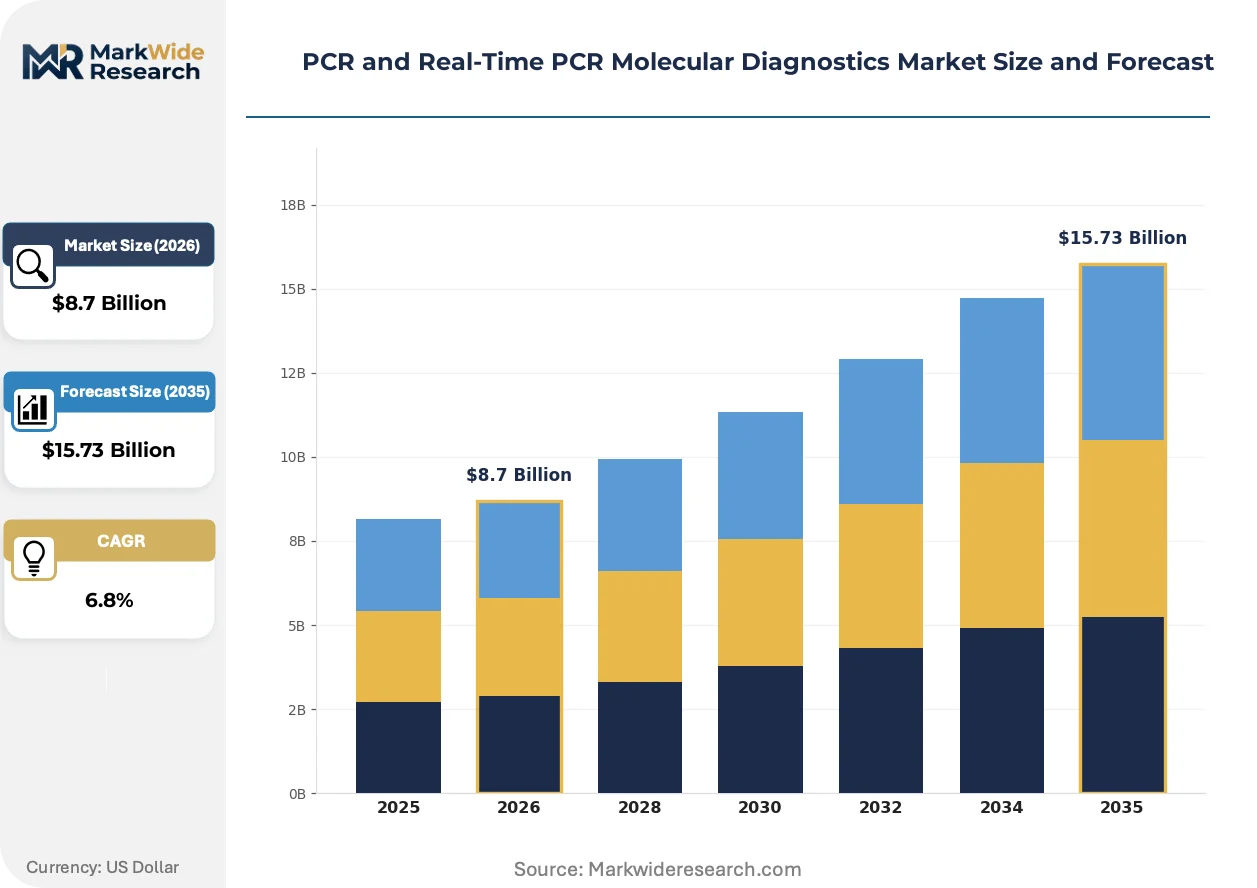
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Reagents, Software, Accessories Application: Infectious Disease Testing, Genetic Testing, Oncology, Blood Screening End User: Hospitals, Diagnostic Laboratories, Research Institutes, Academic Institutions Technology: Real-Time PCR, Digital PCR, Multiplex PCR, Nested PCR |
| Companies Covered | Bio-Rad Laboratories, Agilent Technologies, Abbott, bioMérieux, Danaher, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, GE Healthcare, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR and Real-Time PCR Molecular Diagnostics Market Evolving Landscape
Fluorescence detection architectures and sample-to-answer automation are converging to reshape competitive positioning across clinical, research, and point-of-care environments.
Digital PCR platforms with partitioned microfluidic chambers are rendering obsolete standard curve-dependent quantification in oncology liquid biopsy workflows. Reference laboratories in the United States are adopting these systems for minimal residual disease monitoring. The shift is compressing clinical validation timelines by eliminating run-to-run variability in copy number determination.
EMA's In Vitro Diagnostic Medical Devices Regulation enforces stricter performance documentation and post-market surveillance for Class C molecular diagnostics. Assay developers must now maintain clinical evidence packages across the product lifecycle. European reference laboratories are consolidating supplier relationships to reduce compliance audit burdens.
Centralized procurement through group purchasing organizations is displacing direct manufacturer relationships in US hospital systems. Integrated delivery networks now negotiate multi-year reagent supply contracts tied to instrument placement minimums. This consolidation is most visible in Texas and California health systems where laboratory network mergers have concentrated buying power.
PCR and Real-Time PCR Molecular Diagnostics Market Segmentation
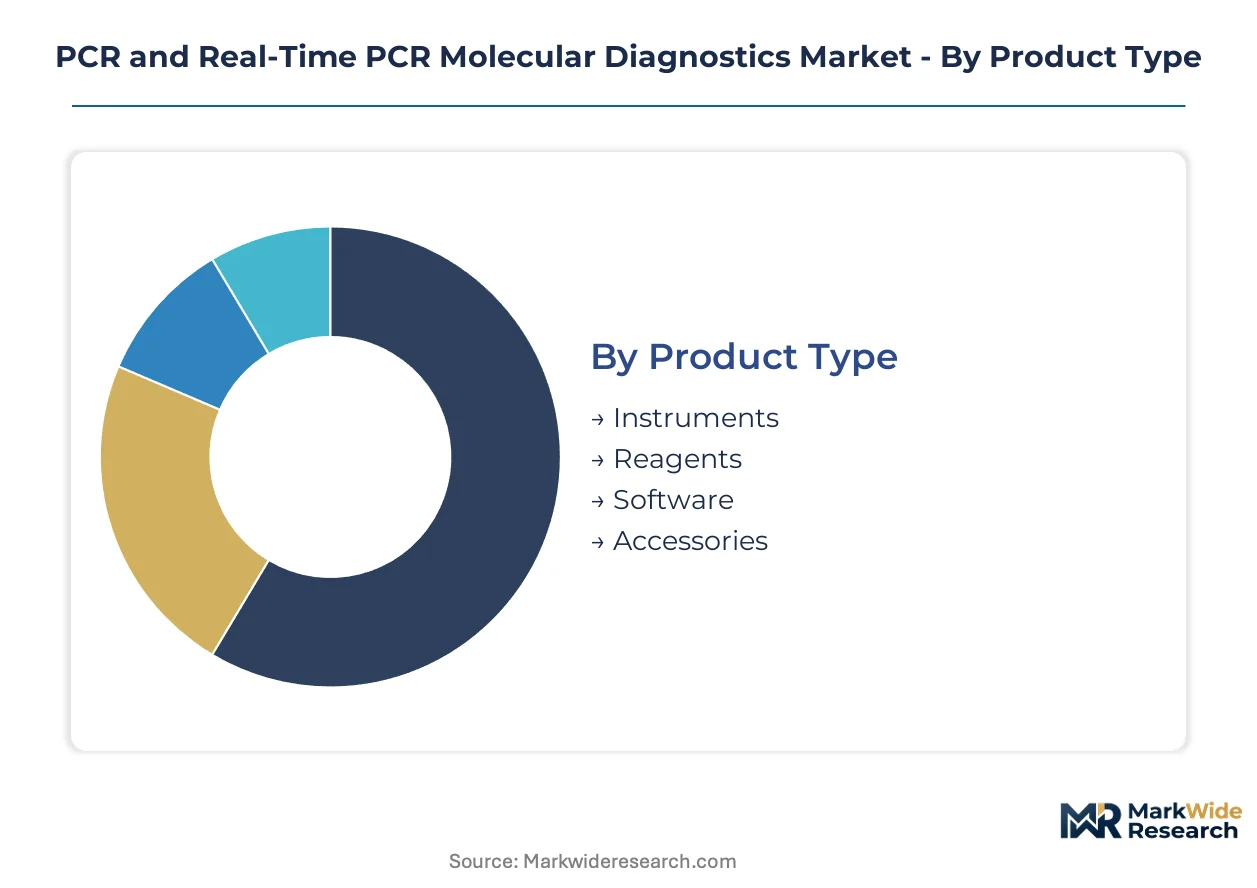
PCR molecular diagnostics segmentation reveals how value pools concentrate across consumable-heavy business models, technology transitions, and customer consolidation. Understanding these divides exposes where pricing power and procurement leverage shift between vendors and buyers.
Product Type:
Mature reagent streams dominate recurring revenue while emerging software layers capture margin expansion through assay design automation.
- Instruments:Thermal cyclers and real-time detection systems anchor laboratory infrastructure with 5-7 year replacement cycles. Demand clusters in China's provincial hospital networks where NMPA accreditation mandates drive high-throughput platform procurement.
- Reagents:Enzyme master mixes, probe chemistries, and nucleotide consumables generate recurring revenue tied to test volumes. US clinical laboratories expanding infectious disease panels drive concentration here, though enzyme supply bottlenecks create margin volatility for assay manufacturers.
- Software:Assay design algorithms and cloud-connected analytics platforms are gaining traction as AI-assisted primer optimization compresses multiplexed panel development timelines.
- Accessories:Consumable plastics, sealing films, and reaction vessels complete workflow bundles, typically sourced through integrated supply contracts rather than standalone procurement.
Reagents handle the majority of throughput; software is the fastest mover on share.
Application:
Cost tier stratification separates high-complexity oncology workflows from high-volume infectious disease screening.
- Infectious Disease Testing:Respiratory pathogen panels, sepsis assays, and viral load monitoring constitute the highest-volume application. Abbott's sample-to-answer platforms reduce technician training burdens in US hospital laboratories facing staffing constraints.
- Oncology:Liquid biopsy minimal residual disease monitoring and companion diagnostic co-development command premium pricing. Digital PCR absolute quantification is displacing standard curve methods here, with reference laboratories in the United States leading adoption.
- Genetic Testing:Carrier screening and pharmacogenomic assays serve mid-tier pricing segments, with validation complexity limiting menu expansion at smaller diagnostic laboratories.
- Blood Screening:Donor pathogen detection maintains steady procurement through national blood service contracts, with regulatory validation depth creating high barriers to competitive entry.
Infectious disease testing commands the largest installed base; oncology applications are climbing the fastest on absolute revenue contribution.
End User:
Customer type determines procurement sophistication, with consolidated networks extracting multi-year supply commitments against volume guarantees.
- Diagnostic Laboratories:National reference laboratories and hospital-affiliated networks concentrate buying power through group purchasing organizations. Texas and California health system mergers have visibly concentrated negotiating leverage in the US market.
- Hospitals:Centralized laboratory accreditation requirements under China's hospital tier reform are accelerating real-time PCR infrastructure deployment across provincial networks.
- Research Institutes:Academic medical centers and government research facilities maintain flexible procurement for novel assay development, though budget cycles create demand lumpiness.
- Academic Institutions:University core facilities balance cost sensitivity with access to emerging digital PCR technologies for grant-funded oncology studies.
Diagnostic laboratories absorb the highest reagent throughput; hospital procurement is gaining share fastest as laboratory networks centralize.
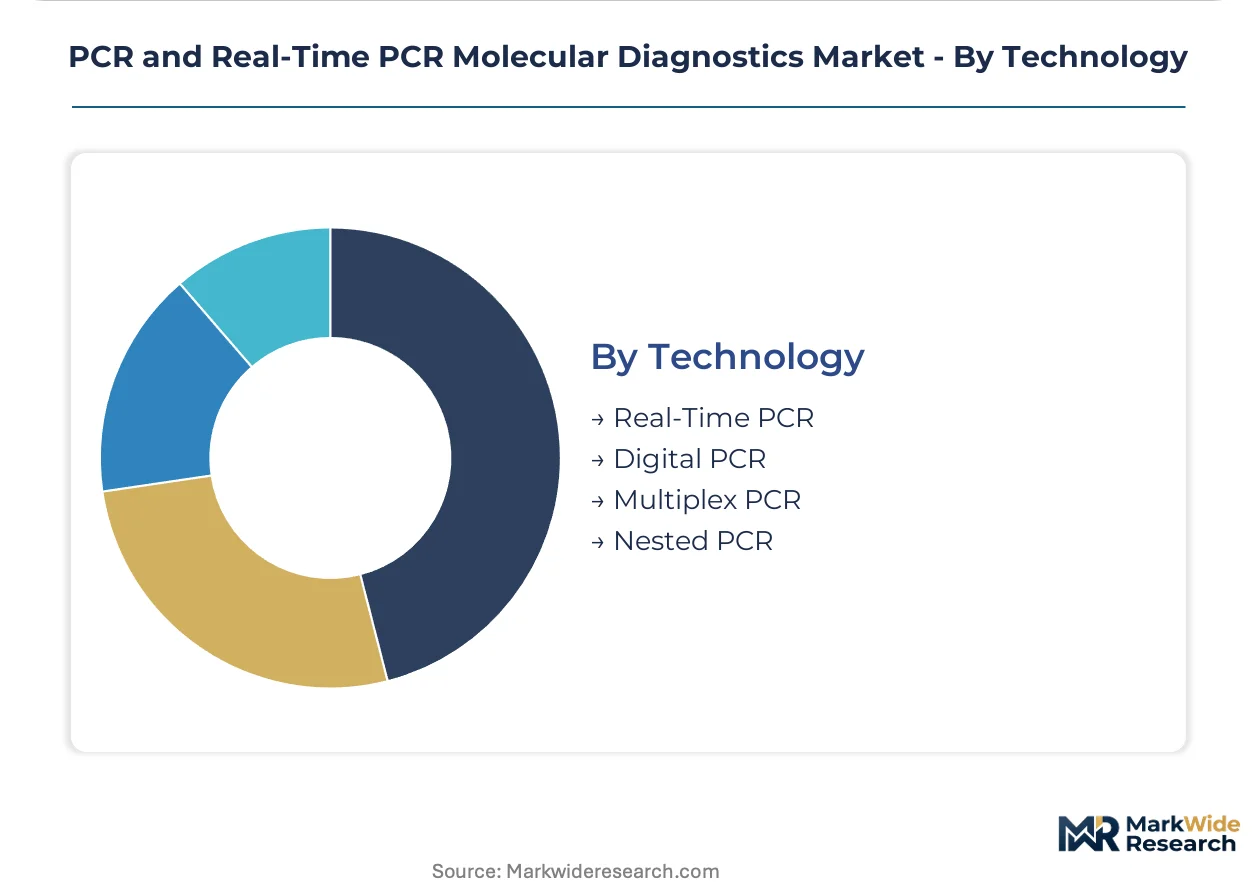
Technology:
Volume-leader real-time PCR faces technology substitution as precision oncology demands push adoption toward absolute quantification methods.
- Real-Time PCR:Fluorescent reporter monitoring during thermal cycling delivers the optimal balance of throughput, cost, and regulatory validation depth. This technology leads instrument placements across clinical and research settings.
- Digital PCR:Partitioned microfluidic chambers enable absolute copy number quantification without standard curve dependency. Liquid biopsy applications in US cancer centers are driving the steepest expansion trajectory here.
- Multiplex PCR:Simultaneous detection of multiple targets strains validation resources, with cross-reactivity testing extending analytical validation timelines for respiratory pathogen panels.
- Nested PCR:Two-round amplification for extreme sensitivity persists in specialized research applications, though contamination risk and workflow complexity limit clinical adoption.
Real-time PCR maintains the dominant installed base; digital PCR is expanding most quickly on new platform placements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for companion diagnostics anchor the United States as the dominant geography, while NMPA mandates and EMA oversight create distinct regulatory environments shaping procurement patterns across hospital networks.
United States
Oncology liquid biopsy demand and infectious disease panel expansion drive procurement in US clinical laboratories. FDA premarket review under streamlined companion diagnostic pathways compresses development timelines for assay developers. Reference laboratories in Massachusetts and California concentrate digital PCR adoption for minimal residual disease monitoring.
China
Hospital laboratory network centralization and provincial accreditation mandates accelerate real-time PCR infrastructure deployment. NMPA domestic clinical trial requirements extend registration timelines for imported platforms. Procurement tenders in Jiangsu and Guangdong provinces concentrate high-throughput instrument placements under national health reform.
Germany
EMA post-market surveillance enforcement and Class C device performance documentation requirements shape laboratory supplier consolidation. REACH compliance for reagent chemistries adds procurement complexity for hospital networks. Industrial clusters in Munich and Heidelberg anchor precision oncology research driving digital PCR validation studies.
Japan
PMDA regulatory validation depth and aging demographics expand cancer screening program procurement. METI technology standards for molecular diagnostics influence instrument interoperability requirements. Tokyo and Osaka metropolitan areas concentrate reference laboratory capacity for companion diagnostic co-development.
Brazil
Underpenetrated molecular diagnostics infrastructure and national cancer screening program expansion create instrument placement opportunities. ANVISA regulatory pathways for imported diagnostics extend commercialization timelines. São Paulo state health system consolidations concentrate negotiating leverage for regional laboratory networks.
PCR and Real-Time PCR Molecular Diagnostics Market Competitive Landscape
Integrated platform vendors and specialized assay content providers split the market into consolidated procurement channels and fragmented innovation pockets. Thermo Fisher Scientific and Abbott anchor the integrated tier through reagent-instrument bundling and sample-to-answer automation. QIAGEN and bioMérieux occupy specialized positions through reference laboratory partnerships and infectious disease menu depth. Competitive moves concentrate on multi-year supply contract negotiations and AI-assisted assay design partnerships.
Among US-based diversified life science conglomerates, Thermo Fisher Scientific and Danaher exemplify the integrated platform archetype through bundled procurement offerings. Swiss pharmaceutical-diagnostic conglomerate F. Hoffmann-La Roche Ltd occupies a position representing premium-tier oncology focus. German sample preparation specialist QIAGEN sits within the specialized content tier, anchoring partnerships with national reference laboratories.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Agilent Technologies |
| Abbott |
| bioMérieux |
| Danaher |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| GE Healthcare |
| QIAGEN |
| Others |
Value Network & Pricing Analysis
Enzyme and oligonucleotide supply concentration among specialized biochemical suppliers in Germany and the United States determines both three-tier pricing structure across premium, standard, and economy levels and the geographic shape of reagent manufacturing networks. NMPA domestic clinical trial requirements for imported PCR platforms compress revenue recognition windows and force foreign manufacturers toward local production partnerships or premium pricing to recover extended timelines.
Pricing Analysis
Geographic price spreads between US cancer centers and China's provincial hospital networks reflect reimbursement differential and procurement sophistication gaps. Premium-mid-economy pricing differentiation separates FDA-cleared companion diagnostic assays from research-use-only reagents and unvalidated economy-tier imports. Pricing pressure stems from group purchasing organization consolidation in Texas and California health systems extracting multi-year supply commitments against volume guarantees. Hospital-affiliated diagnostic laboratories exhibit highest price sensitivity, while national reference laboratories in Massachusetts and California prioritize absolute quantification accuracy over per-test cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for thermal cycler components and fluorescent detection modules. Manufacturing concentrates in China for consumable plastics and reaction vessels, Germany for precision optical components, and the United States for enzyme master mixes and probe chemistries. Raw material dependencies center on Taq polymerase supply from specialized biochemical producers, fluorophore-dye intermediates, and medical-grade polypropylene for consumable vessels. Distribution runs through group purchasing organizations in consolidated US health systems and provincial procurement tenders under China's hospital tier reform mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiplex assay validation expertise and AI-assisted primer optimization capabilities represent scarce assets that concentrate competitive advantage among integrated platform vendors and specialized assay developers with reference laboratory partnerships.
For Market Incumbents: Pre-empt digital PCR substitution in oncology liquid biopsy workflows by accelerating absolute quantification platform placements in US cancer centers before CRISPR-based diagnostic methods gain regulatory validation depth. Secure backward integration into enzyme master mix production to buffer margin volatility from specialized biochemical supplier concentration. Anchor multi-year reagent supply contracts with instrument placement minimums to defend installed-base positions against isothermal amplification substitution in point-of-care infectious disease testing. For New Entrants and Emerging Players: Pursue Latin American laboratory network expansion in Brazil and Mexico where underpenetrated molecular diagnostics infrastructure and national cancer screening program expansion create instrument placement opportunities before ANVISA regulatory pathways mature. Target AI-assisted assay design software partnerships with mid-sized diagnostic laboratories seeking to compress multiplexed infectious disease panel development timelines without expanding regulatory affairs capacity. Lead with cloud-connected analytics platforms that address bioinformatics pipeline integration gaps in hospital networks with legacy IT infrastructure. For Investors and Strategic Acquirers: EU IVDR Class C device performance documentation requirements reshape the acquisition landscape toward assay developers with maintained clinical evidence packages and post-market surveillance capabilities. Long-term viability hinges on regulatory convergence between FDA and EMA on companion diagnostic co-development frameworks that synchronize approval opportunities across pharmaceutical partnerships. Acquisition target archetype: specialized assay content providers with national reference laboratory partnerships and validated multiplex respiratory pathogen panels. Signal to watch: NMPA domestic clinical trial requirement relaxation for imported PCR platforms that would compress registration timelines and expand addressable market for foreign manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA streamlined premarket review pathways accelerate pharmaceutical collaborations and expand reimbursable test menus in US cancer centers. |
| Digital PCR Platform Migration | Absolute quantification capabilities displace standard curve methods in precision oncology workflows and compress clinical validation timelines. |
| AI-Assisted Assay Design Investment | Machine learning convergence with primer optimization software reduces multiplexed infectious disease panel development timelines for mid-sized developers. |
| Provincial Hospital Network Procurement Capture | China's NMPA accreditation mandates drive high-throughput real-time PCR infrastructure deployment under national health reform. |
| Reagent-Instrument Bundling Strategy | Multi-year supply contracts tied to instrument placement minimums defend installed-base positions against integrated platform competitors. |
Research Methodology
Desk research of FDA premarket notification databases, EMA Class C device performance documentation, and NMPA registration filings preceded structured interviews with hospital laboratory directors, reference laboratory procurement managers, assay development executives, and regulatory affairs specialists across the United States, China, Germany, and Japan. Primary fieldwork with biomedical engineers and GPO contracts managers validated secondary findings on group purchasing organization consolidation patterns. Bottom-up test volume modeling across infectious disease, oncology, and genetic testing applications was triangulated against top-down instrument placement data from provincial hospital network tenders.
Assumptions held fixed include NMPA domestic clinical trial requirements for imported PCR platforms, FDA companion diagnostic co-development pathway stability, and EMA IVDR post-market surveillance enforcement intensity across the analysis window. Segmentation dimensions modeled encompass product type, application, end user, and technology with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from test volume growth trajectories weighted by reagent consumption intensity and instrument replacement cycle timing. Forecast inputs incorporated digital PCR adoption curves in US cancer centers and China's hospital tier reform procurement acceleration.
Sensitivities concentrate around NMPA regulatory relaxation timelines, isothermal amplification substitution rates in point-of-care settings, and enzyme supply concentration disruptions. Forecasts reflect documented assumptions on regulatory pathway stability and technology substitution thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Biopsy Devices Market