
 Ocular Allergy Diagnostic System Market | 2026-2036
Ocular Allergy Diagnostic System Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Allergy Diagnostic System Market Analytics
MDR compliance in Europe is broadening the cost-of-entry calculus for ocular diagnostic platforms entering clinical settings. Alcon leverages its ophthalmology channel depth to sustain instrument placement across European eye care networks. Bausch + Lomb anchors its competitive stance through specialized tear film analysis integration with allergy screening protocols. Novartis navigates regulatory complexity by positioning its diagnostic pipeline alongside established ophthalmic therapeutic franchises.
An ocular allergy diagnostic system comprises instruments, assays, and software platforms engineered to detect and quantify allergen-specific IgE, eosinophilic markers, and conjunctival inflammatory mediators in tear fluid or serum specimens, typically operating with sensitivity thresholds below 0.35 kU/L for precise allergen identification. These systems serve ophthalmologists and allergists by distinguishing seasonal, perennial, and vernal allergic conjunctivitis etiologies to guide targeted immunotherapy or pharmacologic intervention. Diagnostic Devices occupy the largest installed base due to capital-intensive ophthalmology suite configurations, while Lateral Flow Assay formats are expanding fastest among point-of-care settings seeking rapid turnaround without laboratory infrastructure. Home Care represents an emerging channel where self-administered test kits compete on convenience against traditional clinic-based workflows.
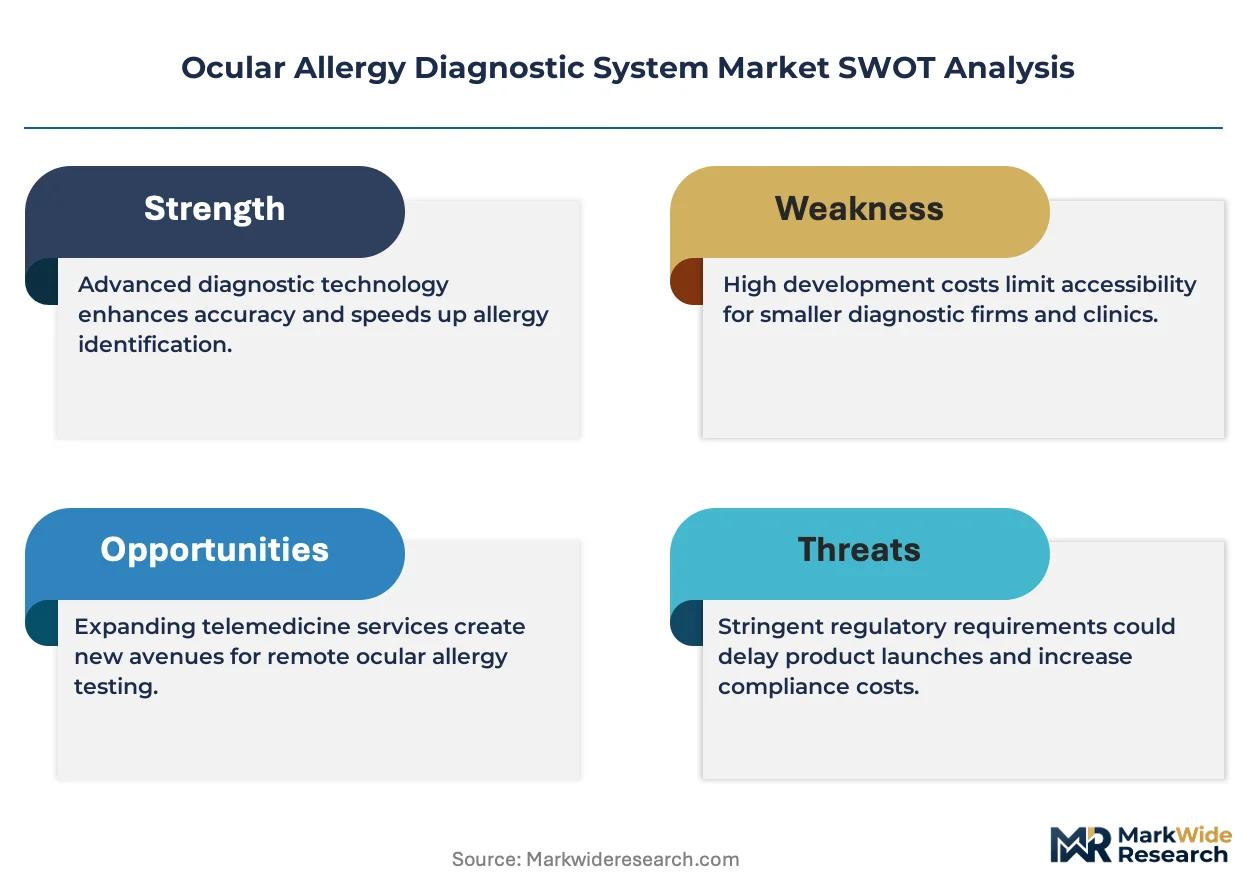
FDA oversight of in vitro diagnostic devices, combined with EMA's MDR enforcement and Japan's PMDA quality management requirements, shapes product development timelines and clinical validation burdens for manufacturers seeking multi-region commercialization. These regulatory frameworks elevate evidence standards for software-enabled diagnostic interpretations and algorithm-driven allergen panel recommendations. Stakeholders must monitor evolving harmonization gaps between FDA's proposed LDT rulemaking and EMA's companion diagnostic guidance to anticipate portfolio restructuring requirements.
Market Dynamics
Point-of-care allergen detection platforms are compressing traditional laboratory workflows as ophthalmology clinics prioritize rapid turnaround over centralized testing infrastructure. This structural shift reconfigures capital deployment and service economics across diagnostic networks.
Growth Catalysts
- EMA MDR enforcement:Stricter clinical evidence requirements for in vitro diagnostic devices elevate barriers for marginal competitors, consolidating purchasing power among established platform vendors.
- Tear fluid biomarker multiplexing:Advanced microfluidic cartridges now quantify eosinophilic cationic protein alongside specific IgE, expanding reimbursable test panels.
- Japan's metropolitan hospital networks:Seasonal allergic conjunctivitis prevalence drives recurring diagnostic volumes through dedicated ophthalmology corridors.
Market Restraints
- Reagent supply concentration:Polyclonal antibody production for allergen-specific assays clusters among limited European contract manufacturers, exposing procurement to batch variability.
- FDA LDT rulemaking uncertainty:Proposed reclassification of laboratory-developed tests threatens parallel regulatory pathways for customized allergen panels.
- Capital intensity of ophthalmology suite integration:Automated tear collection systems require dedicated plumbing and calibration infrastructure that smaller clinics defer.
Strategic Opportunities
- Home Care self-administration:Lateral flow assay formats with smartphone-readable results bypass clinic infrastructure entirely, capturing convenience-sensitive patients.
- EU AI Act compliance:Software-enabled diagnostic interpretation tools that meet algorithmic transparency standards gain preferential placement in reimbursed care pathways.
- Vernal keratoconjunctivitis detection:Specialized pediatric ophthalmology units seek differentiated biomarker signatures for severe allergic subtypes.
Industry Challenges
- Conjunctival sampling standardization:Tear collection technique variability between operators degrades assay reproducibility, complicating multi-site clinical validation.
- Cross-reactivity algorithm training:Machine learning models require geographically diverse allergen exposure datasets to minimize false-positive pollen panel results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Allergy Diagnostic System Market |
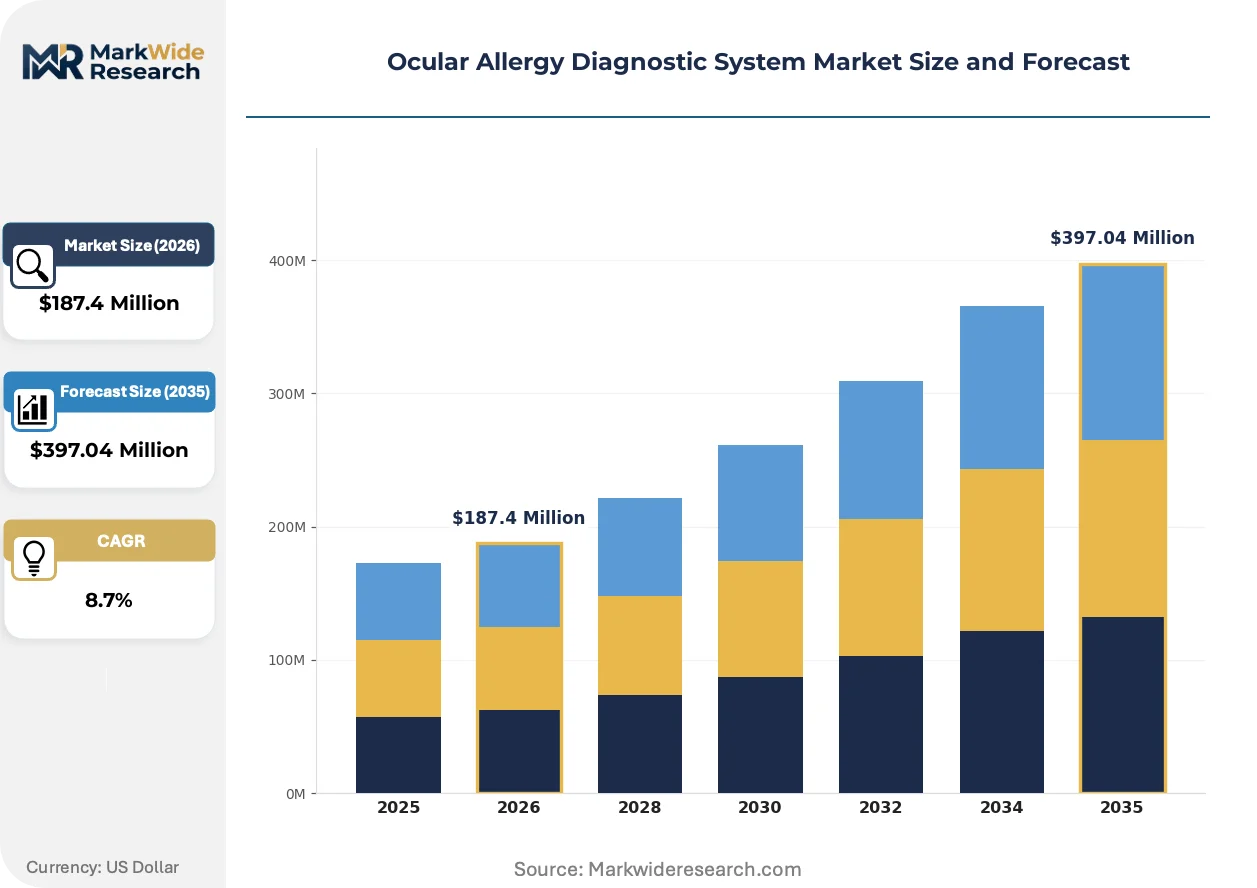
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Diagnostic Devices, Software Solutions, Reagents Technology: Enzyme-Linked Immunosorbent Assay, PCR, Lateral Flow Assay, Flow Cytometry End User: Hospitals, Diagnostic Labs, Home Care, Research Institutes Application: Allergy Testing, Environmental Monitoring, Clinical Research, Drug Development |
| Companies Covered | TearLab, Bausch + Lomb, Alcon, Allergan, OHR Pharmaceutical, Sylentis, Johnson & Johnson Vision Care, Novartis, Santen Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Allergy Diagnostic System Market Evolving Landscape
Multiplex biomarker quantification and software-interpreted results are dissolving boundaries between diagnostic hardware and clinical decision support. These convergences reshape how allergen panels are designed, validated, and reimbursed.
Microfluidic cartridge platforms is modularizing allergen-specific IgE detection into swappable biomarker modules. Academic medical centers in Germany and Japan are piloting configurable panels that match regional pollen calendars. This architecture compresses time-to-market for emerging allergen targets while reducing instrument obsolescence risk.
REACH substance restrictions on phthalate plasticizers are forcing re-engineering of tear collection device housings and assay cassettes. Manufacturers serving European ophthalmology networks must reformulate polymer compositions without compromising optical clarity for fluorescence detection. The transition elevates compliance costs disproportionately for single-product diagnostic specialists.
Subscription-based reagent provisioning is displacing capital purchase models in mid-sized ophthalmology practices. Diagnostic platforms now bundle consumables, software updates, and remote technical support into per-test fees. This shift concentrates vendor lock-in effects while smoothing cash flow volatility for clinic operators in Japan's competitive metropolitan markets.
Ocular Allergy Diagnostic System Market Segmentation
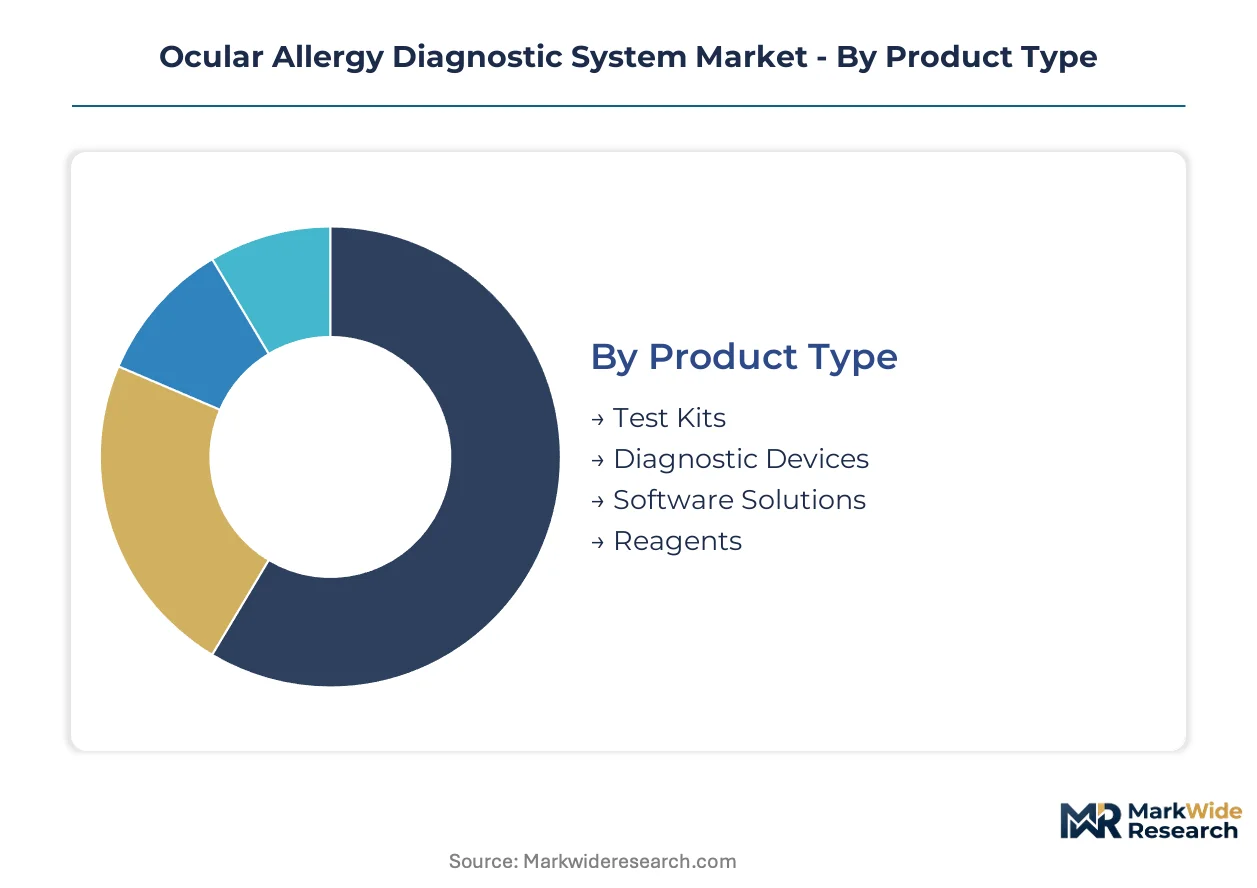
Segmentation in ocular allergy diagnostics reveals how technology choices, care settings, and workflow requirements fragment purchasing decisions across ophthalmology networks. Each axis exposes distinct margin profiles and regulatory burdens that reshape vendor go-to-market strategies.
Product Type:
Capital intensity and consumable economics diverge sharply across hardware-versus-reagent business models, with European MDR compliance costs disproportionately affecting instrument-heavy portfolios.
- Diagnostic Devices:Automated tear collection and analysis platforms integrate fluorescence detection optics with microfluidic sample processing. German ophthalmology clinics in the Rhine-Ruhr corridor prioritize these systems for high-throughput seasonal screening workflows. EMA MDR clinical evidence requirements extend validation timelines for new instrument launches.
- Test Kits:Disposable lateral flow cassettes with smartphone-readable results eliminate capital barriers for smaller practices. Japan's metropolitan hospital networks deploy these for rapid point-of-care allergen identification during peak pollen seasons. PMDA quality management audits concentrate on lot-to-lot antibody consistency.
- Software Solutions:Algorithm-driven allergen panel interpretation tools face EU AI Act transparency mandates for clinical decision support deployment.
- Reagents:Polyclonal antibody production for specific IgE detection clusters among limited European contract manufacturers, exposing supply to batch variability risks.
Diagnostic Devices lead on scale; Test Kits lead on momentum.
Technology:
Detection sensitivity thresholds and throughput requirements determine platform selection, with multiplexing capabilities now table stakes for academic medical center procurement.
- Enzyme-Linked Immunosorbent Assay:Laboratory-based quantitative IgE detection remains the reimbursement benchmark for allergist-ophthalmologist collaborative care. Reference labs in Japan and Germany maintain ELISA infrastructure for complex vernal keratoconjunctivitis workups. Batch processing economics favor centralized deployment over distributed point-of-care settings.
- Lateral Flow Assay:Single-use cartridges with visual or digital readouts compress turnaround times to under fifteen minutes. Home Care channels in Japan's urban prefectures are piloting self-administered formats with telemedicine result transmission. FDA's evolving LDT rulemaking creates uncertainty for customized panel configurations.
- PCR:Nucleic acid amplification for conjunctival pathogen differentiation addresses diagnostic overlap between allergic and infectious etiologies.
- Flow Cytometry:Eosinophil quantification in tear fluid supports severe subtype stratification in pediatric ophthalmology units.
ELISA dominates reimbursed volume; Lateral Flow Assay climbs the fastest.
End User:
Care setting determines regulatory pathway complexity, with hospital procurement committees imposing validation standards that smaller clinics bypass.
- Hospitals:Integrated ophthalmology-allergy departments in Japan's metropolitan networks drive recurring diagnostic volumes through dedicated seasonal screening corridors. Capital purchase committees demand multi-year total cost-of-ownership analyses that favor subscription-based reagent provisioning.
- Home Care:Self-administered test kits with smartphone-integrated results bypass clinic infrastructure entirely. German regulatory pathways for direct-to-consumer diagnostic devices remain fragmented across federal state interpretations.
- Diagnostic Labs:Centralized processing economics concentrate allergen panel volume in reference laboratory networks.
- Research Institutes:Academic medical centers in Germany pilot configurable biomarker modules matching regional pollen calendars.
Hospitals anchor installed base; Home Care gains share fastest.
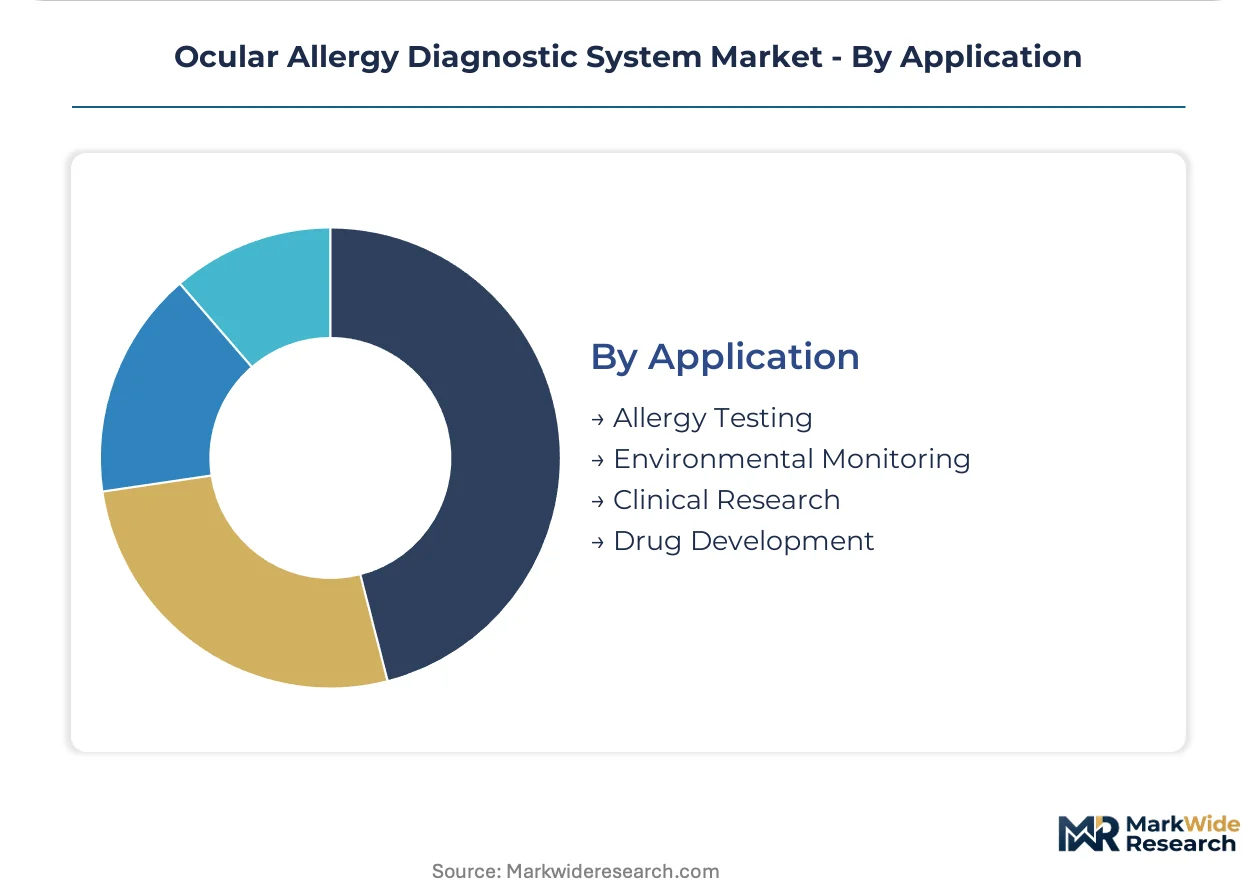
Application:
Reimbursement codes and clinical utility evidence requirements segment demand between routine diagnostic workflows and specialized research use cases.
- Allergy Testing:Specific IgE quantification and eosinophilic marker detection constitute the core reimbursable activity across ophthalmology practices. Seasonal allergic conjunctivitis prevalence in Japan's urban corridors sustains recurring test volumes through predictable pollen calendar patterns.
- Drug Development:Biomarker stratification for clinical trial enrollment demands higher analytical sensitivity than routine diagnostic settings. Pharmaceutical sponsors in Germany require ISO 15189-accredited laboratory partners for regulatory submission support.
- Environmental Monitoring:Population-level allergen exposure surveillance supports public health forecasting without individual diagnostic reimbursement.
- Clinical Research:Academic protocols for vernal keratoconjunctivitis natural history studies drive specialized assay development.
Allergy Testing commands volume concentration; Drug Development shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ophthalmology specialists and Japanese allergist-ophthalmologist collaborative networks anchor diagnostic platform deployment. These workforce concentrations concentrate purchasing authority within metropolitan hospital procurement committees.
United States
Academic medical centers in Boston and the Research Triangle drive biomarker validation studies for tear fluid multiplexing. FDA's evolving in vitro diagnostic device classification framework extends clinical evidence requirements for algorithm-driven allergen panel tools. The Mayo Clinic corridor in Minnesota pilots subscription-based reagent provisioning models for mid-sized ophthalmology practices.
Germany
Rhine-Ruhr ophthalmology clinics prioritize high-throughput seasonal screening workflows during peak pollen periods. EMA MDR enforcement elevates validation timelines and compliance costs for instrument manufacturers. The Munich-Stuttgart corridor hosts contract manufacturers specializing in polyclonal antibody production for allergen-specific assays.
Japan
Metropolitan hospital networks in Tokyo and Osaka sustain recurring diagnostic volumes through dedicated seasonal allergic conjunctivitis screening corridors. PMDA quality management audits concentrate on lot-to-lot antibody consistency for lateral flow assay formats. Kansai-region ophthalmology departments pilot smartphone-integrated self-administered test kits with telemedicine result transmission.
Switzerland
Basel-area pharmaceutical sponsors demand ISO 15189-accredited laboratory partners for biomarker stratification in clinical trial enrollment. Swissmedic oversight harmonizes with EMA guidance while maintaining distinct quality management requirements for diagnostic software. The Zurich-Geneva corridor concentrates specialized pediatric ophthalmology units seeking vernal keratoconjunctivitis detection capabilities.
United Kingdom
London and Southeast England hospital procurement committees impose multi-year total cost-of-ownership analyses favoring subscription-based service models. MHRA post-Brexit regulatory pathways create parallel validation requirements for software-enabled diagnostic interpretation tools. The Oxford-Cambridge arc pilots configurable microfluidic cartridge platforms matching regional pollen calendars.
Ocular Allergy Diagnostic System Market Competitive Landscape
The competitive structure tilts toward diversified ophthalmology conglomerates with established therapeutic franchises. Instrument manufacturers and assay developers occupy distinct tiers based on capital intensity and consumable economics. Three archetypes dominate: integrated eye care conglomerates leveraging channel depth, specialized diagnostic platform vendors, and contract reagent manufacturers. M&A activity concentrates on point-of-care technology acquisition and regional distribution rights consolidation.
Within the integrated conglomerate tier, Alcon and Bausch + Lomb occupy positions anchored by ophthalmology suite configurations and tear film analysis integration. Novartis sits within the therapeutic-aligned diagnostic pipeline archetype, navigating regulatory complexity alongside established pharmaceutical franchises. These three entities exemplify how channel presence and franchise adjacency determine competitive positioning in reimbursed care pathways.
| Leading Market Players |
|---|
| TearLab |
| Bausch + Lomb |
| Alcon |
| Allergan |
| OHR Pharmaceutical |
| Sylentis |
| Johnson & Johnson Vision Care |
| Novartis |
| Santen Pharmaceutical |
| Others |
Value Network & Pricing Analysis
Captive antibody production in Germany and Switzerland anchors both supply security and premium pricing power for allergen-specific assay manufacturers serving European ophthalmology networks. This backward integration into polyclonal antibody manufacturing insulates vendors from batch variability risks while supporting subscription-based reagent provisioning at price points that smaller competitors cannot match.
Pricing Analysis
Bundled subscription models now dominate mid-sized ophthalmology practices, with per-test fees covering consumables, software updates, and remote calibration support. Unbundled capital purchase arrangements persist only in academic medical centers with dedicated biomedical engineering staff. Price differentiation hinges on EMA MDR certification tier and the depth of telemedicine integration for result transmission. Pricing pressure stems from REACH compliance costs for phthalate-free polymer re-engineering, which compresses margins disproportionately for single-product specialists. Home Care self-administration channels exhibit the highest price sensitivity, while hospital procurement committees prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Freight cost volatility for temperature-controlled antibody shipments from Germany, Switzerland, and the Netherlands elevates landed costs for Asian and North American diagnostic platforms. Polyclonal antibody production draws from European contract manufacturers clustered in the Munich-Stuttgart corridor. Microfluidic cartridge substrates source from specialized polymer processors in Japan and Germany. Single-source vulnerability concentrates in polyclonal antibody lots, where batch-to-batch consistency failures trigger assay revalidation cycles. Distribution runs through ophthalmology GPOs in Japan, hospital procurement committees in Germany, and direct-to-clinic field service teams in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ocular allergy diagnostics rests on software-enabled interpretation tools that command premium tier placement through EU AI Act compliance, while reagent subscription models capture recurring revenue streams that offset capital purchase deferrals.
For Market Incumbents: Acquire point-of-care lateral flow assay platforms to fill portfolio gaps against emerging home diagnostic entrants. Consolidate regional distribution rights in Japan's metropolitan hospital networks before PMDA quality management audits intensify. Backward integration into polyclonal antibody production insulates against European contract manufacturer concentration and supports subscription pricing integrity. For New Entrants and Emerging Players: The premium-economy price-point gap in self-administered test kits offers white-space capture for smartphone-integrated formats with telemedicine result transmission. Target German federal state regulatory pathways where direct-to-consumer diagnostic device interpretations remain fragmented. Vernal keratoconjunctivitis pediatric detection represents the most penetrable specialized segment, with academic medical centers piloting configurable biomarker modules. For Investors and Strategic Acquirers: Roll-up economics work for specialized diagnostic platform vendors because EMA MDR compliance costs disproportionately burden single-product specialists, creating distressed acquisition opportunities. Five-to-ten year viability favors vendors with software companion diagnostic pipelines alongside established ophthalmic therapeutic franchises. Watch FDA LDT rulemaking finalization as the inflection signal for customized allergen panel pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR clinical evidence requirements extend validation timelines for algorithm-driven interpretation tools entering European ophthalmology networks. |
| Hospital System Partnership | Subscription-based reagent provisioning with Japanese metropolitan hospital procurement committees smooths cash flow volatility and concentrates vendor lock-in. |
| Software Companion Development | EU AI Act transparency mandates for clinical decision support tools create preferential placement pathways in reimbursed care corridors. |
| Backward Integration into Antibody Production | Captive polyclonal manufacturing in the Munich-Stuttgart corridor insulates assay consistency from European contract manufacturer batch variability. |
| Reimbursement Strategy | Specific IgE quantification panel coding alignment with seasonal allergic conjunctivitis prevalence patterns in Japan sustains recurring test volumes. |
Research Methodology
Direct dialogue with ophthalmology department heads, allergy-immunology clinic directors, diagnostic platform product managers, and hospital GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, PMDA quality management audit reports, and Japanese metropolitan hospital procurement databases. Bottom-up instrument placement counts and top-down allergy prevalence epidemiology were triangulated to anchor market sizing.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through the projection horizon. CAGRs were derived from instrument replacement cycles, reagent consumption rates per installed base unit, and geographic expansion trajectories of point-of-care platforms. Tear fluid biomarker multiplexing adoption curves and EU AI Act compliance timelines fed scenario-weighted forecast inputs.
Caveats apply where FDA LDT rulemaking finalization, REACH substance restriction enforcement, or PMDA audit intensity shifts could materially shift the outlook. Forecasts reflect documented assumptions about pollen season predictability and ophthalmology clinic capital expenditure recovery patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
GCC Breath Analyzer Market