
 Injection Molding Machine Market | 2026-2036
Injection Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Molding Machine Market Analysis
Modular cell configurations is expanding as Tier-1 automotive suppliers unbundle machine purchases from integrated automation packages, letting buyers mix vendors. Engel Austria GmbH leverages its tie-rod-free clamping architecture to anchor premium electric machine contracts with medical device molders. Haitian International Holdings Limited dominates cost-competitive hydraulic and hybrid output from its Ningbo manufacturing base. KraussMaffei Group differentiates through dual-platen technology and sustained R&D intensity in large-part applications.
An injection molding machine applies clamping force to hold a metal mold closed while molten thermoplastic or thermoset material is injected under pressure, cooled, and ejected as a finished part; clamp tonnage ranges from under 50 tons for precision electronics to over 4,000 tons for automotive bumper production. Electric machines command the highest precision and energy efficiency margins in medical and electronics end use, while hybrid systems capture growing share among automotive buyers seeking balance of speed and power. Horizontal molding technology occupies the volume core across consumer goods and packaging, with multi-component molding expanding fastest in automotive interior soft-touch applications.
The EU F-Gas Regulation and REACH compliance frameworks constrain hydraulic fluid formulations and refrigerant choices in European-sold equipment, pushing OEMs toward sealed electric architectures. China's GB energy efficiency standards and MIIT industrial upgrading directives enforce stricter motor and drive specifications on domestically manufactured machines. Japan's METI carbon neutrality roadmap shapes procurement criteria for domestic molders supplying Toyota and Honda supply chains. Stakeholders must monitor how regional decarbonization timelines reshape total cost of ownership calculations across machine replacement cycles.
Market Dynamics
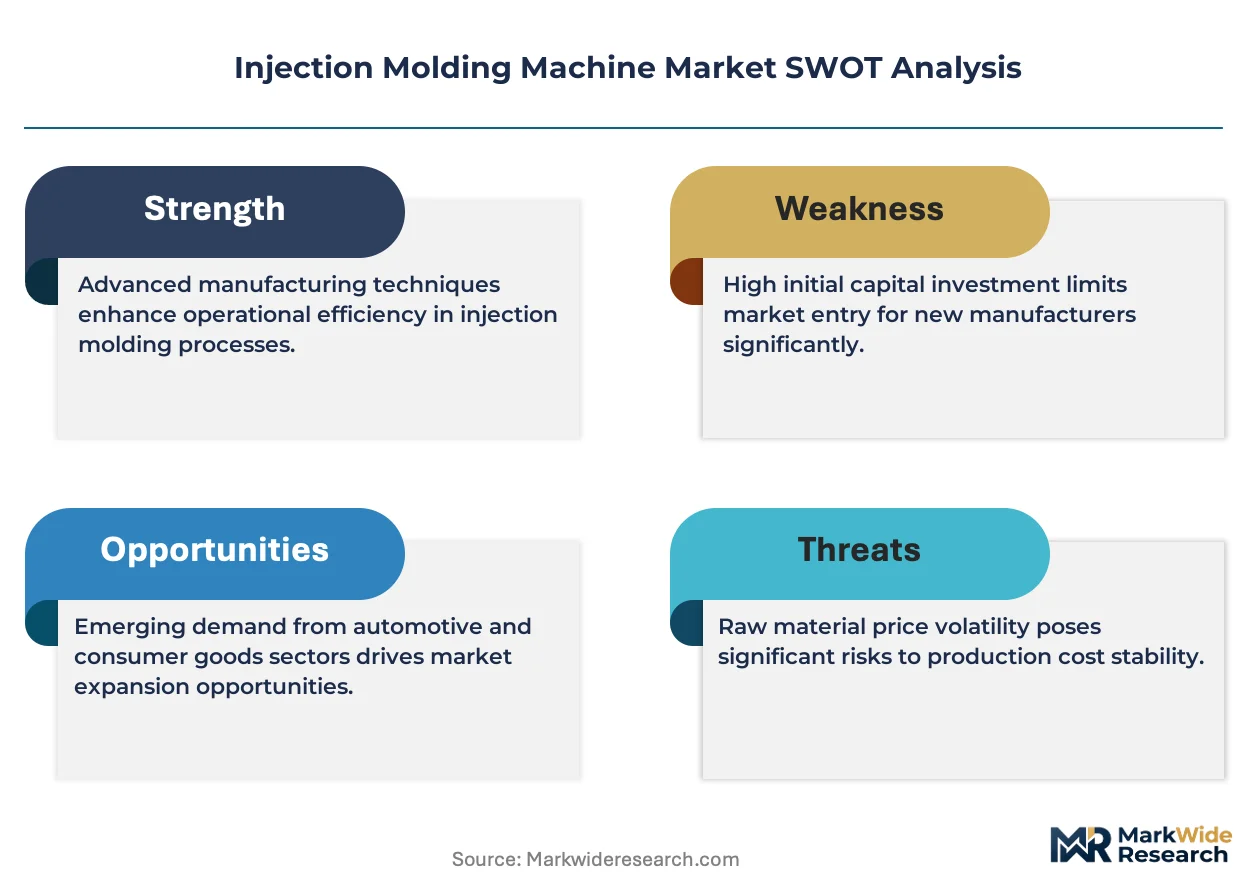
Automotive lightweighting mandates and medical precision requirements are bifurcating demand toward electric servo-driven architectures while hydraulic systems retreat to commodity packaging applications.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases in European manufacturing equipment accelerates replacement of hydraulic systems with sealed electric injection units.
- Medical device molding:ISO 13485-certified cleanroom production demands sub-micron repeatability that only all-electric clamping and injection systems deliver.
- Ningbo plastics cluster concentration:Export-oriented Chinese packaging molders aggregate demand for large-tonnage hybrid systems serving global consumer goods brands.
Market Restraints
- Copper and rare-earth magnet costs:Electric machine motor assemblies face input volatility from concentrate supply concentrated in DRC and Chinese processing facilities.
- REACH compliance friction:Hydraulic fluid reformulation timelines lag machine replacement cycles, stranding capital in legacy architectures.
- Technical ceiling in large-part molding:Electric servo motors above 4,000 kN encounter torque density limits that hybrid systems still overcome.
Strategic Opportunities
- India PLI scheme for medical devices:Domestic production-linked incentives attract molding capacity for export-grade syringe and consumable manufacturing.
- Convergence of Industry 4.0 and predictive maintenance:Sensor-embedded clamping units enable uptime-based service contracts displacing traditional spare parts revenue.
- Thailand automotive supplier base:Japanese OEM supply chain relocation from China creates greenfield demand for multi-component interior molding cells.
Industry Challenges
- Mechatronics technician scarcity:Electric machine commissioning and servo drive calibration require skills absent in legacy hydraulic service networks.
- CE MDR certification timelines:Medical device molders face 18-24 month validation cycles for new machine qualifications, compressing effective equipment life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Molding Machine Market |
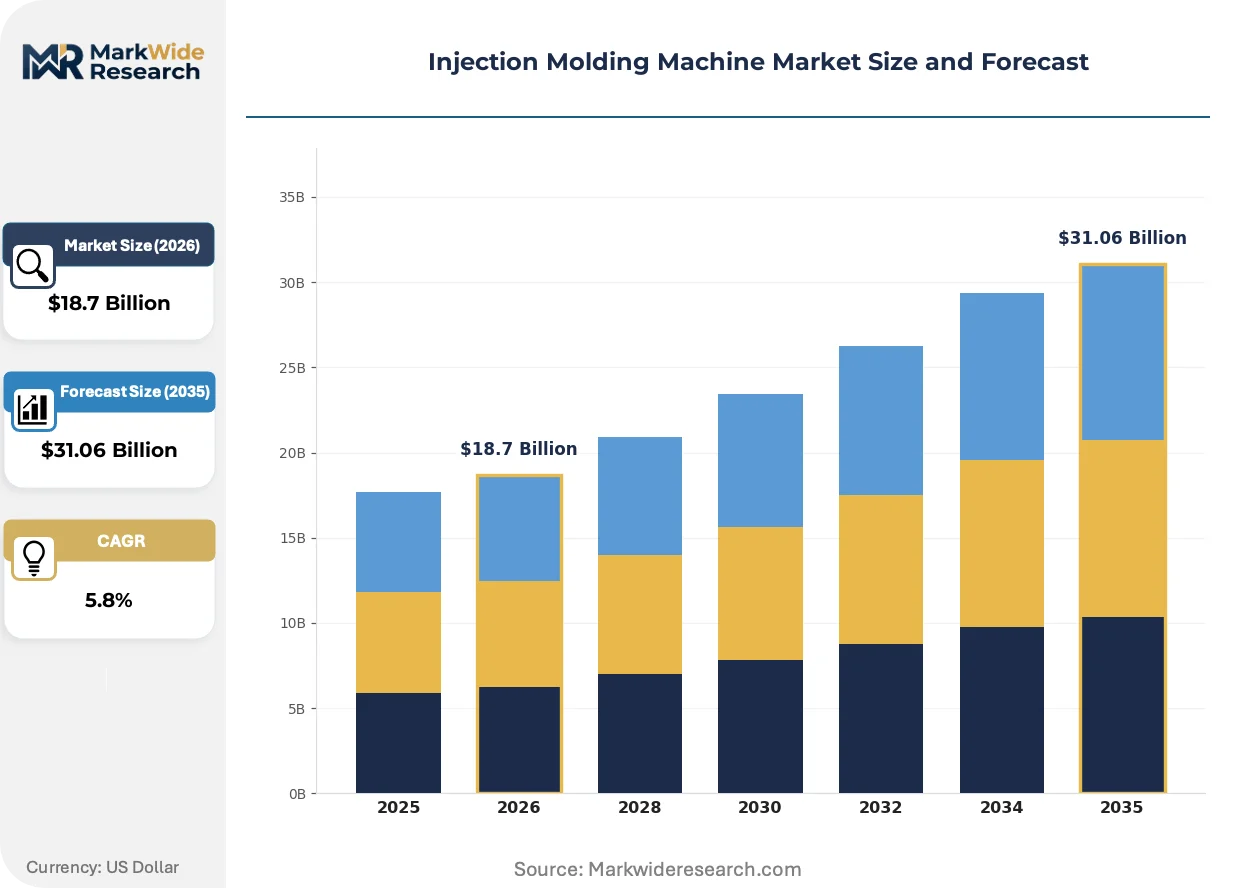
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Hybrid, Others Technology: Vertical Molding, Horizontal Molding, Multi-component Molding, Coreback Molding End User: Automotive, Consumer Goods, Electronics, Medical Size: Small, Medium, Large, Extra-large |
| Companies Covered | Haitian International Holdings Limited, Arburg GmbH + Co KG, Engel Austria GmbH, Milacron, Fanuc, Chen Hsong Holdings Limited, KraussMaffei Group, Nissei Plastic Industrial Co., Limited, Sumitomo (SHI) Demag Plastics Machinery GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Molding Machine Market Emerging Trajectories
Control system digitization and servo motor cost curves are collapsing the price premium between electric and hydraulic architectures faster than OEMs anticipated.
All-electric injection units with direct-drive servo motors is absorbing the precision medical and electronics segments that once tolerated hydraulic inefficiency for capital cost reasons. Medical device molders in Switzerland and Germany now specify electric architectures as baseline procurement criteria. The technology is absorbing service revenue streams as predictive algorithms replace scheduled maintenance contracts.
China's GB energy efficiency standards for industrial motors enforce IE4 efficiency minimums on domestically manufactured injection molding equipment. MIIT industrial upgrading directives tie subsidy eligibility to smart manufacturing readiness levels. Domestic Chinese OEMs respond by integrating indigenous servo drives to avoid imported motor cost exposure.
Buyer unbundling of automation packages from machine purchases lets Tier-1 automotive suppliers mix vendor equipment within single production cells. Tier-1 suppliers in Germany and Japan now procure clamping units, robots, and quality systems from separate specialists. This pattern concentrates most visibly in bumper and fascia production lines where cycle time optimization overrides single-source convenience.
Injection Molding Machine Market Segmentation
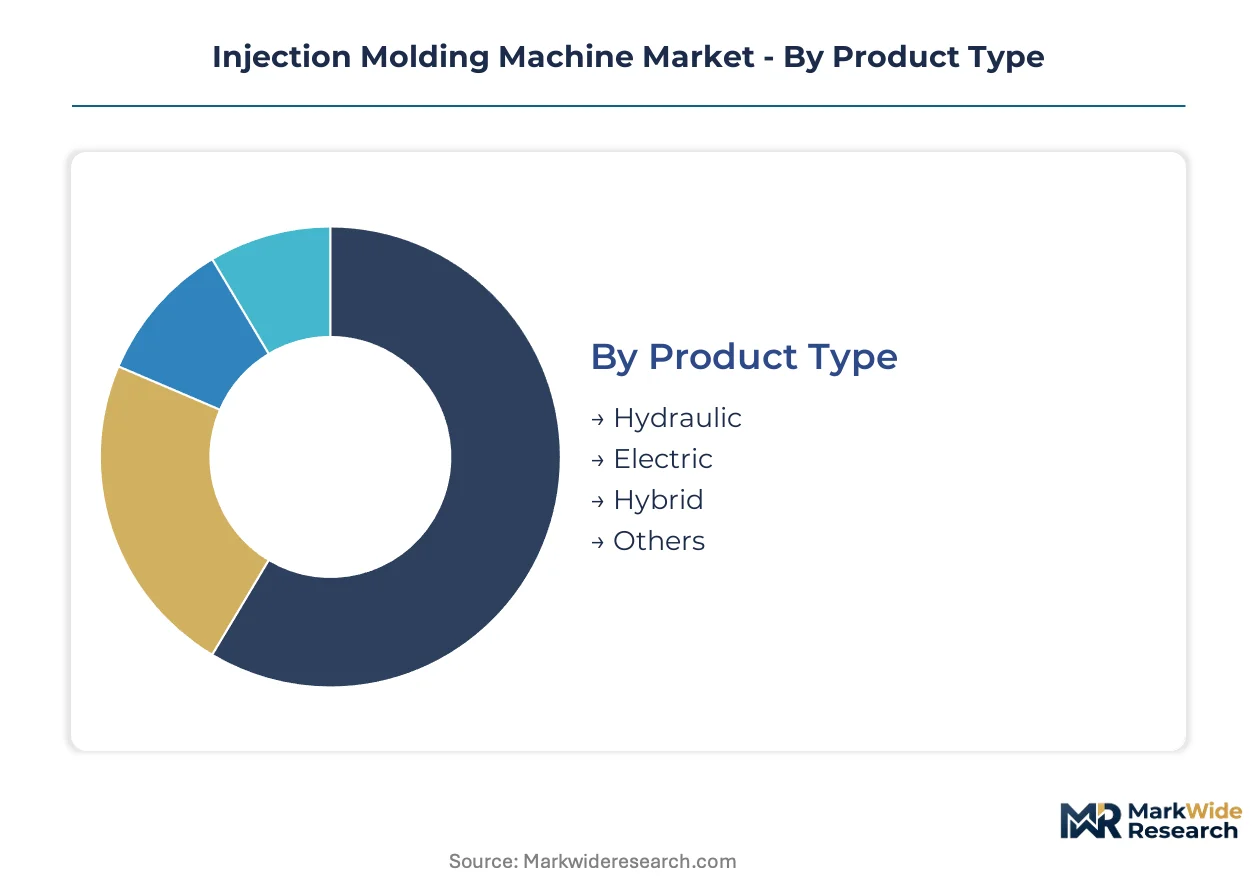
Machine architecture, clamping orientation, end-use precision requirements, and tonnage class collectively determine procurement economics and service lifecycle value. Buyers trade capital cost against energy efficiency, part complexity, and regulatory compliance across these four dimensions.
Product Type:
Customization intensity spans sealed electric architectures at the premium extreme to commodity hydraulic platforms at the standardized base.
- Electric:Direct-drive servo motors eliminate hydraulic fluid circuits, delivering sub-micron repeatability for ISO 13485-certified medical production. Swiss and German device molders specify all-electric systems as baseline procurement criteria. Demand concentrates in cleanroom environments where F-Gas Regulation compliance eliminates hydraulic alternatives.
- Hybrid:Combines electric screw drive with hydraulic clamping, balancing speed and power for automotive interior and bumper applications. China's Ningbo plastics cluster aggregates procurement of large-tonnage hybrid systems serving export-oriented packaging molders. The architecture captures buyers seeking mid-range precision without full electric capital cost.
- Hydraulic:Open-loop fluid power systems dominate commodity packaging and construction material molding where precision tolerances relax.
- Others:Pneumatic and specialized thermoset configurations serve niche rubber and composite applications.
Leading the category by volume: Hydraulic. Growing fastest: Electric.
Technology:
Volume distribution tracks part orientation requirements, with horizontal platforms serving high-throughput consumer goods and vertical systems addressing insert molding complexity.
- Horizontal Molding:Clamping units open parallel to the floor, enabling automated part removal and robot integration at cycle times under 10 seconds. Consumer goods and packaging producers in Germany and Japan specify horizontal architectures for 24/7 production economics. The technology anchors Industry 4.0 retrofit programs with sensor-embedded platens.
- Multi-component Molding:Twin-barrel configurations inject dissimilar materials sequentially, producing soft-touch automotive interiors without secondary assembly. Toyota and Honda supply chains in Thailand drive greenfield demand for multi-component cells as Japanese OEMs relocate capacity from China. Medical device producers leverage the technology for drug-device combination products.
- Vertical Molding:Gravity-assisted mold loading suits insert molding of metal electrical components and medical tubing hubs.
- Coreback Molding:Retractable core mechanisms enable thick-wall optical lenses and hollow automotive ducting.
Horizontal Molding dominates unit shipments. Multi-component Molding climbs the fastest as automotive interior specifications harden.
End User:
Margin structure inverts across this category, with medical and electronics commanding premium pricing and automotive negotiating on scale.
- Automotive:Bumper, fascia, and structural component production consumes 4,000+ kN clamping capacity across tier-1 supplier networks. German and Japanese lightweighting programs accelerate electric and hybrid machine procurement as aluminum and composite substitution intensifies. Tier-1 suppliers unbundle automation packages, mixing vendor equipment within single cells.
- Medical:Syringe, inhaler, and surgical instrument molding demands ISO 13485-certified cleanroom compatibility and CE MDR validation timelines. India's PLI scheme for medical devices attracts molding capacity for export-grade consumable manufacturing. 18-24 month machine qualification cycles compress effective equipment life.
- Electronics:Connector and housing production requires sub-50 ton precision for miniaturized components.
- Consumer Goods:Commodity packaging and household item molding prioritizes throughput over dimensional tolerance.
Automotive leads absolute unit demand. Medical expands most quickly on regulatory tailwinds and reshoring incentives.
Size:
Capital intensity and customer concentration rise with tonnage class, concentrating supplier power in extra-large segments.
- Large:1,000-4,000 kN clamping force serves automotive bumper, appliance housing, and industrial container production. KraussMaffei and Engel anchor premium contracts through dual-platen and tie-rod-free architectures. Electric servo motors above 4,000 kN encounter torque density limits that hybrid systems still overcome.
- Small:Under 500 kN machines address electronics connectors, medical micro-components, and precision gear production. Haitian International dominates cost-competitive output from its Ningbo manufacturing base. The segment absorbs fastest technology refresh cycles as servo motor cost curves collapse price premiums.
- Medium:500-1,000 kN range captures general-purpose packaging and consumer durable applications.
- Extra-large:Exceeding 4,000 kN for automotive structural components, pallets, and waste containers.
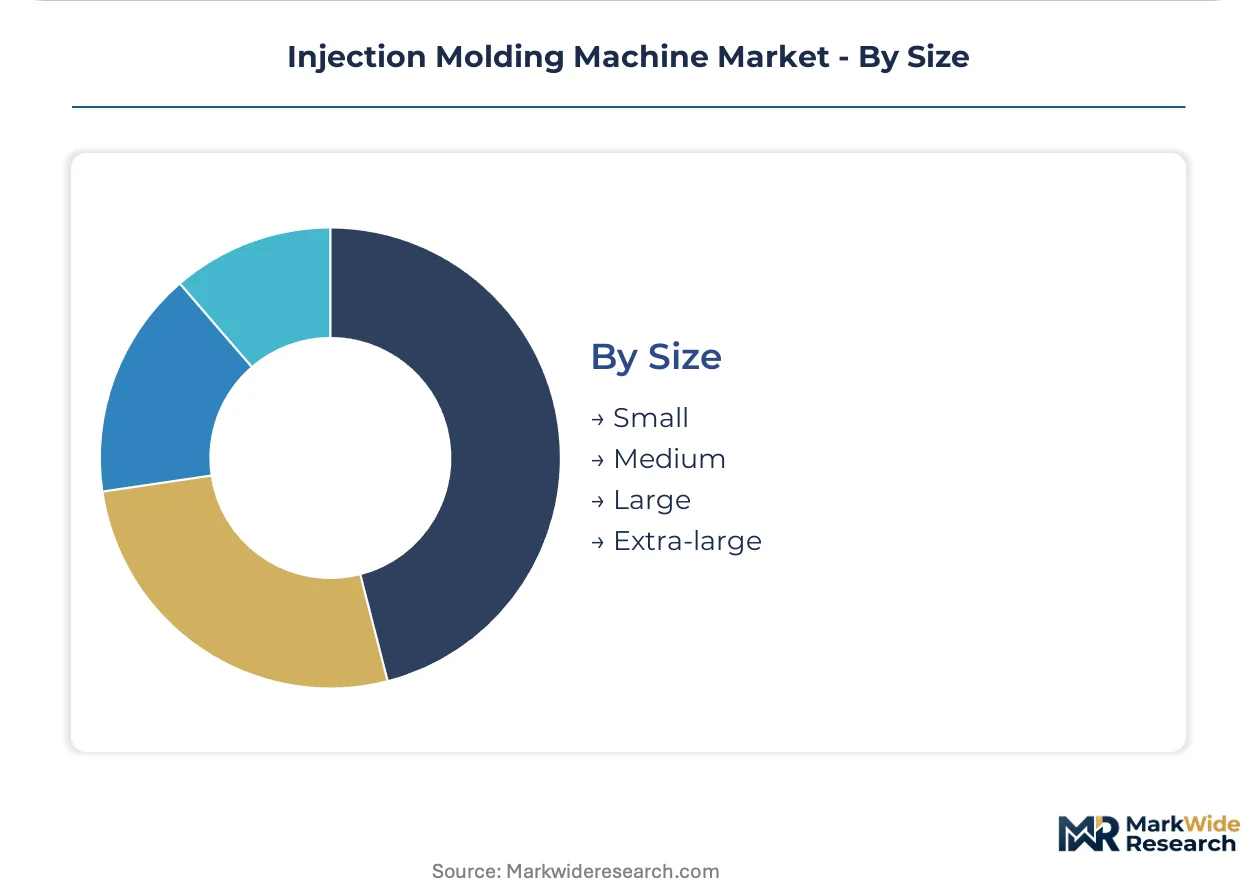
Medium tonnage leads volume shipments. Small tonnage gains share fastest on electronics miniaturization and medical device proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo's plastics machinery cluster concentrates China's export-oriented molding capacity, while special economic zones in Thailand and India's medical device parks reshape procurement geography.
China
Export packaging molders aggregate demand for large-tonnage hybrid systems in the Ningbo plastics cluster. MIIT industrial upgrading directives enforce IE4 motor efficiency minimums on domestically manufactured equipment. Domestic OEMs integrate indigenous servo drives to avoid imported component cost exposure.
Germany
Automotive lightweighting programs accelerate electric and hybrid machine procurement among tier-1 suppliers. The EU F-Gas Regulation phases down fluorinated greenhouse gases in manufacturing equipment, pushing OEMs toward sealed electric architectures. Stuttgart and Munich anchor premium machine contracts with medical device molders requiring sub-micron repeatability.
Japan
Toyota and Honda supply chains drive precision molding requirements through METI's carbon neutrality roadmap. JIS standards and domestic procurement criteria shape machine specifications for automotive interior applications. Nagoya and Osaka concentrate multi-component molding demand as OEMs relocate capacity from China.
United States
Medical device producers in Minnesota and California specify ISO 13485-certified cleanroom compatibility for syringe and inhaler manufacturing. FDA quality system regulations extend validation timelines for new machine qualifications. The Midwest automotive corridor sustains demand for large-tonnage systems serving bumper and structural component production.
India
The PLI scheme for medical devices attracts molding capacity for export-grade syringe and consumable manufacturing. CDSCO regulatory frameworks align with international standards for cleanroom production. Gujarat and Maharashtra medical device parks concentrate greenfield investment in precision electric architectures.
Injection Molding Machine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. The market structure consolidates around scale-driven volume producers, technology-differentiated premium vendors, and regional cost leaders. Strategic archetypes include integrated automation providers, component specialists, and hybrid-electric transition enablers. M&A activity and capacity expansion dominate competitive moves as players defend position in electrifying segments.
Within the premium technology tier, Engel Austria GmbH and KraussMaffei Group occupy positions defined by proprietary clamping architectures and sustained R&D intensity. Haitian International Holdings Limited anchors the cost-competitive volume segment from its Ningbo manufacturing base. Among Japanese precision specialists, Nissei Plastic Industrial Co., Limited and Sumitomo (SHI) Demag Plastics Machinery GmbH exemplify the servo-drive expertise concentrated in automotive and medical supply chains.
| Leading Market Players |
|---|
| Haitian International Holdings Limited |
| Arburg GmbH + Co KG |
| Engel Austria GmbH |
| Milacron |
| Fanuc |
| Chen Hsong Holdings Limited |
| KraussMaffei Group |
| Nissei Plastic Industrial Co., Limited |
| Sumitomo (SHI) Demag Plastics Machinery GmbH |
| Others |
Supply Flow & Price Mechanics
Captive servo motor production at Haitian International's Ningbo complex anchors both supply security and cost leverage against imported drive assemblies from Japanese and European sources. This vertical integration choice insulates the volume tier from rare-earth magnet price volatility while forcing premium OEMs to compete on service bundling rather than component sourcing.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to electric machine orders from German and Japanese medical molders facing CE MDR certification deadlines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified architectures from general-purpose hybrids and commodity hydraulic platforms. Pricing pressure stems from collapsing servo motor cost curves compressing electric-to-hydraulic premiums faster than OEMs anticipated. Automotive tier-1 suppliers exhibit highest price sensitivity, while medical device producers prioritize repeatability over capital cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota and Honda supply chains, while distributor networks serve mid-tier packaging molders. Manufacturing concentrates in China, Germany, and Japan, with Ningbo anchoring volume output and Stuttgart-Nagoya corridor dominating precision architectures. Copper windings and neodymium magnets draw from concentrate supply concentrated in DRC and Chinese processing facilities. Single-source vulnerability in rare-earth magnet refining creates supply chain risk. Distribution runs through authorized service partners for commissioning and aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric servo motor capacity constraints prop pricing power for OEMs with captive drive production, while mechatronics technician scarcity extends commissioning lead times. Supply bottlenecks in precision ball screw and linear guide assemblies reinforce order backlogs at premium tier suppliers.
For Market Incumbents: Hedge against servo motor cost curve compression by deepening aftermarket service revenue through predictive maintenance contracts. Anchor premium positioning with tie-rod-free or dual-platen patent portfolios. Capacity addition in Thailand captures Japanese OEM supply chain relocation from China. Certification investment in ISO 13485 cleanroom compatibility defends medical segment share against emerging Chinese electric specialists. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized medical device parks where domestic molding capacity lags syringe export demand. Target underpenetrated multi-component molding applications in Thai automotive interior supply chains. Partner with indigenous servo drive suppliers to bypass imported motor cost exposure and accelerate electric machine cost parity. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking plastics machinery platform expansion. Long-term viability favors OEMs with captive servo drive production and installed base density for recurring service revenue. Acquisition target archetype: mid-tier hybrid-electric specialists with regional service networks and medical certification pipelines. Watch Ningbo cluster consolidation activity as inflection indicator for volume-tier pricing discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Production | Haitian International's indigenous motor manufacturing avoids imported component cost exposure from Japanese suppliers. |
| CE MDR Certification Investment | Engel Austria and KraussMaffei anchor premium medical contracts through validated cleanroom architectures. |
| Thailand Manufacturing Footprint Expansion | Japanese OEM supply chain relocation from China creates greenfield demand for multi-component molding cells. |
| Predictive Maintenance Platform Launch | Sensor-embedded clamping units enable uptime-based service contracts displacing traditional spare parts revenue. |
| Joint Venture with Indigenous Drive Suppliers | Domestic Chinese OEMs integrate local servo technology to meet MIIT IE4 efficiency mandates. |
Methodological Framework
Independent corroboration across OEM sales directors, tier-1 automotive procurement managers, and medical device manufacturing engineers underwrites the qualitative findings. Primary interviews with maintenance directors at German packaging molders and plant engineers at Ningbo export facilities combined with secondary validation from MIIT industrial policy filings, EU F-Gas Regulation implementation guidance, and SEC 10-K disclosures from listed machinery manufacturers. Bottom-up unit shipment tallies triangulate against top-down market value estimates across machine architecture segments.
Comparable-period anchoring to historical replacement cycle data and energy efficiency upgrade patterns shapes the projection horizon. The analytical framework models demand across electric, hybrid, and hydraulic architectures; horizontal, vertical, and multi-component technologies; and automotive, medical, electronics, and consumer goods end uses. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include copper and rare-earth magnet price trajectories, regional decarbonization timeline enforcement, and automotive lightweighting program intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to DRC supply disruptions and REACH hydraulic fluid reformulation delays. Forecasts reflect documented assumptions regarding servo motor cost curve progression and MIIT subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Concrete Block Making Machines Market