
 Energy Efficient Lighting Technology Market | 2026-2036
Energy Efficient Lighting Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Lighting Technology Market Intelligence
The emergence of Lighting-as-a-Service (LaaS) models, which shift capital expenditure to operational expenditure for end-users, is rewriting the competitive landscape. This service-based approach allows new entrants to compete on operational expertise rather than just product sales. Signify N.V. leverages its extensive portfolio to offer comprehensive LaaS packages for large commercial clients. Acuity Brands, Inc. differentiates through its integrated controls and building management system compatibility.
Energy efficient lighting technology refers to illumination sources that maximize lumen output per watt, primarily using solid-state principles. Its purpose is to reduce electricity consumption and operational costs for end-users. LED products dominate the product type segment due to superior longevity and efficiency. Within the technology landscape, smart lighting with advanced controls represents the fastest-growing category, driven by demand for connected building systems.
Regulatory frameworks from the US EPA, via its ENERGY STAR program, and the European Union, through its Ecodesign Directive, establish minimum performance thresholds. These mandates, along with China's GB standards, accelerate the phase-out of inefficient technologies and dictate design specifications for market entry. Future competitive advantage hinges on integrating lighting solutions into broader IoT and smart building ecosystems.
Market Dynamics
The market's central dynamic is the transition from standalone hardware sales to integrated, service-based models. This shift is driven by the convergence of lighting with IoT platforms, making data and control as valuable as the light itself.
Growth Catalysts
- Regulatory Mandates:The European Union's Green Deal establishes stringent energy performance standards for buildings, compelling owners to invest in efficient lighting systems to comply with new construction and renovation codes.
- Commercial Retrofits:Demand from commercial real estate for retrofitting existing office, retail, and industrial spaces to reduce electricity consumption and operational expenditures is a primary market driver.
- Infrastructure Investment:Government policies in China supporting large-scale infrastructure projects and industrial efficiency improvements create concentrated demand for energy efficient lighting technologies.
Market Restraints
- High Initial Cost:The significant upfront capital investment required for large-scale LED retrofits can be a substantial barrier for small and medium-sized enterprises without access to financing or incentive programs.
- Supply Chain Concentration:Heavy reliance on a few geographies, particularly China, for the production of LED chips and associated electronic components creates vulnerability to geopolitical tensions and supply disruptions.
- Interoperability Issues:A lack of standardization among proprietary smart lighting control systems from different manufacturers creates integration challenges, locking customers into single-vendor ecosystems.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture and vertical farming creates a specialized, high-growth application for advanced LED systems tailored to specific plant growth cycles.
- Smart Building Integration:Opportunities exist to bundle lighting solutions with other building management systems, such as HVAC and security, to offer a unified platform for facility optimization.
- Emerging Economies:Rapid urbanization and new construction in Southeast Asian nations provide significant greenfield opportunities for deploying modern, efficient lighting infrastructure from the ground up.
Industry Challenges
- Legacy System Integration:The complexity and cost of integrating modern, IP-based lighting controls with older, analog building management systems (BMS) can deter facility managers from undertaking upgrades.
- Installer Skill Gap:A shortage of electricians and technicians trained in both traditional lighting installation and the IT networking skills required for commissioning smart, connected lighting systems.
- Protocol Standardization:The slow development and adoption of universal communication standards for IoT devices, such as Matter, hinders the creation of a truly interoperable multi-vendor smart lighting market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Lighting Technology Market |
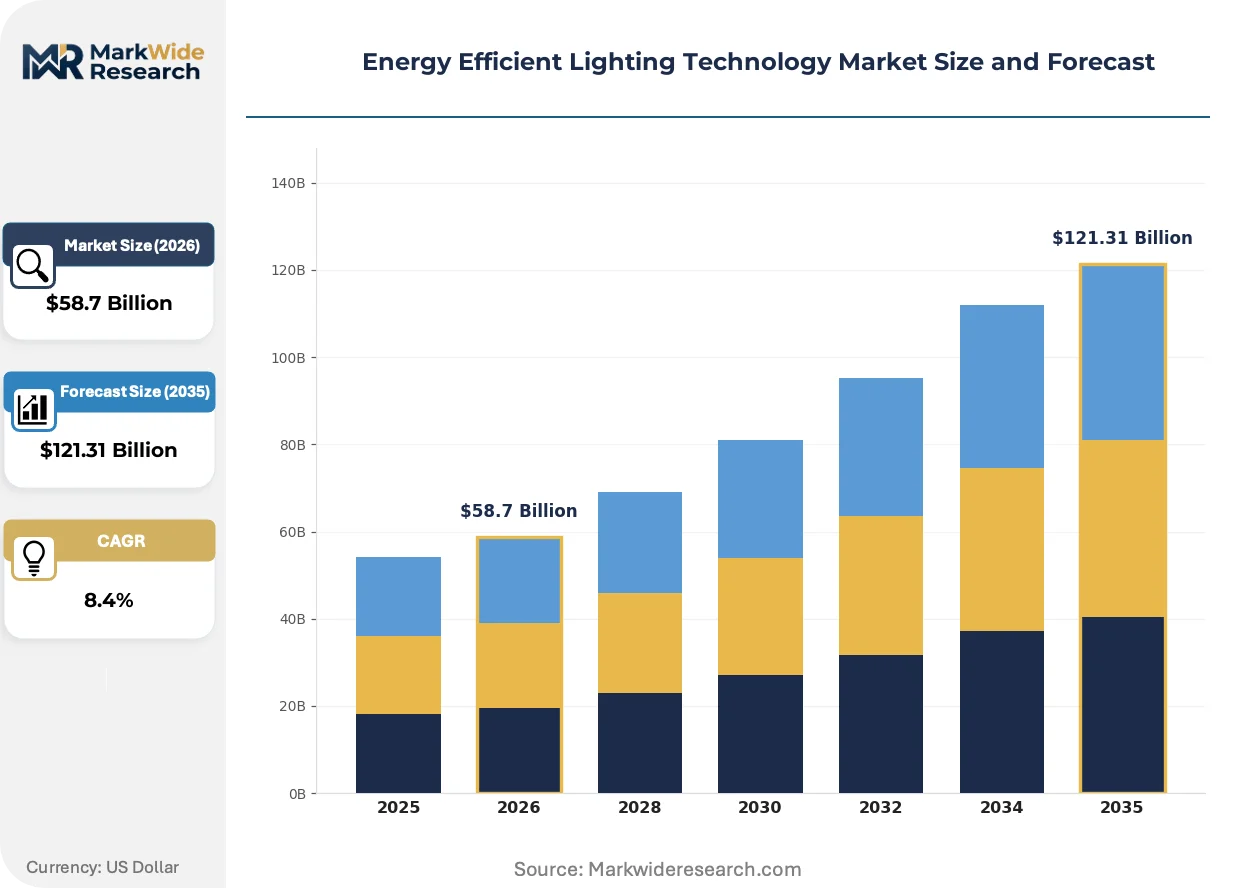
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, CFL, Halogen, Fluorescent Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Solar Lighting, Traditional Lighting, Advanced Controls End User: Homeowners, Businesses, Contractors, Government |
| Companies Covered | Signify N.V., OSRAM Licht AG, Acuity Brands, Inc., GE Current, a Daintree company, Cree Lighting, Eaton Corporation plc, Schneider Electric SE, Panasonic Holdings Corporation, Nichia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Lighting Technology Market Strategic Shifts & Innovations
The function of lighting is fundamentally changing from simple illumination to a key component of building intelligence. This evolution is defined by connectivity, data generation, and the integration of lighting into broader operational technology stacks, making it an active asset.
Digital Twin technology creates a real-time virtual replica of a physical lighting infrastructure for monitoring and simulation. Facility managers in commercial and industrial settings adopt it for predictive maintenance and energy modeling. The technology is virtualizing system diagnostics and commissioning, reducing the need for extensive on-site physical intervention after initial setup.
Regulatory frameworks like the European Union's Ecodesign Directive are progressively raising minimum energy performance standards. This directive accelerates the market exit of less efficient technologies, such as certain types of halogen lamps, by setting higher efficacy thresholds. The commercial and residential luminaire segments are most impacted, requiring redesigns to meet new performance and lifetime requirements.
End-user preference is moving towards service-based acquisition through Lighting-as-a-Service (LaaS) contracts. This subscription model shifts the financial burden from a large capital expense to a predictable operational expense, covering hardware, software, and maintenance. The model is gaining traction in large municipal infrastructure projects and multi-site retail chains seeking budget predictability.
Energy Efficient Lighting Technology Market Segmentation
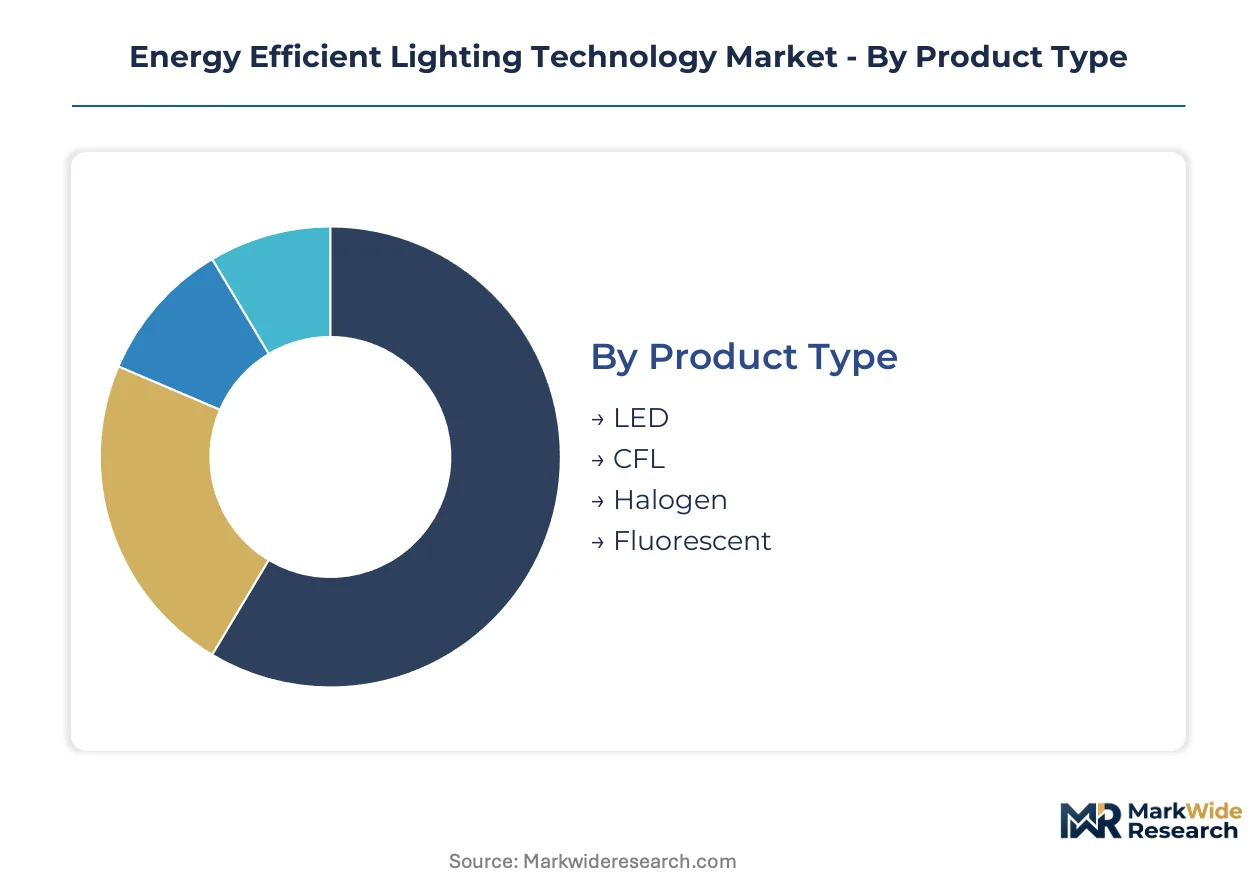
The segmentation analysis provides a granular view of the energy efficient lighting technology market, dissecting it into distinct categories that reflect product characteristics, deployment scenarios, technological sophistication, and primary consumers. Understanding these segments is crucial for identifying specific demand patterns and strategic investment opportunities across the industry.
Product Type:
The product type segmentation categorizes lighting solutions based on their primary illumination mechanism and suitability across diverse applications.
- LED:Light Emitting Diodes represent solid-state lighting technology, offering superior energy efficiency, extended lifespan, and versatile design options. Demand concentrates in commercial building retrofits and new construction projects across Europe, driven by stringent energy performance standards.
- Fluorescent:These lamps produce light by exciting mercury vapor, emitting UV radiation that then energizes a phosphor coating. While being phased out in many regions, they still hold significant installed base in industrial facilities and older commercial buildings in emerging economies like India, where replacement cycles are slower.
- CFL:Compact Fluorescent Lamps are miniaturized fluorescent lights designed to fit standard incandescent fixtures, providing moderate energy savings over traditional bulbs. Homeowners in various developing countries still utilize CFLs for cost-effective upgrades.
- Halogen:Halogen lamps are a type of incandescent lamp that uses a halogen gas to improve filament efficiency and lifespan compared to standard incandescent bulbs. These are increasingly being phased out due to lower energy efficiency compared to LEDs.
Established volume favors Fluorescent technology; emerging adoption favors LED.
Application:
The application segment delineates where energy-efficient lighting solutions are deployed, reflecting varying requirements for illumination intensity and operational hours.
- Commercial:This segment includes offices, retail spaces, hospitality venues, and educational institutions, demanding high-quality, long-lasting illumination for extensive operating hours. Commercial retrofits in the United States aim to reduce operational expenditures and improve occupant comfort.
- Industrial:Industrial applications encompass factories, warehouses, and manufacturing plants, requiring robust, high-lumen output lighting often in harsh environments. Government policies in China supporting industrial efficiency improvements drive concentrated demand for these solutions.
- Residential:Residential applications cover lighting for homes and apartments, focusing on aesthetics, dimmability, and ease of installation for individual consumers. Energy Star programs in the US encourage homeowners to upgrade to efficient lighting.
- Outdoor:This category involves streetlights, park lighting, architectural exterior lighting, and public infrastructure, emphasizing durability, weather resistance, and smart control capabilities. Rapid urbanization in Southeast Asian nations provides significant greenfield opportunities.
Volume contribution from commercial applications remains substantial, while industrial applications are experiencing rapid growth due to efficiency mandates.
Technology:
The technology segmentation distinguishes between foundational illumination methods and sophisticated control systems that enhance functionality and efficiency.
- Smart Lighting:This technology integrates lighting fixtures with sensors, communication modules, and control systems, enabling features like occupancy sensing, daylight harvesting, and remote management. Demand for connected building systems in Germany propels smart lighting adoption.
- Advanced Controls:Advanced controls encompass dimmers, timers, occupancy sensors, and centralized building management system integration, optimizing light output and energy consumption. Compatibility with existing building infrastructure is a key differentiator for solutions in the United Kingdom.
- Solar Lighting:Solar lighting systems utilize photovoltaic panels to convert sunlight into electricity, storing it in batteries for nighttime illumination, primarily for outdoor and off-grid applications. Rural electrification projects in various African countries leverage solar lighting.
- Traditional Lighting:This refers to conventional lighting sources such as incandescent and older fluorescent technologies that lack advanced controls or smart features. Regulatory frameworks like the EU Ecodesign Directive accelerate the phase-out of these less efficient technologies.
Innovation in smart lighting drives future market expansion, contrasting with the mature presence of traditional lighting.
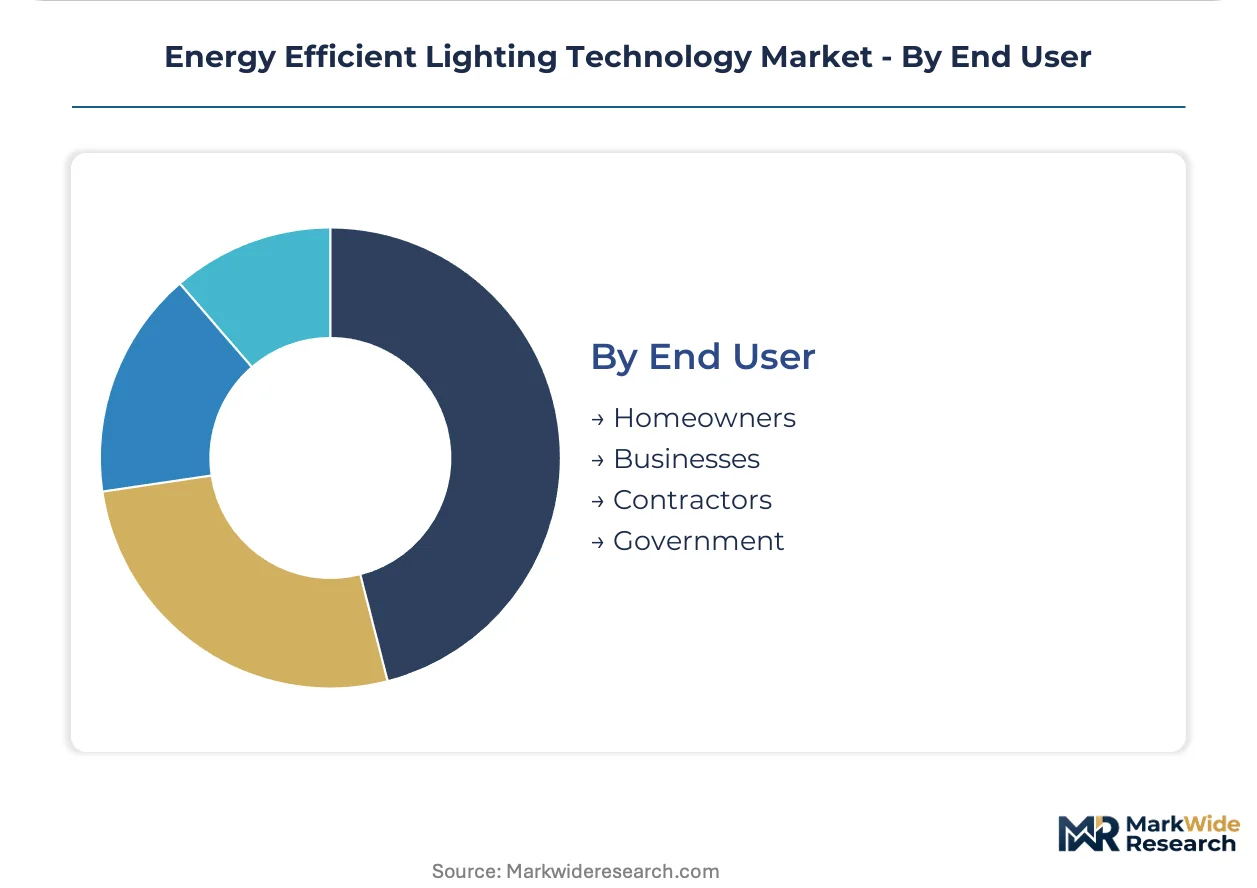
End User:
The end-user category identifies the primary purchasers and beneficiaries of energy-efficient lighting, each with distinct procurement processes and scale requirements.
- Businesses:This segment includes small, medium, and large enterprises that purchase lighting for their commercial and industrial premises, often seeking operational cost reductions. LaaS models are gaining traction among multi-site retail chains in France for budget predictability.
- Government:Government entities procure energy-efficient lighting for public infrastructure, municipal buildings, and street lighting projects, often driven by sustainability goals and long-term cost savings. Large municipal infrastructure projects in Japan increasingly adopt efficient lighting solutions.
- Homeowners:Individual consumers purchasing lighting for their residential properties, prioritizing aesthetic appeal, ease of installation, and immediate energy bill savings. The US EPA's ENERGY STAR program influences homeowner purchasing decisions.
- Contractors:Contractors are intermediaries who install and integrate lighting systems for various clients, requiring reliable products and technical support. A shortage of electricians trained in IT networking skills presents a challenge in the Canadian market.
Large-scale procurement by businesses shapes market demand, while government mandates influence long-term infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global energy efficient lighting market reflects a dynamic interplay of localized demand and concentrated manufacturing capabilities. While production of LED chips often centers in specific Asian geographies, adoption patterns vary significantly across continents. Regulatory frameworks in developed economies drive demand for advanced solutions, influencing global trade flows.
United States
Commercial retrofits in the United States drive substantial demand for energy efficient lighting, aiming to reduce operational expenditures. The US EPA's ENERGY STAR program encourages widespread adoption by homeowners. Major metropolitan areas like New York City and Los Angeles see significant activity in upgrading existing building infrastructure.
Germany
Germany exhibits strong demand for smart lighting solutions, propelled by connected building systems. The European Union's Ecodesign Directive enforces high-efficiency standards. Industrial hubs in Bavaria and North Rhine-Westphalia actively integrate smart lighting to optimize facility management.
China
China's government policies supporting large-scale infrastructure projects and industrial efficiency improvements create concentrated demand. China's GB standards dictate design specifications for market entry. Industrial zones in the Yangtze River Delta region see extensive deployment for manufacturing plants and public infrastructure.
Japan
Large municipal infrastructure projects in Japan increasingly adopt efficient lighting solutions, driven by sustainability goals and cost savings. The Ministry of Economy, Trade and Industry (METI) promotes energy conservation. Major urban centers like Tokyo and Osaka metros prioritize efficient lighting upgrades for public buildings.
Vietnam
Rapid urbanization and new construction in Vietnam provide greenfield opportunities for deploying modern, efficient lighting infrastructure. Government initiatives support sustainable building development. Cities like Ho Chi Minh City and Hanoi are actively implementing efficient lighting in new residential and commercial developments.
Energy Efficient Lighting Technology Market Key Industry Players
On the supply side, the industry is characterized by a blend of established lighting giants and specialized smart technology providers. The market structure includes vertically integrated manufacturers producing a full range of products, alongside innovators focusing on advanced control systems. Strategic archetypes include broad portfolio providers, smart lighting specialists, and regional manufacturers. Competitive moves often involve strategic partnerships with IoT platform providers and ongoing portfolio diversification into service-based models.
Established players like Signify N.V. and Acuity Brands, Inc. exemplify the broad portfolio provider archetype, leveraging extensive product lines for comprehensive client solutions. These companies often integrate their lighting offerings with broader building management systems, providing advanced control capabilities and data analytics. OSRAM Licht AG also occupies a significant position, particularly in specialized industrial and automotive lighting segments where robust performance is critical. These entities anchor the market through their global reach, deep relationships within commercial and industrial sectors, and ongoing investment in smart lighting innovation.
| Leading Market Players |
|---|
| Signify N.V. |
| OSRAM Licht AG |
| Acuity Brands, Inc. |
| GE Current, a Daintree company |
| Cree Lighting |
| Eaton Corporation plc |
| Schneider Electric SE |
| Panasonic Holdings Corporation |
| Nichia Corporation |
| Others |
Cost & Logistics Intelligence
China's concentration in LED chip manufacturing influences pricing power across the downstream luminaire assembly sector. This supply dynamic impacts the cost structures for comprehensive Lighting-as-a-Service packages.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for large-scale installations. Price differentiation stems from integration with building management systems and comprehensive service level agreements offered through LaaS models. Pricing softness runs through the standard LED product segment due to intense competition and commoditization. Small and medium-sized enterprises exhibit higher price sensitivity compared to large municipal entities or multi-site retail chains.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive nature of component procurement. Supply concentrates heavily in China for LED chips and electronic components, with secondary sourcing from South Korea and Japan. Key dependencies include rare earth elements for phosphor coatings and specialized semiconductor materials for diodes. Geopolitical tensions represent a structural risk for component availability. Distribution runs through a mix of direct commercial sales and specialized electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy efficient lighting technology market represents an early-cycle expansion story, driven by the accelerating penetration of smart lighting solutions into connected building systems. Regulatory mandates from the European Union's Ecodesign Directive further catalyze this transition.
For Market Incumbents: Entrench existing market share by expanding comprehensive LaaS portfolios that bundle hardware, software, and maintenance. Deepen integration with broader smart building ecosystems to counter commoditization pressure from standard LED products. Invest strategically in R&D for advanced control algorithms and data analytics to maintain differentiation. Leverage established distribution channels and contractor networks to reinforce market presence against emerging software-centric competitors.
For New Entrants and Emerging Players: Pursue specialized high-growth applications such as horticultural lighting for controlled environment agriculture. Target greenfield opportunities in rapidly urbanizing Southeast Asian nations, focusing on modern, efficient infrastructure. Differentiate through vertical-specific software solutions and integrated control systems, rather than competing on hardware price. Forge strategic partnerships with broader IoT platform providers to offer unified smart building solutions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed smart lighting control specialists and niche application innovators. The long-term viability remains strong over the next decade, driven by ongoing energy efficiency mandates and smart building integration. Target acquisition profiles include firms with proprietary control software or significant intellectual property in connected lighting. Watch the adoption rate of universal communication standards like Matter as an inflection indicator for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Lighting-as-a-Service (LaaS) Portfolios | Shifts customer capital expenditure to operational expenditure, enhancing budget predictability for businesses. |
| Integrate with Broader Smart Building Platforms | Bundles lighting with HVAC and security, offering unified facility optimization for commercial clients. |
| Develop Advanced Horticultural Lighting Solutions | Captures high-growth demand from controlled environment agriculture and vertical farming applications. |
| Acquire Specialized Smart Control Software Firms | Strengthens proprietary control systems and accelerates integration with connected building technologies. |
| Invest in Universal Protocol Standardization | Addresses interoperability issues, enabling seamless multi-vendor smart lighting ecosystems for end-users. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights came from lighting manufacturers, facility managers, smart building integrators, and government energy regulators. Secondary sources included EU Ecodesign Directive documents, US EPA ENERGY STAR program data, national infrastructure project reports, and corporate annual filings. This data underwent bottom-up and top-down triangulation to ensure accuracy.
Forecast inputs considered historical market performance, regulatory shifts, and technological adoption rates across the analysis window. The analytical framework modeled product type, application, technology, end user, and regional regulatory compliance dimensions. Compound Annual Growth Rates derived from historical data regression and projected adoption curves. Energy efficiency mandates and smart building investment trends served as key industry inputs.
Sensitivities concentrate around geopolitical disruptions in key manufacturing regions and the pace of smart building adoption. Forecasts reflect underlying assumptions regarding technological advancements and market dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market