
 Energy-Saving Constant Humidity Storage Cabinet Market | 2026-2036
Energy-Saving Constant Humidity Storage Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Energy-Saving Constant Humidity Storage Cabinet Market Insights
Equipment leasing and performance-based service contracts is rewriting competitive entry barriers for humidity-controlled storage, allowing smaller facilities to access enterprise-grade climate management without capital expenditure. Thermo Fisher Scientific leverages its global service infrastructure to sustain long-term instrument protection contracts with pharmaceutical clients. Hoshizaki Corporation anchors its position through captive refrigeration component production, while Eureka Dry Tech specializes in compact desiccant systems for electronics preservation niches.
Energy-saving constant humidity storage cabinets are enclosed environmental control systems that maintain relative humidity within specified tolerances, typically employing thermoelectric modules or desiccant media with regenerative cycles to achieve setpoints without continuous compressor operation. These units serve primarily to prevent moisture-induced degradation of moisture-sensitive materials, instruments, and documents across industrial and cultural applications. Modular cabinets are capturing disproportionate interest from quality control labs seeking scalable capacity expansion, while desiccant dehumidification technology leads in archival and museum settings where ultra-low humidity setpoints and silent operation prove essential. Portable cabinets represent the fastest-growing configuration as field calibration teams and mobile research units demand transportable environmental protection.
The EPA and DOE appliance efficiency frameworks in the United States, alongside the EU Ecodesign Directive and F-Gas Regulation in Europe, are tightening energy consumption and refrigerant specifications for climate-controlled equipment, directly shaping R&D priorities and product certification requirements. China's SAMR enforces GB standards for energy labeling that disadvantage conventional vapor compression designs in public procurement. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional product variants offer superior path economics.
Market Dynamics
Phase-out mandates for fluorinated refrigerants under the EU F-Gas Regulation and China's dual carbon goals are structurally compressing vapor compression supply chains while elevating thermoelectric and desiccant platform economics.
Growth Catalysts
- EU F-Gas Regulation:Accelerated refrigerant phase-down timelines force industrial buyers toward desiccant regeneration cycles and solid-state cooling architectures.
- Calibration laboratories:Expanding metrology infrastructure in Germany and Japan drives demand for ultra-stable humidity setpoints below ±2% RH tolerance.
- Thermoelectric modules:Advancing semiconductor materials improve coefficient of performance ratios, enabling compressor-free operation in mid-capacity cabinets.
Market Restraints
- Copper and rare-earth price volatility:Thermoelectric module substrates and heat exchanger materials face input cost swings that compress OEM margins.
- Desiccant media supply concentration:Synthetic zeolite production clusters in East Asian chemical processing hubs create single-source vulnerability.
- Technical limitation in ultra-low setpoints:Below 10% RH, desiccant regeneration frequency escalates energy consumption toward vapor compression parity.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Domestic electronics assembly incentives create first-mover advantage for localized cabinet production.
- Biologics cold chain convergence:Integration of humidity control with validated pharmaceutical storage opens clinical trial material preservation.
- Performance-based leasing:Smithsonian and Max Planck Institute procurement templates normalize service-contract models that bypass capital budget constraints.
Industry Challenges
- Multiphysics simulation expertise:Coupled heat-mass transfer modeling for desiccant wheel optimization requires scarce computational fluid dynamics specialists.
- Cross-jurisdiction certification timelines:Parallel UL, CE, and GB standard testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy-Saving Constant Humidity Storage Cabinet Market |
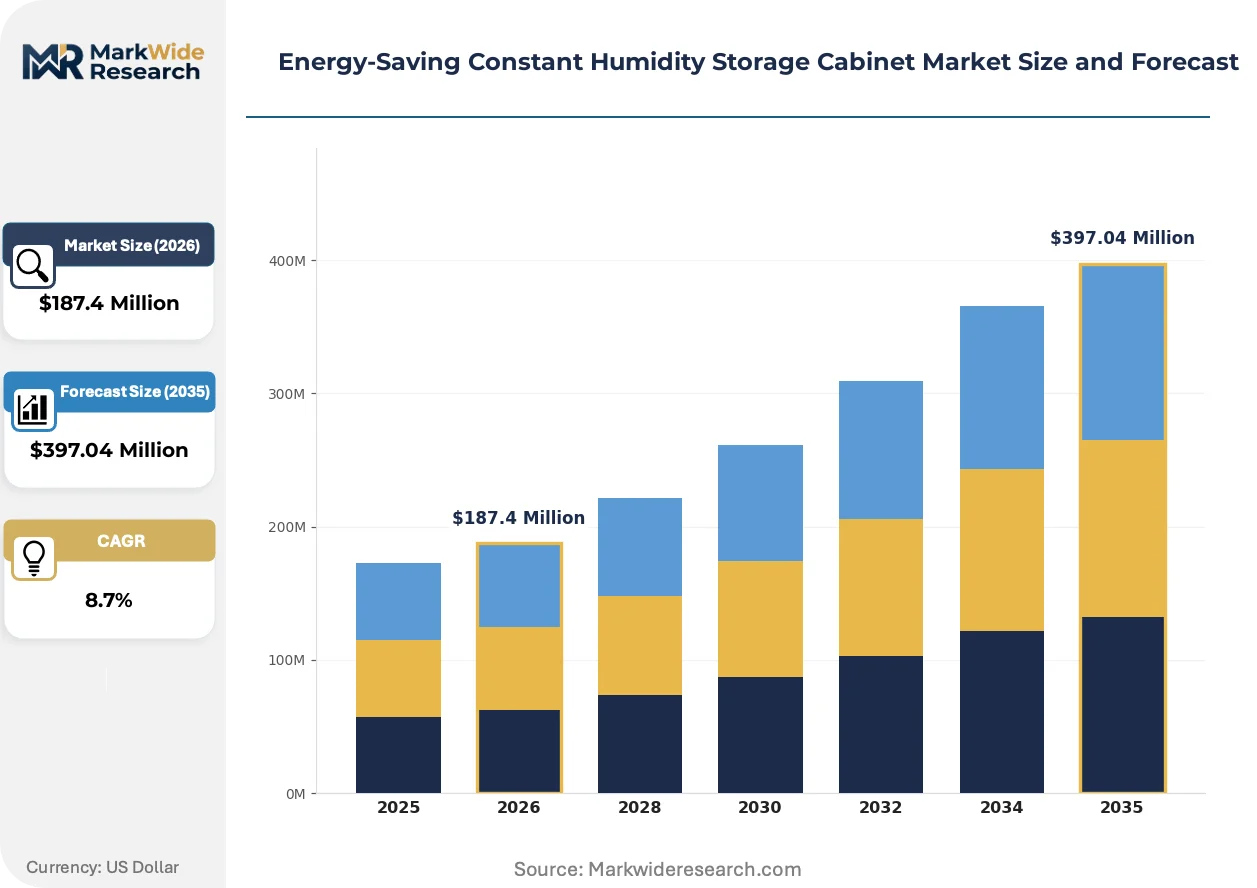
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Cabinets, Modular Cabinets, Upright Cabinets, Wall-Mounted Cabinets, Portable Cabinets Technology: Peltier Cooling, Thermoelectric, Vapor Compression, Desiccant Dehumidification, Absorption Cooling Application: Pharmaceutical Storage, Laboratory Equipment Storage, Electronics Preservation, Archival Document Storage, Artistic Material Storage End User: Research Institutes, Quality Control Labs, Manufacturing Facilities, Museums, Calibration Centers |
| Companies Covered | Thermo Fisher Scientific, Sartorius, Totech, Hoshizaki Corporation, Dr. Storage, Eureka Dry Tech, Guangdong SIRUI Optical, Terra Universal, Desiccant Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy-Saving Constant Humidity Storage Cabinet Market Trends and Innovations
Active materials science breakthroughs and procurement model reinvention are compressing technology refresh cycles while fragmenting vendor concentration across humidity control architectures.
Solid-state thermoelectric cooling is migrating from niche electronics preservation toward mainstream pharmaceutical stability storage. Merck and Roche manufacturing quality units in Switzerland and Germany now specify Peltier-based cabinets for intermediate bulk container staging. This platform shift enables modular capacity scaling without centralized chiller infrastructure, compressing facility retrofit costs.
China's SAMR enforcement of GB 12021 energy labeling standards disadvantages imported vapor compression equipment in public hospital and museum tenders. Domestic OEMs accelerate thermoelectric platform development to capture procurement preference points. European manufacturers respond with dual-certification strategies targeting both CE and GB mark compliance.
Leasing structures with guaranteed uptime clauses displace outright purchase in North American university research infrastructure. Harvard and MIT facilities management now contract for humidity performance rather than equipment ownership, transferring regeneration media replacement and calibration burden to service providers. This model concentrates in high-cost labor markets where technical staffing constraints favor outsourced environmental management.
Energy-Saving Constant Humidity Storage Cabinet Market Segmentation
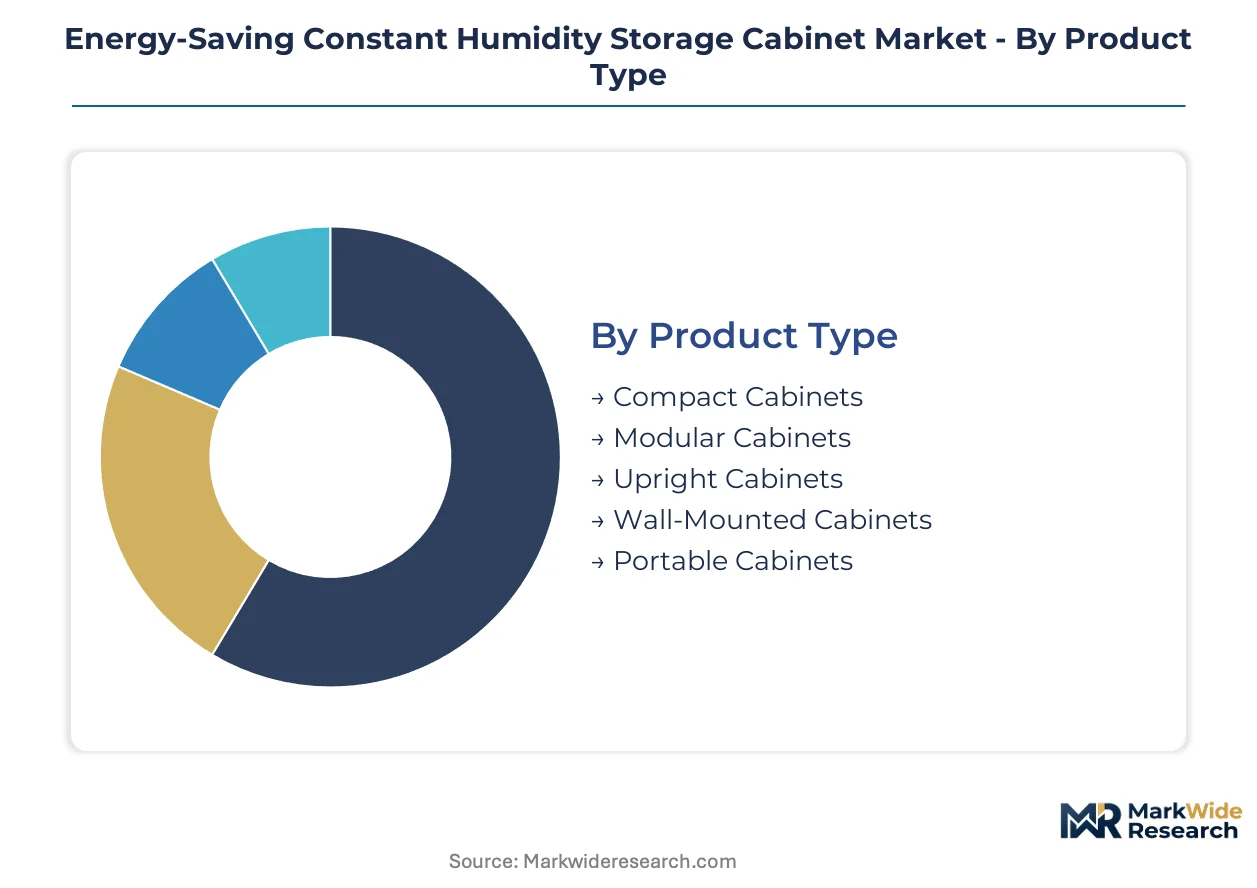
Segmentation in the energy-saving constant humidity storage cabinet market reflects divergent technical requirements across precision manufacturing, cultural heritage preservation, and pharmaceutical stability applications. Buyers prioritize different performance attributes—setpoint accuracy, energy consumption profiles, or physical footprint—depending on end-use constraints and facility infrastructure.
Product Type:
Use-case spectrum spans fixed installation for permanent collections to mobile units for field calibration teams and distributed quality control networks.
- Compact Cabinets:Enclosed systems under 100 liters designed for benchtop placement in crowded laboratory environments. Demand concentrates in Japanese electronics manufacturers and German automotive quality labs where floor space commands premium pricing and multiple discrete humidity zones prove necessary.
- Modular Cabinets:Scalable units with standardized connection interfaces permitting capacity expansion without full system replacement. Quality control labs in Switzerland and the United States favor this architecture for staged investment aligned with production ramp schedules.
- Upright Cabinets:Vertical floor-standing configurations maximizing storage density per square meter.
- Wall-Mounted Cabinets:Space-efficient installations preserving floor access in congested facilities.
- Portable Cabinets:Transportable units with battery or vehicle-power compatibility for mobile deployment.
Established volume favors upright configurations; emerging adoption favors portable units.
Technology:
Cost tier differentiation separates premium solid-state platforms from conventional compressor-based systems facing regulatory phase-out pressures.
- Thermoelectric:Solid-state heat pumping through semiconductor junctions eliminates refrigerant circulation entirely. Swiss pharmaceutical manufacturers and Japanese precision instrument makers specify these systems for intermediate staging areas where vibration and noise constraints exclude compressor operation.
- Desiccant Dehumidification:Regenerative media systems using synthetic zeolite or silica gel rotating through process and regeneration zones. Museums in Germany and archival facilities in France deploy this technology for ultra-low humidity setpoints below 15% RH where vapor compression efficiency collapses.
- Peltier Cooling:Thermoelectric variant optimized for cooling-dominated applications with modest dehumidification requirements.
- Vapor Compression:Conventional refrigerant-cycle systems facing accelerated obsolescence under EU F-Gas Regulation phase-down schedules.
- Absorption Cooling:Heat-activated systems using lithium bromide or ammonia-water working pairs for waste-heat recovery applications.
Desiccant platforms gain share fastest in cultural heritage applications; thermoelectric architectures expand most quickly in pharmaceutical manufacturing.
Application:
Customer type determines specification stringency, with validated pharmaceutical storage demanding continuous monitoring and documentation absent from general industrial uses.
- Pharmaceutical Storage:ICH Q1A-compliant stability chambers and clinical trial material vaults requiring continuous temperature and humidity mapping with alarm redundancy. Roche and Merck manufacturing sites in Switzerland and Germany drive specification intensity for intermediate bulk container staging prior to final packaging.
- Electronics Preservation:Moisture-sensitive device storage for semiconductor components, printed circuit boards, and precision sensors. Taiwan and South Korea fabrication facilities maintain extensive cabinet fleets for work-in-process inventory protection against oxidation and solderability degradation.
- Laboratory Equipment Storage:Analytical instrument protection in research and quality environments.
- Archival Document Storage:Paper-based record preservation with emphasis on gradual humidity transitions preventing dimensional stress.
- Artistic Material Storage:Conservation-grade environments for paintings, textiles, and organic artifacts.
Pharmaceutical applications command premium pricing; electronics preservation offers highest volume potential.
End User:
Volume concentration aligns with capital expenditure cycles in precision manufacturing and public funding availability for cultural infrastructure.
- Calibration Centers:Metrology laboratories maintaining national and reference standards requiring humidity stability within ±2% RH tolerance. Germany's Physikalisch-Technische Bundesanstalt and Japan's National Metrology Institute anchor procurement volume for highest-specification cabinets.
- Museums:Conservation departments managing mixed-media collections with incompatible optimal humidity ranges. Smithsonian Institution and Max Planck Institute collections management normalize performance-based service contracts transferring operational risk to vendors.
- Research Institutes:University and government laboratories with episodic capital renewal cycles.
- Quality Control Labs:Industrial testing facilities integrated with production lines.
- Manufacturing Facilities:In-process storage and staging areas within electronics and pharmaceutical plants.
Calibration centers sustain replacement demand; museums represent the steepest expansion trajectory through leasing model normalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of energy-saving constant humidity storage cabinets concentrate from German precision engineering clusters and Japanese component manufacturing hubs toward calibration centers and museums in import-dependent markets. The United States runs a structural trade deficit in specialized climate control equipment, sourcing premium desiccant and thermoelectric platforms from European and Asian suppliers. China's domestic production capacity now satisfies most local museum and electronics manufacturing demand while emerging as a net exporter to Southeast Asian calibration infrastructure projects.
United States
Smithsonian Institution conservation departments and MIT research facilities normalize performance-based service contracts that transfer operational risk to vendors. EPA appliance efficiency frameworks tighten energy consumption specifications for climate-controlled equipment in federal procurement. Boston and Washington DC metropolitan areas concentrate demand from university laboratories and cultural heritage institutions seeking modular capacity expansion.
Germany
Physikalisch-Technische Bundesanstalt and Max Planck Institute collections management drive specification intensity for ultra-stable humidity setpoints below ±2% RH tolerance. EU F-Gas Regulation phase-down timelines force industrial buyers toward desiccant regeneration cycles and solid-state cooling architectures. Stuttgart and Munich industrial corridors anchor production of precision thermoelectric modules serving pharmaceutical stability storage applications.
China
SAMR enforcement of GB 12021 energy labeling standards disadvantages imported vapor compression equipment in public hospital and museum tenders. Dual carbon goals accelerate phase-out of conventional refrigerant-cycle systems in favor of domestic thermoelectric platform development. Yangtze River Delta electronics manufacturing clusters expand procurement of compact desiccant cabinets for semiconductor component preservation.
Japan
National Metrology Institute maintains reference standards requiring humidity stability within ±2% RH tolerance, sustaining replacement demand for highest-specification cabinets. METI industrial policy supports domestic production of precision instrument protection equipment. Osaka and Nagoya precision manufacturing corridors integrate humidity-controlled staging areas within electronics and automotive quality control networks.
Switzerland
Roche and Merck manufacturing sites in Basel and Geneva specify Peltier-based cabinets for intermediate bulk container staging prior to final packaging. Swissmedic pharmaceutical storage regulations mandate continuous temperature and humidity mapping with alarm redundancy. Zurich and Lausanne research clusters contract for modular environmental protection systems enabling staged investment aligned with production ramp schedules.
Energy-Saving Constant Humidity Storage Cabinet Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying thermoelectric modules, desiccant media, and regenerative cycle controllers. The vendor base organizes into three functional layers: diversified laboratory equipment conglomerates with global service infrastructure, captive refrigeration manufacturers leveraging backward integration into compressor and heat exchanger production, and niche desiccant specialists focused on ultra-low humidity archival applications. Consolidation pressure operates through technology licensing agreements that transfer desiccant wheel designs between regional fabricators, while capacity expansion concentrates in East Asian chemical processing hubs for synthetic zeolite production.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Hoshizaki Corporation exemplify contrasting strategic positions. Thermo Fisher leverages its global service infrastructure to sustain long-term instrument protection contracts. Hoshizaki anchors its position through captive refrigeration component production. Eureka Dry Tech occupies a specialist niche serving compact desiccant requirements for electronics preservation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius |
| Totech |
| Hoshizaki Corporation |
| Dr. Storage |
| Eureka Dry Tech |
| Guangdong SIRUI Optical |
| Terra Universal |
| Desiccant Technologies |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across this market, with container rate volatility feeding into both East Asian supply concentration and tiered price differentiation between premium thermoelectric systems and economy-grade desiccant units. Procurement officers at German calibration centers and Japanese electronics manufacturers absorb freight passthrough differently, fragmenting effective price bands despite nominal list convergence.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as primary differentiation drivers. Premium tiers command substantial markups for SAMR GB compliance and dual UL-CE marking, while price erosion runs through economy segments as Chinese domestic OEMs expand thermoelectric capacity. Museum conservation departments exhibit lowest price sensitivity, prioritizing guaranteed uptime clauses over capital expenditure minimization.
Supply Chain Analysis
Export-control restrictions on semiconductor-grade thermoelectric substrates limit flows from United States and Japanese suppliers to Chinese cabinet assemblers, compressing available module supply for mid-capacity pharmaceutical applications. Synthetic zeolite desiccant media draws from concentrated East Asian chemical processing hubs, creating single-source vulnerability for European archival equipment manufacturers. Distribution runs through authorized service networks rather than direct OEM sales, with spare parts and regeneration media replacement sustaining recurring revenue attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as performance-based leasing normalizes across museum and research institute procurement, creating niche entry points for specialized service providers outside traditional equipment manufacturing.
For Market Incumbents: Insulate core pharmaceutical accounts through captive supply of thermoelectric modules and backward integration into heat exchanger fabrication, countering margin compression from rare-earth price volatility. Expand GB certification capacity ahead of SAMR enforcement tightening in Yangtze River Delta public tenders. For New Entrants and Emerging Players: Establish a beachhead in India's precision manufacturing corridor ahead of PLI scheme maturation, targeting domestic electronics assembly facilities with localized desiccant cabinet production. Lead with rapid-deployment modular architectures that bypass incumbent service infrastructure advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified laboratory conglomerates seeking to divest non-core climate control divisions, particularly those with stranded vapor compression product lines facing EU F-Gas obsolescence. Monitor India's electronics manufacturing cluster formation as inflection indicator for regional demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Leasing Model | Smithsonian and Max Planck Institute procurement templates now normalize service-contract structures bypassing capital constraints. |
| Dual-Certification Pathway | European manufacturers pursuing simultaneous CE and GB mark compliance capture preference points in Chinese public tenders. |
| Backward Integration into Thermoelectric Modules | Hoshizaki's captive semiconductor substrate production insulates margin position against rare-earth input volatility. |
| Localized Production in India | Domestic assembly capacity leverages PLI scheme incentives while reducing freight exposure for Southeast Asian calibration projects. |
| Desiccant Media Supply Agreement | Long-term synthetic zeolite contracts with East Asian chemical processors mitigate single-source concentration risk for archival equipment OEMs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study, combining structured interviews with museum conservation officers, pharmaceutical quality directors, calibration laboratory managers, and thermoelectric module procurement leads with secondary validation against SAMR GB filings, EU F-Gas Regulation implementation reports, and customs trade data for climate-controlled equipment. Bottom-up segment sizing triangulated against top-down industry association estimates.
Calibration against historical shipment data and disclosed OEM capacity announcements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology platform, cabinet configuration, application vertical, and end-user institutional type. CAGRs derived from fitted growth curves incorporating regulatory phase-out timelines and public procurement budget cycles specific to cultural heritage preservation and pharmaceutical manufacturing.
Stress conditions across copper and rare-earth price bands, freight rate volatility, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in EU F-Gas refrigerant phase-down schedules or China's dual carbon policy implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Retrofit Systems Market