
 Energy Efficiency Gamification Market | 2026-2036
Energy Efficiency Gamification Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficiency Gamification Market Foresight
The split between premium analytics-intensive platforms and commodity notification tools is hardening in the energy efficiency gamification space. OPower anchors enterprise utility deployments with deep backward integration into meter data management. EcoTrack competes through specialized mobile-first architectures for residential behavioral programs. Sense differentiates by controlling hardware-software integration across smart home device ecosystems.
Energy efficiency gamification denotes the application of game mechanics—point systems, leaderboards, and real-time feedback loops—to reduce electricity and thermal consumption in buildings and grids. Platforms typically integrate with AMI smart meters, building management systems, and IoT sensors to deliver sub-15-minute interval feedback that triggers measurable demand reduction. Mobile Applications and Smart Devices dominate current deployment volumes, while Game-based Learning represents the fastest-expanding technology segment as educational institutions embed sustainability curricula. Utility Companies command the largest end-user spend pool, though Commercial Buildings show the steepest adoption curve as ESG reporting requirements intensify.
The EPA's ENERGY STAR program, the EU Energy Efficiency Directive, and California's Title 24 Building Energy Efficiency Standards collectively shape product specifications and procurement pathways for platform vendors. These frameworks mandate benchmarking, disclosure, and continuous improvement protocols that gamification tools directly address. Stakeholders must monitor evolving interoperability standards between utility data platforms and third-party engagement software to preserve deployment scalability.
Market Dynamics
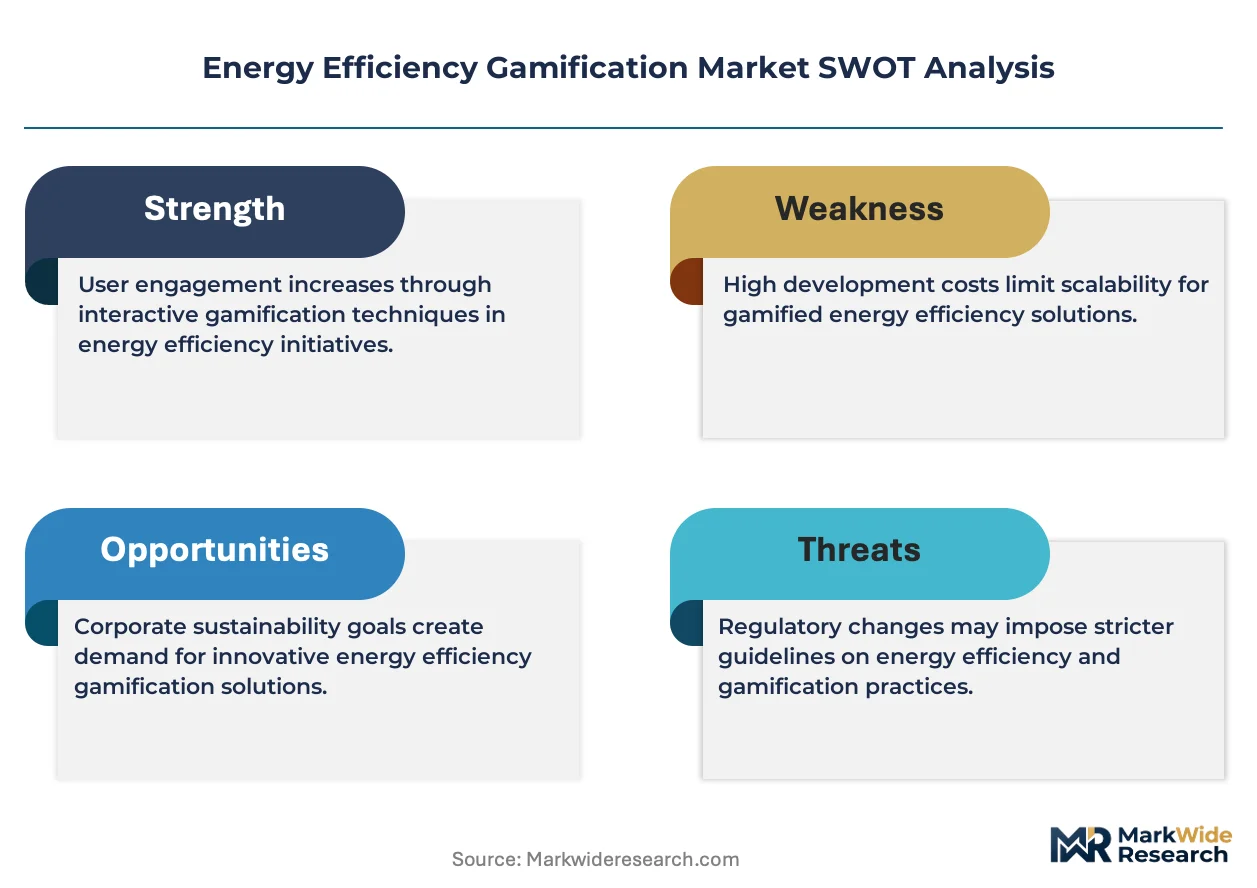
Utility procurement of behavioral engagement platforms is concentrating around vendors capable of sub-15-minute interval data integration with AMI smart meter infrastructure, creating a capability gap between analytics-intensive suites and notification-only tools.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for building performance benchmarking and continuous improvement protocols are accelerating utility procurement of gamification platforms across Germany, France, and the Netherlands.
- Smart meter penetration thresholds:Deployment environments in California, the United Kingdom, and Germany now support real-time feedback loops that enable measurable demand reduction programs.
- ESG reporting intensification:Commercial building operators are adopting consumption-tracking gamification to satisfy investor disclosure requirements and secure green financing.
Market Restraints
- AMI integration costs:Backward compatibility with legacy meter data management systems requires substantial capital expenditure from smaller municipal utilities.
- Data interoperability fragmentation:Absence of unified standards between utility data platforms and third-party engagement software limits deployment scalability across multi-utility regions.
- Behavioral fatigue risk:Sustained engagement rates decline after initial enrollment periods, compressing the effective measurement and verification window for demand response programs.
Strategic Opportunities
- Educational institution curricula:Game-based Learning represents the fastest-expanding technology segment as universities embed sustainability modules with campus building energy challenges.
- Smart home ecosystem convergence:Integration with IoT sensor networks and building management systems enables hardware-software bundles that lock in residential subscribers.
- California Title 24 standards:Continuous commissioning mandates for commercial buildings create recurring revenue potential for analytics-intensive platform vendors.
Industry Challenges
- Data science talent scarcity:Behavioral analytics and machine learning engineering functions face acute hiring competition from fintech and ad-tech sectors.
- Legacy BMS integration complexity:Proprietary protocols in existing building automation systems extend deployment timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficiency Gamification Market |
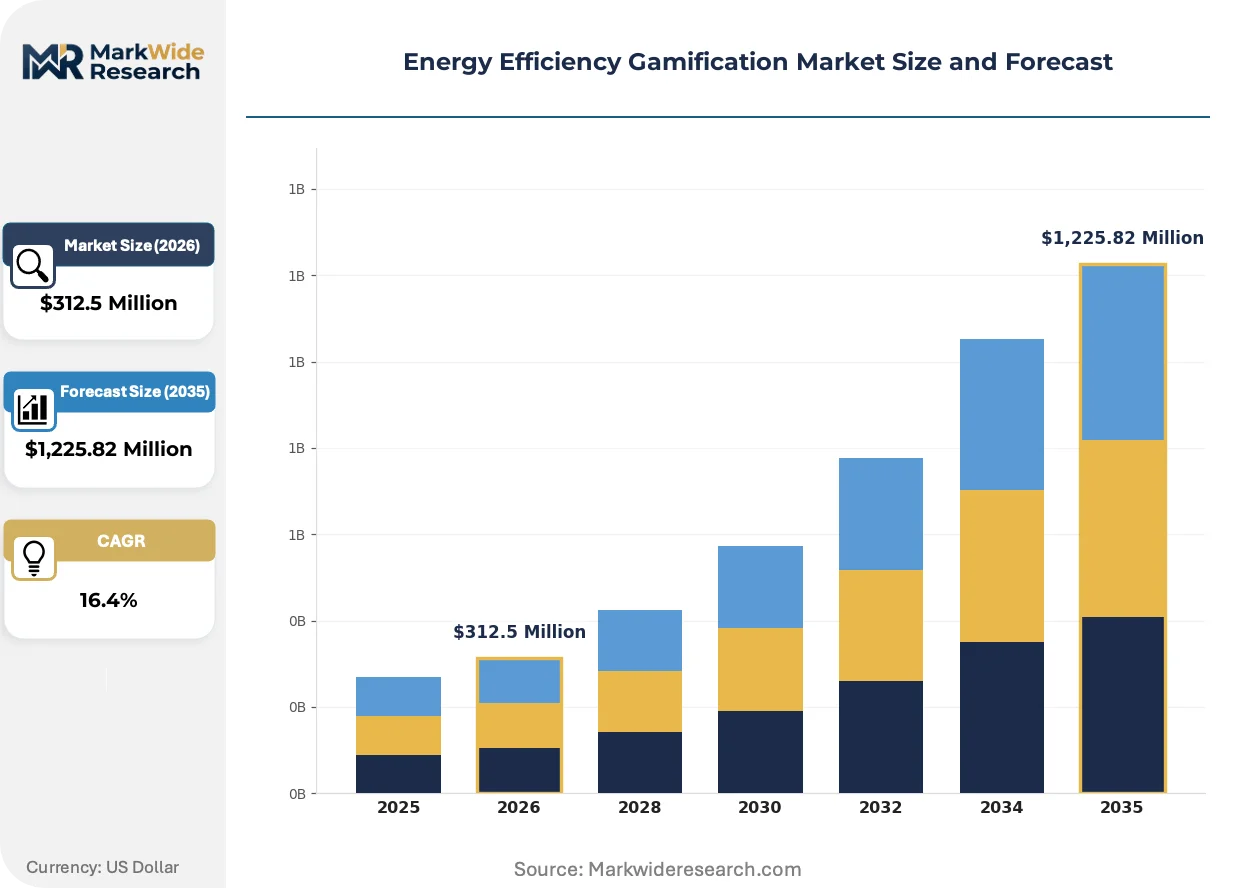
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,225.82 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile Applications, Web Platforms, Smart Devices, Game-based Learning End User: Residential Users, Commercial Buildings, Educational Institutions, Utility Companies Application: Energy Monitoring, Behavioral Change, Incentivized Challenges, Community Engagement Solution: Feedback Mechanisms, Reward Systems, Leaderboards, Energy Reports |
| Companies Covered | PowerPlay, EcoTrack, EngageEnergy, OPower, EnergyBoost, EnergyQuest, GreenGamify, Sense, EcoChallenge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficiency Gamification Market Shifts & Advancements
Platform architectures are pivoting from standalone engagement tools toward embedded components within broader utility customer information systems and smart home operating environments.
Machine learning-driven personalization engines are converging with interval meter data streams to generate individualized consumption insights. Large investor-owned utilities in California and Texas are deploying these engines at scale. This convergence is compressing the gap between aggregate portfolio analytics and household-level behavioral intervention.
EPA ENERGY STAR certification requirements are expanding to cover multifamily residential buildings, mandating documented energy performance tracking. Platform vendors are adapting reporting modules to auto-populate ENERGY STAR Portfolio Manager submissions. Commercial real estate investment trusts with national footprints are prioritizing procurement of compliant tools.
Tenant engagement models are displacing landlord-only procurement in commercial building segments. Property technology managers are subscribing to white-label gamification layers that embed in tenant experience applications. This shift is most visible in Class A office markets in New York, London, and Singapore where lease structures pass through utility costs.
Energy Efficiency Gamification Market Segmentation
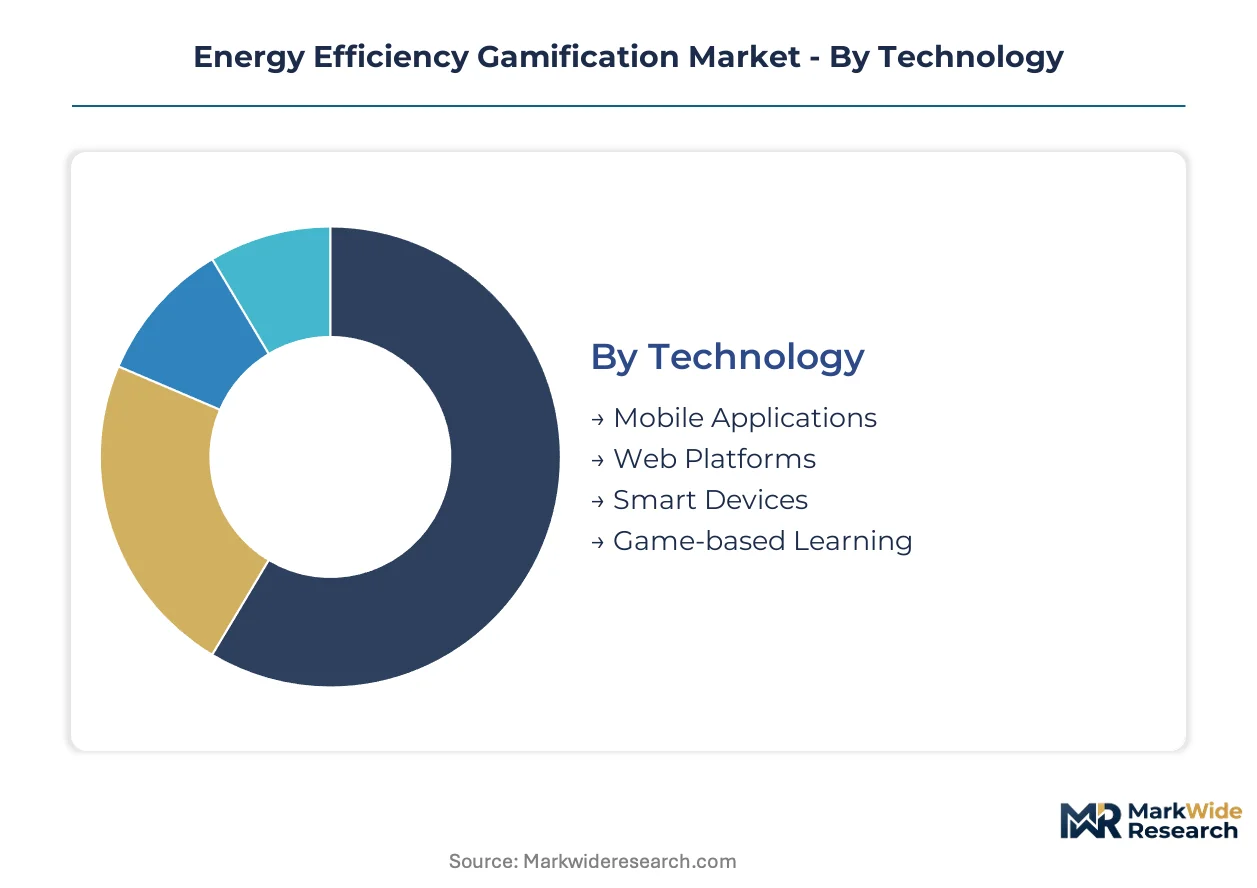
Segmentation in energy efficiency gamification reveals how platform architectures align with distinct operational requirements across deployment environments. Technology choices determine integration complexity with AMI infrastructure, while end-user categories dictate engagement mechanics and revenue model viability.
Technology:
Standardization dominates mobile and web delivery, while smart devices and immersive learning modules demand deeper customization for hardware integration and curriculum alignment.
- Mobile Applications:Native iOS and Android architectures deliver sub-15-minute interval feedback through push notifications and dashboard interfaces. Utility procurement concentrates in California, Germany, and the United Kingdom where smart meter penetration exceeds deployment thresholds for real-time behavioral loops.
- Smart Devices:Hardware-software bundles integrate IoT sensors, smart thermostats, and in-home displays with proprietary gamification layers. Demand clusters around residential retrofit programs in deregulated utility markets seeking subscriber lock-in through ecosystem control.
- Web Platforms:Browser-based engagement tools target commercial building operators requiring portfolio-level analytics without mobile dependency.
- Game-based Learning:Educational institutions embed campus building energy challenges into sustainability curricula, with fastest expansion in university systems facing carbon neutrality commitments.
Leading the category by volume: Mobile Applications. Growing fastest: Game-based Learning.
End User:
Procurement scale varies dramatically—utility enterprise contracts anchor revenue stability while commercial buildings exhibit steepest adoption curves under ESG disclosure pressure.
- Utility Companies:Investor-owned and municipal utilities deploy behavioral engagement platforms to satisfy decarbonization mandates and demand response program targets. Procurement concentrates around vendors capable of AMI smart meter backward integration.
- Commercial Buildings:Property technology managers subscribe to white-label gamification layers embedded in tenant experience applications. Class A office markets in New York and London drive demand as lease structures pass through utility costs.
- Residential Users:Individual households participate through utility-sponsored programs or direct-to-consumer smart home bundles.
- Educational Institutions:Universities and K-12 districts adopt campus-wide energy challenges to meet institutional sustainability goals and student engagement objectives.
Highest contract values: Utility Companies. Steepest expansion trajectory: Commercial Buildings.
Application:
Functional depth separates monitoring-only deployments from intervention platforms—behavioral change and incentivized challenges require more sophisticated data science infrastructure.
- Behavioral Change:Machine learning-driven personalization engines generate individualized consumption insights by converging interval meter data with household demographic proxies. Large investor-owned utilities in California and Texas deploy these engines at scale.
- Energy Monitoring:Real-time consumption visualization provides baseline engagement without gamified intervention mechanics.
- Incentivized Challenges:Time-bound competitions with monetary or status rewards drive concentrated demand reduction events. Peak load reduction programs in Texas and Australia leverage this application for grid stability.
- Community Engagement:Social comparison features and neighborhood leaderboards activate peer effects for sustained participation.
Widest deployment base: Energy Monitoring. Gaining share fastest: Behavioral Change.
Solution:
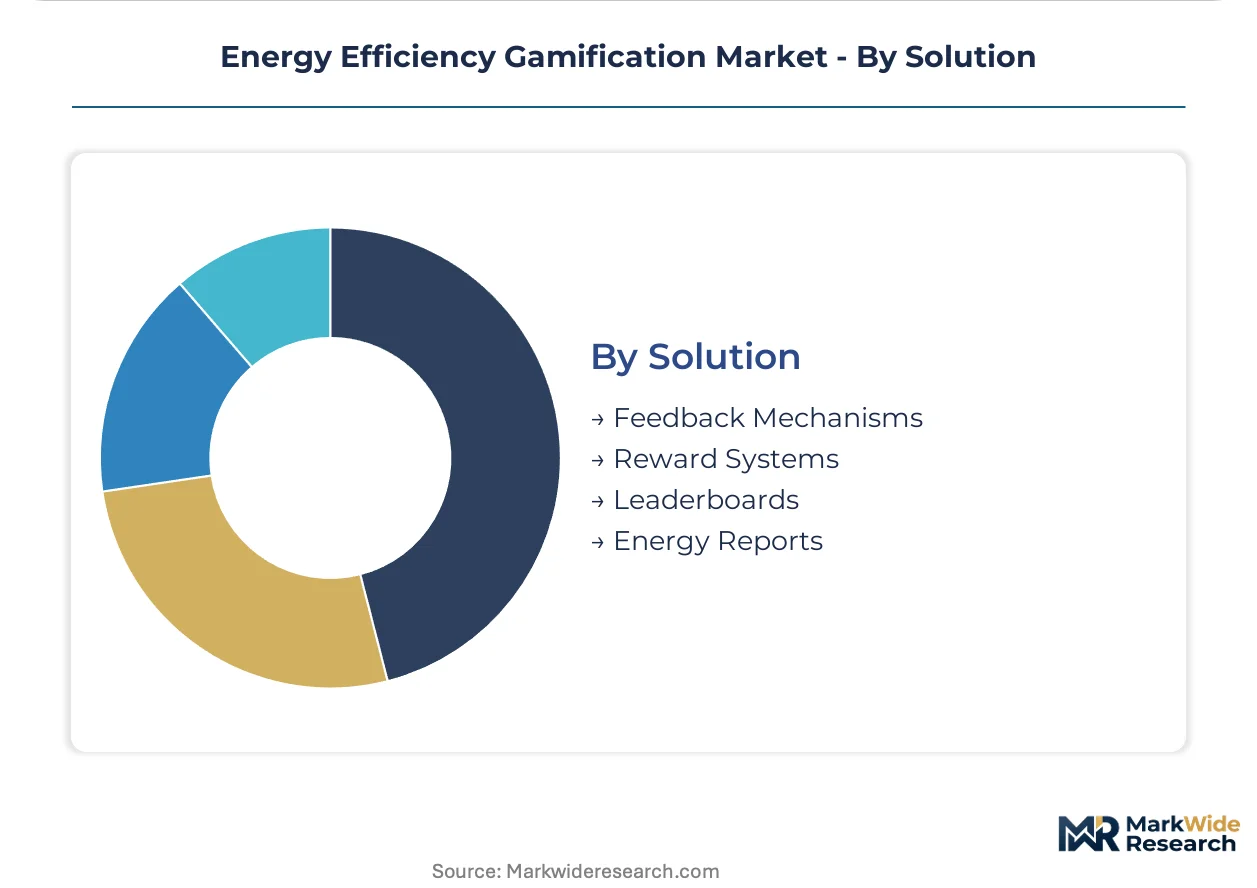
Modular architectures allow utilities to assemble engagement stacks—feedback and reward mechanisms represent commoditized layers while advanced reporting commands premium pricing.
- Reward Systems:Points, badges, and redeemable incentives sustain enrollment through variable reinforcement schedules. Integration with utility billing systems or third-party retail partners determines operational complexity.
- Energy Reports:Personalized consumption summaries with peer benchmarking and efficiency recommendations. EPA ENERGY STAR certification expansion to multifamily residential buildings mandates auto-populated Portfolio Manager submissions.
- Feedback Mechanisms:Real-time alerts and usage notifications provide immediate behavioral cues without accumulated incentive structures.
- Leaderboards:Ranked performance displays activate competitive dynamics across households, buildings, or organizational departments.
Most mature solution layer: Feedback Mechanisms. Expanding most quickly: Energy Reports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Silicon Valley and Los Angeles corridor anchor platform development and utility deployment for energy efficiency gamification, drawing venture funding and pilot program density unmatched elsewhere.
United States
California's Title 24 Building Energy Efficiency Standards and Texas's ERCOT demand response programs drive utility procurement of behavioral engagement platforms. The EPA's ENERGY STAR certification expansion to multifamily residential buildings mandates performance tracking tools. Class A office markets in New York and Chicago embed white-label gamification layers in tenant experience applications as lease structures pass through utility costs.
Germany
The EU Energy Efficiency Directive mandates building performance benchmarking and continuous improvement protocols across municipal and investor-owned utilities. Smart meter penetration in North Rhine-Westphalia and Bavaria now supports sub-15-minute interval feedback loops for measurable demand reduction. Berlin and Munich host concentrated vendor development activity serving both domestic deployment and export markets.
United Kingdom
Ofgem's energy price cap adjustments and net-zero regulatory pressure accelerate utility adoption of customer engagement platforms. Smart meter rollout thresholds in Greater London and the Midlands enable real-time behavioral feedback infrastructure. Oxford and Cambridge university systems embed campus energy challenges into sustainability curricula, expanding the Game-based Learning segment.
France
The national energy efficiency obligation scheme (CEE) creates procurement incentives for utility behavioral programs. EDF's demand response pilot programs in Île-de-France leverage gamified peak load reduction. Lyon and Grenoble industrial clusters develop hardware-software integration for smart home ecosystem convergence.
Australia
AEMO's grid stability requirements and state-level renewable energy targets drive incentivized challenge deployments for peak demand reduction. Smart meter penetration in New South Wales and Victoria enables community engagement features with neighborhood leaderboards. Sydney and Melbourne commercial real estate markets adopt tenant-facing consumption tracking to satisfy ESG disclosure requirements.
Energy Efficiency Gamification Market Competitive Landscape
Premium-margin players sit above commodity-margin players across AMI integration depth and behavioral analytics sophistication. The vendor base separates into analytics-intensive suites capable of machine learning-driven personalization and notification-only tools with limited data science infrastructure. Three strategic archetypes dominate: enterprise utility platforms with deep meter data management integration, mobile-first specialists targeting residential behavioral programs, and hardware-software bundlers controlling smart home ecosystems. Competitive moves concentrate on strategic partnerships with utility customer information systems and backward integration into IoT sensor networks.
Within the enterprise utility tier, OPower and Sense occupy positions representing contrasting integration strategies—OPower exemplifies deep backward integration into AMI infrastructure while Sense anchors hardware-software ecosystem control. EcoTrack sits within the mobile-first specialist archetype, demonstrating the architectural approach targeting residential behavioral programs through native application delivery.
| Leading Market Players |
|---|
| PowerPlay |
| EcoTrack |
| EngageEnergy |
| OPower |
| EnergyBoost |
| EnergyQuest |
| GreenGamify |
| Sense |
| EcoChallenge |
| Others |
Supply & Pricing Matrix
Silicon wafer price indices and cloud computing cost benchmarks cascade through energy efficiency gamification supply chains, compressing margins for hardware-dependent platform tiers while amplifying pricing power for pure-software analytics vendors serving California utilities under Title 24 mandates.
Pricing Analysis
Outcome-based pricing tied to verified demand reduction kilowatt-hours anchors enterprise utility contracts. Three-tier pricing structure across premium analytics suites, standard engagement tools, and economy notification layers separates vendors by AMI integration depth. Cost compression in the economy tier intensifies because municipal utilities face capital constraints for legacy meter backward compatibility. Commercial building operators exhibit highest price sensitivity due to ESG budget fragmentation, while investor-owned utilities show lowest sensitivity given regulatory recovery mechanisms.
Supply Chain Analysis
Direct-to-utility channels handle enterprise procurement volume, while app marketplace distribution reaches residential subscribers. Hardware component sourcing concentrates in Taiwan, South Korea, and China for IoT sensors and smart thermostat chipsets. Platform development draws from cloud infrastructure providers and specialized behavioral analytics talent pools concentrated in California and Germany. Single-source vulnerability in AMI smart meter firmware creates supply chain risk for vendors requiring backward integration. Distribution runs through utility customer information system partnerships and direct-to-consumer smart home retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Energy Efficiency Directive and California Title 24 standards create a cost-of-compliance barrier that protects incumbent platform vendors with certified AMI integration capabilities while raising capital requirements for new market entrants.
For Market Incumbents: Acquire behavioral analytics engineering teams to counter talent competition from fintech and ad-tech sectors. Deepen backward integration into IoT sensor networks to lock in residential subscriber ecosystems. Defend against mobile-first specialists by embedding gamification layers directly into utility customer information systems, reducing disintermediation risk from standalone applications.
For New Entrants and Emerging Players: Begin with white-label gamification modules for commercial building tenant experience platforms in Class A office markets where procurement bypasses utility enterprise sales cycles. Target educational institution sustainability curricula as the fastest-expanding segment with lower AMI integration barriers. Pursue partnership-first go-to-market strategies with property technology managers rather than direct utility channel competition.
For Investors and Strategic Acquirers: The window for entry favors analytics-intensive platform vendors with demonstrated machine learning personalization engines and California utility reference contracts. Long-term viability hinges on regulatory compliance moats deepening through continuous commissioning mandates and ESG disclosure expansion. Monitor ENERGY STAR certification expansion signals as inflection indicators for multifamily residential market addressability.
| Strategic Initiative | Industry Significance |
|---|---|
| AMI Smart Meter Integration Partnership | Secures backward compatibility with California IOU infrastructure and Title 24 compliance pathways. |
| Machine Learning Personalization Engine Development | Compresses household-level intervention latency for Texas ERCOT demand response programs. |
| Educational Institution Curriculum Embedding | Captures Game-based Learning segment expansion driven by university carbon neutrality commitments. |
| IoT Sensor Network Backward Integration | Enables hardware-software bundles that increase residential subscriber switching costs. |
| Tenant Experience Platform White-Labeling | Bypasses utility procurement cycles to reach commercial building operators directly. |
Research Methodology
Utility regulatory filings, smart meter deployment databases, and EPA ENERGY STAR certification records formed the secondary backbone for market sizing validation. Primary interviews with utility demand response program managers, AMI infrastructure engineers, commercial building sustainability officers, and educational institution facilities directors combined with secondary triangulation. Bottom-up segment modeling across technology deployment modes and top-down regulatory mandate impact assessment converged on volume estimates.
Historical trendline analysis of platform procurement cycles and smart meter penetration thresholds informed the projection framework. Segmentation dimensions modeled include technology delivery mode, end-user category, application functional depth, and solution modularity across the analysis window. CAGRs derived from regression analysis of procurement velocity against regulatory compliance deadlines, incorporating behavioral engagement program enrollment decay curves and ESG disclosure mandate expansion timelines as industry-specific inputs.
Underlying measurement precision varies by segment; utility enterprise contracts carry tighter precision than emerging educational institution deployments. Forecasts reflect assumptions regarding smart meter rollout continuity and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended against behavioral fatigue risk and data interoperability standard evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market