
 Solar Photovoltaic Modules Market | 2026-2036
Solar Photovoltaic Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic Modules Market Insights
The EU Green Deal's Carbon Border Adjustment Mechanism is expanding the compliance burden for non-European module suppliers entering the single market. Jinko Solar leverages integrated polysilicon-to-module capacity to absorb these carbon-accounting costs internally. LONGi Green Energy anchors its competitive position through relentless R&D intensity in monocrystalline wafer efficiency. JA Solar Technology Co., Ltd. competes aggressively on manufacturing scale across Southeast Asian production bases.
Solar photovoltaic modules are semiconductor-based energy conversion devices, typically comprising crystalline silicon cells laminated between tempered glass and polymer back sheets, designed to transform incident solar radiation into direct-current electrical output for grid-connected or standalone power systems. The utility-scale application segment dominates absolute volume deployment, though bifacial modules represent the fastest-expanding product category as tracking systems and albedo-enhancing installations multiply. C-Si technology sustains overwhelming manufacturing share, while thin-film alternatives occupy specialized niches in building-integrated and lightweight rooftop contexts where weight constraints dominate.
The EPA enforces domestic content thresholds for federal clean-energy procurement under the Inflation Reduction Act, reshaping supply chain geography for modules serving US public projects. China's MIIT administers GB standards for cell efficiency and module durability, effectively setting baseline technical parameters for globally traded equipment. India's BIS certification mandates and PLI scheme conditions are forcing foreign suppliers to localize assembly or surrender public-tender eligibility. Stakeholders must monitor how divergent carbon-accounting rules across Brussels, Beijing, and Washington reconfigure cost structures and sourcing decisions.
Market Dynamics
Carbon-accounting border mechanisms and embodied-carbon standards are restructuring procurement geography, forcing module suppliers to reconfigure supply chains around polysilicon provenance and manufacturing energy intensity rather than pure unit economics.
Growth Catalysts
- India's PLI scheme:Production-linked incentives are scaling domestic cell and wafer capacity, creating alternative supply bases outside China for Asia-Pacific demand absorption.
- Bifacial module technology:Dual-sided energy capture is expanding addressable market in high-albedo installations and agrivoltaic applications where land productivity matters.
- EU Green Deal implementation:The Carbon Border Adjustment Mechanism is tightening entry requirements for imported modules, advantaging suppliers with verified low-carbon production.
Market Restraints
- Polysilicon supply concentration:Xinjiang-sourced material faces due diligence barriers under forced-labor prevention acts, constraining input availability for cost-competitive manufacturing.
- Silver paste cost volatility:Metallization paste represents a locked-in cost component for crystalline silicon cells, with price swings directly compressing margin at scale.
- Grid interconnection queues:Utility-scale project commissioning delays in major demand markets are extending working capital cycles and deployment timelines.
Strategic Opportunities
- US domestic content compliance:The Inflation Reduction Act's domestic content bonus credits are creating first-mover advantage for localized module assembly and upstream integration.
- Building-integrated photovoltaics:Thin-film and lightweight crystalline formats are penetrating commercial roofing retrofits where structural load limits excluded conventional modules.
- Green hydrogen offtake:Electrolyzer projects are contracting dedicated solar supply, creating long-term purchase agreements that de-risk manufacturing capacity expansion.
Industry Challenges
- Module recycling infrastructure:End-of-life collection and high-purity silicon recovery capabilities lag installed base growth, creating looming waste management obligations under extended producer responsibility frameworks.
- Technical workforce gaps:Utility-scale installation and grid integration engineering talent is constraining deployment velocity in high-growth markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic Modules Market |
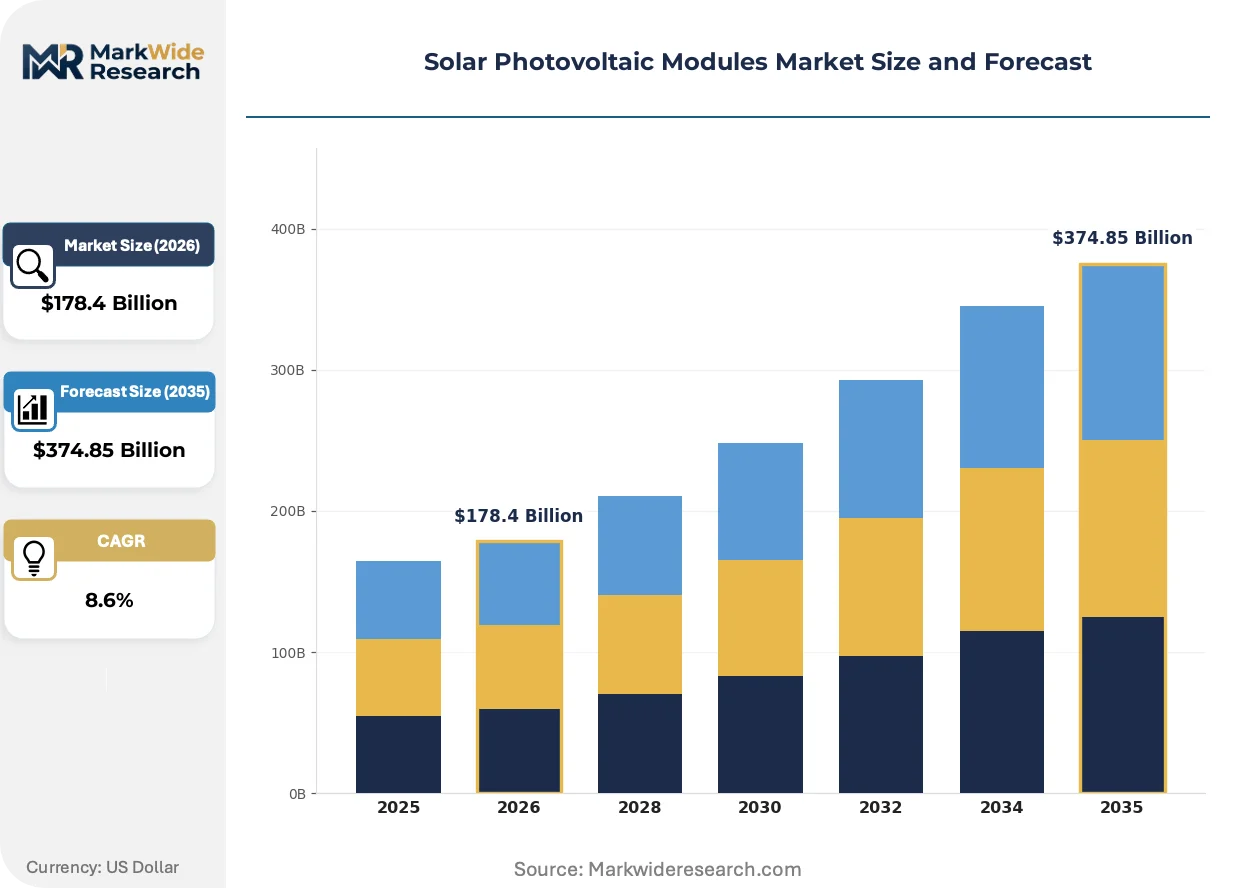
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $374.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: C-Si, CdTe, CIGS, Organic Photovoltaics Application: Residential, Commercial, Utility-Scale, Off-Grid End User: Homeowners, Businesses, Utilities, Government |
| Companies Covered | Jinko Solar, LONGi Green Energy, JA Solar Technology Co., Ltd., Trina Solar, Canadian Solar, Adani Solar, Tongwei Co., Ltd., Astronergy, DMEGC Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic Modules Market Trends and Innovations
Module efficiency trajectories and manufacturing process innovation are compressing cost curves while regulatory carbon accounting is embedding new performance dimensions into procurement decisions.
N-type tunnel oxide passivated contact cells are consolidating manufacturing investment as the successor to PERC architecture. Utility-scale developers are specifying TOPCon modules for new procurement tranches given their higher bifaciality and temperature coefficients. This technology transition is consolidating supplier tiers around those with the capital intensity to retool cell lines at gigawatt scale.
The EU's Carbon Border Adjustment Mechanism is operationalizing embodied-carbon disclosure requirements for module imports into the single market. Manufacturers must now document cradle-to-gate emissions intensity to avoid tariff penalties. Chinese suppliers with integrated polysilicon-to-module production using renewable-heavy grid regions are responding fastest with third-party verified carbon footprints.
Corporate power purchase agreements are displacing merchant offtake as the dominant procurement channel for utility-scale solar. Energy-intensive industrials and data center operators are contracting directly with project developers, bypassing traditional utility intermediaries. This channel shift is most visible in the US and Europe where C&I buyers face Scope 2 emissions reduction mandates.
Solar Photovoltaic Modules Market Segmentation
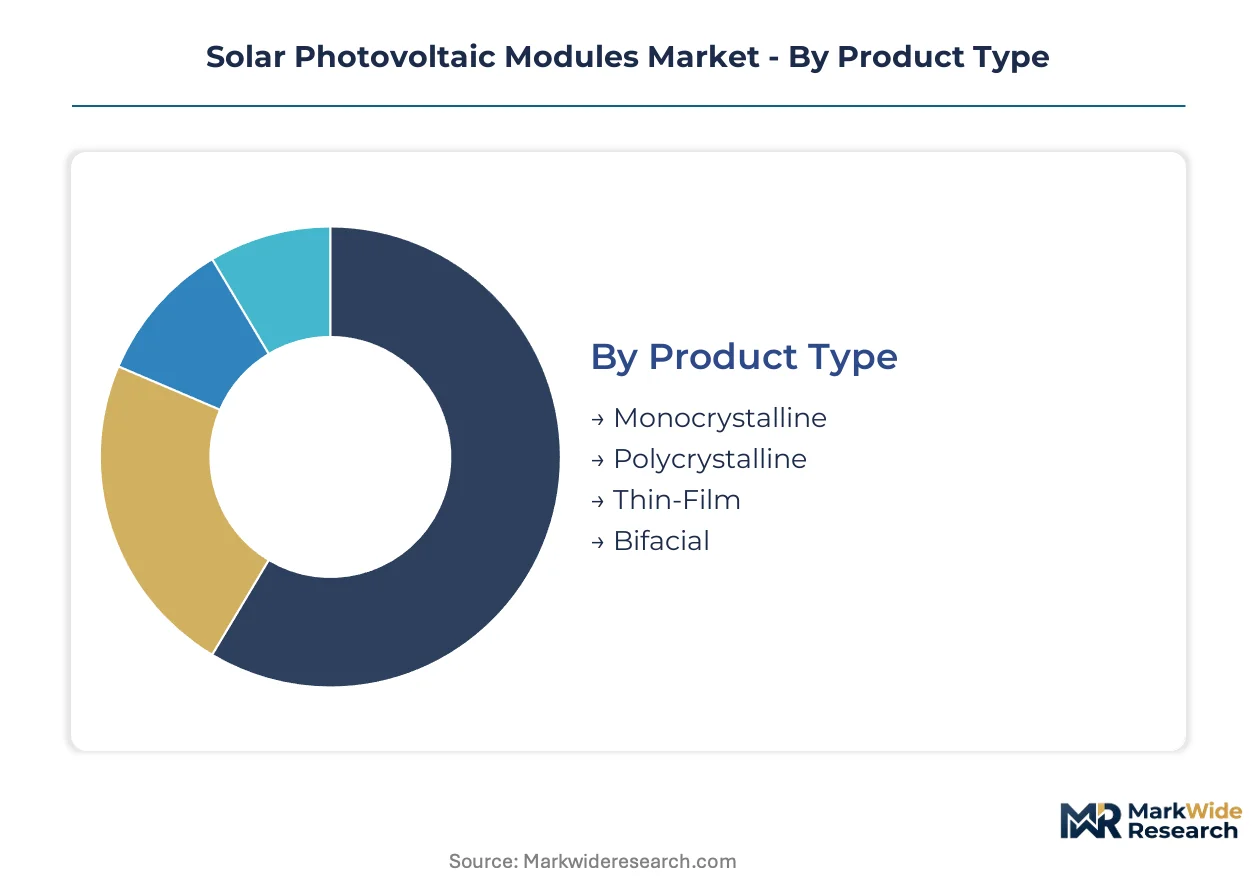
Module specification and application context determine procurement economics, installation logistics, and regulatory compliance pathways. Technology choices cascade through supply chain configuration, carbon-accounting obligations, and end-use performance guarantees. Each segmentation axis reveals distinct competitive dynamics and margin structures.
Product Type:
Cell architecture and wafer structure define efficiency ceilings, degradation profiles, and manufacturing capital intensity.
- Monocrystalline:Single-crystal silicon ingots sliced into wafers yield the highest commercial cell efficiencies. Utility-scale developers in India and the US specify monocrystalline modules for projects seeking maximum energy density per hectare under land-constrained permitting.
- Polycrystalline:Multi-crystal silicon formed through directional solidification offers lower unit costs at modest efficiency penalties. Demand concentrates in price-sensitive distributed installations across Southeast Asian markets where rooftop area abundance offsets efficiency trade-offs.
- Thin-Film:Cadmium telluride and amorphous silicon deposits on glass substrates enable lightweight, flexible formats. Building-integrated and weight-constrained commercial retrofits in Germany and Japan specify thin-film where structural load limits exclude conventional crystalline modules.
- Bifacial:Dual-sided cell construction captures reflected and diffuse light from rear surfaces. Agrivoltaic arrays and high-albedo desert installations in Saudi Arabia and Australia are absorbing bifacial volumes as tracking system compatibility improves.
Mature deployment sits with polycrystalline modules in legacy distributed markets. Newer deployment is concentrated in bifacial formats for utility-scale greenfield projects.
Technology:
Material systems and junction architectures differentiate manufacturing scale, supply chain geography, and efficiency trajectories.
- C-Si:Crystalline silicon dominates manufacturing capacity through established polysilicon purification, ingot growth, and cell fabrication ecosystems. Chinese vertical integration from metallurgical-grade silicon through module assembly controls cost structures for global supply.
- CdTe:Cadmium telluride thin-film deposition achieves competitive levelized cost of energy in utility-scale applications through streamlined manufacturing. First Solar's captive tellurium sourcing and continuous deposition processes anchor CdTe's position in the US utility procurement channel.
- CIGS:Copper indium gallium selenide flexible substrates serve niche building-integrated and portable power applications where form factor flexibility outweighs efficiency premiums. Manufacturing scale constraints limit CIGS to specialized architectural and aerospace offtake.
- Organic Photovoltaics:Polymer and small-molecule absorber layers enable ultra-lightweight, semi-transparent formats. Early-stage commercialization targets indoor energy harvesting and temporary installation contexts where silicon mechanical properties are prohibitive.
Volume concentration favors C-Si manufacturing scale. Technology diversification is expanding fastest in CdTe as domestic content requirements reshape US procurement geography.
Application:
Installation scale and grid connection topology determine module specification, financing structures, and regulatory exposure.
- Residential:Rooftop systems sized 5-20kW serve behind-the-meter consumption with net metering or self-consumption economics. Australia's high retail electricity tariffs and Germany's feed-in tariff legacy sustain residential deployment despite interconnection standard fragmentation across distribution utilities.
- Commercial:C&I installations from 100kW to 5MW balance rooftop or carport siting against demand charge reduction and sustainability procurement mandates. Corporate power purchase agreement aggregation in the US and on-site self-generation in India's industrial estates drive commercial segment specification.
- Utility-Scale:Ground-mounted arrays exceeding 5MW connect at transmission voltage with merchant or contracted offtake. India's renewable purchase obligations and Saudi Arabia's Vision 2030 gigawatt-scale tenders are absorbing utility-scale module volumes through long-term contract structures.
- Off-Grid:Standalone systems with battery storage serve unelectrified rural populations and remote industrial loads. Sub-Saharan African mini-grid developers and Indonesian archipelago electrification programs specify off-grid configurations where grid extension is economically unviable.
Revenue scale centers on utility-scale procurement. Deployment velocity is climbing fastest in commercial applications as corporate Scope 2 reduction commitments harden.
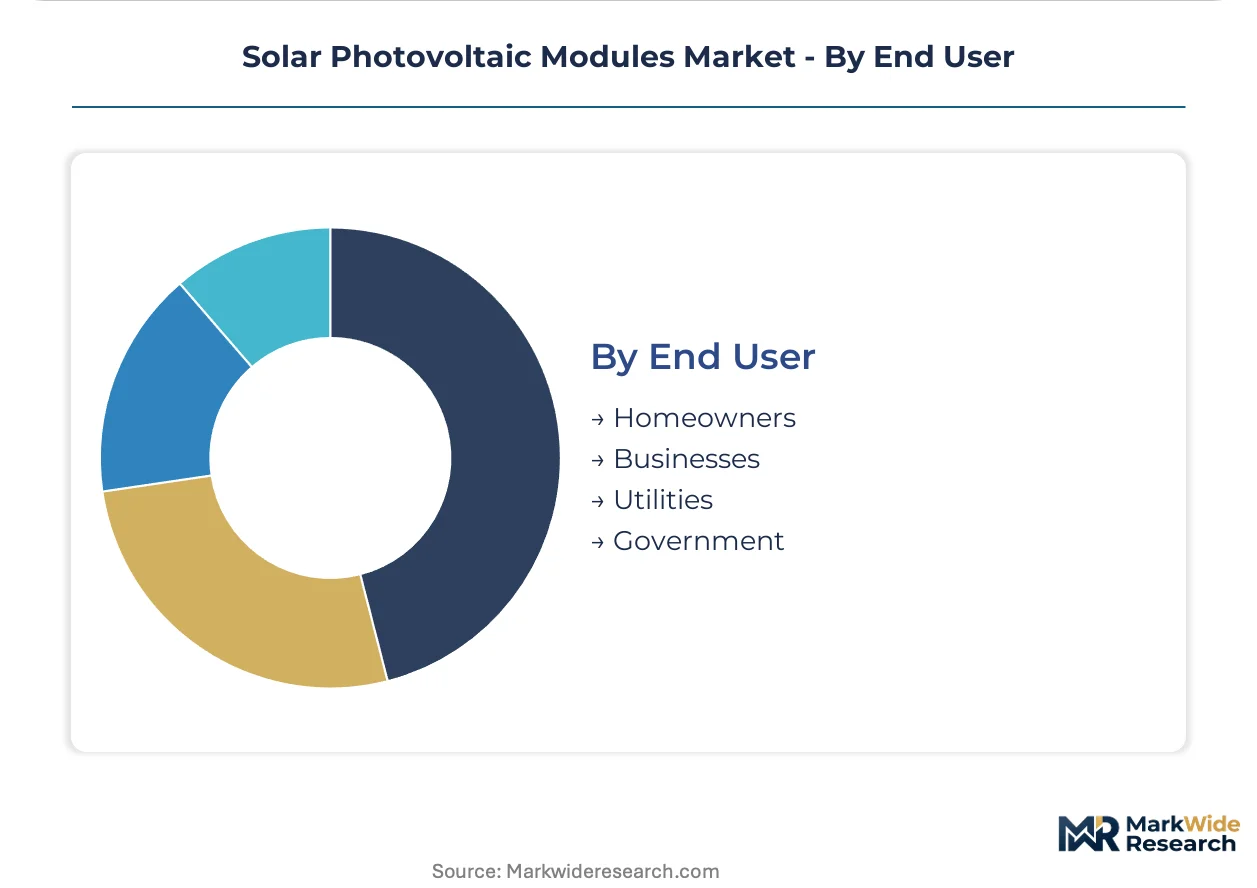
End User:
Procurement authority and capital access differentiate contract structures, performance guarantees, and supplier qualification requirements.
- Homeowners:Individual retail purchasers rely on installer networks for system design, financing facilitation, and maintenance coverage. US solar loan products and European green mortgage incentives shape homeowner acquisition economics.
- Businesses:Commercial and industrial entities contract direct ownership or third-party leases to manage energy costs and emissions reporting. Data center operators in Virginia and semiconductor fabricators in Taiwan are contracting dedicated solar supply for 24/7 clean energy matching.
- Utilities:Vertically integrated and independent power producers procure through competitive tenders with long-term power purchase agreements. State-owned utilities in India and Middle East national champions specify multi-gigawatt tranches with domestic content and local partnership requirements.
- Government:Federal, state, and municipal agencies enforce procurement standards including domestic content, prevailing wage, and disadvantaged business participation. The US EPA administers Inflation Reduction Act bonus credit eligibility through domestic content verification protocols.
Contract standardization sits with utility procurement. Procurement complexity is expanding fastest in government segments as industrial policy embeds non-price criteria into award decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of module procurement volumes, with India and the United States following as concentrated demand centers. Utility-scale deployment drives procurement intensity across these markets, while policy mechanisms reshape sourcing geography.
China
Domestic installation quotas and dual carbon goals sustain gigawatt-scale procurement from state-owned utilities. MIIT-administered GB standards for cell efficiency and module durability set technical baselines for exported equipment. Xinjiang polysilicon clusters face due diligence barriers under forced-labor prevention acts, constraining input availability for cost-competitive manufacturing.
India
Renewable purchase obligations and PLI scheme incentives accelerate utility-scale tendering by state distribution companies. BIS certification mandates and domestic content conditions force foreign suppliers to localize assembly or surrender public-tender eligibility. Gujarat and Rajasthan host manufacturing clusters where cell and wafer capacity scales under production-linked incentives.
United States
Data center operators and semiconductor fabricators contract dedicated solar supply for 24/7 clean energy matching. EPA-administered domestic content thresholds for federal procurement reshape supply chain geography under Inflation Reduction Act bonus credits. Texas and California utility-scale pipelines face extended interconnection queues, delaying commissioning timelines.
Germany
Commercial rooftop retrofits and agrivoltaic installations absorb bifacial module volumes as albedo-enhancing deployment expands. EU Green Deal Carbon Border Adjustment Mechanism tightens entry requirements for imported modules, advantaging suppliers with verified low-carbon production. Bavaria and North Rhine-Westphalia concentrate building-integrated photovoltaics demand where structural load limits exclude conventional modules.
Saudi Arabia
Vision 2030 gigawatt-scale tenders absorb utility-scale module volumes through long-term contract structures with domestic content requirements. NEOM Northwest and Eastern Province host solar manufacturing zones where localization partnerships qualify suppliers for state-owned utility procurement. Green hydrogen offtake from electrolyzer projects contracts dedicated solar supply, de-risking capacity expansion.
Solar Photovoltaic Modules Market Competitive Landscape
Chinese producers anchor one tier; North American and European specialists hold differentiated positions in domestic-content-compliant channels. The vendor base concentrates around vertically integrated polysilicon-to-module operators and technology-focused wafer specialists. Two archetypes dominate: scale-driven integrated manufacturers and efficiency-focused monocrystalline innovators. Capacity expansion and carbon-accounting verification constitute the primary competitive moves as border mechanisms reshape procurement eligibility.
Among Chinese integrated manufacturers, Jinko Solar, LONGi Green Energy, and JA Solar Technology Co., Ltd. represent the scale-driven tier. These entities exemplify vertical integration from polysilicon through module assembly, positioning them to absorb carbon-accounting costs internally. Their geographic concentration aligns with renewable-heavy grid regions capable of generating third-party verified low-carbon footprints for EU market entry.
| Leading Market Players |
|---|
| Jinko Solar |
| LONGi Green Energy |
| JA Solar Technology Co., Ltd. |
| Trina Solar |
| Canadian Solar |
| Adani Solar |
| Tongwei Co., Ltd. |
| Astronergy |
| DMEGC Solar |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China and India anchor manufacturing capacity expansion, translating state-supported financing into aggressive unit-cost positioning that compresses margins for private-capital-dependent competitors. This ownership pattern tightens pricing discipline while accelerating polysilicon-to-module capacity buildouts that reshape procurement geography under carbon-accounting border mechanisms.
Pricing Analysis
Short lead-time premiums command substantial markups for utility-scale developers facing interconnection queue delays, while spot inventory from Southeast Asian assembly facilities trades at discounts to contract volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon-intensity certification and domestic-content compliance, with EU Green Deal CBAM thresholds driving the premium tier. Price erosion runs through economy-tier polycrystalline modules as Chinese integrated producers absorb margin compression to maintain volume share. Distributed residential buyers in price-sensitive Southeast Asian markets exhibit highest elasticity, while data center operators contracting 24/7 clean energy matching show lowest sensitivity to unit premiums.
Supply Chain Analysis
Module refurbishment and end-of-life silicon recovery flows remain underdeveloped, creating stranded asset risk as extended producer responsibility frameworks mature across European markets. Manufacturing concentrates in China, India, and Vietnam, with Xinjiang polysilicon clusters facing due diligence barriers under forced-labor prevention acts. Supply draws from metallurgical-grade silicon, silver metallization paste, and tempered glass inputs, with silver paste cost volatility representing a locked-in margin compression point. Single-source vulnerability sits with Xinjiang-sourced polysilicon for cost-competitive production. Distribution runs through utility-scale EPC contractors, independent power producers, and corporate PPA aggregators serving C&I offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Carbon Border Adjustment Mechanism erects a compliance moat that advantages suppliers with verified low-carbon production, raising capital requirements for market entry while embedding cost-of-compliance into procurement decisions.
For Market Incumbents: Lock in carbon-accounting verification capabilities through third-party auditing partnerships to defend EU market access against emerging entrants lacking documentation infrastructure. Prioritize backward integration into polysilicon purification using renewable-heavy grid regions to internalize embodied-carbon cost advantages. Expand cell and wafer capacity in India under PLI scheme conditions to capture public-tender eligibility that foreign competitors forfeit. For New Entrants and Emerging Players: Utility-scale developers in Saudi Arabia and Australia represent the most penetrable channel, given Vision 2030 localization requirements and high-albedo bifacial demand that reset competitive positioning away from established Chinese scale. Target building-integrated photovoltaics in Germany and Japan where structural load constraints exclude conventional crystalline modules. Pursue joint-venture structures with state-owned utilities to satisfy domestic content mandates. For Investors and Strategic Acquirers: EPA domestic content bonus credit activation for federal procurement is the leading indicator that US supply chain localization will accelerate, warranting exposure to assembly capacity in Texas and California. Five-to-ten-year viability favors vertically integrated operators with polysilicon-to-module control and verified low-carbon footprints. Monitor BIS certification approval timelines for foreign suppliers as signal of India's public-tender accessibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Footprint Verification Program | Third-party auditing partnerships secure EU CBAM compliance and tariff avoidance for module imports. |
| India PLI-Aligned Capacity Expansion | Cell and wafer manufacturing in Gujarat qualifies suppliers for state distribution company tenders. |
| US Domestic Content Compliance Buildout | Localized assembly in Texas satisfies EPA thresholds for Inflation Reduction Act bonus credits. |
| Green Hydrogen offtake Partnership | Long-term electrolyzer supply contracts de-risk manufacturing capacity expansion in Saudi Arabia. |
| TOPCon Cell Line Retooling | N-type tunnel oxide passivated contact investment consolidates supplier tier position for utility-scale procurement. |
Research Methodology
Multi-period observation of module procurement volumes, carbon-intensity disclosures, and interconnection queue durations anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA project databases, IEA renewable energy reports, FERC interconnection filings, and customs trade records. Bottom-up capacity buildout tracking and top-down demand forecast reconciliation ensured cross-verification of volume estimates.
Segment-weighting across cell architecture, application scale, and regional regulatory framework shaped the analytical framework over the projection horizon. Crystalline silicon technology splits, utility-scale versus distributed deployment patterns, and domestic-content compliance tiers formed core segmentation dimensions. CAGRs derived from installed capacity trajectories, policy incentive durability assessments, and learning-curve cost compression modeling. Forecast inputs incorporated silver paste price volatility assumptions and polysilicon supply concentration risk factors.
Caveats apply where forced-labor due diligence enforcement, grid interconnection queue reform, or carbon-border tariff rate adjustments could materially shift the outlook. Forecasts reflect documented assumptions regarding policy continuity and technology transition timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market