
 Energy Efficient Windows Market | 2026-2036
Energy Efficient Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Windows Market Intelligence
The substitution of traditional wood and aluminum with advanced vinyl and composite frame materials is broadening the performance and cost options available to builders. Andersen Corporation leverages its brand strength in the premium wood-clad and composite window categories. Pella Corporation differentiates with custom solutions and smart window integrations for the high-end residential market. Meanwhile, Jeld-Wen sustains a broad portfolio, competing across multiple material types and price points.
Energy efficient windows are fenestration products engineered to minimize thermal transfer and improve a building's insulation. Their performance is quantified by metrics like a low U-factor, indicating less heat loss, and a tailored Solar Heat Gain Coefficient (SHGC) to control passive solar energy. Triple glazing products command the premium end of the market, while double glazing remains the volume standard. The residential end-user segment, particularly for replacement and renovation installations, constitutes the largest source of demand.
Government regulations are a primary market catalyst, with programs like the US EPA's ENERGY STAR and the EU's CE marking setting stringent performance benchmarks. In China, national GB standards for building energy conservation are pushing manufacturers toward higher-performing glazing and frame technologies. Manufacturers must now navigate the challenge of integrating smart glass technologies and advanced coatings while maintaining accessible price points for mass-market adoption.
Market Dynamics
The market's primary dynamic is the convergence of stringent government energy mandates, such as the EU's building performance directives, with homeowner demand for lower utility costs, forcing a rapid evolution in material science and glazing technology.
Growth Catalysts
- Government Mandates:The US EPA's ENERGY STAR program and Europe's CE marking requirements set progressively stricter U-factor and SHGC benchmarks, compelling manufacturers to innovate and phase out lower-performing products from their portfolios.
- Renovation Incentives:Government-backed financial incentives for thermal renovation projects, particularly prominent in countries like Germany, directly subsidize the replacement of old windows, accelerating adoption in the large residential retrofit segment.
- Material Advancement:The substitution of traditional wood with advanced vinyl and composite frame materials expands performance options, offering improved thermal breaks and durability at more accessible price points for builders and homeowners.
Market Restraints
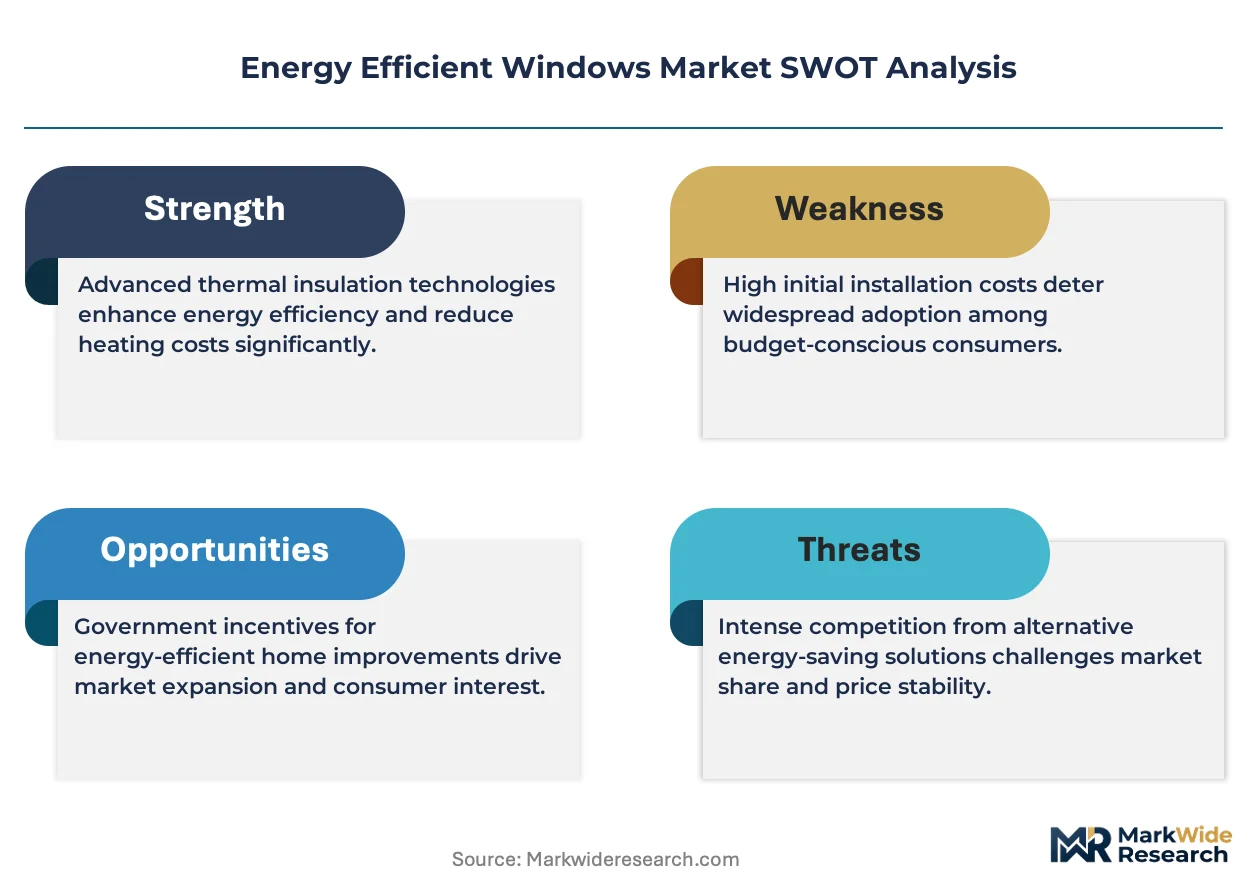
- High Upfront Cost:Premium technologies like triple glazing and dynamic smart glass carry a significant cost premium over standard double-glazed units, limiting their adoption to the high-end residential and commercial construction sectors.
- Installation Complexity:Achieving the rated energy performance of advanced windows depends on precise, airtight installation, a skill not universally present in the fragmented residential contractor base, leading to performance gaps.
- Competition from Legacy Products:In regions with less stringent building codes, lower-cost traditional aluminum or basic wood windows remain a viable, albeit less efficient, alternative that slows the penetration of advanced products.
Strategic Opportunities
- Emerging Market Modernization:Rapid urbanization and the implementation of new national building energy codes, such as China's GB standards, create vast new markets for energy efficient fenestration products in new construction projects.
- Smart Building Integration:The convergence of energy efficient windows with smart home ecosystems enables dynamic control of solar heat gain and natural light, creating new value-added product categories for tech-savvy consumers.
- Net-Zero Building Initiatives:Global commitments to decarbonize the built environment create a long-term regulatory tailwind, positioning high-performance windows as a critical component for achieving future net-zero energy building standards.
Industry Challenges
- Supply Chain Volatility:Manufacturers face difficulties in securing a stable supply of specialized components like low-emissivity coatings and inert gases at predictable costs, impacting production planning and final product pricing.
- Navigating Regional Standards:The lack of a single global performance standard requires manufacturers to test and certify products for multiple regional schemes, such as ENERGY STAR in the US and CE marking in the EU, increasing compliance costs.
- Consumer Education Gap:A significant portion of the residential market lacks a deep understanding of performance metrics like U-factor and SHGC, making it difficult to communicate the long-term value of higher-cost windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Windows Market |
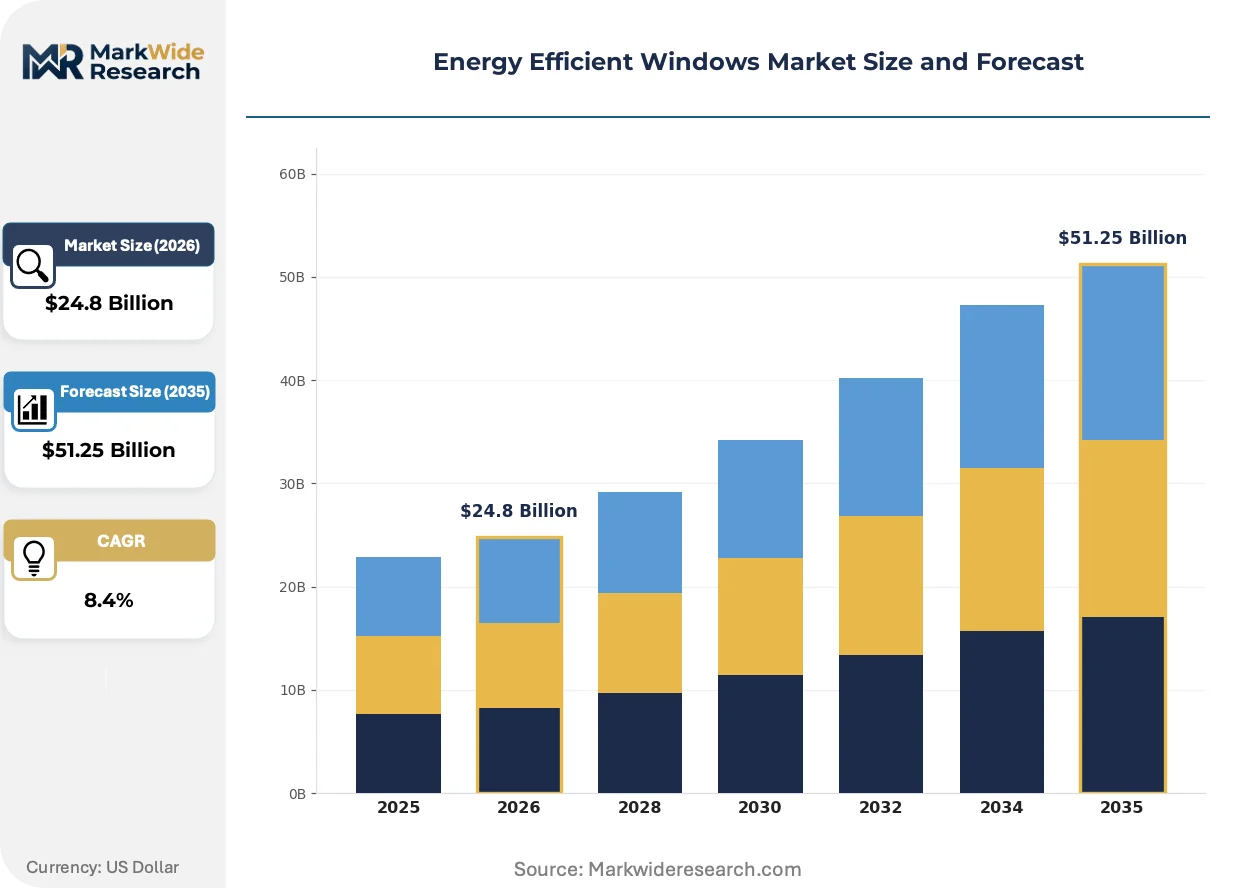
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Glazing, Triple Glazing, Low-E Glass, Smart Glass Frame Material: Vinyl, Wood, Aluminum, Composite End User: Residential, Commercial, Industrial, Institutional Installation Type: Retrofit, New Construction, Replacement, Renovation |
| Companies Covered | Andersen Corporation, Jeld-Wen, Pella Corporation, MI Windows and Doors, Ply Gem Windows, Marvin Windows & Doors, Milgard Manufacturing, YKK AP America, PGT Windows, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Windows Market Strategic Shifts & Innovations
Performance metrics are evolving beyond simple thermal resistance to encompass a building's holistic energy profile. This shift drives innovation in materials science and system integration, redefining what constitutes a high-performance window for modern construction and renovation projects.
Advanced frame materials, including multi-chamber vinyl and pultruded fiberglass composites, provide superior thermal breaks and structural stability. Residential retrofit and new construction segments are steadily adopting these materials over traditional wood or aluminum. This development is modularizing window assembly, enabling manufacturers to combine specific frame profiles with different glazing packages to meet precise regional energy codes.
Europe's Energy Performance of Buildings Directive (EPBD) is a significant regulatory driver for the market. The directive's mandates for Nearly Zero-Energy Buildings (NZEB) effectively require the use of ultra-high-performance fenestration. Consequently, the new construction sector in countries like France and the Netherlands is rapidly standardizing on triple-glazed units with advanced low-emissivity coatings.
Homeowner purchasing decisions are shifting toward whole-building performance assessments rather than isolated product upgrades. This change disrupts the direct-to-consumer replacement model, elevating the role of energy auditors and building science consultants who specify integrated systems. This trend is most pronounced in North American residential markets where utility and government rebates incentivize comprehensive energy efficiency retrofits.
Energy Efficient Windows Market Segmentation
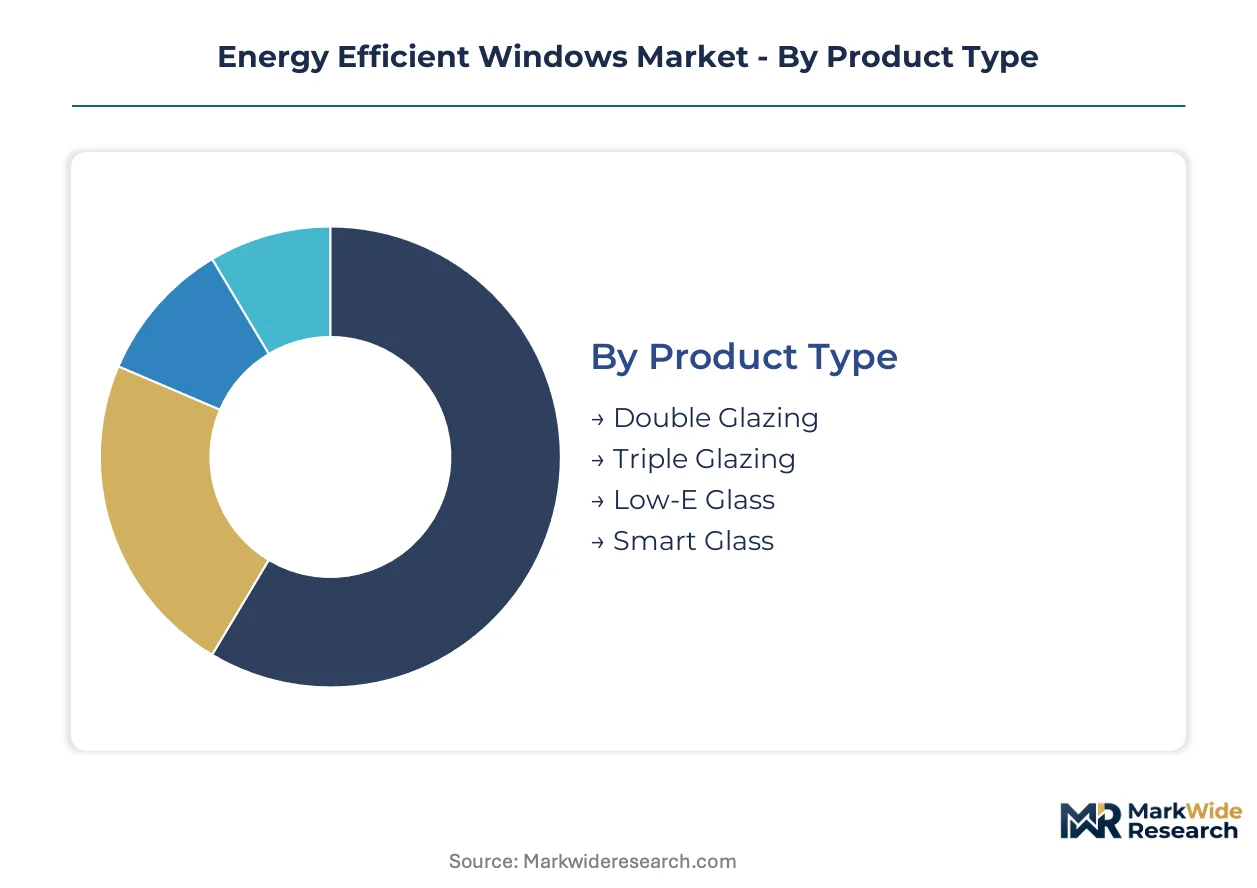
The Energy Efficient Windows Market is segmented to provide a granular view of product adoption across diverse applications and user needs. Understanding these distinctions helps manufacturers align product development with specific performance requirements and market demand drivers. This segmentation highlights the interplay between material science, regulatory mandates, and end-user preferences.
Product Type:
Buyers in the energy efficient windows market differentiate their product choices based on the specific performance characteristics required for thermal regulation and light control.
- Triple Glazing:Incorporates three panes of glass with two sealed air or inert gas-filled spaces, significantly reducing heat transfer and enhancing sound insulation. Demand concentrates in colder climates like Germany, driven by stringent net-zero building initiatives and high energy performance standards.
- Low-E Glass:Features a microscopic metallic coating that reflects infrared light, improving thermal performance by reducing heat loss in winter and heat gain in summer. This technology sees high adoption in residential retrofits across Europe, driven by energy efficiency mandates and homeowner utility cost savings.
- Double Glazing:Consists of two glass panes separated by an inert gas-filled space, offering improved insulation over single-pane windows for broad market applications.
- Smart Glass:Utilizes electrochromic or thermochromic technologies to dynamically adjust opacity or tint, controlling light and solar heat gain for advanced building management systems.
Double Glazing leads volumes today; Smart Glass is gaining share fastest.
Frame Material:
Frame material selection often reflects a balance between initial investment, aesthetic preferences, and long-term durability requirements for a building project.
- Vinyl:Constructed from polyvinyl chloride (PVC), offering excellent thermal insulation, low maintenance, and cost-effectiveness for widespread adoption. The residential replacement segment in North America shows strong demand for vinyl frames due to their accessibility and performance balance.
- Composite:Combines materials like fiberglass, wood fibers, and polymer resins, providing superior strength, durability, and thermal performance with enhanced structural integrity. New construction projects in Europe increasingly specify composite frames to meet stringent U-factor requirements.
- Wood:Provides natural aesthetics and good insulation properties, often chosen for its traditional appearance and sustainability in custom residential and historic renovation projects.
- Aluminum:Known for its strength and slim profiles, aluminum frames are durable but typically require integrated thermal breaks for energy efficiency in modern construction.
Vinyl frames currently dominate market volumes, while composite materials are expanding most quickly.
End User:
The end-user segment for energy efficient windows is defined by the distinct operational needs and regulatory compliance requirements of various building types.
- Residential:Encompasses single-family homes, multi-family dwellings, and apartment buildings, where homeowners prioritize energy cost savings, comfort, and aesthetic appeal. This segment constitutes the largest source of demand, particularly for replacement and renovation installations.
- Commercial:Includes office buildings, retail spaces, and hospitality establishments, focusing on occupant comfort, energy code compliance, and aesthetic appeal for large-scale projects. Demand for high-performance fenestration in this segment is strong in urban centers like those in the Netherlands.
- Industrial:Covers manufacturing plants, warehouses, and factories, where durability, security, and specific environmental controls are primary concerns for operational efficiency.
- Institutional:Pertains to schools, hospitals, and government buildings, requiring robust, long-lasting windows that meet strict energy, safety, and acoustic regulations.
Residential applications represent the largest demand, with commercial installations showing steep expansion trajectory.
Installation Type:
Installation type reflects the project scope and the stage of a building's lifecycle, influencing product specifications and market dynamics.
- Retrofit:Involves upgrading existing buildings with energy efficient windows to improve thermal performance and reduce utility costs, often driven by government incentives. Government-backed financial incentives for thermal renovation projects in Germany significantly accelerate adoption in this segment.
- New Construction:Pertains to the installation of windows in newly built structures, driven by evolving building codes and architectural specifications from project inception. China's national GB standards for building energy conservation are pushing manufacturers toward higher-performing glazing in new builds.
- Replacement:Focuses on direct substitution of old windows with new ones, often driven by wear and tear, minor aesthetic upgrades, or improved functionality.
- Renovation:Encompasses broader remodeling projects where windows are part of a larger overhaul to update building aesthetics, functionality, and energy performance.
Retrofit projects generate significant market activity, while new construction is consistently expanding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European building performance directives drive significant demand for high-performance fenestration products. Homeowner demand for lower utility costs converges with government mandates, accelerating market evolution. Renovation incentives and material advancements further shape regional adoption patterns.
Germany
Demand for high-performance windows in Germany stems from stringent net-zero building initiatives and homeowner focus on utility cost reduction. Government-backed financial incentives for thermal renovation projects directly subsidize window upgrades. Berlin's green building initiatives heavily favor triple glazing and advanced frame materials.
United States
United States residential retrofit segment drives substantial demand for energy efficient windows, motivated by energy cost savings. The US EPA's ENERGY STAR program sets progressively stricter benchmarks for U-factor and SHGC. California's strict building codes drive innovation in low-emissivity glass technologies across its major cities.
China
China's rapid urbanization and extensive new construction projects generate vast markets for advanced fenestration products. National GB standards for building energy conservation push manufacturers toward higher-performing glazing. Shanghai's ambitious green construction targets necessitate high-performance glazing and integrated smart glass solutions.
Netherlands
Netherlands' new construction sector rapidly standardizes on triple-glazed units due to NZEB mandates. Europe's Energy Performance of Buildings Directive (EPBD) effectively requires ultra-high-performance fenestration for new builds. Amsterdam's focus on sustainable urban development integrates high-performance fenestration into residential and commercial projects.
France
French decarbonization goals and residential renovation initiatives fuel demand for improved thermal performance. The Energy Performance of Buildings Directive, alongside national policies, mandates higher efficiency levels for buildings. Lyon's commitment to eco-districts promotes advanced vinyl and composite frames, enhancing energy efficiency.
Energy Efficient Windows Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers broaden their offerings across material types and price points. The market exhibits a tiered structure, with established brands focusing on premium segments and specialized players targeting niche applications. Geographic expansion and strategic partnerships represent two dominant competitive moves, enabling access to new markets and technology sharing. Manufacturers balance innovation in smart glass with the need for accessible price points for mass-market adoption.
Among the established North American fabricators, Andersen Corporation exemplifies a premium brand strategy, focusing on wood-clad and composite window categories. Pella Corporation, another US-based entity, differentiates with custom solutions and smart window integrations for the high-end residential market. Meanwhile, Jeld-Wen, an international manufacturer, sustains a broad portfolio, competing across multiple material types and price points to capture wider market share. These companies collectively anchor the market's mid to high-end segments.
| Leading Market Players |
|---|
| Andersen Corporation |
| Jeld-Wen |
| Pella Corporation |
| MI Windows and Doors |
| Ply Gem Windows |
| Marvin Windows & Doors |
| Milgard Manufacturing |
| YKK AP America |
| PGT Windows |
Cost & Logistics Intelligence
Europe's building performance directives, alongside homeowner demand for lower utility costs, compel manufacturers to innovate in materials and glazing technology. This evolution influences pricing structures, balancing advanced performance with mass-market accessibility.
Pricing Analysis
Volatile input costs for specialized components like low-emissivity coatings and inert gases directly influence final product pricing. The market primarily operates on a per-unit transactional model, with a tiered pricing structure across premium, standard, and economy levels. Price differentiation stems from performance metrics, certification levels like ENERGY STAR, and material sophistication such as smart glass technology. Pricing softness can emerge in volume segments due to competition from legacy products. Residential retrofit buyers exhibit higher price sensitivity compared to commercial and high-end residential clients.
Supply Chain Analysis
Meeting stringent performance benchmarks like Europe's CE marking and the US EPA's ENERGY STAR program acts as a critical qualification gate for suppliers. The supply chain draws heavily on specialized glass manufacturers and advanced coating providers, often concentrated in specific regions. Raw material dependencies include low-emissivity coatings, inert gases, and specialized frame materials. A structural risk involves single-source vulnerability for these high-performance components. Distribution primarily runs through a network of fabricators, builders, and specialized contractors for both residential and commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Energy Efficient Windows Market presents a margin-expansion story, driven by the increasing shift towards premium-tier products like smart glass and triple glazing. Homeowner demand for utility cost savings fuels this transition to higher-value fenestration.
For Market Incumbents: Cement brand loyalty by investing in advanced R&D for next-generation low-emissivity coatings and dynamic smart glass technologies. Integrate vertically into key component manufacturing to mitigate supply chain volatility, a significant threat to production stability. Control specialized installer networks to ensure precise, airtight installation, directly addressing performance gaps. Leverage established certifications like ENERGY STAR to differentiate offerings against lower-cost legacy products.
For New Entrants and Emerging Players: Enter via niche high-performance segments, focusing on smart building integration within the commercial sector in urban centers like Amsterdam. Target the residential retrofit market in Germany, leveraging strong government incentives and a focus on ultra-high-performance fenestration. The new construction segment in China presents a penetrable opportunity for advanced glazing and frame technologies. Go-to-market strategies should emphasize bundled solutions that integrate dynamic window control with broader smart home ecosystems.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized component manufacturers and smart glass technology firms possessing unique intellectual property. The market's long-term viability is underpinned by global decarbonization goals and the continuous tightening of building energy performance directives. Acquisition targets should include innovators in advanced low-emissivity coatings or dynamic tinting solutions. A critical signal to watch is the accelerated adoption rate of triple glazing units in new construction beyond current European mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in Smart Glass | Accelerates the integration of dynamic light and thermal control features for tech-savvy consumers. |
| Vertical Integration into Low-E Coating Production | Secures critical supply of specialized components, mitigating volatility and cost pressures for manufacturers. |
| Expansion into Emerging Construction Markets | Capitalizes on rapid urbanization and new national building energy codes in countries like China. |
| Strategic Partnerships with Smart Home Platforms | Creates new value-added product categories by enabling dynamic control of solar heat gain. |
| Certification and Compliance Specialization | Ensures product alignment with progressively stricter U-factor and SHGC benchmarks set by EPA ENERGY STAR. |
Research Approach
Coverage spans Europe, the United States, and China, with primary inputs from each region's key stakeholders. This includes in-depth interviews with building science consultants, architects, commercial procurement managers, and residential contractors. Secondary validation draws from government building code databases, industry association reports, and manufacturer technical specifications. A rigorous bottom-up and top-down triangulation approach ensures data accuracy across diverse market segments.
Rate-of-change decomposition analyzes growth drivers and restraints across the projection horizon. The analytical framework models segmentation dimensions including product type, frame material, end-user, installation type, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) are derived from historical adoption trends and projected market dynamics. Key forecast inputs include evolving U-factor requirements and government incentive program budgets for thermal renovation projects.
Inputs from national building code databases and manufacturer disclosures were available through the study window; gaps in real-time installation cost data introduce uncertainty bands. Forecasts reflect assumptions regarding future regulatory stringency and material science advancements. A model refresh is warranted upon material change in global energy pricing or building performance directives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Retrofits Market