
 Economizer Market | 2026-2036
Economizer Market Size, Share, and Industry Trends Forecast 2026-2036
Economizer Market Analysis
OEM-direct contracting is rewriting how economizer systems reach end users in North America and Europe. Honeywell International Inc leverages its building automation portfolio to control specification channels across commercial HVAC projects. Johnson Controls International plc anchors its position through deep vertical integration into controls and heat exchanger manufacturing. Schneider Electric competes on digital twin integration for predictive economizer maintenance.
An economizer is a mechanical device that pre-cools or pre-heats incoming air or fluid using exhaust stream energy, typically achieving effectiveness ratios of 50-80 percent in commercial HVAC applications. The device reduces chiller or boiler load by transferring sensible or latent heat between two isolated fluid streams via plate-and-frame or rotary wheel exchangers. Heat Recovery technology leads the technology segment due to its direct applicability across climate zones and payback periods under five years. Commercial Buildings dominate end user demand as Class A office retrofits accelerate in urban cores. Cloud-Based deployment is gaining share fastest where building management platforms aggregate sensor data across multi-site portfolios.
The EPA enforces emissions thresholds that directly mandate economizer inclusion in large commercial boiler systems, while the EU Green Deal and F-Gas Regulation push refrigerant-based systems toward lower-GWP alternatives. China's MEE implements dual carbon goals through provincial building efficiency mandates that specify minimum heat recovery effectiveness. Stakeholders must monitor how refrigerant phase-down schedules interact with air-cooled economizer designs in jurisdictions with divergent chemical approval timelines.
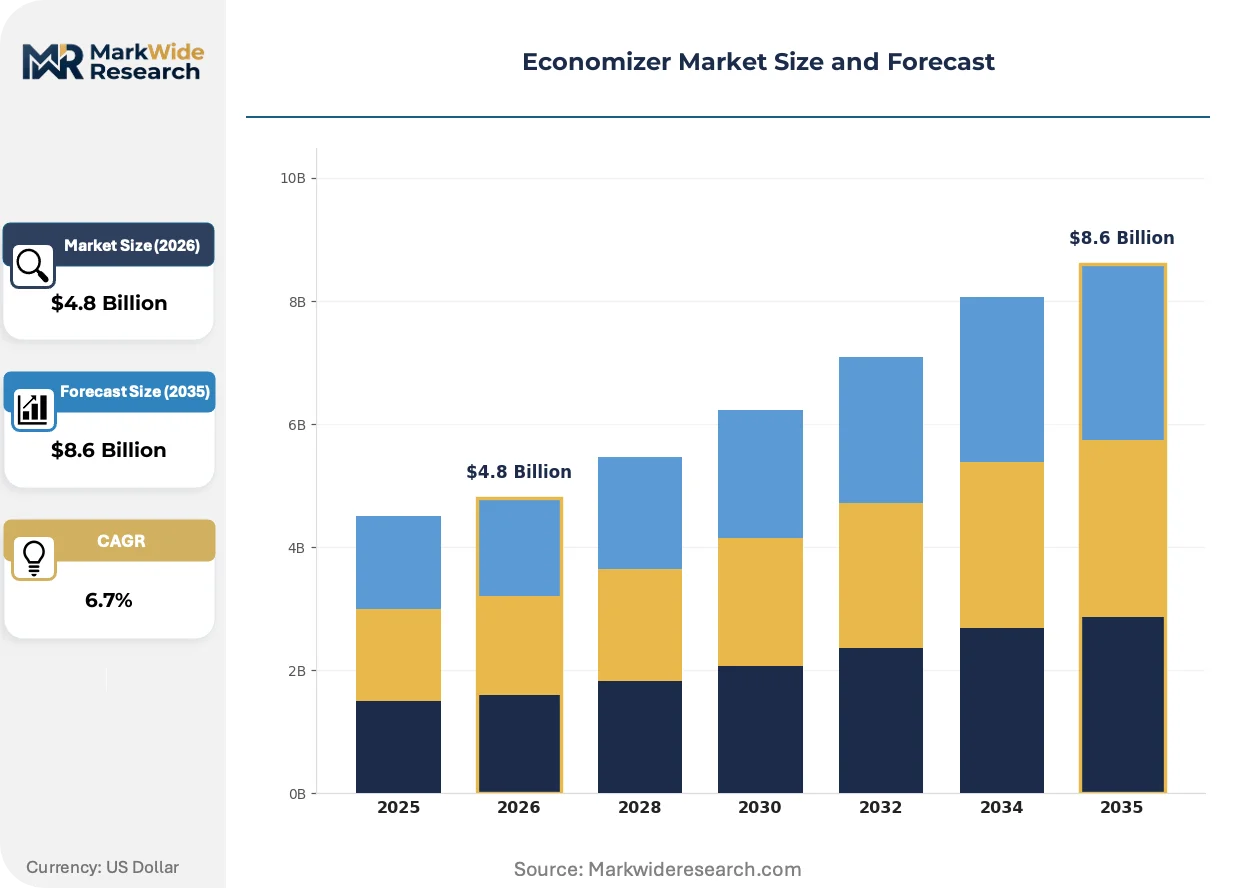
Market Dynamics
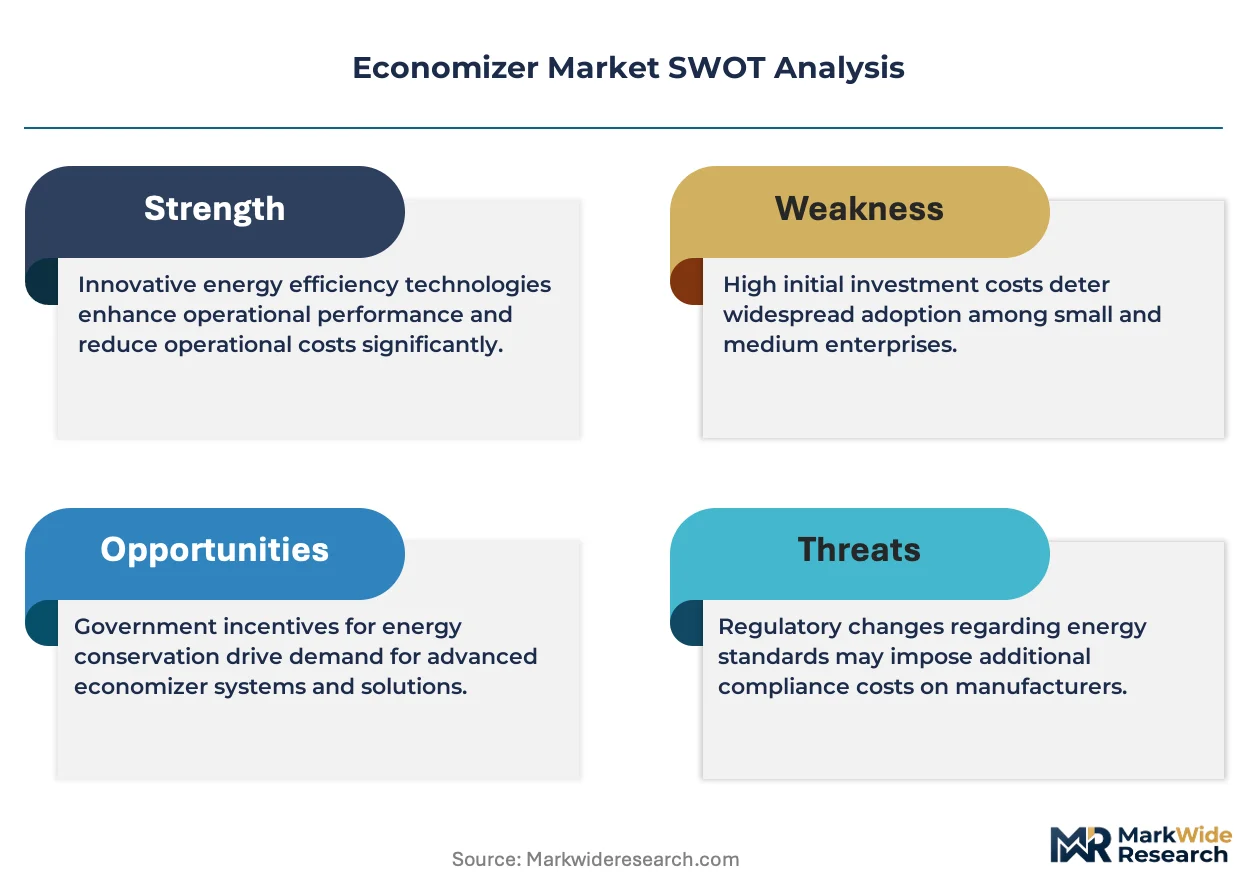
Building energy code tightening across multiple jurisdictions is forcing rapid specification upgrades in commercial HVAC systems, compressing payback thresholds and accelerating replacement cycles for legacy heat recovery equipment.
Growth Catalysts
- EPA Emissions Thresholds:The EPA mandates economizer inclusion in large commercial boiler systems above defined thermal capacities, creating specification pull through engineered procurement channels.
- China's Provincial Building Efficiency Mandates:The MEE implements dual carbon goals through effectiveness minimums that specify heat recovery ratios, driving retrofit demand in Tier-1 and Tier-2 urban cores.
- Plate-and-Frame Exchanger Advances:Improved sealing technologies and corrosion-resistant coatings extend service intervals in coastal and industrial environments, expanding addressable climate zones.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger core materials face commodity input swings that compress fabrication margins and destabilize project bidding.
- Refrigerant Phase-Down Schedules:The EU F-Gas Regulation and divergent national chemical approval timelines create specification fragmentation that complicates air-cooled economizer design standardization.
- Technical Limitation in Low-Delta-T Applications:Economizer effectiveness degrades below 50 percent when exhaust-to-intake temperature differentials narrow, constraining deployment in temperate maritime climates.
Strategic Opportunities
- Digital Twin Integration:Convergence of building automation platforms with physics-based simulation enables predictive maintenance contracts that monetize uptime guarantees.
- Cloud-Based Deployment:Multi-site portfolio operators aggregate sensor data across distributed assets, creating demand for centralized economizer performance analytics.
- India's Bureau of Energy Efficiency:The BEE's commercial building code adoption creates a regulatory tailwind for heat recovery specifications in new construction and major renovation.
Industry Challenges
- Controls Integration Complexity:Economizer sequencing logic must interface with legacy chiller and boiler management systems, requiring specialized commissioning expertise that strains field service capacity.
- Certification Timeline Compression:Multiple jurisdiction approvals for refrigerant-based designs extend product launch cycles, delaying revenue recognition on next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Economizer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Heat Exchangers, Control Valves, Fans, Sensors End User: Commercial Buildings, Industrial Facilities, Power Plants, District Heating Systems Deployment: On-Premise, Cloud-Based, Hybrid, Retrofits Technology: Heat Recovery, Water Loop, Air-Cooled, Refrigeration |
| Companies Covered | Honeywell International Inc, Alfa Laval, Johnson Controls International plc, Schneider Electric, Cleaver-Brooks, Inc., Thermax Limited, Babcock & Wilcox, SAACKE GmbH, BELIMO Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Economizer Market Emerging Trajectories
Sensor fusion and edge computing are transforming economizer control architectures from reactive damper modulation to predictive load balancing, compressing the gap between equipment capability and operational optimization.
Rotary enthalpy wheels with desiccant-coated aluminum substrates are digitizing latent heat recovery performance through real-time humidity tracking and variable-speed drive modulation. Class A office developers in urban cores are specifying these systems to meet stringent ventilation effectiveness targets. The technology is digitizing how building operators manage indoor air quality energy penalties, compressing the historical trade-off between ventilation rates and thermal load.
The EU F-Gas Regulation's staged refrigerant phase-down is forcing manufacturers toward lower-GWP alternatives and air-cooled designs that bypass refrigerant circuits entirely. Industrial consequence includes accelerated R&D spend on indirect evaporative cooling and membrane-based heat exchange. Data center operators in Northern Europe are most affected, responding with pilot deployments of water-side economizer retrofits that eliminate refrigerant exposure.
Facility managers are unbundling after-sales service from equipment procurement, contracting predictive maintenance separately through building automation vendors rather than original equipment channels. This pattern disrupts traditional OEM service revenue streams and shifts specification influence toward controls integrators. The behavior is most visible in United States multi-site healthcare and retail portfolios where centralized procurement mandates standardized analytics platforms.
Economizer Market Segmentation
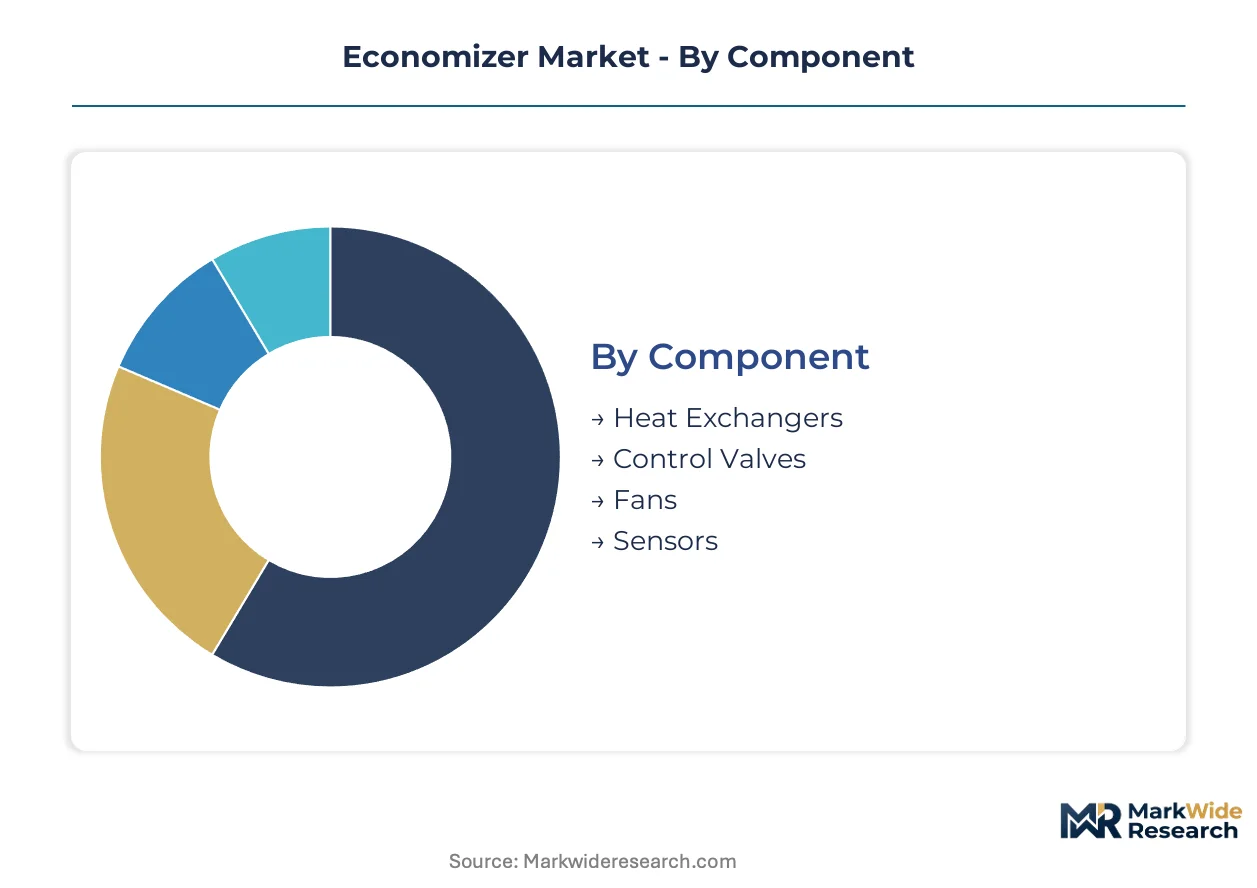
Economizer system configurations fragment sharply across thermal exchange methods and installation contexts. Specification decisions hinge on payback period sensitivity, legacy infrastructure compatibility, and regulatory compliance thresholds rather than unit economics alone.
Component:
Mature hardware categories dominate bill-of-materials composition while sensing and control layers emerge as differentiation vectors.
- Heat Exchangers:Plate-and-frame and rotary wheel architectures constitute the thermal core, with aluminum substrates and desiccant coatings extending service intervals in corrosive environments. Demand concentrates in Class A office retrofits across United States urban cores where effectiveness ratios above 70 percent justify premium specification.
- Control Valves:Pneumatic and electronic actuation systems modulate fluid flow rates to maintain design delta-T conditions. Germany's commercial building code tightening accelerates specification of intelligent valve packages with embedded position feedback.
- Fans:Variable-speed drives integrated with building automation systems optimize airflow against static pressure curves.
- Sensors:Temperature, humidity, and pressure transducers enable edge-based economizer sequencing logic.
Heat Exchangers retain volume leadership; Sensors hold the steepest expansion curve.
End User:
Application contexts range from standardized commercial installations to mission-critical industrial thermal management.
- Commercial Buildings:Office towers, retail portfolios, and healthcare facilities deploy economizers to offset chiller loads during shoulder seasons. China's provincial efficiency mandates in Tier-1 cities specify minimum heat recovery effectiveness for new construction above defined floor areas.
- Industrial Facilities:Manufacturing plants and process industries recover exhaust energy from ovens, kilns, and drying operations. United States EPA emissions thresholds for large boiler systems mandate economizer inclusion, pulling specification through engineered procurement channels.
- Power Plants:Combined cycle and cogeneration facilities integrate economizers into flue gas streams to boost thermal efficiency.
- District Heating Systems:Urban thermal networks deploy centralized heat recovery to reduce primary energy input per delivered megawatt-hour.
Commercial Buildings command the largest installed base; Industrial Facilities face the most compressed payback requirements.
Deployment:
Installation modalities reflect capital availability, IT infrastructure maturity, and portfolio scale economics.
- On-Premise:Standalone control systems with localized sensor networks and dedicated PLCs manage economizer sequencing without external connectivity. Legacy chiller integration demands predominate in single-asset facilities with limited IT support.
- Cloud-Based:Multi-site portfolio operators aggregate sensor telemetry across distributed assets through centralized analytics platforms. United States healthcare and retail chains standardize on cloud deployment to enforce uniform performance benchmarking.
- Hybrid:Edge computing architectures process time-critical damper modulation locally while uploading trend data to cloud repositories for predictive maintenance.
- Retrofits:Field adaptation of existing air handling units with economizer sections addresses energy code compliance without full system replacement.
On-Premise retains the largest installed footprint; Cloud-Based is climbing the fastest.
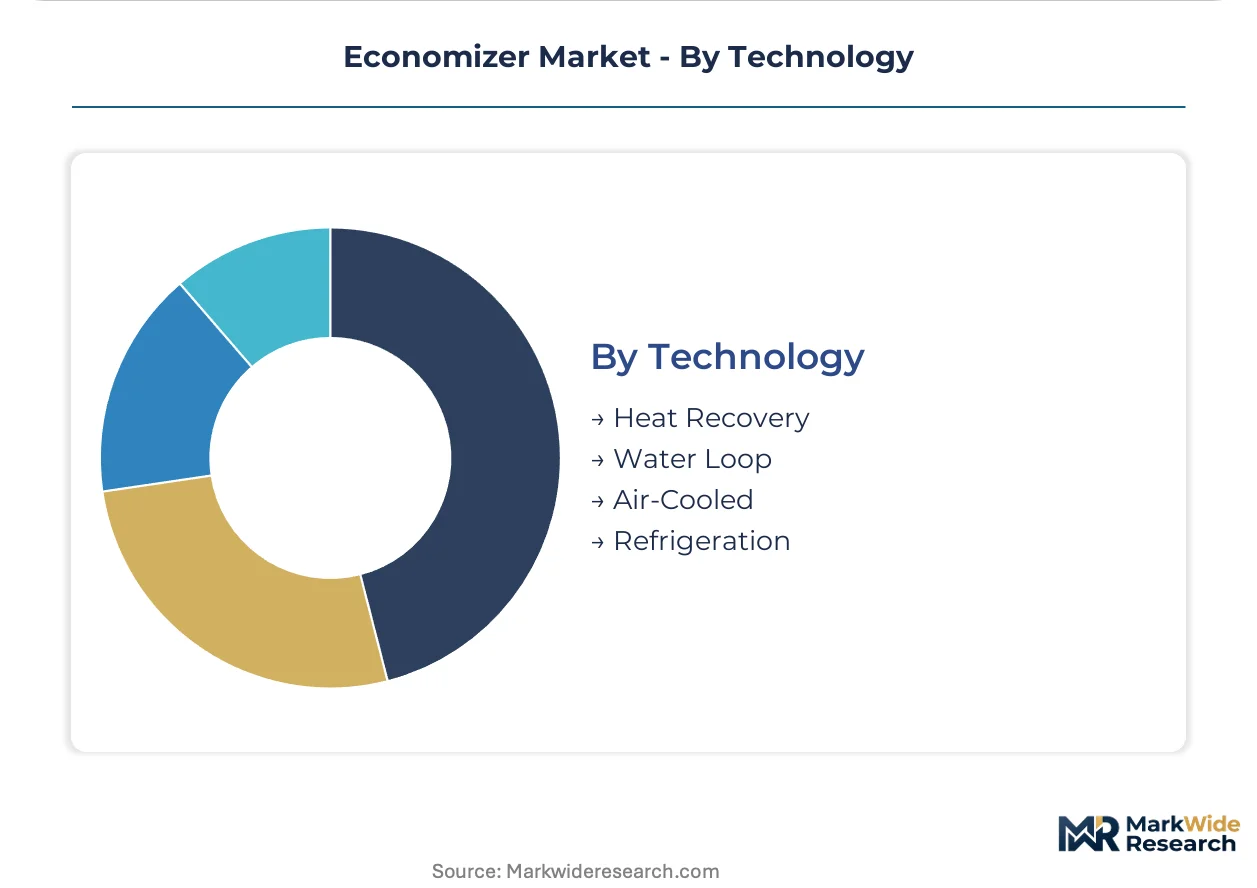
Technology:
Thermal exchange mechanisms span sensible, latent, and refrigeration-based energy recovery with divergent climate applicability.
- Heat Recovery:Plate-and-frame and rotary enthalpy wheels transfer sensible and latent heat between exhaust and intake streams, achieving 50-80 percent effectiveness in commercial HVAC applications. Direct applicability across climate zones and payback periods under five years sustain specification dominance.
- Water Loop:Hydronic circuits connect multiple air handlers to centralized heat rejection or recovery equipment, enabling thermal load sharing across building zones.
- Air-Cooled:Direct outdoor air economization bypasses mechanical cooling when ambient conditions permit, eliminating refrigerant exposure entirely.
- Refrigeration:Heat pump-based energy recovery systems face EU F-Gas Regulation phase-down pressure, forcing migration toward lower-GWP alternatives or air-cooled redesign.
Heat Recovery maintains specification dominance; Air-Cooled is gaining share fastest where refrigerant regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's energy transition hub anchors European demand for industrial heat recovery equipment. China's ultra-high voltage grid interconnects distribute thermal efficiency mandates across provincial load centers. United States LNG export terminals on the Gulf Coast drive specification upgrades in adjacent petrochemical corridors.
United States
Class A office retrofits in Manhattan and Chicago accelerate specification of plate-and-frame exchangers with effectiveness ratios above 70 percent. The EPA mandates economizer inclusion in commercial boiler systems above defined thermal capacities, pulling demand through engineered procurement channels. Data center operators in Northern Virginia pilot water-side economizer retrofits to eliminate refrigerant exposure entirely.
Germany
Commercial building code tightening in Frankfurt and Munich accelerates intelligent valve packages with embedded position feedback. The EU F-Gas Regulation's staged refrigerant phase-down forces migration toward air-cooled designs in Baden-Württemberg's industrial belt. District heating networks in Hamburg deploy centralized heat recovery to reduce primary energy input per delivered megawatt-hour.
China
Provincial efficiency mandates in Shanghai and Beijing specify minimum heat recovery effectiveness for new construction above defined floor areas. The MEE implements dual carbon goals through effectiveness minimums that drive retrofit demand in Tier-1 and Tier-2 urban cores. Yangtze River Delta manufacturing clusters adopt rotary enthalpy wheels with desiccant-coated aluminum substrates for humidity tracking.
India
The BEE's commercial building code adoption creates regulatory tailwinds for heat recovery specifications in Mumbai and Delhi-NCR new construction. Centralized procurement mandates in multi-site healthcare and retail portfolios standardize on cloud-based deployment for uniform performance benchmarking. Gujarat's pharmaceutical corridors specify economizers to offset chiller loads during shoulder seasons.
Economizer Market Vendor Landscape
On the supply side, the industry is consolidating around building automation platforms that bundle controls with thermal exchange hardware. Tiered player concentration separates integrated HVAC conglomerates from specialized heat exchanger fabricators and regional boiler-system suppliers. Three archetypes dominate: full-stack building technology providers, component-focused thermal engineering specialists, and energy-service companies with captive installation networks. M&A activity concentrates on controls software acquisitions and geographic expansion into provincial efficiency mandate zones.
Within the building technology tier, Honeywell International Inc and Johnson Controls International plc exemplify integrated platform strategies that span specification channels through vertical control of automation portfolios. Schneider Electric occupies a position emphasizing digital infrastructure for predictive maintenance monetization. Among thermal engineering specialists, Alfa Laval and Cleaver-Brooks, Inc. represent component-focused archetypes with deep fabrication expertise in plate-and-frame and boiler-integrated configurations respectively.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Alfa Laval |
| Johnson Controls International plc |
| Schneider Electric |
| Cleaver-Brooks, Inc. |
| Thermax Limited |
| Babcock & Wilcox |
| SAACKE GmbH |
| BELIMO Holding AG |
| Others |
Supply Flow & Price Mechanics
Aluminum and copper concentrate in Chinese and Indonesian smelting complexes, anchoring heat exchanger fabrication costs and compressing margin pools toward controls-integrated OEMs with captive sourcing arrangements.
Pricing Analysis
Volume-discount tiering structures separate premium effectiveness systems above 70 percent from standard 50-65 percent units and economy-grade retrofits. Price differentiation rests on certification grade—UL-listed and CE-marked packages command 15-25 percent premiums—and after-sales service bundling. Cost compression in the economy tier is intensifying because commodity input swings destabilize project bidding. Multi-site healthcare and retail portfolios exhibit lowest price sensitivity due to centralized procurement mandates, while single-asset industrial facilities face acute budget constraints.
Supply Chain Analysis
Upstream feedstock of aluminum substrates, copper tubing, and desiccant coatings draws from China, Indonesia, and Chilean mining complexes. Component dependencies center on precision-actuated valves from German and Japanese suppliers, corrosion-resistant coatings from specialty chemical producers, and sensor arrays from South Korean fabs. Single-source vulnerability concentrates in high-grade aluminum alloy supply for coastal applications. Distribution runs through OEM-direct contracting in North America and tiered distributor networks in Europe and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification influence is consolidating around building automation vendors with multi-site portfolio contracts, fragmenting traditional OEM channel control and shifting margin capture toward software-integrated providers.
For Market Incumbents: Build switching-cost moats through embedded digital twin contracts that monetize uptime guarantees. Deepen backward integration into sensor manufacturing to offset valve supply risk from German and Japanese sources. Prioritize certification investment for EU F-Gas Regulation compliance to defend specification position against air-cooled substitutes. For New Entrants and Emerging Players: Build out cloud-based deployment capabilities targeting India's BEE-mandated new construction in Mumbai and Delhi-NCR. The most penetrable segment lies in Tier-2 Chinese urban cores where provincial efficiency mandates outrun local supplier technical service capacity. A controls-first go-to-market angle—selling analytics subscriptions before hardware—sidesteps incumbent fabrication scale advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building automation software specialists holding multi-site healthcare contracts but lacking captive heat exchanger supply. Long-term viability hinges on 5-10 year regulatory enforcement durability across EPA, EU F-Gas, and China's MEE jurisdictions. The signal to watch is refrigerant phase-down acceleration in the EU forcing air-cooled redesign R&D spend above 8 percent of revenue.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Schneider Electric's predictive maintenance monetization compresses competitor service revenue streams. |
| Backward Integration into Sensor Manufacturing | Honeywell's building automation portfolio gains specification channel control through captive supply. |
| Air-Cooled Design Migration | EU F-Gas Regulation phase-down forces R&D redirection toward refrigerant-free architectures. |
| Cloud-Based Deployment Expansion | Johnson Controls captures multi-site healthcare and retail procurement standardization mandates. |
| India Market Entry Partnership | BEE commercial code adoption creates regulatory tailwind for heat recovery specification in new construction. |
Methodological Framework
The analysis maps heat recovery, air-cooled, water loop, and refrigeration-based economizer configurations, each validated through building automation engineers, HVAC procurement officers, facilities directors at Class A office portfolios, and aftermarket service heads. Primary interviews with controls integrators and heat exchanger fabricators combined with secondary validation from EPA emissions filings, EU ECHA refrigerant registration databases, China's MEE provincial mandate documents, and SEC 10-K disclosures from listed building technology providers. Bottom-up project pipeline assessment and top-down regulatory mandate sizing were triangulated against trade flow data.
Assumptions held fixed include current EPA emissions threshold enforcement levels, EU F-Gas Regulation phase-down schedules, and China's dual carbon goal provincial implementation pace; variables stress-tested included copper-aluminum commodity price bands and cloud platform adoption curves across multi-site portfolios. Segmentation dimensions modeled span technology type, deployment modality, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base turnover analysis and code-mandated replacement cycle compression. Industry-specific forecast inputs incorporated chiller load profiles by climate zone and effectiveness ratio specification trends in Class A office retrofits.
Stress conditions across commodity input volatility, refrigerant approval timeline divergence, and cloud platform cybersecurity incident frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; acceleration or delay in China's provincial mandate rollout and EU F-Gas enforcement intensity represent primary revision risks. Cross-checking against IEA building energy efficiency investment benchmarks and ASHRAE standard adoption timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Heat Pump Water Heater Market