
 Global Energy Efficient Lamps and Ballasts Market | 2026-2036
Global Energy Efficient Lamps and Ballasts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Efficient Lamps and Ballasts Market Intelligence
Commercial lighting retrofit activity is shifting toward integrated LED-ballast systems as property managers face stricter operating cost targets. Signify leverages its vertical integration across lamp and control manufacturing to capture specification-driven projects. Osram sustains technology leadership in high-efficacy LED modules for industrial environments. Acuity Brands competes through channel control in North American specification markets.
Energy efficient lamps and ballasts comprise lighting devices and power-regulating components designed to minimize electrical losses while maintaining luminous output; electronic ballasts operate at frequencies above 20 kHz to eliminate flicker and reduce copper losses compared to magnetic predecessors. LED lamps now dominate product type dynamics due to lumen-per-watt thresholds exceeding 150 lm/W and declining phosphor costs. Electronic ballasts represent the fastest-growing segment as magnetic alternatives face regulatory obsolescence across major economies. Application-level margin pools concentrate in institutional lighting where long maintenance cycles justify premium procurement.
The EU Ecodesign Directive and REACH frameworks enforce minimum efficacy standards and hazardous substance limits, effectively blocking non-compliant imports from third-country manufacturers. The US DOE appliance standards program and California Title 24 building codes mandate automatic daylight harvesting and dimming compatibility, reshaping ballast control architecture requirements. China's GB standards and dual carbon goals accelerate domestic LED conversion timelines. Stakeholders must monitor regulatory divergence between efficiency mandates and circular economy recycling obligations as compliance costs fragment competitive positioning.
Market Dynamics
Retrofit mandates across commercial building portfolios are compressing replacement cycles for legacy magnetic ballasts while electronic alternatives capture specification-driven procurement. The EU Ecodesign Directive's phase-out schedule is accelerating inventory turnover in Western European renovation corridors.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficacy standards are eliminating magnetic ballast imports from third-country manufacturers, clearing shelf space for electronic alternatives in German and French distribution channels.
- LED lumen-per-watt thresholds:Performance exceeding 150 lm/W is electrifying specification decisions in institutional lighting where maintenance cycle costs dominate total cost of ownership calculations.
- China's dual carbon goals:Domestic conversion timelines for GB standards compliance are expanding manufacturing scale and driving phosphor cost curves downward.
Market Restraints
- Rare earth phosphor volatility:Concentrated supply from Chinese processing facilities creates input cost instability for LED manufacturers dependent on yttrium and europium derivatives.
- REACH hazardous substance limits:Compliance testing timelines extend product certification cycles by four to six months for non-EU manufacturers seeking European market access.
- Magnetic ballast substitution ceiling:Remaining installed base in legacy industrial facilities in India resists conversion due to capital replacement thresholds.
Strategic Opportunities
- Underpenetrated Indian commercial retrofit:Bureau of Energy Efficiency appliance labeling programs are creating specification pull in Mumbai and Delhi NCR office complexes.
- Daylight harvesting convergence:Integration of photosensor networks with dimmable electronic ballasts is opening building automation specification channels.
- US IRA efficiency incentives:Tax credit structures for commercial building envelope improvements are bundling lighting upgrades into holistic retrofit financing.
Industry Challenges
- Legacy magnetic ballast removal protocols:PCB contamination in pre-1980s installations requires specialized handling certification that fragments contractor qualification pools.
- Cross-regional standard divergence:Incompatible dimming protocols between IEC and ANSI control architectures force manufacturers to maintain dual product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Efficient Lamps and Ballasts Market |
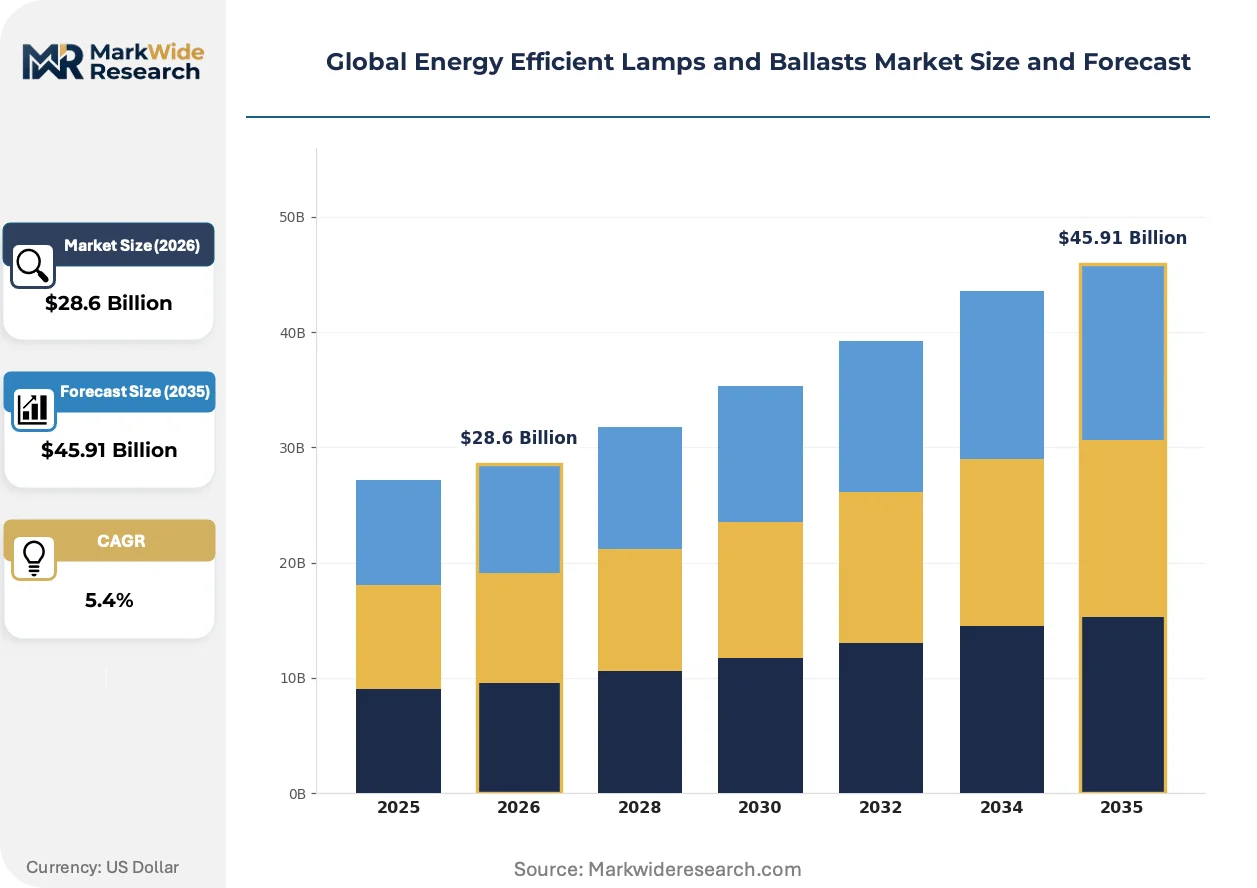
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Fluorescent Lamps, LED Lamps, Fluorescent Lamps, Electronic Ballasts, Magnetic Ballasts Application: Commercial Lighting, Industrial Lighting, Street Lighting, Institutional Lighting, Public Spaces End User: Manufacturing Units, Educational Institutions, Government Facilities, Retail Outlets, Hospitality Venues Distribution Channel: Direct Sales, Electrical Wholesalers, Online Stores, Specialty Retailers, Contractors |
| Companies Covered | Signify, Osram, GE Lighting, Panasonic Lighting, Lutron Electronics, Sylvania, Eaton, Cree, Acuity Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Efficient Lamps and Ballasts Market Strategic Shifts & Innovations
Control architecture is migrating from standalone ballast function toward networked luminaire management, with power electronics and communication protocols converging in single-package designs. This integration is compressing specification decisions around ecosystem compatibility rather than component-level performance.
Human-centric lighting systems with tunable white spectrum control are electrifying specification decisions in healthcare and education verticals. Dutch and Swedish hospital networks are adopting circadian rhythm-aligned installations. The technology is compressing traditional lumen-per-watt procurement criteria toward biological impact metrics.
California Title 24 building codes now mandate automatic daylight harvesting and dimming compatibility for all new commercial construction. The regulation is forcing ballast manufacturers to embed 0-10V or DALI control interfaces as standard rather than premium features. Multi-tenant office developments in Los Angeles and San Francisco are driving highest specification velocity.
Building owners are consolidating lighting procurement under facility management outsourcing contracts that bundle equipment, installation, and energy performance guarantees. Jones Lang LaSalle and CBRE specification teams are displacing traditional electrical distributor relationships. This concentration is most visible in London and New York Class A office portfolios.
Global Energy Efficient Lamps and Ballasts Market Segmentation
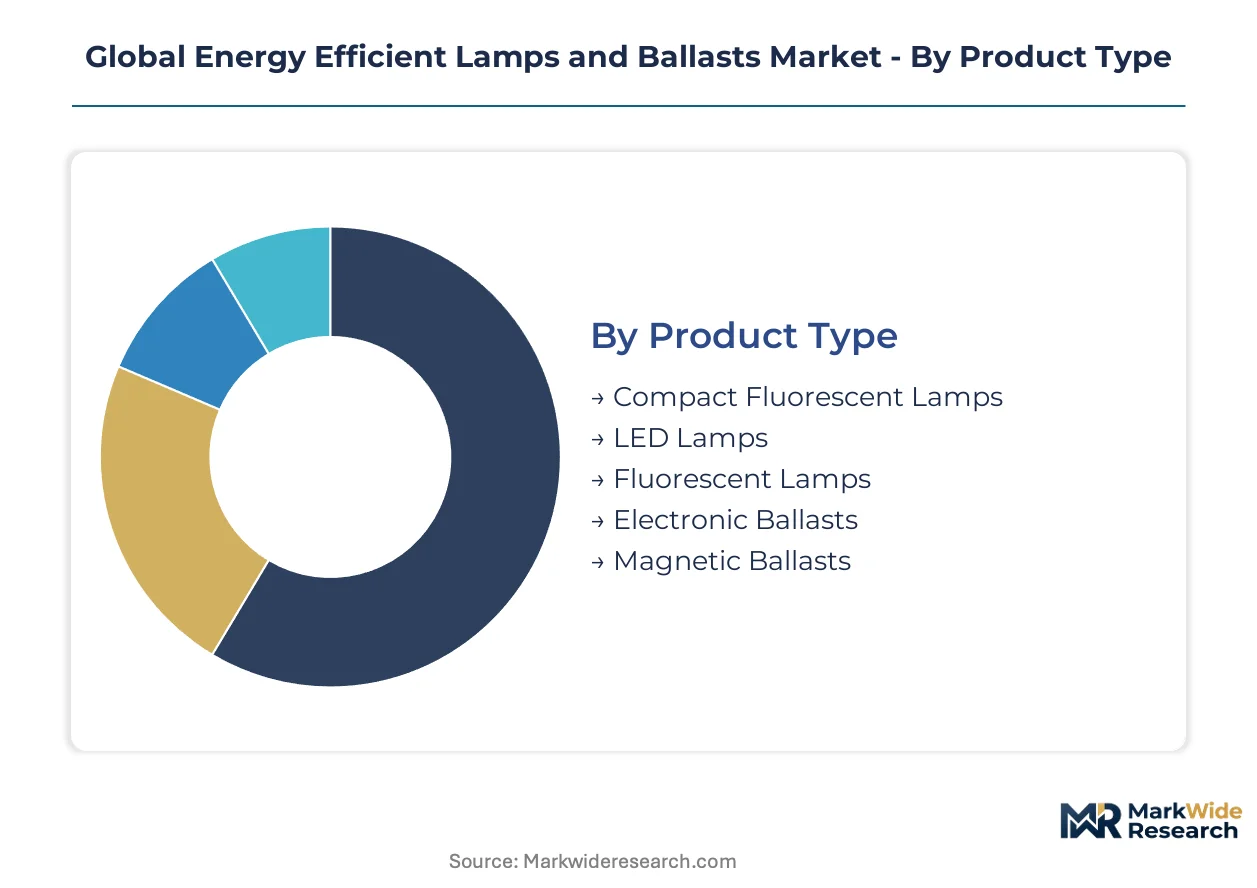
Segmentation in this market reveals how procurement authority, technical specifications, and regulatory exposure fragment demand across buyer types. Understanding these divides exposes where margin pools concentrate and where specification battles unfold.
Product Type:
Buyers differentiate primarily by efficacy thresholds and regulatory compliance timelines rather than upfront cost.
- LED Lamps:Solid-state devices utilizing semiconductor junctions to convert electricity directly to light, achieving luminous efficacy above 150 lm/W. Demand concentrates in German and French commercial retrofit corridors where EU Ecodesign Directive phase-outs accelerate replacement cycles. Phosphor cost curves from Chinese manufacturing scale are compressing price premiums versus legacy alternatives.
- Electronic Ballasts:High-frequency switching devices operating above 20 kHz to eliminate flicker and reduce copper losses compared to magnetic predecessors. Specification velocity is highest in California multi-tenant office developments where Title 24 mandates automatic daylight harvesting compatibility. REACH hazardous substance testing extends certification timelines for non-EU manufacturers seeking European market access.
- Compact Fluorescent Lamps:Mercury-vapor discharge lamps with integrated ballast systems, now facing regulatory obsolescence across major economies.
- Fluorescent Lamps:Linear tube configurations with external ballast dependency, retaining residual demand in legacy industrial installations.
- Magnetic Ballasts:Copper-wound electromagnetic transformers facing import restrictions under EU Ecodesign minimum efficacy standards.
LED Lamps lead volumes today; Electronic Ballasts is gaining share fastest.
Application:
Procurement sophistication varies sharply by maintenance cycle length and energy cost exposure.
- Commercial Lighting:Office, retail, and hospitality installations where operating cost targets dominate total cost of ownership calculations. Mumbai and Delhi NCR office complexes are driving specification pull through Bureau of Energy Efficiency appliance labeling programs. Facility management outsourcing contracts at Jones Lang LaSalle and CBRE are displacing traditional electrical distributor relationships.
- Institutional Lighting:Healthcare and education verticals with extended maintenance cycles justifying premium procurement. Dutch and Swedish hospital networks are adopting circadian rhythm-aligned tunable white systems. Human-centric lighting specifications are compressing traditional lumen-per-watt criteria toward biological impact metrics.
- Industrial Lighting:Manufacturing environments where high-efficacy LED modules reduce heat generation and maintenance frequency.
- Street Lighting:Municipal procurement with extended payback horizons and smart city integration requirements.
- Public Spaces:Transportation hubs and civic buildings with 24/7 operational profiles and security lighting mandates.
Commercial Lighting commands the largest revenue pool; Institutional Lighting shows the steepest expansion trajectory.
End User:
Budget authority and technical specification control sit in different organizational functions across these buyer types.
- Government Facilities:Public sector procurement with mandatory efficiency compliance and extended contract terms. US IRA tax credit structures for commercial building envelope improvements are bundling lighting upgrades into holistic retrofit financing. Dual carbon goals in China are accelerating domestic LED conversion timelines for state-owned properties.
- Manufacturing Units:Industrial facilities where production continuity requirements prioritize reliability over initial cost. Legacy magnetic ballast substitution ceilings persist in Indian industrial facilities due to capital replacement thresholds. PCB contamination in pre-1980s installations requires specialized handling certification that fragments contractor qualification pools.
- Educational Institutions:School and university systems with daylight harvesting integration and circadian health specifications.
- Retail Outlets:Brand-conscious environments where color rendering index and merchandising illumination quality drive specification.
- Hospitality Venues:Hotels and restaurants with dimming protocol requirements and guest experience-centered lighting design.
Government Facilities anchor procurement volumes; Manufacturing Units present the most complex retrofit conversion dynamics.
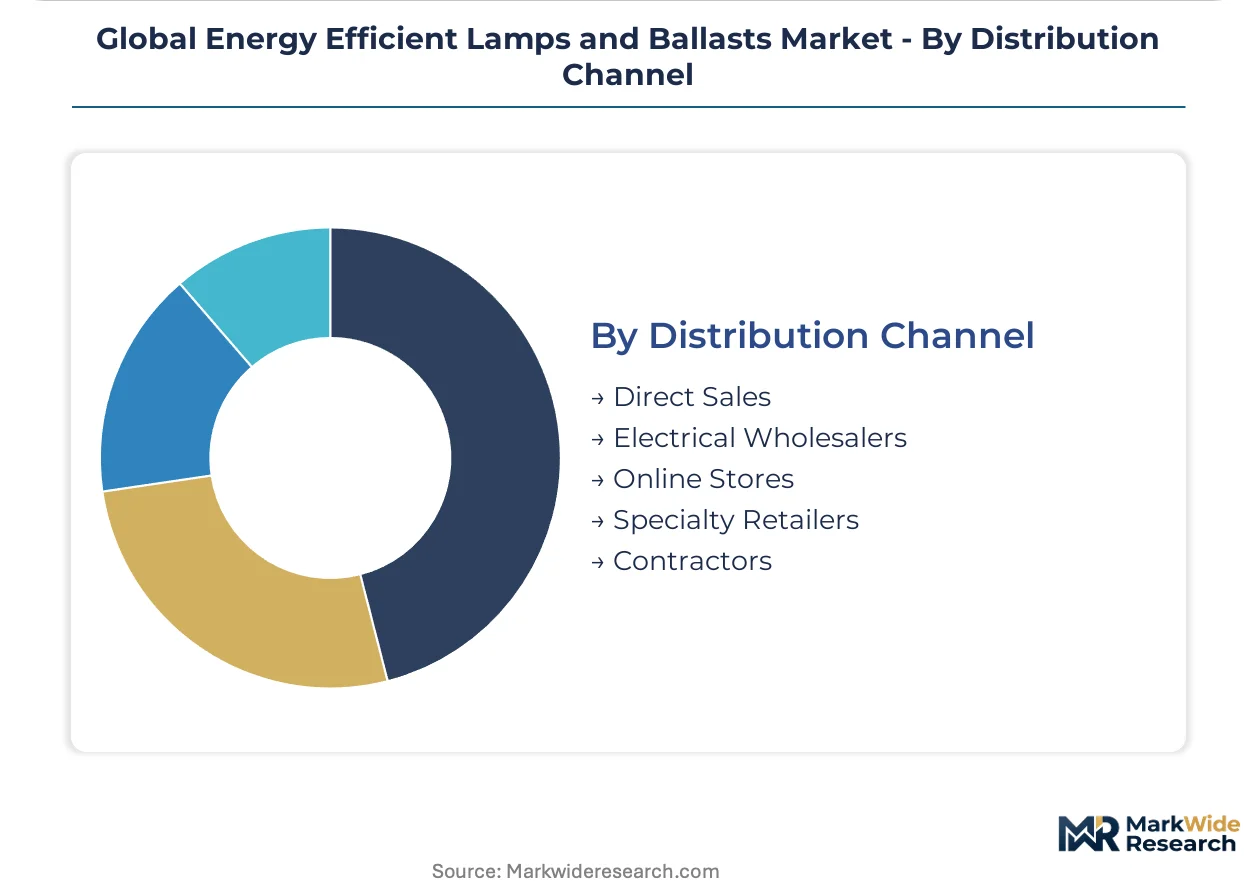
Distribution Channel:
Channel selection reflects project scale, specification complexity, and installer relationship intensity.
- Electrical Wholesalers:Traditional distribution networks with regional inventory positioning and contractor credit relationships. German and French distribution channels are clearing shelf space for electronic alternatives as EU Ecodesign Directive eliminates magnetic ballast imports. Inventory turnover acceleration is compressing working capital requirements for compliant product lines.
- Contractors:Installation-centric procurement where specification influence and project bundling create margin capture opportunities. Los Angeles and San Francisco multi-tenant office developments are driving highest specification velocity through integrated design-build contracts. Cross-regional standard divergence between IEC and ANSI dimming protocols forces contractors to maintain dual qualification pools.
- Direct Sales:Large project specifications where manufacturer technical support and warranty terms dominate procurement decisions.
- Online Stores:Replacement lamp procurement for residential and small commercial retrofit applications.
- Specialty Retailers:Premium architectural lighting showrooms with designer specification relationships.
Electrical Wholesalers maintain volume leadership; Contractors are capturing specification authority fastest in major metro corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with lower cost-of-compliance gaps, particularly as REACH testing timelines and Ecodesign certification requirements fragment competitive positioning across major economies.
Germany
Commercial retrofit corridors in Frankfurt and Munich are accelerating electronic ballast procurement as EU Ecodesign Directive phase-outs clear distribution shelf space. The country's national energy efficiency regulator enforces minimum efficacy standards that block non-compliant magnetic ballast imports. Manufacturing clusters in Bavaria are expanding LED module production capacity to serve renovation demand across Western Europe.
United States
Multi-tenant office developments in Los Angeles and San Francisco are driving specification velocity through California Title 24 mandates for automatic daylight harvesting. The US DOE appliance standards program and IRA tax credit structures are bundling lighting upgrades into holistic retrofit financing. Specification control is consolidating under facility management outsourcing contracts in New York and Chicago Class A portfolios.
China
Domestic LED conversion timelines are compressing as GB standards compliance aligns with dual carbon goals for state-owned properties. The Ministry of Ecology and Environment enforces hazardous substance limits that reshape phosphor supply chain configurations. Manufacturing scale in Guangdong and Jiangsu provinces is driving cost curves downward for rare earth derivatives.
India
Mumbai and Delhi NCR office complexes are generating specification pull through Bureau of Energy Efficiency appliance labeling programs. The Central Electricity Authority mandates efficiency compliance that fragments import qualification for legacy magnetic ballast alternatives. Industrial clusters in Gujarat and Maharashtra face capital replacement thresholds that resist retrofit conversion in legacy manufacturing facilities.
Netherlands
Hospital networks in Amsterdam and Rotterdam are adopting circadian rhythm-aligned tunable white systems that compress traditional procurement criteria. The country's national environmental regulator enforces REACH hazardous substance limits that extend certification timelines for non-EU manufacturers. Dutch specification teams at integrated facility management firms are displacing traditional electrical distributor relationships.
Global Energy Efficient Lamps and Ballasts Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-driven procurement favoring vertically integrated lamp and control producers while price-sensitive retrofit volumes flow toward OEM fabricators. The vendor base organizes around three archetypes: full-spectrum lighting conglomerates with captive component production, control-system specialists with embedded power electronics expertise, and regional assemblers serving replacement lamp demand. Consolidation pressure concentrates in the specification channel where warranty terms and technical support capabilities determine procurement decisions. Dominant competitive moves include backward integration into phosphor and semiconductor supply chains, plus geographic expansion through distribution partnerships in underpenetrated retrofit corridors.
Among vertically integrated lighting conglomerates, Signify and Osram occupy positions that exemplify specification-driven market presence, with Signify leveraging channel control across integrated LED-ballast systems and Osram anchoring technology leadership in high-efficacy modules. Acuity Brands represents the North American specification specialist archetype, competing through project-level technical engagement rather than component commoditization. These three companies collectively illustrate how competitive positioning fragments between ecosystem compatibility, lumen-per-watt performance, and regional channel density.
| Leading Market Players |
|---|
| Signify |
| Osram |
| GE Lighting |
| Panasonic Lighting |
| Lutron Electronics |
| Sylvania |
| Eaton |
| Cree |
| Acuity Brands |
| Others |
Cost & Logistics Intelligence
Ballast design engineering talent clusters in Germany's Bavarian manufacturing belt, where labor-cost differentials between specialized power electronics engineers and assembly-line technicians drive pricing-tier spreads across premium specification-grade and economy retrofit products.
Pricing Analysis
Distributor margin layers absorb 18-25 points between factory gate and contractor invoice in European electrical wholesale channels. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked high-frequency electronic ballasts from uncertified magnetic alternatives facing import restrictions. Cost compression in economy LED lamp tiers is intensifying because Chinese phosphor manufacturing scale has collapsed yttrium derivative input curves. Municipal procurement teams exhibit highest price sensitivity, while Dutch hospital facility managers prioritize circadian system performance over unit economics.
Supply Chain Analysis
REACH hazardous substance certification gates European market access, extending qualification timelines for non-EU manufacturers seeking distribution shelf space. Manufacturing concentrates in China, Germany, and the United States, with Guangdong province hosting captive LED chip fabrication and Bavaria anchoring high-frequency ballast power electronics. Rare earth phosphor supply rests on concentrated Chinese processing facilities for europium and yttrium derivatives. Single-source vulnerability in rare earth separation creates input cost instability. Distribution runs through electrical wholesalers with regional inventory positioning and contractor credit relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
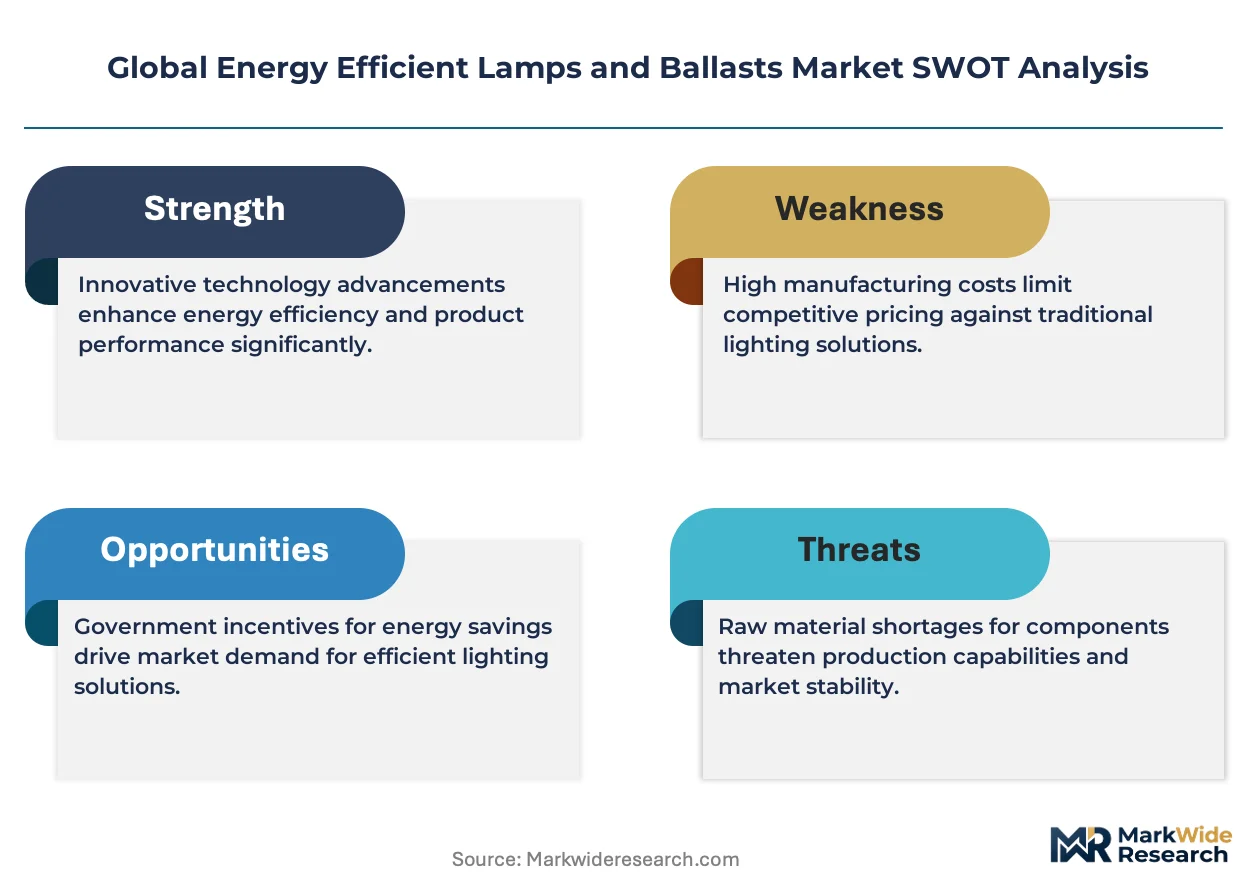
Margin expansion potential concentrates in specification-grade electronic ballast segments where phosphor cost curves and integrated control architecture justify premium positioning over commodity LED replacement lamps.
For Market Incumbents: Anticipate regulatory divergence between EU Ecodesign efficacy mandates and REACH circular economy recycling obligations that will fragment compliance cost structures. Backward integration into semiconductor and phosphor supply chains defends margin position against rare earth price volatility. Channel control through facility management outsourcing contracts at Jones Lang LaSalle and CBRE specification teams displaces traditional electrical distributor relationships. For New Entrants and Emerging Players: Launch via integrated design-build contractor channels in Los Angeles and San Francisco multi-tenant office developments where California Title 24 mandates automatic daylight harvesting compatibility. Underpenetrated Indian commercial retrofit corridors through Bureau of Energy Efficiency appliance labeling programs offer specification pull with lower incumbent density. Bundle photosensor network integration with dimmable electronic ballast offerings to capture building automation specification channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers serving replacement lamp demand without captive control-system technology. Long-term viability favors vertically integrated lighting conglomerates with in-house LED module and ballast production capabilities. The signal to monitor is consolidation velocity in specification channels where warranty terms and technical support capabilities determine procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Supply | Captive rare earth processing insulates margin from Chinese yttrium and europium price volatility. |
| Daylight Harvesting Control Integration | Embedded 0-10V or DALI interfaces capture California Title 24 mandate-driven specification demand. |
| Facility Management Partnership | Direct relationships with CBRE and Jones Lang LaSalle displace electrical wholesaler channel control. |
| Circadian System Certification | Tunable white spectrum alignment with Dutch and Swedish hospital network procurement criteria commands premium positioning. |
| Indian Distribution Expansion | Bureau of Energy Efficiency labeling program compliance opens Mumbai and Delhi NCR office complex specification channels. |
Research Approach
Coverage spans Germany, the United States, China, India, and the Netherlands, with primary inputs from each market's specification community. The research combines primary interviews with electrical contractor procurement heads, facility management specification directors, ballast design engineers, phosphor supply chain managers, and national energy regulator compliance officers with secondary validation from EU Ecodesign Directive filings, US DOE appliance standards documentation, China GB standards publications, India Bureau of Energy Efficiency labeling databases, and REACH hazardous substance registration records. Bottom-up project pipeline assessment and top-down regulatory mandate sizing were triangulated to establish market dimensions.
Granularity-level modeling disaggregated volume and value across product type, application, end user, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regulatory phase-out schedule impacts, replacement cycle compression in commercial retrofit corridors, and manufacturing scale effects on input cost curves. Industry-specific forecast inputs included EU Ecodesign Directive magnetic ballast elimination timelines and China dual carbon goal acceleration effects on state-owned property conversion rates.
Several conditions sit outside the modeled scope, including unannounced revisions to REACH hazardous substance limits, sudden rare earth export restrictions from Chinese processing facilities, and unanticipated technology substitutions from solid-state lighting alternatives. Forecasts reflect assumptions regarding regulatory enforcement consistency and phosphor cost curve trajectories. A model refresh is warranted upon material change in EU Ecodesign Directive implementation schedules or China dual carbon policy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market