

Residential Energy-Efficient Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Energy-Efficient Technologies Market Insights
Modular HVAC-plus-controls bundling is hardening as the dominant product configuration, pushing buyers toward integrated systems rather than point solutions. Daikin Industries leverages its compressor manufacturing depth to anchor premium heat pump offerings across Asian and European markets. Carrier Global competes through extensive service-network control in North America, while Schneider Electric extends its building-management software into residential-grade energy monitoring.
Residential energy-efficient technologies encompass systems and components engineered to reduce household energy consumption through improved thermal performance, power conversion efficiency, or demand-responsive operation, typically achieving 15-40% consumption reductions versus baseline equipment through enhanced insulation values, variable-speed drives, or photovoltaic conversion rates exceeding 20%. Their primary purpose centers on lowering operational energy costs while aligning dwelling performance with tightening building codes and carbon-reduction mandates. Efficient HVAC Systems and Solar Water Heaters occupy the deepest margin pools as capital-intensive categories where installation labor and after-service attach rates protect profitability. LED Lighting has matured into a replacement-driven segment with compressed margins, whereas Smart Thermostats sustain faster expansion through software-subscription layering and utility demand-response program enrollment.
The EU Green Deal and F-Gas Regulation are restructuring refrigerant-phaseout timelines and minimum efficiency thresholds, forcing manufacturers to redesign compressor architectures and accelerating heat pump deployment across member states. The EPA's SNAP program and IRA tax-credit frameworks in the United States are similarly redirecting homeowner capital toward electrified heating and envelope upgrades. Stakeholders must monitor how building-performance standards migrate from voluntary certification toward code-mandated minimums, as this shift will determine which technology portfolios retain market access and which require fundamental reinvestment.
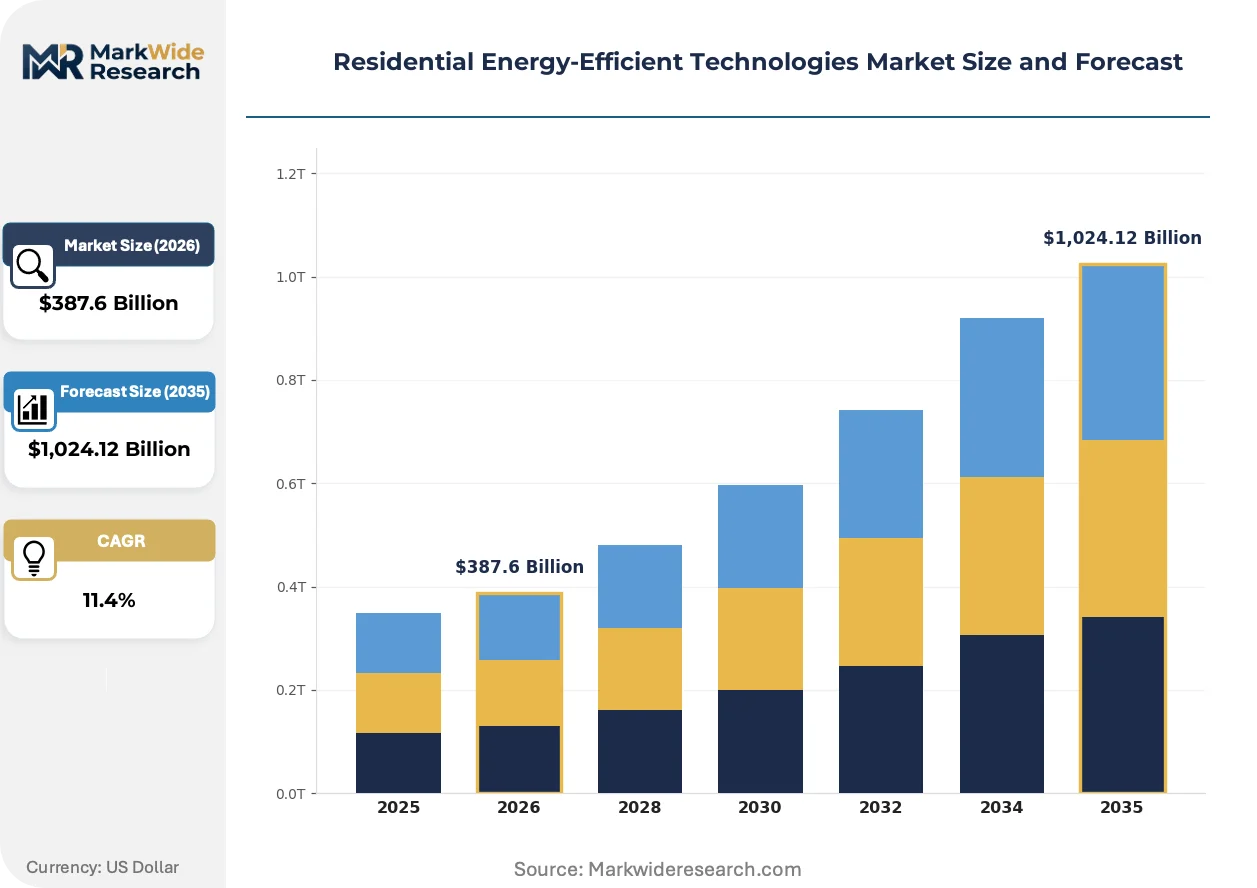
Market Dynamics
The EU F-Gas Regulation and IRA tax-credit frameworks are compressing refrigerant-phaseout timelines and redirecting homeowner capital toward electrified heating systems, forcing compressor architecture redesigns across the supply base.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory efficiency thresholds for existing housing stock across Germany, France, and Italy are accelerating heat pump deployment and envelope retrofit demand.
- Net-metering policy expansion:Single-family homeowners in deregulated US utility territories are capturing full retail rate compensation for rooftop photovoltaic exports, improving project economics.
- Heat pump technology advances:Variable-speed compressor controls and low-GWP refrigerant compatibility are extending operational temperature ranges into colder climate zones previously served by fossil fuel heating.
Market Restraints
- Copper and rare-earth magnet cost volatility:Compressor motor laminations and permanent magnet sourcing expose manufacturers to commodity price swings that compress margin buffers on fixed-price installation contracts.
- Installation labor scarcity:Qualified HVAC technician density concentrates in legacy metropolitan markets, creating bottlenecks for rural and secondary-city retrofit penetration.
- Legacy gas infrastructure lock-in:Existing residential connections to municipal distribution networks in the Netherlands and United Kingdom create switching friction against all-electric heating adoption.
Strategic Opportunities
- Smart thermostat software layering:Utility demand-response program enrollment creates recurring revenue streams beyond hardware margins, with enrollment concentrated in California and Texas deregulated markets.
- Modular HVAC-controls bundling:Integrated system configurations displace point-solution procurement, capturing fuller wallet share through single-contractor installation relationships.
- China new construction corridors:Provincial building efficiency mandates in Jiangsu and Guangdong provinces are mandating heat recovery ventilation and high-performance envelope specifications in residential towers.
Industry Challenges
- Refrigerant handling certification timelines:EPA Section 608 technician credentialing requirements and EU F-Gas personnel certification create training backlogs that delay field deployment of low-GWP equipment.
- Legacy control system integration:Proprietary communication protocols between existing building automation layers and new residential-grade energy monitoring hardware create commissioning complexity and callback risk.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Energy-Efficient Technologies Market Trends and Innovations
Residential energy-efficient technologies are pivoting from component sales toward integrated system architectures, with software-defined performance optimization and utility-interactive controls reshaping how value is captured across the hardware lifecycle.
Heat pump water heaters are decentralizing thermal energy storage by enabling load-shifting coordination with grid operators. Single-family retrofits in California and Texas are adopting these systems at accelerated pace. This technology is decentralizing peak demand management away from centralized generation assets toward distributed residential flexibility resources.
The EPA SNAP program and IRA tax-credit frameworks are redirecting homeowner capital toward electrified heating and envelope upgrades. Manufacturers must redesign compressor architectures to meet refrigerant-phaseout timelines. The US Southeast and Midwest retrofit segments are responding by accelerating heat pump water heater stocking at distributor level.
Homeowner purchasing patterns are compressing equipment replacement cycles as utility rebate windows create time-bound incentive cliffs. The traditional HVAC replacement channel through independent contractors is fragmenting toward utility-direct and big-box retail pathways. This shift is most visible in Texas and Florida markets where municipal utility efficiency programs have achieved scale.
Residential Energy-Efficient Technologies Market Segmentation
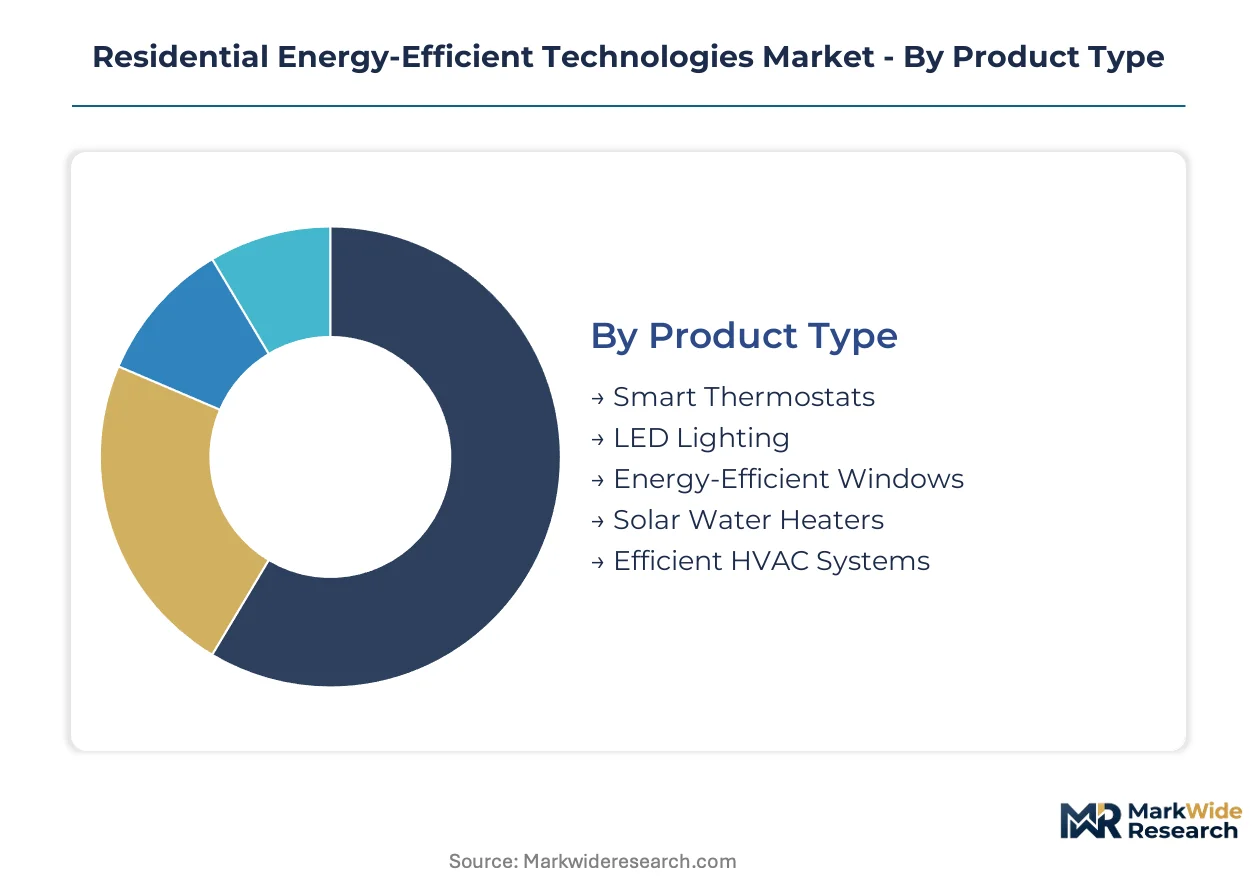
Segmentation in residential energy-efficient technologies reveals how buyer priorities diverge across retrofit urgency, new construction mandates, and utility incentive timing. Understanding these splits allows manufacturers to align product development with the specific payback expectations and installation constraints governing each purchase decision.
Product Type:
Capital intensity and installation labor requirements drive buyer selection more than incremental efficiency gains alone.
- Efficient HVAC Systems:Variable-speed compressors and heat pump architectures dominate retrofit spending in Germany, France, and Italy as EU Green Deal renovation targets compress payback periods. Cold-climate performance improvements extend addressable markets into Nordic regions previously resistant to electrified heating.
- Solar Water Heaters:Evacuated tube and flat-plate collector systems anchor thermal storage strategies in Jiangsu and Guangdong province construction mandates. Net-metering policy expansion in Texas and California deregulated utility territories improves project economics for single-family installations.
- Smart Thermostats:Utility demand-response program enrollment in California and Texas creates recurring revenue streams beyond hardware margins.
- Energy-Efficient Windows:Triple-pane low-emissivity specifications penetrate envelope retrofit channels where building code minimums are tightening.
- LED Lighting:Replacement-driven demand concentrates in commercial-to-residential conversion projects with compressed margin profiles.
Volume sits with Efficient HVAC Systems; growth tilts toward Solar Water Heaters.
Technology:
Regulatory phaseout timelines for refrigerants and materials are forcing architecture redesigns across the supply base.
- Heat Pumps:Low-GWP refrigerant compatibility and variable-speed inverter controls extend operational temperature ranges into climate zones previously served by fossil fuel systems. EPA SNAP program timelines and EU F-Gas Regulation are accelerating deployment across US Southeast and Midwest retrofit segments.
- Photovoltaic Cells:Conversion rates exceeding 20% anchor rooftop generation economics where net-metering policies offer full retail rate compensation. Module efficiency improvements concentrate demand in California and Texas single-family installations.
- Insulation Materials:Vacuum insulation panels and aerogel blankets penetrate high-performance envelope specifications in EU renovation targets.
- Programmable Controls:Utility-interactive load management integrates with grid operator demand-response signals.
- Motion Sensors:Occupancy-based lighting control reduces waste in multi-unit residential corridors and common areas.
Deployment scale favors Heat Pumps; technology advancement concentrates in Photovoltaic Cells.
Application:
End-use priority varies sharply between new construction efficiency mandates and retrofit urgency driven by equipment failure or utility rebate windows.
- Space Heating:Heat pump electrification displaces fossil fuel systems across EU member states with building renovation targets and US regions with IRA tax-credit frameworks. Cold-climate compressor advances penetrate markets previously resistant to electrification.
- Water Heating:Heat pump water heaters enable load-shifting coordination with grid operators in California and Texas distributed flexibility programs. Distributor stocking accelerates in US Southeast and Midwest corridors responding to refrigerant-phaseout timelines.
- Cooling:High-efficiency air conditioning demand concentrates in China new construction corridors with provincial efficiency mandates.
- Lighting Control:Daylight harvesting and dimming protocols integrate with utility demand-response enrollment.
- Energy Monitoring:Residential-grade building management software extends from commercial platforms into single-family installations.
Investment priority rests with Space Heating; policy support accelerates Water Heating fastest.
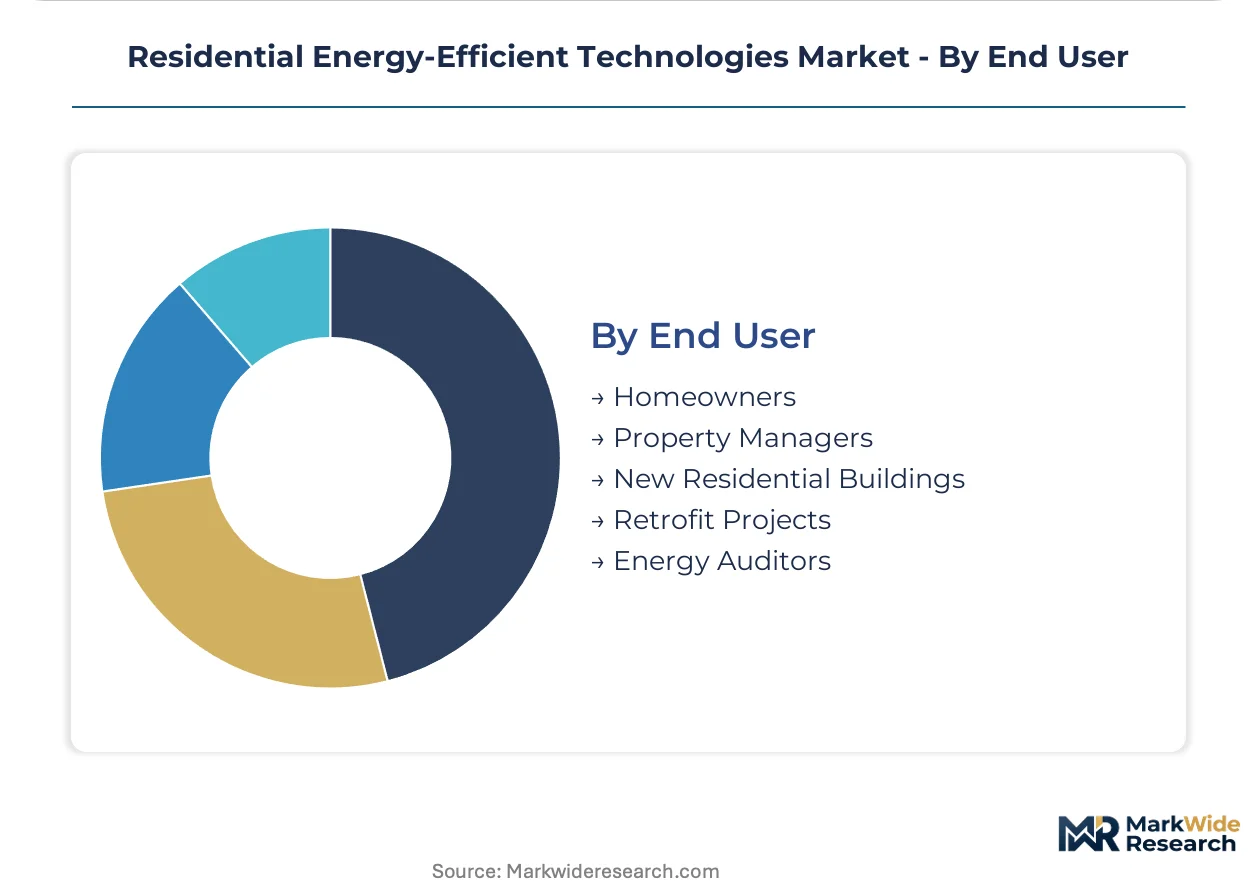
End User:
Procurement authority and financing access determine whether sales flow through contractor channels, utility-direct programs, or big-box retail.
- Homeowners:Single-family purchasers respond to time-bound utility rebate windows and net-metering policy economics in deregulated US territories. Equipment replacement cycles compress as incentive cliffs approach in Texas and Florida municipal programs.
- Retrofit Projects:Existing housing stock renovations concentrate in Germany, France, and Italy under EU Green Deal mandatory efficiency thresholds. Installation labor scarcity in rural and secondary-city markets creates penetration bottlenecks.
- New Residential Buildings:Provincial mandates in Jiangsu and Guangdong specify heat recovery ventilation and high-performance envelopes in residential towers.
- Property Managers:Multi-unit portfolio efficiency upgrades prioritize common area lighting and HVAC controls with measurable utility savings.
- Energy Auditors:Professional assessment services gate access to utility rebate programs and financing products.
Transaction volume concentrates with Homeowners; project scale expands fastest through Retrofit Projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA tax-credit zones in the US Southeast and EU Green Deal renovation corridors in Germany and Italy are concentrating capital deployment for residential energy-efficient retrofits.
United States
Single-family homeowners in Texas and Florida compress equipment replacement cycles around municipal utility rebate windows. The EPA SNAP program and IRA tax-credit frameworks redirect capital toward electrified heating and envelope upgrades. Distributor stocking accelerates for heat pump water heaters across Southeast and Midwest retrofit segments.
Germany
Building renovation targets under the EU Green Deal mandate efficiency thresholds for existing housing stock. The EU F-Gas Regulation compresses refrigerant-phaseout timelines and forces compressor architecture redesigns. Installation demand concentrates in metropolitan corridors where qualified HVAC technician density supports retrofit penetration.
China
Provincial building efficiency mandates in Jiangsu and Guangdong provinces specify heat recovery ventilation and high-performance envelopes in residential towers. The country's dual carbon goals tighten enforcement of GB standards for new construction. Technology deployment clusters in Yangtze River Delta and Pearl River Delta urban corridors.
France
EU Green Deal renovation targets accelerate heat pump deployment across single-family and multi-unit housing stock. The EU F-Gas Regulation structures low-GWP refrigerant transition timelines for heating equipment. Retrofit activity concentrates in Île-de-France and Auvergne-Rhône-Alpes where building code minimums are tightening fastest.
Italy
Mandatory efficiency thresholds for existing housing stock drive envelope retrofit demand under EU Green Deal implementation. The EU F-Gas Regulation accelerates refrigerant-phaseout compliance across the installed base. Project pipelines concentrate in northern industrial regions with denser contractor networks.
Residential Energy-Efficient Technologies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product categories, creating a tiered structure where capital depth determines geographic reach. The market fragments across HVAC equipment, controls hardware, and software-enabled monitoring layers. Three archetypes dominate: integrated system bundlers, component specialists with manufacturing depth, and building-management software extenders. Competitive moves center on modular product bundling and utility partnership channels for demand-response program enrollment.
Within the integrated system tier, Daikin Industries and Carrier Global occupy positions anchored by compressor manufacturing depth and service-network control respectively. Schneider Electric exemplifies the building-management software extension archetype, migrating commercial-grade energy monitoring into residential applications. These three represent distinct competitive vectors: manufacturing integration, installation-channel capture, and software-layer monetization.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global |
| Trane Technologies |
| Robert Bosch |
| Mitsubishi Electric |
| Panasonic Holdings |
| LG Electronics |
| Schneider Electric |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Mandatory EU F-Gas refrigerant-phaseout timelines are compressing procurement windows for low-GWP compressor architectures, forcing distributors to pre-position inventory and manufacturers to absorb retooling costs that transmit into tiered hardware pricing. This dynamic concentrates margin pressure on mid-tier equipment suppliers lacking captive compressor production.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to heat pump water heater orders where EPA Section 608 certification backlogs constrain qualified installer availability. Pricing stratifies across premium inverter-driven systems, standard fixed-speed units, and economy-tier replacement equipment based on SEER rating tiers and connected-control bundling. Cost compression in the economy tier is intensifying because Chinese manufacturers are flooding distributor channels with unsubsidized inventory ahead of provincial efficiency mandate deadlines. Single-family homeowners in Texas and Florida municipal rebate programs exhibit highest price sensitivity, while commercial property managers prioritize lifecycle operating cost over upfront capital.
Supply Chain Analysis
Dual-sourcing requirements from European HVAC OEMs now mandate qualified secondary suppliers for rare-earth magnet laminations and low-GWP refrigerant blends, extending procurement cycles. Manufacturing concentrates in China for compressor motors and heat exchanger coils, in Germany for precision control electronics, and in Mexico for final assembly serving North American retrofit demand. The supply chain draws from copper cathode markets in Chile, neodymium processing in China, and aluminum extrusion in Canada. Single-source vulnerability concentrates in semiconductor-based inverter controls sourced from Taiwan. Distribution runs through authorized dealer networks in legacy metropolitan markets, with direct-to-contractor platforms gaining share in deregulated US utility territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor manufacturing depth and installation-channel control have become the decisive vertical-integration levers as modular system bundling displaces point-solution procurement across retrofit and new construction segments.
For Market Incumbents: Anchor manufacturing integration through captive production of variable-speed inverter modules and low-GWP refrigerant-compatible compressor architectures. Defend against emerging Chinese OEMs by tightening exclusive distribution agreements with top-20 US HVAC contractors and securing EPA SNAP program pre-qualification for next-generation equipment lines. Prioritize backward integration into rare-earth magnet sourcing to buffer commodity volatility exposure. For New Entrants and Emerging Players: Enter via software-layer specialization in utility demand-response program enrollment platforms, where incumbent hardware manufacturers lack native digital capabilities. Target rural and secondary-city retrofit segments in Germany and Italy where installation labor scarcity has created penetration gaps underserved by legacy metropolitan contractor networks. Pursue white-label partnerships with regional distributors lacking in-house controls development capacity. For Investors and Strategic Acquirers: The window for entry favors mid-scale HVAC controls specialists with proven utility interoperability and recurring revenue attachment rates above hardware margins. Long-term viability hinges on regulatory compliance architecture that navigates EU F-Gas and EPA SNAP phaseout timelines without fundamental reinvestment. Monitor refrigerant-handling certification backlogs as the inflection signal—resolution velocity determines which equipment portfolios retain field deployment access.| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Architecture Redesign | Low-GWP refrigerant compatibility secures EU F-Gas and EPA SNAP program market access. |
| Utility Demand-Response Partnership | Software-subscription layering with California and Texas grid operators creates recurring revenue streams. |
| Installation Channel Consolidation | Exclusive contractor agreements in Texas and Florida municipal rebate territories capture replacement-cycle volume. |
| Rare-Earth Magnet Backward Integration | Captive neodymium sourcing buffers margin compression from commodity price volatility. |
| Smart Controls Platform Integration | Residential-grade energy monitoring extends commercial building-management software into single-family retrofits. |
Research Methodology
Multi-period observation of heat pump deployment rates, utility rebate program enrollment curves, and refrigerant-phaseout compliance timelines anchored the trend analysis, supplemented by interviews with HVAC equipment procurement directors, utility demand-response program managers, EPA regulatory affairs specialists, and independent contractor network owners. Secondary validation drew from EPA SNAP program filings, EU F-Gas Regulation implementation reports, EIA residential energy consumption surveys, and IEA building efficiency policy databases. Bottom-up equipment shipment data triangulated against top-down construction permit and retrofit financing flow analysis.
Input-output matrices mapped product-type demand across application segments and end-user archetypes, with CAGRs derived from regression analysis of historical adoption curves against policy incentive intensity and technology cost reduction trajectories. Segmentation dimensions modeled include equipment category, technology architecture, end-use application, and construction type. Forecast inputs incorporated provincial building code adoption schedules in China, IRA tax-credit renewal probability distributions, and cold-climate heat pump performance threshold improvements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU F-Gas enforcement acceleration or copper price spike scenarios. Deviation in EPA Section 608 certification throughput or qualified technician training pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.