
 Residential Air to Water Heat Pump Market | 2026-2036
Residential Air to Water Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Air to Water Heat Pump Market Outlook
Multi-family housing developers are recalibrating their mechanical specifications toward centralized air-to-water systems as gas boiler bans tighten across jurisdictions. Daikin Industries Ltd leverages its inverter compressor manufacturing scale to anchor supply contracts with large European housing associations. Mitsubishi Electric sustains technology leadership in cold-climate performance through its proprietary flash-injection cycle designs.
A residential air-to-water heat pump extracts ambient thermal energy from outdoor air and transfers it via refrigerant cycle to a hydronic distribution system, typically operating with coefficient of performance ratings between 2.5 and 5.0 depending on source temperature and emitter design. Monobloc systems dominate volume in new construction channels where outdoor-unit-only architecture eliminates refrigerant handling indoors, while split configurations retain margin premiums in retrofit applications requiring flexible indoor placement. Smart controls integration represents the fastest-expanding technology dimension as utilities and homeowners prioritize demand-response compatibility and remote diagnostics.
The EU Green Deal, Ecodesign regulations, and national building codes in Germany and France collectively mandate minimum renewable heat shares and restrict fossil-fuel installations in new residential builds. The F-Gas Regulation progressively limits high-global-warming-potential refrigerants, forcing manufacturers toward R-290 propane and R-454B blends with revised safety standards. Stakeholders must monitor refrigerant transition timelines and certify compatibility with existing hydronic emitter temperatures before committing to platform architectures.
Market Dynamics
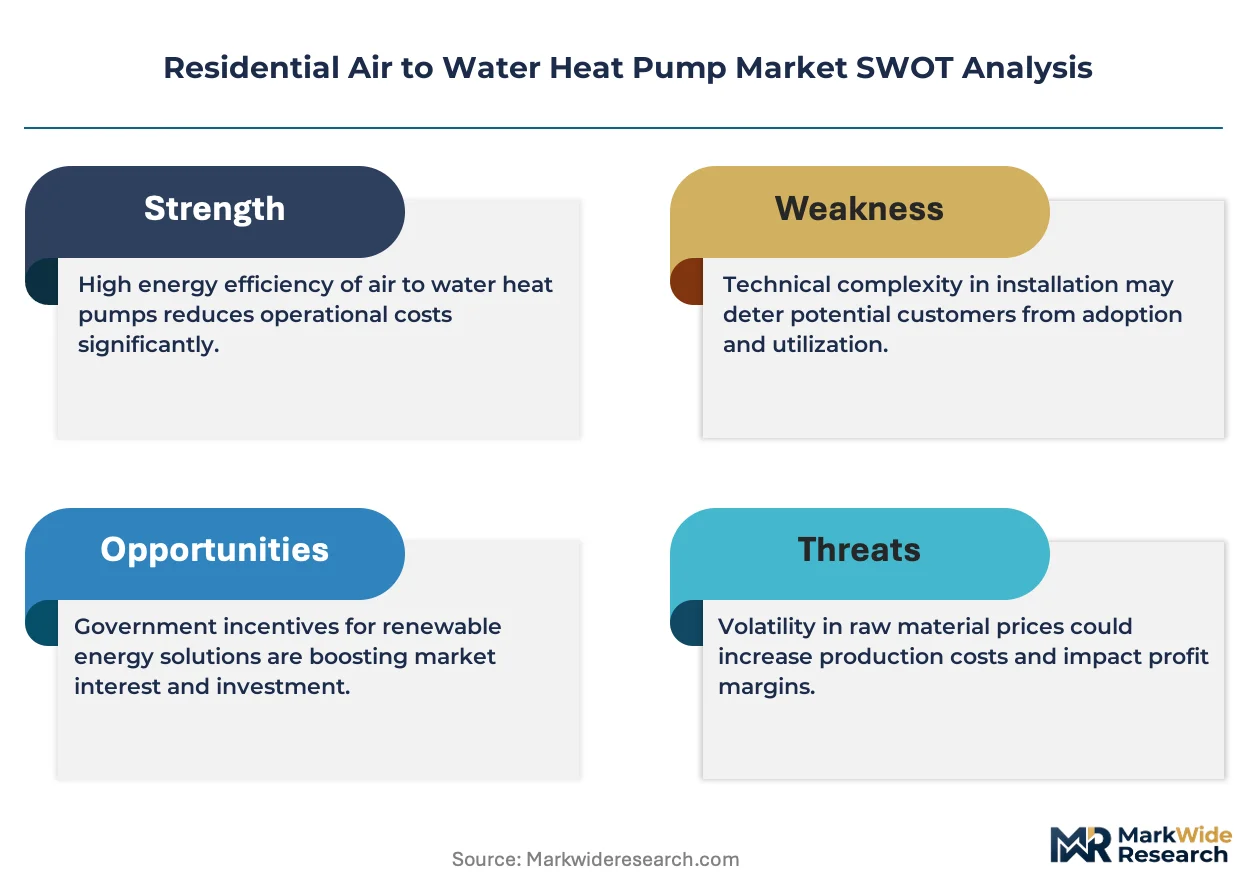
The EU Green Deal's fossil-fuel heating phaseout mandates are compressing installation timelines and forcing refrigerant platform transitions before supply chains have fully matured, creating a structural scramble for compliant cold-climate equipment.
Growth Catalysts
- Building renovation wave:Germany's federal subsidy programs covering up to 70% of heat pump installation costs are accelerating retrofits in single-family housing stock built before 1995.
- F-Gas Regulation:The progressive GWP limits on R-410A and R-134a are pulling forward demand for R-290 and R-454B-ready systems ahead of the 2027 enforcement cliff.
- Monobloc architecture:The elimination of indoor refrigerant handling is expanding installer capacity and reducing commissioning time in new construction channels.
Market Restraints
- Copper and rare-earth magnet costs:Inverter compressor manufacturing depends on neodymium supply concentrated in Chinese processing facilities, exposing margins to export restriction volatility.
- Cold-climate performance gaps:Air-source systems below -15°C ambient require supplemental electric resistance or hybrid gas backup, degrading operating economics in Nordic and Alpine zones.
- Hydronic emitter incompatibility:Legacy radiator systems designed for 70°C flow temperatures force either emitter replacement or larger-capacity heat pump oversizing.
Strategic Opportunities
- Multi-family centralization:District-scale air-to-water plants serving 50-200 units unlock economies unavailable to single-family installers, with Danish housing cooperatives piloting shared thermal storage.
- Demand-response integration:Utility-controlled thermal batteries and smart tariff optimization are creating recurring revenue streams for OEMs with cloud-connected control platforms.
- Flash-injection cycle expansion:Two-stage compression with economized vapor injection is extending effective operating range into -25°C zones without efficiency collapse.
Industry Challenges
- Refrigerant handling certification:The transition to flammable A3-class R-290 requires technician retraining and specialized charging equipment that installer networks lack at scale.
- Hydronic system integration:Mismatched flow rates between heat pump output and existing distribution loops cause short-cycling, premature compressor wear, and warranty disputes.
- Permitting fragmentation:Municipal noise ordinances, electrical service upgrades, and heritage building restrictions create unpredictable project timelines across German Länder.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Air to Water Heat Pump Market |
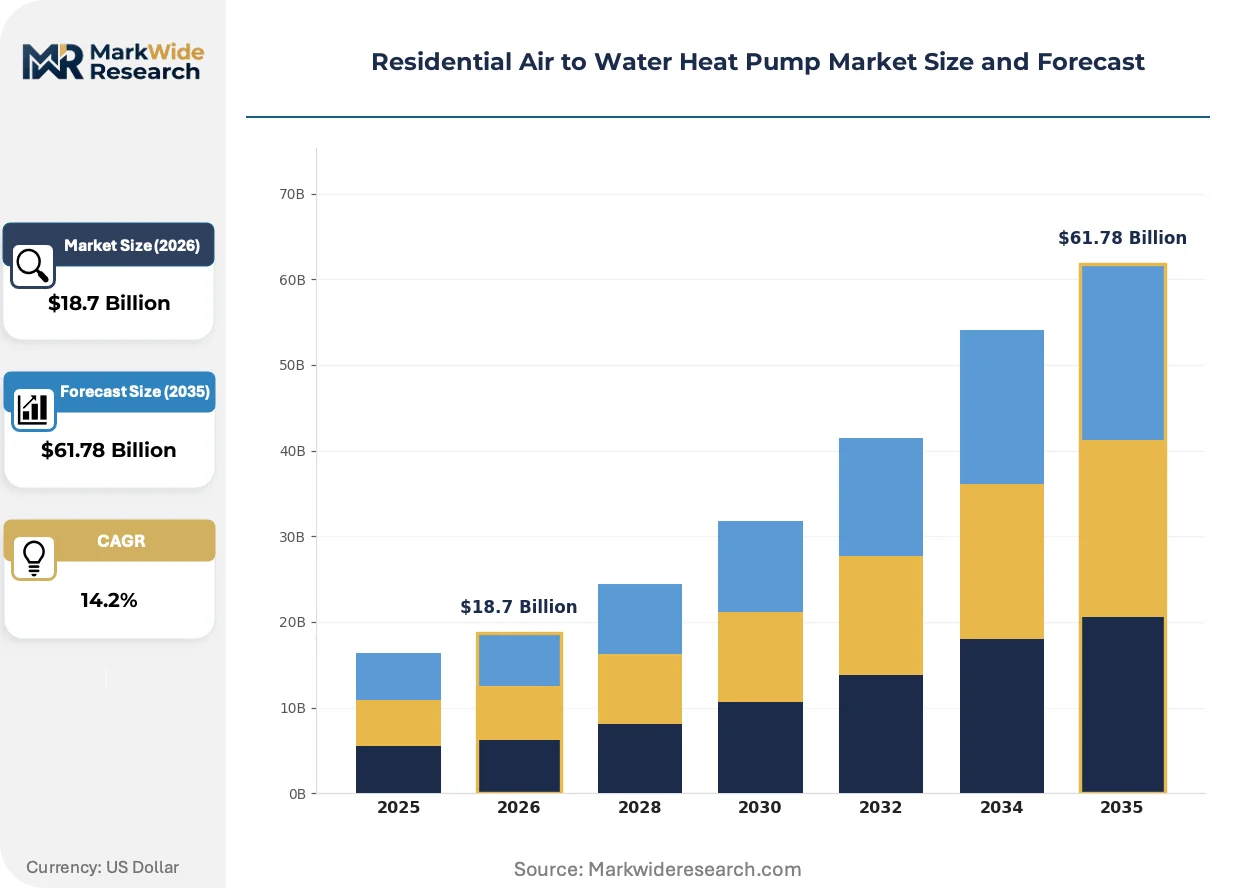
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Monobloc Systems, Plug-and-Play Systems, Integrated Systems End User: Homeowners, Builders, Renovators, Property Managers Technology: Inverter Technology, Scroll Compressors, Variable Refrigerant Flow, Smart Controls Installation: New Construction, Retrofit, Replacement, Seasonal Installation |
| Companies Covered | Daikin Industries Ltd, Mitsubishi Electric, Panasonic Corp., Vaillant Group, NIBE Industrier AB, Viessmann Climate Solutions, Bosch Thermotechnology, Carrier Global Corp., LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Air to Water Heat Pump Market Strategic Shifts
Refrigerant chemistry, control intelligence, and procurement models are converging to redefine equipment value propositions and channel economics across residential heating markets.
R-290 propane is decentralizing product architecture decisions as manufacturers redesign outdoor units with reduced charge volumes and hermetically sealed circuits. Housing associations in the Netherlands and Belgium are specifying A3-ready systems for new construction clusters despite higher upfront costs. The technology is decentralizing supply chain risk by eliminating dependence on HFC quota allocations and import licensing complexity.
The EU F-Gas Regulation's phasedown schedule is compressing R-410A equipment availability and forcing distributor inventory liquidation ahead of 2027. OEMs are dual-certifying platforms for both refrigerants to maintain shipping flexibility, while national building codes in France and Germany are preemptively banning high-GWP systems in new builds. Cold-climate performance ratings under EN 14825 are becoming the decisive specification criterion for northern European tenders.
Homeowner purchasing patterns are fragmenting across digital direct channels, eroding traditional installer-mediated sales. Aggregator platforms in Germany now quote fully installed prices with certified local technicians, capturing margin that previously sat with wholesale distributors. The shift is most pronounced in urban retrofit markets where consumers research efficiency ratings and subsidy eligibility independently before requesting installation bids.
Residential Air to Water Heat Pump Market Segmentation
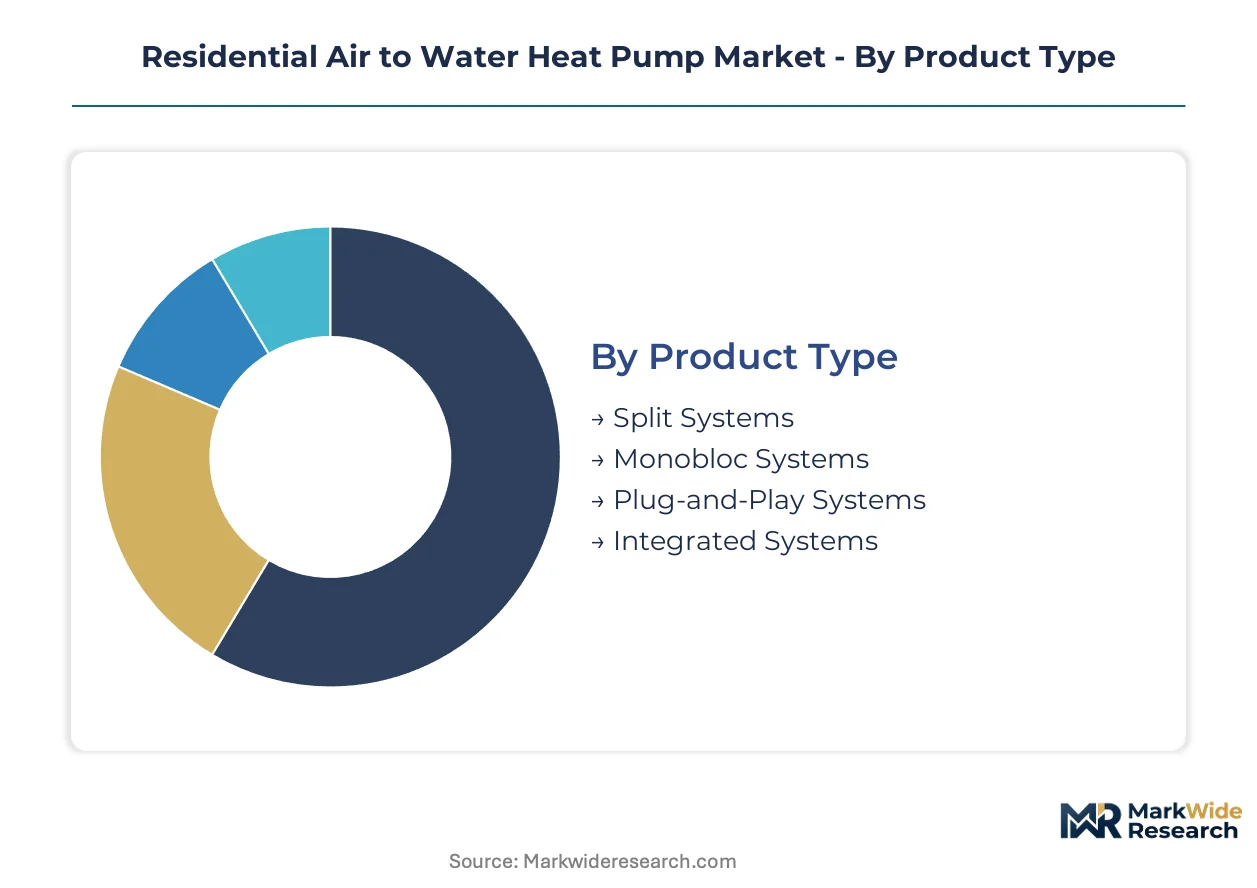
Segmentation in the residential air-to-water heat pump market determines capital allocation, refrigerant platform choices, and installer network targeting. Each dimension reveals distinct margin structures and regulatory exposure profiles.
Product Type:
Capital intensity varies sharply across system architectures, with integrated platforms requiring the highest upfront manufacturing investment while monobloc configurations minimize field installation costs.
- Monobloc Systems:Outdoor-unit-only architecture eliminates indoor refrigerant handling, reducing commissioning time and expanding installer capacity in new construction channels. German housing developers favor these for multi-unit residential clusters where standardized hydronic connections accelerate project timelines.
- Split Systems:Separate indoor and outdoor units connected by refrigerant lines offer flexible placement in retrofit applications with constrained exterior space. Demand concentrates in urban French and German markets where heritage building restrictions limit outdoor unit sizing.
- Plug-and-Play Systems:Pre-charged, factory-sealed units reduce field labor requirements for R-290 propane handling.
- Integrated Systems:Combined heat pump and thermal storage tanks demand the highest capital commitment from OEMs.
Most installed capacity flows through monobloc configurations. Expansion is steepest in plug-and-play systems as A3 refrigerant certification requirements tighten.
End User:
Customer type dictates purchasing behavior, subsidy navigation complexity, and after-service revenue potential across residential heating value chains.
- Homeowners:Individual purchasers research efficiency ratings and subsidy eligibility through digital aggregator platforms before requesting installation bids, fragmenting traditional distributor channels in German urban retrofit markets.
- Builders:Volume purchasers in new construction specify standardized monobloc platforms with extended warranty terms to minimize project risk across multiple units.
- Renovators:Retrofit specialists navigate hydronic emitter compatibility challenges and municipal permitting fragmentation across German Länder.
- Property Managers:Multi-family housing operators prioritize demand-response compatibility and cloud-connected diagnostics for portfolio-scale energy management.
Builders currently absorb the largest equipment volumes. Property managers are gaining share fastest as district-scale thermal plants proliferate in Danish and Dutch housing cooperatives.
Technology:
Technology choices determine cold-climate performance boundaries, utility integration depth, and exposure to rare-earth supply concentration risks.
- Inverter Technology:Variable-speed compressor modulation optimizes coefficient of performance across ambient temperature ranges, though neodymium magnet dependence exposes margins to Chinese export restrictions.
- Smart Controls:Cloud-connected platforms enable utility-controlled thermal batteries and tariff optimization, creating recurring revenue streams for OEMs with demand-response certification.
- Scroll Compressors:Fixed-speed alternatives dominate economy-tier pricing in mild-climate Southern European markets.
- Variable Refrigerant Flow:Multi-zone distribution capability serves high-end residential applications with heterogeneous heating loads.
Inverter platforms command the dominant installed base. Smart controls are climbing the fastest as EU electricity market reforms prioritize flexible demand response.
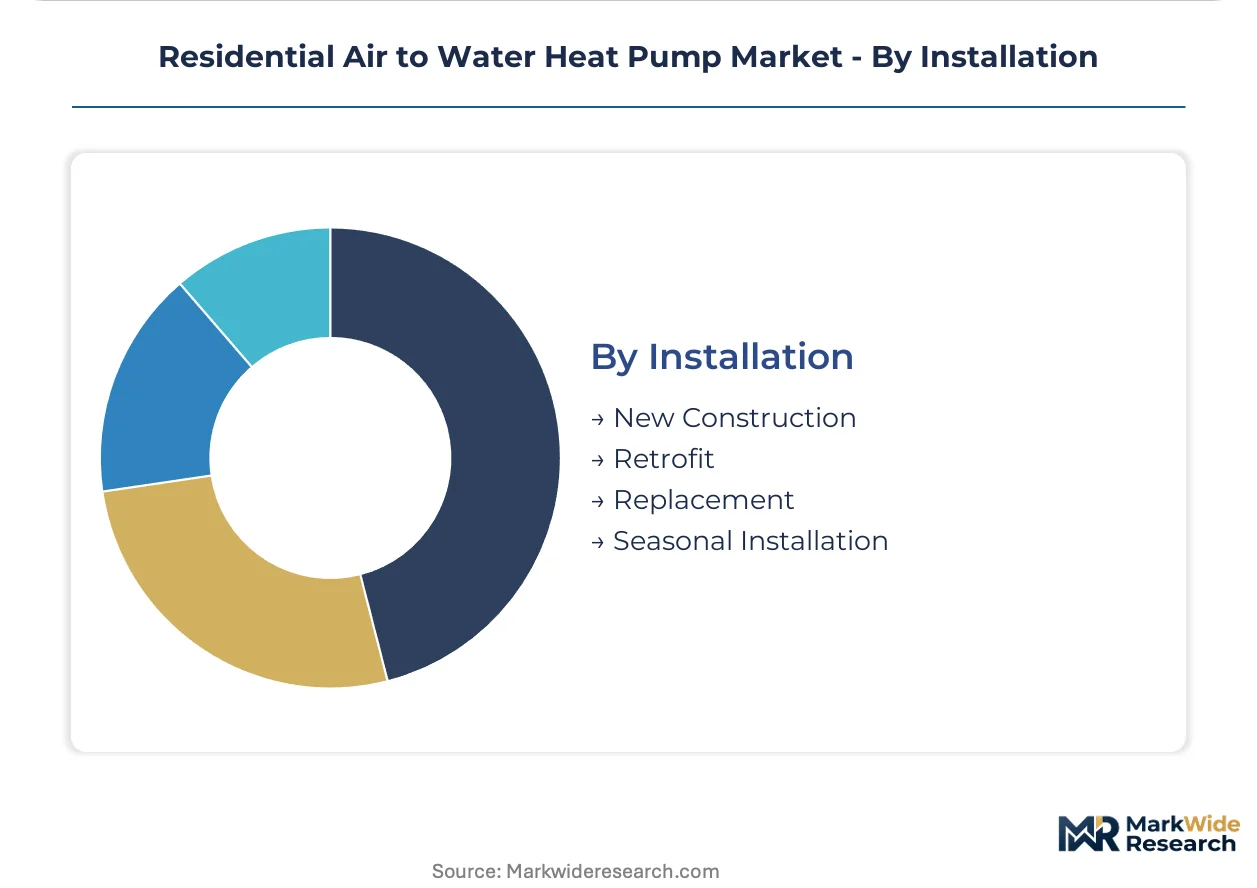
Installation:
Installation context shapes equipment specification, refrigerant handling requirements, and project timeline predictability.
- New Construction:Monobloc dominance and standardized hydronic design enable fastest deployment, with German building codes mandating renewable heat shares that exclude fossil-fuel alternatives.
- Retrofit:Legacy radiator incompatibility and electrical service upgrades create project complexity, though German federal subsidies covering up to 70% of costs accelerate single-family uptake in pre-1995 housing stock.
- Replacement:Direct boiler swaps face emitter temperature mismatches requiring either radiator replacement or heat pump oversizing.
- Seasonal Installation:Off-peak contractor scheduling offers modest cost reductions in markets with installer capacity constraints.
New construction channels process the greatest equipment volumes. Retrofit applications are expanding most quickly as F-Gas Regulation deadlines compress replacement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly capacity toward jurisdictions with aligned refrigerant standards and subsidy regimes, exploiting compliance-cost arbitrage as the EU F-Gas Regulation tightens faster than North American equivalents.
Germany
Single-family renovation subsidies covering up to 70% of installation costs are accelerating heat pump deployment in pre-1995 housing stock. The Federal Office for Economic Affairs and Export Control administers tiered BAFA grants that favor monobloc systems in multi-unit developments. Manufacturing clusters in Bavaria and Baden-Württemberg host inverter compressor assembly lines serving Central European distribution networks.
France
The RE2020 environmental regulation mandates renewable heat shares in new construction that effectively exclude fossil-fuel boilers from 2024 onward. ANAH renovation grants target low-income households in dense urban zones where split-system retrofit dominates. Industrial concentration around Lyon and Grenoble supports heat exchanger fabrication for cold-climate equipment.
Netherlands
Housing associations are specifying R-290-ready systems for new construction clusters ahead of the 2027 F-Gas enforcement cliff. The national heat transition program subsidizes district-scale thermal plants serving 50-200 unit cooperatives. Eindhoven-region engineering firms pilot shared thermal storage integration with air-to-water heat pumps.
Sweden
Stringent building codes and carbon taxation have driven air-source heat pump penetration above 40% of residential heating stock. Boverket energy performance standards require sub-55°C flow temperatures that optimize heat pump coefficient of performance. Manufacturing presence in southern industrial zones concentrates on flash-injection cycle designs for Nordic ambient conditions.
Italy
Superbonus 110% tax credits have compressed payback periods for residential heat pump retrofits, though administrative complexity delays project execution. The GSE energy services agency certifies equipment for national incentive eligibility. Northern manufacturing corridors in Lombardy and Veneto supply hydronic components to Mediterranean and Alpine markets.
Residential Air to Water Heat Pump Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs dominating new construction channels and regional fabricators capturing retrofit installation margin. The market structure concentrates around five to seven vertically integrated players with captive compressor production, while dozens of assembly-only operators serve price-sensitive Southern European markets. Three archetypes define competitive positioning: full-system manufacturers with refrigerant chemistry capabilities, controls-integrated platform developers, and regional hydronic specialists with installer-captive distribution. Capacity expansion and refrigerant platform dual-certification represent the dominant competitive moves as the 2027 F-Gas deadline approaches.
Among Japanese diversified industrials, Daikin Industries Ltd and Mitsubishi Electric exemplify the full-system archetype with inverter manufacturing scale and cold-climate cycle engineering. European specialists including NIBE Industrier AB and Vaillant Group occupy positions anchored in hydronic system integration and housing association procurement relationships. Korean and Chinese appliance conglomerates represent volume-driven challengers with cost-optimized platforms targeting subsidy-eligible mass markets.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Mitsubishi Electric |
| Panasonic Corp. |
| Vaillant Group |
| NIBE Industrier AB |
| Viessmann Climate Solutions |
| Bosch Thermotechnology |
| Carrier Global Corp. |
| LG Electronics Inc. |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet costs in inverter compressor manufacturing flow from Chinese processing facilities through OEM tiering to distributor markups, with raw material volatility compressing margins in economy-tier platforms while premium cold-climate systems retain pricing power through proprietary cycle engineering.
Pricing Analysis
Distributor margins absorb the steepest compression as German housing developers negotiate volume rebates for monobloc platforms in multi-unit clusters. Pricing stratifies across premium flash-injection systems, standard inverter configurations, and economy fixed-speed alternatives, with differentiation anchored in EN 14825 cold-climate certification tiers. Cost compression in economy tiers intensifies because Korean and Chinese appliance conglomerates compete on subsidy-eligible mass-market positioning. Renovators in single-family retrofit channels exhibit highest price sensitivity, while property managers in Danish housing cooperatives prioritize demand-response compatibility over upfront equipment cost.
Supply Chain Analysis
Specialized technician shortages in Bavarian and Baden-Württemberg manufacturing clusters constrain inverter compressor assembly expansion despite subsidy-driven demand acceleration. Component sourcing draws from Chinese rare-earth processing for neodymium magnets, Japanese precision electronics for variable-speed drives, and German steel fabrication for heat exchanger housings. Single-source vulnerability in Chinese magnet supply exposes OEM margins to export restriction volatility. Distribution runs through certified installer networks in retrofit channels and direct-to-developer contracts in new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential air-to-water heat pump market functions as a stable compounder, with regulatory mandates under the EU F-Gas Regulation and national building codes ensuring replacement demand visibility regardless of macroeconomic cyclicality.
For Market Incumbents: Deepen backward integration into refrigerant handling certification infrastructure to capture installer network loyalty as R-290 propane transitions accelerate. Fortify captive compressor manufacturing capacity in Central European clusters to defend against Korean and Chinese appliance conglomerates competing on cost-optimized platforms. The threat of flammable refrigerant technician shortages creates first-mover advantage for OEMs with pre-trained installation partnerships.
For New Entrants and Emerging Players: Begin with plug-and-play A3-ready system development targeting Dutch and Belgian housing associations specifying R-290 for new construction clusters ahead of enforcement deadlines. The most penetrable white space sits in shared thermal storage integration for district-scale plants serving 50-200 unit cooperatives. A go-to-market angle anchored in cloud-connected diagnostics and utility demand-response certification bypasses incumbent installer channel saturation.
For Investors and Strategic Acquirers: Roll-up economics work for regional hydronic specialists with installer-captive distribution because municipal permitting fragmentation across German Länder creates local scale advantages that resist national platform consolidation. Long-term viability rests on refrigerant platform dual-certification capabilities and BAFA subsidy navigation expertise. The signal to watch is F-Gas quota allocation announcements affecting R-410A equipment liquidation timelines and distributor inventory repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Dual-Certification | Maintains shipping flexibility through the 2027 F-Gas enforcement cliff for R-410A phaseout. |
| Installer Network Certification Investment | Captures R-290 propane handling capacity before technician shortages constrain market access. |
| Flash-Injection Cycle R&D Expansion | Extends effective operating range into Nordic -25°C zones without efficiency collapse. |
| Demand-Response Platform Integration | Creates recurring revenue streams through utility-controlled thermal battery optimization. |
| District-Scale Thermal Plant Development | Unlocks economies unavailable to single-family installers in Danish housing cooperatives. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with heat pump OEM product managers, BAFA subsidy program administrators, certified installation contractors, and housing association procurement directors with secondary validation through EU F-Gas Regulation filings, national building code databases, and equipment certification registries. Bottom-up unit shipment estimates triangulated against top-down subsidy disbursement records.
Segment-weighting approaches applied product architecture splits, end-user purchasing behavior patterns, technology adoption curves, and installation context variables across the analysis window. CAGRs derived from regression analysis of historical subsidy program uptake rates and regulatory mandate enforcement schedules. Cold-climate performance ratings under EN 14825 and refrigerant platform transition timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced revisions to EU Ecodesign regulations, sudden rare-earth export restrictions, and municipal noise ordinance changes. Forecasts reflect documented assumptions about subsidy program continuity and installer capacity expansion rates. Material deviation in F-Gas quota allocations or BAFA grant tier restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Waste Heat Recovery System Market