
 Energy Efficient Lighting Market | 2026-2036
Energy Efficient Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Lighting Market Intelligence
The distinction between basic LED fixtures and integrated smart lighting systems is collapsing as connectivity becomes a standard feature. Philips Lighting leverages its brand strength in connected lighting solutions for both commercial and residential sectors. Cree Lighting specializes in high-output LED components and fixtures for demanding industrial applications. Osram Sylvania competes across the technology spectrum with its broad product portfolio.
Energy efficient lighting refers to illumination products designed to produce high luminous efficacy, often exceeding 100 lumens per watt. Its primary purpose is to reduce electrical energy consumption compared to traditional sources, lowering operational costs. LED products now dominate the product type segment due to superior lifespan and efficiency. Smart lighting technologies are seeing rapid uptake, particularly within commercial buildings and public infrastructure applications where data analytics add value.
Market access and product design are influenced by multiple regulatory frameworks. The EU’s RoHS directive restricts hazardous materials, while international IEC standards define safety and performance. The US EPA’s ENERGY STAR program sets benchmarks that guide procurement. Stakeholder success now depends on navigating the convergence of energy efficiency mandates with the demand for human-centric, controllable lighting systems.
Market Dynamics
The central force shaping the market is the convergence of stringent government energy efficiency mandates with enterprise demand for intelligent buildings. This dual pressure accelerates the transition from basic LED retrofits to integrated, data-generating smart lighting networks.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and similar frameworks in North America and Asia create non-negotiable demand for high-efficiency lighting in new construction and major renovations, effectively outlawing less efficient legacy technologies.
- Commercial Cost Reduction:Large-scale operators of commercial real estate, retail, and logistics facilities are adopting advanced LED systems and controls as a primary lever to reduce significant operational electricity expenditures.
- Infrastructure Modernization:National-level investment in public infrastructure, particularly visible in China and India, drives massive volume demand for durable, efficient lighting for roadways, airports, and public transit systems.
Market Restraints
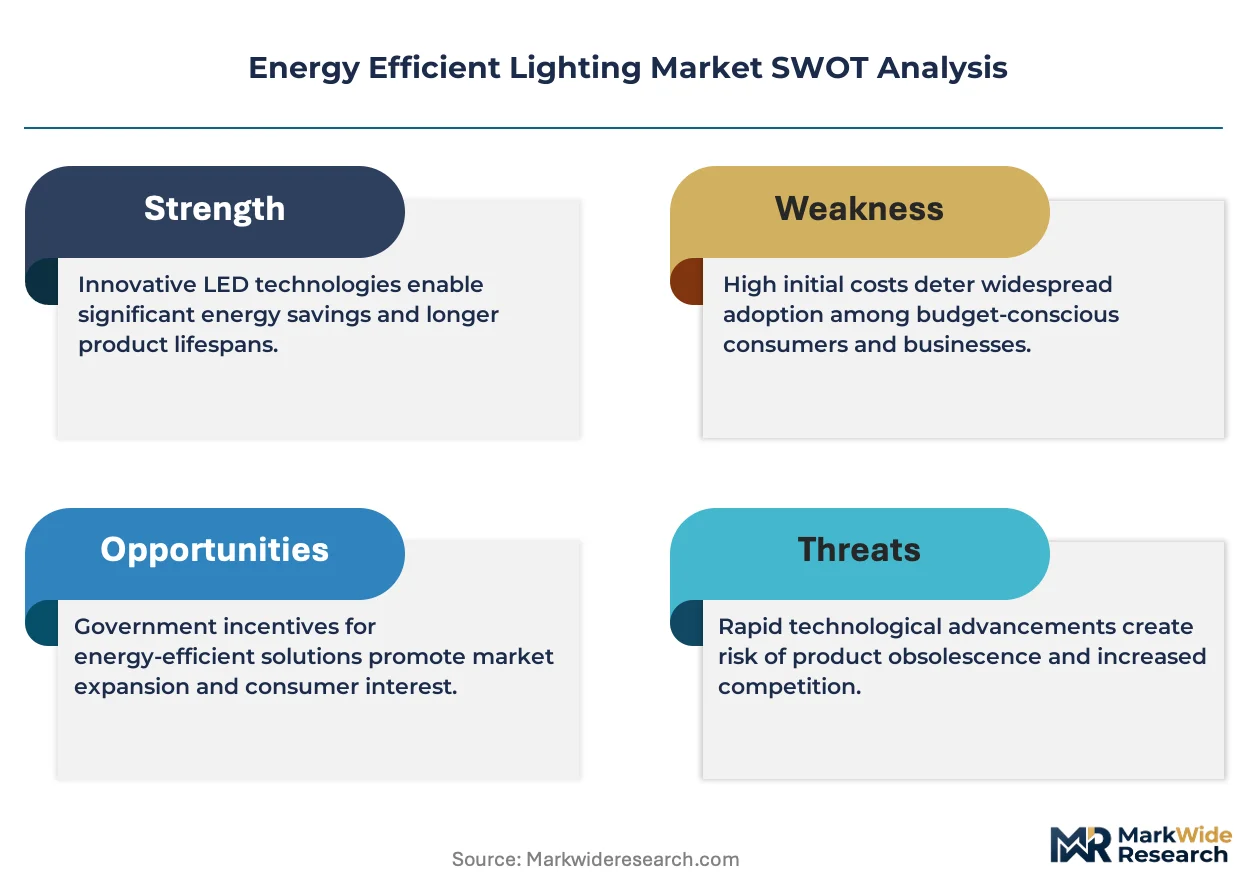
- High Initial Capital Outlay:The upfront cost of integrated smart lighting systems, including sensors and network controls, remains a significant barrier for small-to-medium-sized enterprises and budget-constrained public entities.
- Component Supply Concentration:The global supply chain for critical LED components, such as high-brightness chips and sapphire substrates, is heavily concentrated in a few countries in East Asia, posing risks of price volatility and disruption.
- Interoperability and Standardization:A lack of universal standards among competing smart lighting communication protocols creates integration complexity, increases installation costs, and risks vendor lock-in for building managers.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture and indoor farming creates a substantial new market for specialized, spectrum-tunable LED fixtures designed to optimize plant growth and yield.
- Li-Fi Integration:The convergence of illumination with data transmission through Li-Fi (Light Fidelity) presents an opportunity for secure, high-speed wireless communication in environments sensitive to radio frequency interference, like hospitals.
- Retrofit Service Models:Developing economies in regions like Southeast Asia and Latin America represent a vast, underpenetrated market for energy performance contracts that finance lighting upgrades through guaranteed future savings.
Industry Challenges
- Installer Skill Gaps:A shortage of electricians and technicians with dual expertise in both traditional electrical work and modern IT networking protocols hinders the correct deployment and commissioning of complex smart lighting systems.
- Compliance Navigation:Manufacturers face the complex and costly challenge of certifying products across a fragmented landscape of regional regulations, including the EU's RoHS directive and North America's ENERGY STAR program.
- Integration with Legacy Infrastructure:Retrofitting older buildings with smart lighting controls often requires significant, disruptive, and expensive work to overcome limitations of existing wiring and building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Lighting Market |
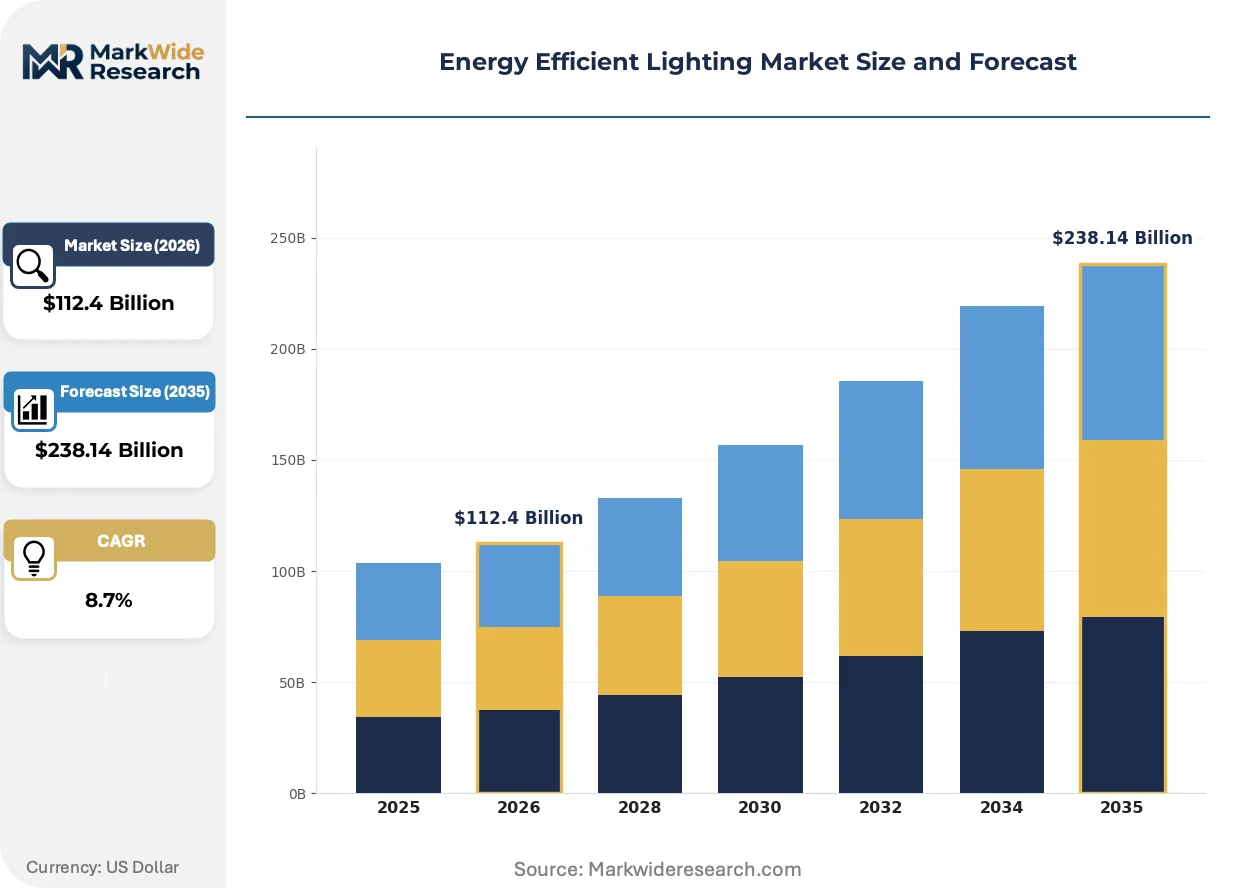
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, CFL, Halogen, Fluorescent, Induction, Organic LED Technology: Smart Lighting, Solar-powered, Motion Sensor, Dimmable, Daylight Harvesting Application: Commercial Buildings, Industrial Facilities, Public Infrastructure, Residential Properties End User: Facility Management, Government Agencies, Property Developers, Retail Chains |
| Companies Covered | Eaton Lighting, Liron Lighting, Philips Lighting, All In One Led Solar Street Light, Cooledge Lighting, Osram Sylvania, Excel Energy Group, Kastlite, Cree Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Lighting Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from pure energy savings toward human-centric benefits and data-driven operational intelligence. Illumination is now being integrated into the core of building management and occupant well-being strategies.
Tunable-white technology, which allows for dynamic adjustment of light's color temperature and intensity, is a key product innovation. Commercial offices, schools, and healthcare facilities are adopting it to create lighting that supports human circadian rhythms. This capability is bifurcating the market into basic efficiency products and premium, wellness-focused systems that deliver higher value.
Regulatory frameworks are increasingly focused on circular economy principles beyond just energy consumption. The EU's Ecodesign for Sustainable Products Regulation (ESPR) is pushing manufacturers to design for durability, repairability, and material recyclability. This affects product development lifecycles, forcing a move away from sealed, disposable fixtures toward modular and serviceable designs.
Service-based models, frequently called Lighting-as-a-Service (LaaS), are gaining favor over one-time capital equipment sales. This approach bundles the hardware, software, installation, and ongoing maintenance into a recurring subscription fee, transferring performance risk to the provider. The model is most prominent within large retail chains and industrial facilities in Europe and North America seeking predictable operational expenses.
Energy Efficient Lighting Market Segmentation
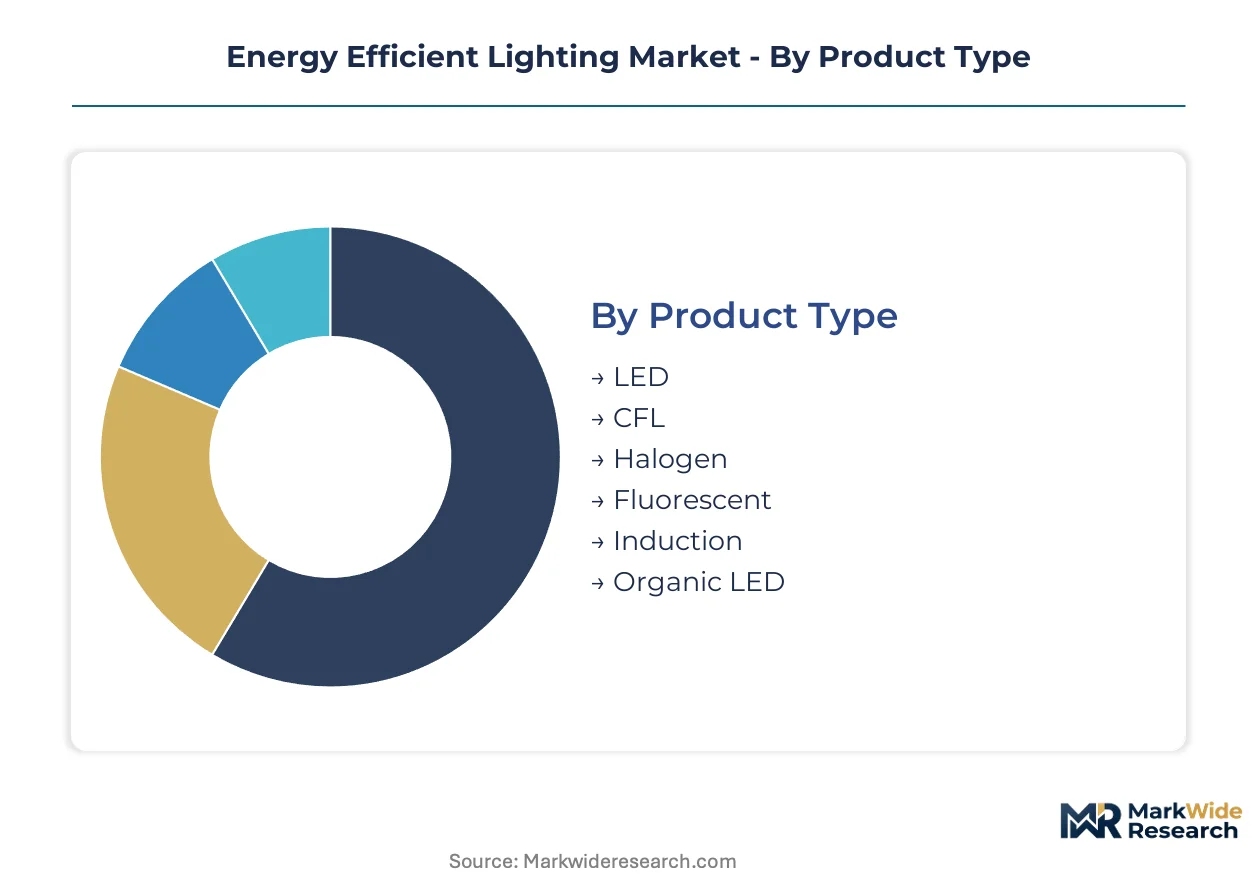
The Energy Efficient Lighting Market exhibits diverse segmentation across various product types, underlying technologies, application areas, and end-user profiles. Understanding these distinctions helps illuminate the specific demand drivers and supply chain dynamics influencing market expansion. Each segment reflects unique customer needs, regulatory compliance requirements, and technological readiness levels.
Product Type:
The distribution channels for energy efficient lighting products vary significantly based on product complexity and target customer, ranging from direct sales for specialized industrial solutions to retail channels for consumer-grade items.
- LED:Light Emitting Diodes convert electrical energy into light with high efficacy and extended lifespans. Demand concentrates in commercial buildings and public infrastructure due to superior energy savings.
- Organic LED:Organic Light Emitting Diodes use organic compounds to emit light, offering flexible, thin, and diffuse light sources. Growing demand in premium architectural lighting, driven by aesthetic appeal.
- CFL:Compact Fluorescent Lamps produce light using a fluorescent coating, offering an energy-efficient alternative to incandescent bulbs.
- Halogen:Halogen lamps are incandescent lamps using halogen gas to improve light output and lifespan.
- Fluorescent:Fluorescent lamps are low-pressure mercury-vapor gas-discharge lamps using fluorescence to produce visible light, common in commercial spaces.
- Induction:Induction lamps are electrodeless fluorescent lamps using electromagnetic induction, known for very long lifespans and high durability.
LED products dominate the installed base. Organic LED is where expansion concentrates.
Technology:
Different lighting technologies find primary adoption across distinct end-use applications, driven by specific functional requirements and desired outcomes beyond basic illumination.
- Smart Lighting:These systems integrate sensors, controls, and networks for dynamic light adjustment based on occupancy or daylight. Demand is strong in commercial real estate and smart city initiatives, driven by operational efficiency.
- Daylight Harvesting:This technology uses sensors to detect ambient natural light, automatically adjusting artificial lighting to maintain desired levels. Commercial offices adopt this for energy savings and enhanced occupant comfort.
- Solar-powered:These systems use photovoltaic panels to convert sunlight into electricity, stored for nighttime illumination in off-grid applications.
- Motion Sensor:Motion sensor technology automatically switches lights based on detected movement, deployed in low-traffic areas like corridors to conserve energy.
- Dimmable:Dimmable lighting allows users to adjust light intensity, providing flexibility for tasks and moods while contributing to energy conservation.
Specific technologies are demonstrating accelerated uptake across commercial and public sectors.
Application:
The volume demand for energy efficient lighting is heavily influenced by the scale and regulatory environment of specific application sectors, each presenting unique challenges and opportunities for adoption.
- Commercial Buildings:This segment includes offices, retail spaces, and healthcare facilities, where lighting accounts for significant electricity consumption. Adoption is driven by operational cost reduction and green building certifications.
- Public Infrastructure:This segment encompasses street lighting, tunnels, and airports, requiring robust, long-lasting, and highly efficient illumination. National energy conservation policies and urban modernization projects in China propel demand.
- Industrial Facilities:This segment includes factories and warehouses, demanding durable, high-output lighting capable of withstanding harsh operating conditions.
- Residential Properties:This segment covers homes, where demand is influenced by consumer awareness, aesthetic preferences, and energy cost savings.
The largest installed base resides within commercial properties, while public infrastructure projects offer substantial future growth.
End User:
End user segments prioritize distinct aspects of energy efficient lighting, ranging from operational cost savings and maintenance reduction to advanced data integration and occupant well-being.
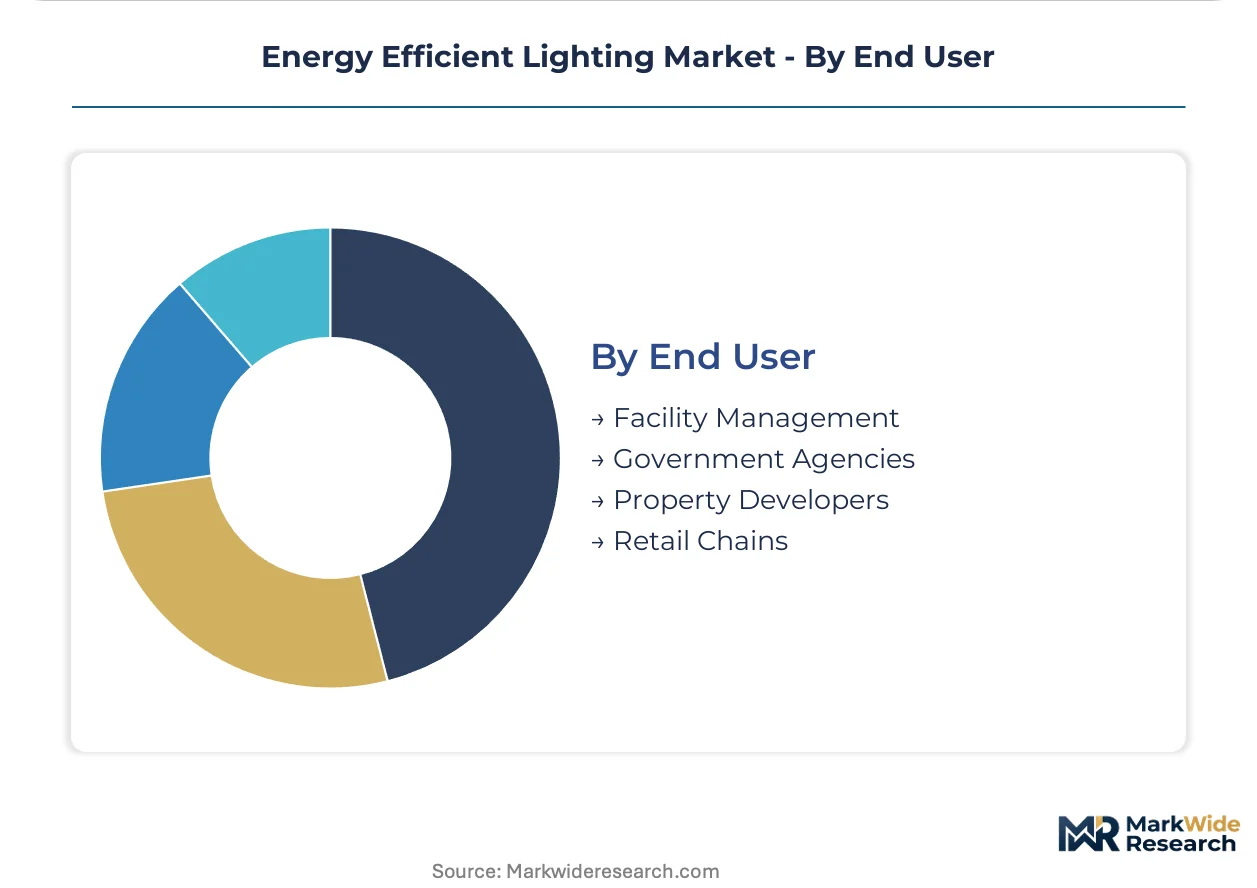
- Facility Management:These entities manage building operations and maintenance, focusing on lighting solutions offering long-term reliability, low energy use, and simplified maintenance. Procurement prioritizes total cost of ownership.
- Government Agencies:Public sector bodies procure energy efficient lighting for municipal buildings and infrastructure projects, guided by national energy conservation mandates. Large-scale tenders characterize purchasing patterns.
- Property Developers:These stakeholders integrate energy efficient lighting into new construction and renovations, enhancing building value and meeting green building standards.
- Retail Chains:Retailers adopt efficient lighting to reduce operational overhead, enhance product display, and create inviting customer environments.
Government agencies drive large-scale procurement, while facility management firms focus on long-term operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across global markets for energy efficient lighting, with some regions prioritizing upfront cost savings while others value advanced features. Commercial and public sector buyers often exhibit lower price sensitivity for integrated smart systems. Residential consumers in mature markets, however, remain highly responsive to initial purchase price.
China
Demand for efficient lighting in China is driven by massive public infrastructure development and rapid urbanization. The national dual carbon goals mandate higher efficiency standards for new construction and renovation projects. Major cities like Shanghai and Beijing are investing in smart city initiatives, integrating advanced lighting controls into urban management systems.
United States
Commercial real estate operators in the United States seek operational cost reductions through advanced LED systems. The US EPA's ENERGY STAR program sets benchmarks that influence procurement decisions across various sectors. Silicon Valley and other tech hubs are pioneering smart building solutions, integrating lighting with broader IoT platforms.
Germany
Enterprise demand for intelligent buildings and stringent energy efficiency mandates propel adoption in Germany. The EU Green Deal and national energy conservation policies create non-negotiable requirements for high-efficiency lighting. Major industrial centers like Stuttgart and Munich are implementing advanced LED lighting in factories and warehouses.
India
National-level investment in public infrastructure, including smart cities and transportation networks, drives significant volume demand in India. The Bureau of Energy Efficiency (BEE) promotes energy-efficient lighting through various programs and standards. Urban centers such as Delhi and Mumbai are modernizing street lighting with durable, efficient LED solutions.
Japan
Aesthetic appeal and long-term operational savings influence demand for premium architectural and commercial lighting in Japan. METI regulations encourage energy conservation through subsidies and efficiency targets for businesses. Tokyo and Osaka are integrating advanced lighting solutions into smart office buildings and retail spaces.
Energy Efficient Lighting Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the energy efficient lighting market. The market exhibits a tiered structure, with established conglomerates competing alongside specialized technology providers and emerging smart solution developers. Strategic archetypes include diversified lighting giants, niche component manufacturers focusing on specific applications, and integrated smart system developers. Portfolio diversification and strategic partnerships are dominant competitive moves, alongside targeted capacity expansion in high-growth segments.
On the premium solutions vector, Philips Lighting occupies a position as a globally recognized brand in connected lighting systems, particularly for commercial and residential sectors. Cree Lighting, an Inc.-structured entity, exemplifies expertise in high-output LED components and fixtures for demanding industrial applications, often requiring robust performance. Osram Sylvania, with its broad product portfolio, represents a diversified player competing across various technology segments and end-user markets, from basic efficiency products to more advanced systems.
| Leading Market Players |
|---|
| Eaton Lighting |
| Liron Lighting |
| Philips Lighting |
| All In One Led Solar Street Light |
| Cooledge Lighting |
| Osram Sylvania |
| Excel Energy Group |
| Kastlite |
| Cree Lighting |
| Others |
Cost & Logistics Intelligence
The substitution of traditional illumination sources with advanced LED technology simultaneously reshapes global supply geography and pricing economics, driving demand for specialized components. This shift centralizes manufacturing in East Asia while fostering new value propositions in integrated solutions.
Pricing Analysis
After-sales service and software subscriptions increasingly drive lifetime value for advanced lighting systems, moving beyond initial hardware sales. The dominant pricing structure for smart lighting is project-based, often incorporating a subscription for ongoing data services. Price differentiation stems from brand premium, particularly for established players like Philips Lighting, and the certification level for energy efficiency programs such as ENERGY STAR. Pricing pressure stems from component commoditization in the basic LED segment, especially from Chinese manufacturers. Residential consumers exhibit the highest price sensitivity, while commercial and public sector buyers prioritize total cost of ownership and advanced features.
Supply Chain Analysis
A just-in-time inventory strategy dominates for standard LED components, but strategic stockpiling occurs for critical high-brightness chips. Geographic supply concentration for essential LED components, including sapphire substrates and specialized chips, centers heavily in China, Taiwan, and South Korea. Raw material dependencies include rare earth elements for phosphors and gallium nitride for epitaxy. Component supply concentration presents a structural risk of price volatility and disruption due to geopolitical factors or natural disasters. Downstream distribution runs through direct sales channels for large commercial and public projects, and through electrical wholesalers and retail outlets for smaller commercial and residential applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy efficient lighting market presents a fragmentation opportunity, driven by the demand-side shift towards human-centric lighting and data-driven building management systems.
For Market Incumbents:
Consolidate market share by acquiring specialized software and sensor companies, integrating their capabilities into existing product portfolios. This move mitigates the threat from emerging smart solution developers. Invest in advanced manufacturing for modular and repairable designs to comply with circular economy regulations like the EU's Ecodesign for Sustainable Products Regulation. Control key intellectual property for tunable-white technology and Li-Fi integration to maintain a premium position.
For New Entrants and Emerging Players:
A certification fast-track through regional energy efficiency programs, such as the US EPA's ENERGY STAR, offers a viable entry point. Target underpenetrated developing economies in Southeast Asia and Latin America with energy performance contracts for retrofit service models. Focus on niche applications like horticultural lighting, which requires specialized spectrum-tunable LED fixtures. A direct-to-customer sales model for specialized solutions can bypass established distribution channels.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors integrated smart lighting system developers with strong software and data analytics capabilities. Long-term viability hinges on companies that can bundle hardware, software, and services into Lighting-as-a-Service (LaaS) models. Target acquisition archetypes include firms specializing in IoT platforms for smart buildings or those with proprietary Li-Fi technology. The signal to watch is the increasing adoption rate of LaaS contracts in commercial real estate.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Smart Lighting Software Firms | Integrates data analytics and control capabilities, enhancing product ecosystems for commercial buildings. |
| Invest in Circular Economy Design | Ensures compliance with EU Ecodesign regulations, extending product lifecycles and reducing material waste. |
| Expand Lighting-as-a-Service (LaaS) Models | Captures recurring revenue streams and addresses customer demand for predictable operational expenses. |
| Develop Specialized Horticultural Solutions | Addresses the growing demand for optimized lighting in controlled environment agriculture. |
| Form Partnerships for Li-Fi Integration | Positions companies at the forefront of secure, high-speed wireless communication in sensitive environments. |
Research Approach
The analysis maps energy efficient lighting sub-sectors, including product types, technologies, and applications, each validated through primary interviews with facility management executives, government procurement officers, and property developers. Secondary validation involved reviewing regulatory filings, industry association reports, and trade publications. This approach utilized both bottom-up market sizing and top-down market share analysis.
Outputs were consistently checked against external benchmarks over the projection horizon. The analytical framework modeled segmentation dimensions including product type, underlying technology, application area, and end-user profile. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future demand. Key forecast inputs included national energy conservation policies and commercial building construction rates.
Underlying assumptions cover stable regulatory environments and consistent technological advancements, with deviation risk concentrated in component supply chain disruptions. Revision becomes warranted when major policy shifts or unforeseen technological breakthroughs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Waste Heat Recovery System Market