
 Spain Artificial Organs and Bionic Implants Market | 2026-2036
Spain Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Artificial Organs and Bionic Implants Market Analytics
Spain's national sustainability procurement criteria for medical devices is consolidating purchasing power toward suppliers with certified biocompatible material supply chains. Medtronic plc leverages its integrated cardiac implant portfolio to sustain long-term contracts with Spanish public health systems. Edwards Lifesciences Corp. anchors its competitive position through specialized transcatheter heart valve technologies adapted to European regulatory pathways. Otto Bock Holding GmbH & Co. KG differentiates in limb prosthetics through advanced sensory feedback systems designed for rehabilitation center workflows.
Artificial organs and bionic implants comprise electromechanical and biological substitute systems engineered from titanium alloys, medical-grade polymers, and living tissue matrices to restore or enhance physiological functions lost to disease, trauma, or congenital conditions. These devices integrate microelectromechanical systems for real-time physiological monitoring and closed-loop therapeutic response, serving primary purposes in chronic disease management, post-surgical recovery, and mobility restoration. Cardiac implants command the largest revenue share due to established reimbursement for heart valve and ventricular assist procedures, while neural implants represent the fastest-expanding category driven by deep brain stimulation applications for Parkinson's and epilepsy treatment in Spanish neurology centers. Limb prosthetics sustain steady demand through Ossur hf. and Ottobock SE and Co. KGaA's dominance in socket technologies and myoelectric control systems, with margin pools concentrating in custom-fitted upper-extremity devices.
Spain's Ministry of Health coordinates with the Spanish Agency for Medicines and Health Products and ISO 13485 quality management standards to enforce pre-market clinical evaluation and post-market surveillance of active implantable devices. EMA centralized procedures and the EU Medical Device Regulation shape product certification timelines and clinical evidence requirements for manufacturers seeking market access across Iberian healthcare networks. Stakeholders must monitor evolving reimbursement thresholds for high-cost bionic implants under Spain's regional health service budgets and anticipate how EU-wide health technology assessment harmonization will reshape competitive positioning for next-generation sensory feedback technologies.
Market Dynamics
Spain's regional health service procurement consolidation under Ministry of Health sustainability criteria is concentrating purchasing power toward suppliers with certified biocompatible material supply chains and closed-loop manufacturing capabilities.
Growth Catalysts
- EU Medical Device Regulation harmonization:EMA centralized procedures streamline pre-market clinical evaluation timelines for active implantable devices, accelerating Spanish hospital access to next-generation cardiac and neural technologies.
- Deep brain stimulation adoption:Spanish neurology centers in Madrid and Barcelona are expanding Parkinson's and epilepsy treatment protocols, pulling demand for advanced neural prosthetics into specialized clinical workflows.
- Titanium alloy supply chain localization:Iberian raw material processing investments reduce import dependency for cardiac implant manufacturers serving Spain's public procurement frameworks.
Market Restraints
- High-cost device reimbursement thresholds:Spain's regional health service budgets impose strict cost-effectiveness criteria for bionic sensory feedback systems, limiting patient access outside specialized transplant centers.
- Biocompatible polymer input volatility:Medical-grade silicone and polyurethane supply concentration in German and Swiss chemical producers exposes Spanish manufacturers to price instability and allocation constraints.
- Post-market surveillance compliance burden:ISO 13485 quality management standards and Spanish Agency for Medicines and Health Products vigilance requirements extend product lifecycle documentation costs for implantable device suppliers.
Strategic Opportunities
- Andalusia and Valencia regional expansion:Underpenetrated rehabilitation hospital networks in southern and eastern Spain present whitespace for limb prosthetic and myoelectric control system deployment.
- Transcatheter heart valve ambulatory migration:Minimally invasive cardiac implant procedures are shifting from inpatient to day-hospital settings, creating channel restructuring opportunities for catheter-based delivery technologies.
- EU Green Deal sustainable procurement incentives:Spain's national sustainability criteria for medical devices reward suppliers with circular material flows and carbon-reduced manufacturing, favoring early adopters in public tender processes.
Industry Challenges
- Bioelectronics systems integration complexity:Microelectromechanical systems engineering for real-time physiological monitoring requires cross-functional expertise spanning materials science, signal processing, and clinical validation that Spanish medical device firms struggle to source domestically.
- MDR certification timeline compression:Notified body capacity constraints under EU Medical Device Regulation extend active implantable device approval cycles, delaying revenue recognition for manufacturers targeting Spanish hospital procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Artificial Organs and Bionic Implants Market |
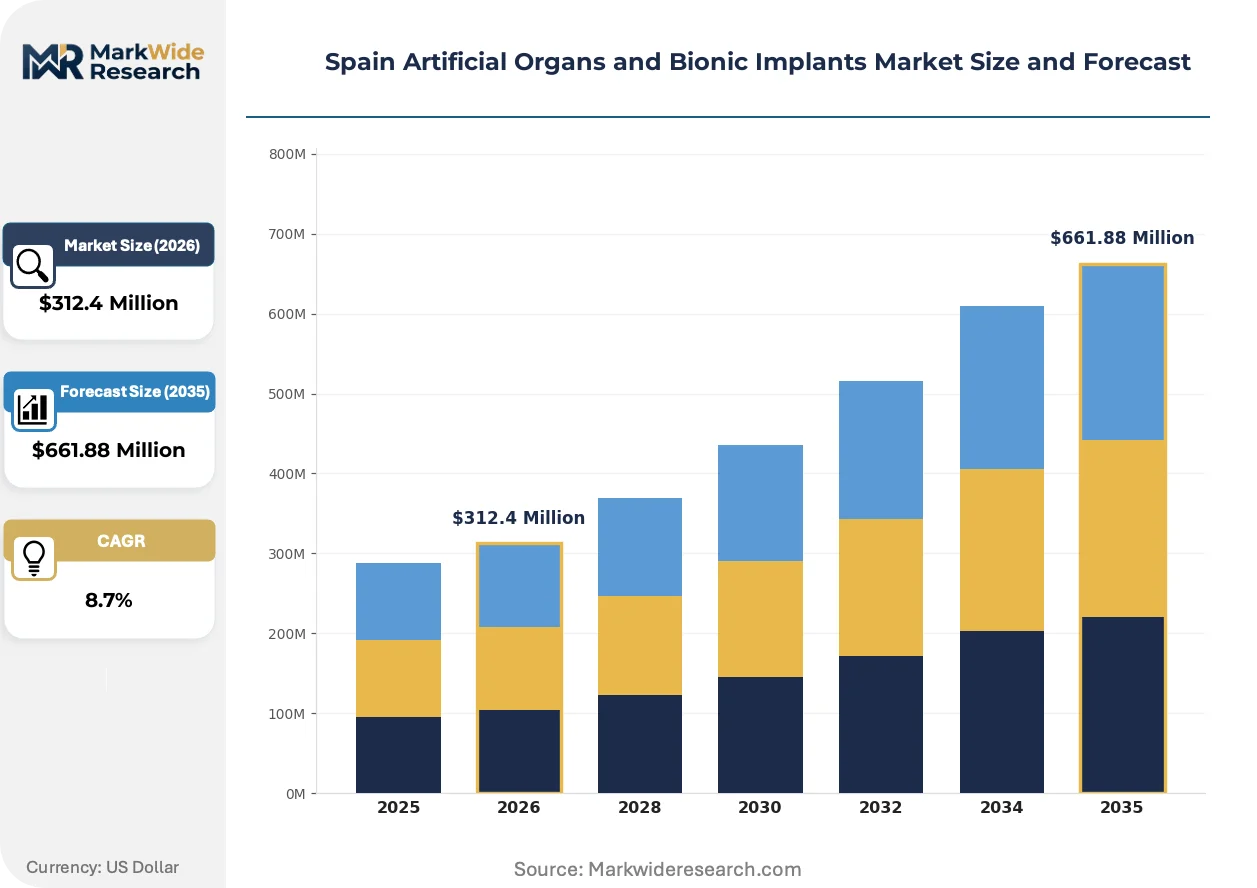
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Neural Implants, Respiratory Devices, Limb Prosthetics Technology: Biocompatible Materials, Sensory Feedback, Power Management, Microelectromechanical Systems Application: Chronic Diseases Treatment, Surgical Procedures, Rehabilitation, Cosmetic Enhancements End User: Hospitals, Rehabilitation Centers, Homecare Settings, Research Institutions |
| Companies Covered | Sonova Holding AG, Abiomed Inc., Medtronic plc, Ossur hf., Edwards Lifesciences Corp., Zimmer Biomet, Otto Bock Holding GmbH & Co. KG, Ottobock SE and Co. KGaA, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Artificial Organs and Bionic Implants Market Evolving Landscape
Closed-loop therapeutic response systems are reconfiguring competitive advantage in Spain's bionic implant sector, with real-time physiological monitoring capabilities becoming the primary differentiator in cardiac and neural device tenders.
Neural implants with integrated sensing electrodes are overtaking traditional deep brain stimulation devices in Spanish neurology centers. These systems enable adaptive stimulation parameters based on patient-specific biomarker feedback. Madrid's Hospital Clínico San Carlos and Barcelona's Hospital de la Santa Creu i Sant Pau are piloting these platforms for epilepsy and movement disorder protocols. The technology is compressing competitive margins for manufacturers lacking bioelectronic closed-loop architectures.
EMA centralized procedures under EU Medical Device Regulation are compressing clinical evidence requirements for transcatheter heart valve technologies. Manufacturers must now demonstrate real-world performance data through Spanish national registries alongside pre-market trials. Cardiac implant suppliers are responding by embedding post-market surveillance infrastructure directly into hospital contracts, particularly in Catalonia's integrated health system networks.
Spanish public hospital procurement is consolidating toward framework agreements with multi-year service bundles. Limb prosthetic and myoelectric device purchasing is shifting from transactional orders to total-cost-of-ownership contracts covering fitting, maintenance, and patient training. This restructuring is most visible in Madrid's regional health service, where rehabilitation hospital networks now specify outcome metrics for upper-extremity device functionality in tender documentation.
Spain Artificial Organs and Bionic Implants Market Segmentation
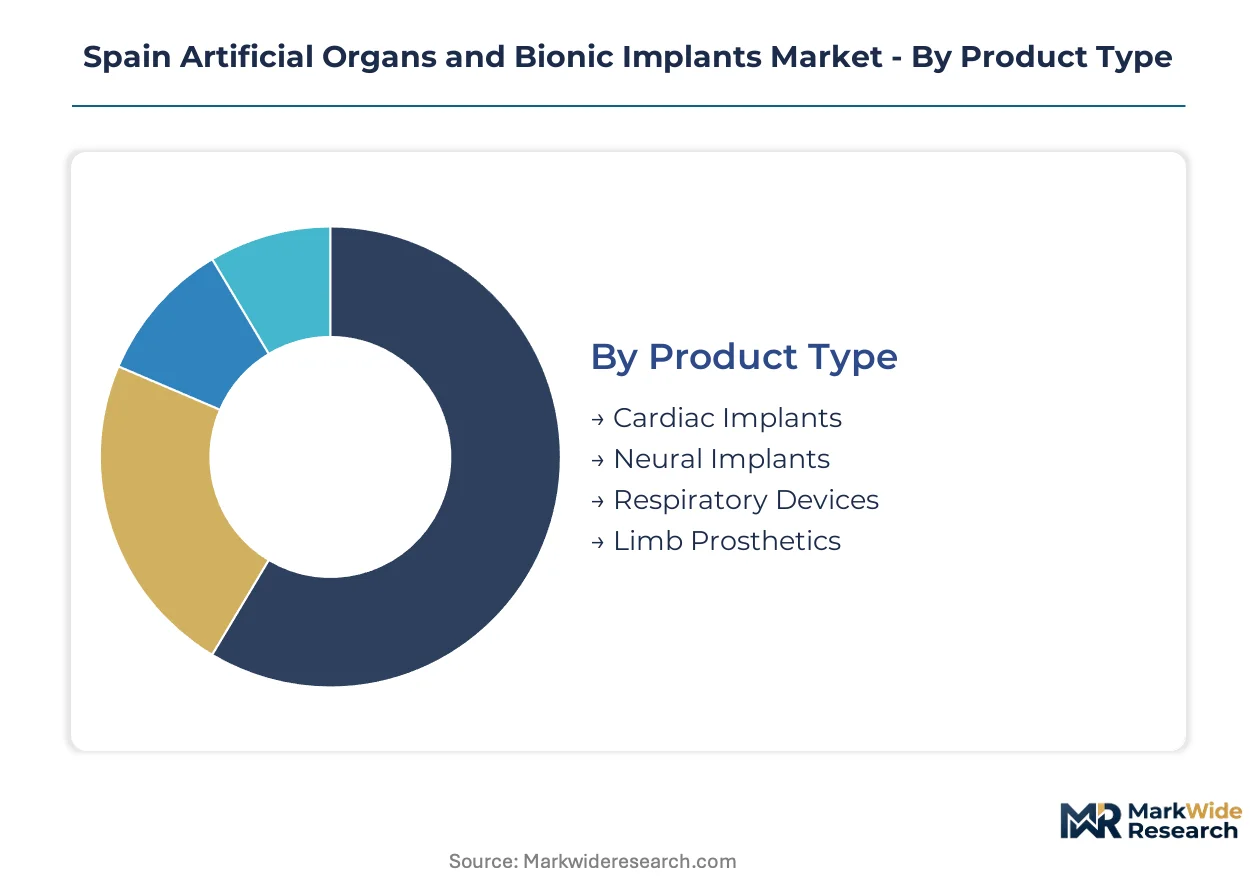
Spain's artificial organs and bionic implants market fragments across four distinct dimensions that determine procurement pathways, reimbursement eligibility, and regulatory scrutiny intensity. Each segmentation axis carries specific certification burdens from Spanish Agency for Medicines and Health Products and EU Medical Device Regulation frameworks that shape competitive access.
Product Type:
MDR Class III certification requirements fall most heavily on active implantable segments, with passive prosthetics navigating lighter conformity assessment routes through notified bodies in Barcelona and Madrid.
- Cardiac Implants:Titanium-alloy heart valves and ventricular assist devices incorporate biological tissue coatings and electromechanical pumping mechanisms. Demand clusters in Catalonia's integrated health system networks, where transcatheter procedures are migrating to day-hospital settings under compressed reimbursement protocols.
- Neural Implants:Deep brain stimulation electrodes with integrated sensing architectures enable adaptive parameter adjustment for Parkinson's and epilepsy protocols. Spanish neurology centers in Madrid and Barcelona are expanding these platforms fastest, pulling specialized procurement into regional framework agreements.
- Respiratory Devices:Artificial lung and diaphragmatic pacing systems for chronic obstructive pulmonary disease management.
- Limb Prosthetics:Socket technologies and myoelectric control systems for upper and lower extremity replacement.
Cardiac implants sit at the top of the volume ranking, with neural implants climbing the fastest.
Technology:
Cost tiers separate premium sensory-enabled platforms from standard passive devices, with reimbursement thresholds in Andalusia and Valencia favoring proven material categories over experimental bioelectronic architectures.
- Biocompatible Materials:Medical-grade titanium alloys, silicone elastomers, and polyurethane formulations form the structural substrate for implantable devices. Madrid's regional health service procurement concentrates purchasing power toward suppliers with ISO 13485-certified material traceability and closed-loop manufacturing documentation.
- Sensory Feedback:Closed-loop neural interfaces and haptic response systems in limb prosthetics command premium positioning. Spanish rehabilitation hospitals specify outcome metrics for upper-extremity functionality in tender documentation, compressing margins for manufacturers lacking real-time physiological monitoring capabilities.
- Power Management:Rechargeable lithium-ion cells and transcutaneous energy transfer systems for active implants.
- Microelectromechanical Systems:Miniaturized sensors and actuators enabling real-time biomarker detection.
Biocompatible materials capture the largest procurement volumes, while sensory feedback platforms gain share fastest through specialized transplant center contracts.
Application:
Customer workflow patterns distinguish acute surgical implantation from chronic disease management, with rehabilitation protocols requiring distinct training infrastructure and outcome measurement frameworks.
- Chronic Diseases Treatment:Long-term implant management for heart failure, movement disorders, and respiratory insufficiency. Spanish national healthcare system reimbursement policies under the Ministry of Health accelerate patient access to advanced bionic devices for diabetes-related complications and neurodegenerative conditions.
- Surgical Procedures:Acute implantation events for trauma response and congenital correction. Hospital de la Santa Creu i Sant Pau in Barcelona and Hospital Clínico San Carlos in Madrid anchor specialized surgical volumes for complex cardiac and neural interventions.
- Rehabilitation:Post-implant functional training and prosthetic fitting protocols.
- Cosmetic Enhancements:Aesthetic prosthetic applications outside medical necessity criteria.
Chronic diseases treatment dominates installed base maintenance, with surgical procedures expanding most quickly through minimally invasive platform adoption.
End User:
Procurement consolidation patterns vary sharply across institutional settings, with public hospital networks leveraging multi-year framework agreements while homecare channels remain fragmented.
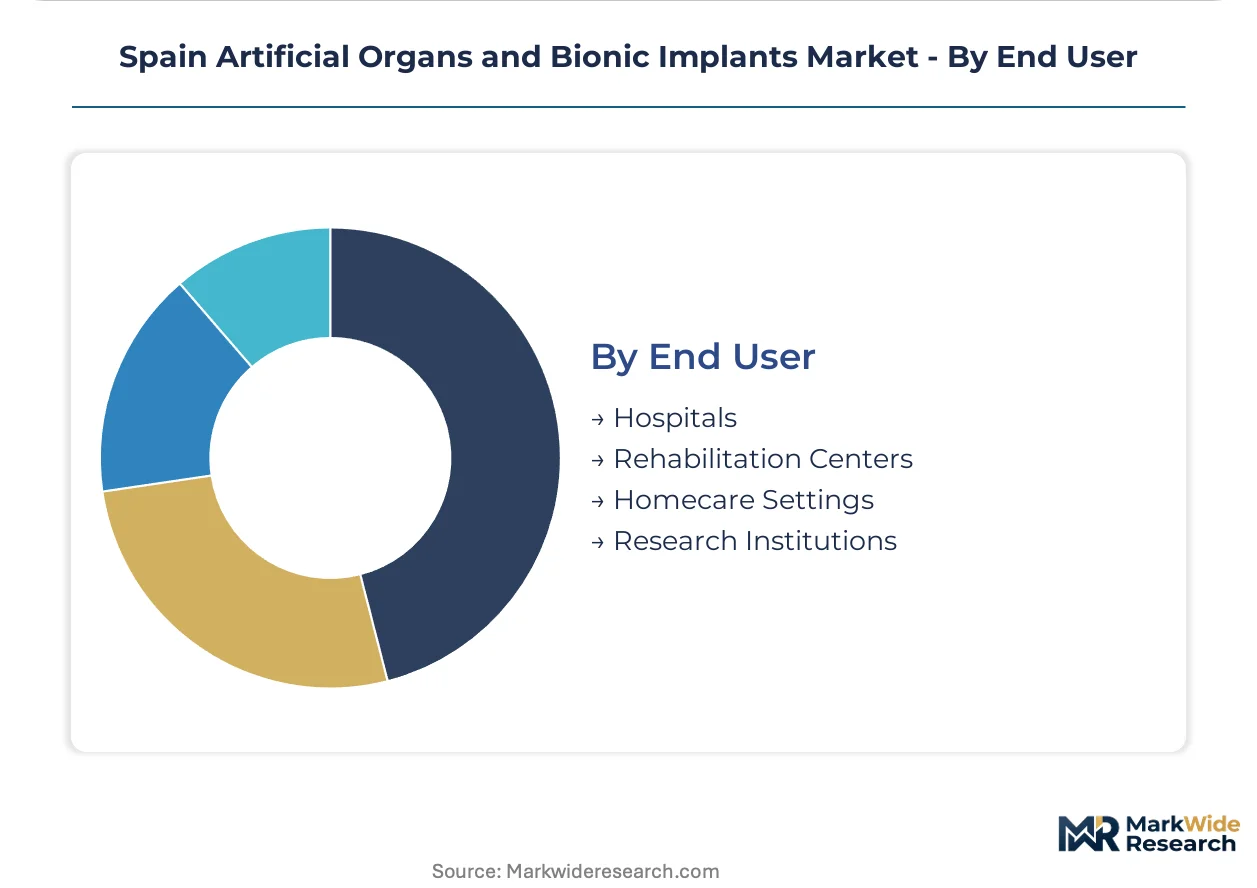
- Hospitals:Acute care facilities with catheterization laboratories and specialized surgery suites. Procurement concentrates in Madrid and Barcelona, where transplant centers and university hospitals cluster under regional health service sustainability criteria favoring certified biocompatible supply chains.
- Rehabilitation Centers:Post-acute facilities for prosthetic fitting and neural stimulation parameter optimization. Underpenetrated networks in Andalusia and Valencia present whitespace for limb prosthetic deployment as regional budgets expand.
- Homecare Settings:Patient-managed devices for remote monitoring and maintenance.
- Research Institutions:Clinical trial sites and experimental protocol development centers.
Hospitals anchor procurement volume, with rehabilitation centers posting the steepest expansion trajectory as regional networks professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's artificial organs and bionic implants sector emerged from post-war European reconstruction efforts, with early cardiac valve development in Barcelona establishing the Iberian Peninsula as a medical device manufacturing hub. Regional health service networks now coordinate procurement across autonomous communities, concentrating specialized surgical capacity in metropolitan centers while expanding rehabilitation infrastructure into underserved provinces.
Madrid
Hospital Clínico San Carlos and La Paz University Hospital anchor the capital's cardiac implant volumes, performing complex transcatheter procedures under compressed regional reimbursement protocols. The Ministry of Health's sustainability criteria favor suppliers with ISO 13485-certified biocompatible material traceability in public tenders. Madrid's regional health service consolidates multi-year framework agreements covering device procurement, fitting services, and patient training outcomes.
Catalonia
Hospital de la Santa Creu i Sant Pau pilots adaptive deep brain stimulation platforms for epilepsy and movement disorders, pulling neural prosthetic demand into specialized clinical workflows. The Catalan integrated health system networks embed post-market surveillance infrastructure directly into supplier contracts. Barcelona's concentration of university hospitals and research institutions accelerates translation of bioelectronic closed-loop architectures into commercial protocols.
Andalusia
Underpenetrated rehabilitation hospital networks in Seville and Málaga present whitespace for limb prosthetic and myoelectric control system deployment as regional budgets expand. The Andalusian Health Service applies stricter cost-effectiveness criteria for premium sensory feedback systems than Madrid or Barcelona. Public procurement consolidation favors suppliers offering total-cost-of-ownership contracts covering fitting, maintenance, and functional outcome metrics.
Basque Country
Advanced manufacturing clusters around Bilbao and San Sebastián supply precision titanium alloy components to cardiac implant producers serving Spanish and French markets. Basque regional health authorities coordinate cross-border procurement with French Aquitaine networks under EU Medical Device Regulation harmonization. Local industrial policy incentivizes circular material flows and carbon-reduced manufacturing for medical device tenders.
Valencia
La Fe Hospital and Dr. Peset University Hospital expand minimally invasive cardiac procedures into day-hospital settings, restructuring channel requirements for catheter-based delivery technologies. The Valencian regional health service lags Madrid and Catalonia in neural prosthetic adoption but accelerates limb prosthetic professionalization. Procurement patterns favor established biocompatible material categories over experimental bioelectronic architectures under current budget constraints.
Spain Artificial Organs and Bionic Implants Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Spain's bionic implant sector, with integrated manufacturers maintaining captive titanium alloy processing while specialized firms outsource component fabrication to Iberian foundries. Market structure tilts toward consolidation in cardiac and neural segments, where EMA centralized procedures and MDR certification timelines erect barriers to new entrants. Three archetypes dominate: diversified medical technology conglomerates with multi-implant portfolios, focused limb prosthetic specialists with rehabilitation service integration, and emerging bioelectronics firms betting on closed-loop sensory feedback differentiation. Competitive dynamics center on strategic partnerships with Spanish regional health services for multi-year framework agreements and backward integration into biocompatible material supply chains to satisfy sustainability procurement criteria.
Among diversified medical technology conglomerates, Medtronic plc and Boston Scientific Corporation occupy positions anchored by integrated cardiac implant portfolios and long-term public health system relationships. Edwards Lifesciences Corp. exemplifies the specialized cardiovascular technology archetype, with transcatheter heart valve expertise adapted to European regulatory pathways. Within limb prosthetics, Ossur hf. and Ottobock SE and Co. KGaA represent the rehabilitation-integrated specialist model, competing through socket technology customization and myoelectric control system deployment across Spanish regional hospital networks. Otto Bock Holding GmbH & Co. KG anchors the sensory feedback innovation vector, differentiating through advanced haptic response systems designed for rehabilitation center workflows. These named entities serve as reference points for understanding competitive positioning without attributing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Abiomed Inc. |
| Medtronic plc |
| Ossur hf. |
| Edwards Lifesciences Corp. |
| Zimmer Biomet |
| Otto Bock Holding GmbH & Co. KG |
| Ottobock SE and Co. KGaA |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Titanium alloy feedstock from German and Swiss smelters flows through Iberian processors into three distinct pricing tiers for cardiac implants, with Madrid's regional health service procurement compressing margins on standard-grade devices while premium sensory-enabled platforms command protected positioning through outcome-based contracting.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Spain's bionic implant procurement, with ISO 13485 certification grade and closed-loop manufacturing documentation serving as the primary price differentiation drivers. Cost compression in standard-grade cardiac valves is intensifying because Madrid's framework agreements consolidate purchasing power toward multi-year service bundles. Public hospital networks exhibit the highest price sensitivity, while specialized transplant centers in Barcelona maintain appetite for premium neural prosthetics with integrated sensing architectures.
Supply Chain Analysis
Remanufacturing flows for explanted cardiac devices and prosthetic component refurbishment are emerging as critical reverse-logistics capabilities under Spain's EU Green Deal procurement incentives. Supply concentrates in Germany for medical-grade polymers, Switzerland for precision titanium processing, and the Netherlands for microelectromechanical system packaging. Spanish manufacturers draw from concentrated silicone elastomer and polyurethane sources, exposing the sector to single-source vulnerability from German chemical producers. Distribution runs through regional health service procurement consortia directly to hospital cath labs and rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's artificial organs and bionic implants market represents a late-cycle quality story where regional health service consolidation favors suppliers with certified biocompatible material traceability and proven post-market surveillance infrastructure. The demand shift toward adaptive deep brain stimulation platforms with real-time biomarker feedback is elevating premium-tier pricing power.
For Market Incumbents: To counter margin compression from Madrid's framework agreement consolidation, Medtronic plc and Edwards Lifesciences Corp. should deepen backward integration into Iberian titanium alloy processing and embed post-market surveillance infrastructure directly into Catalan health system contracts. Certification investment in MDR Class III active implantable pathways remains essential for defending procurement access. For New Entrants and Emerging Players: Direct-to-rehabilitation-center digital platforms offer the most penetrable route for limb prosthetic specialists seeking Andalusian and Valencia market entry. Underpenetrated rehabilitation hospital networks in southern Spain present whitespace for myoelectric control system deployment, with total-cost-of-ownership contracting providing the strongest go-to-market angle against established incumbents. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap sensory feedback technology specialists because Spain's regional procurement consolidation creates acquisition currency for platforms with closed-loop bioelectronic architectures. The long-term viability window favors targets with ISO 13485-certified supply chains and existing framework agreements with Madrid or Catalonia. Practitioners should monitor EMA centralized procedure approval timelines for adaptive neural implants as the inflection signal for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class III Certification Pathway | EMA centralized procedures compress approval timelines for active implantable devices entering Spanish hospital procurement windows. |
| Hospital System Partnership | Catalonia's integrated health system networks embed post-market surveillance requirements directly into multi-year supplier contracts. |
| Backward Integration into Titanium Processing | Iberian raw material investments reduce import dependency and satisfy Madrid's sustainability procurement criteria for biocompatible supply chains. |
| Software Companion Development | Closed-loop therapeutic response systems with real-time physiological monitoring differentiate neural prosthetics in Spanish neurology center tenders. |
| Reimbursement Strategy | Spain's Ministry of Health regional budget negotiations determine patient access thresholds for high-cost bionic sensory feedback systems. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers at transplant centers, GPO contracts managers, and regional health service procurement directors grounded the qualitative assessment, cross-referenced against EMA submission databases, Spanish Agency for Medicines and Health Products vigilance records, hospital procurement registries, and ISO 13485 certification listings. Secondary validation combined bottom-up device shipment analysis with top-down healthcare expenditure modeling across autonomous communities.
Bottom-up segmentation modeling tracked cardiac implants, neural prosthetics, limb prosthetics, and respiratory devices by technology tier, application setting, and end-user institution type throughout the forecast period. Top-down triangulation anchored volume projections to Spanish national healthcare system expenditure patterns and regional health service budget allocations. CAGRs derived from procedure volume growth in Madrid and Barcelona transplant centers, MDR certification pipeline visibility, and reimbursement policy evolution under Ministry of Health coordination.
The model assumes a particular technology adoption path for closed-loop neural interfaces; alternative pathways for non-invasive neuromodulation would alter the outlook for invasive deep brain stimulation penetration. Forecasts reflect assumptions about EMA centralized procedure efficiency and regional budget expansion trajectories. Practitioners should monitor notified body capacity constraints and Andalusian Health Service reimbursement threshold adjustments for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Intravaginal Device Market
Medical Devices
Annuloplasty System Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Foot Suction Unit Market