
 Electric Shoe Dryer Market | 2026-2036
Electric Shoe Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Shoe Dryer Market Foresight
Subscription-based maintenance and filter-replacement programs is broadening recurring revenue streams beyond one-time hardware sales. Peet Shoe Dryer, Inc. leverages its established dealer network to sustain strong aftermarket attachment rates. Caframo Limited anchors its competitive stance through R&D intensity in low-wattage thermal designs. StinkBOSS differentiates via ozone-integration technology that extends its addressable base beyond moisture removal into odor neutralization.
An electric shoe dryer is an electromechanical appliance that applies controlled thermal energy, forced convection, or radiant heat to footwear interiors to accelerate moisture evaporation and inhibit microbial proliferation. Typical units operate between 35 watts and 250 watts, with convection models relying on heated air circulation and infrared variants employing ceramic emitters to penetrate dense boot materials without surface degradation. Portable dryers lead unit shipments due to their travel compatibility and low entry price, though wall-mounted dryers command superior margin pools in commercial installations where permanence and capacity justify premium positioning. UV Light technology represents the fastest-growing segment as antimicrobial efficacy becomes a non-negotiable specification for institutional buyers such as sports teams and hotels.
The US Consumer Product Safety Commission and the EU Ecodesign Directive jointly shape product standards by enforcing thermal safety thresholds and standby power limits that determine market access. Germany's Federal Institute for Materials Research and Testing provides voluntary certification pathways that manufacturers increasingly treat as de facto requirements for premium positioning. Stakeholders must monitor how pending amendments to EU energy-labeling rules recalibrate the cost-competitiveness of infrared versus convection architectures.
Market Dynamics
EU Ecodesign Directive standby power limits are compressing margins for convection-heavy portfolios while favoring infrared architectures with inherently lower idle consumption, forcing manufacturers to retool thermal management strategies.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power ceilings below one watt are accelerating R&D investment in ceramic emitter and PTC heating element designs that minimize parasitic load.
- Sports team hygiene protocols:Collegiate and professional athletic programs now mandate post-practice footwear sanitization, creating institutional demand for UV-integrated drying cabinets.
- German outdoor recreation culture:Hiking and skiing participation rates sustain replacement cycles for residential portable units in a market with above-average price tolerance for energy-efficient models.
Market Restraints
- Ceramic emitter supply concentration:Sourcing of alumina-based infrared emitters clusters among East Asian substrate specialists, exposing manufacturers to freight cost volatility and extended lead times.
- Substitution by low-tech alternatives:Silica gel desiccant packs and newspaper stuffing retain cost-sensitive consumer segments, particularly in emerging markets with unreliable electricity access.
- REACH compliance complexity:Registration requirements for ozone-generating components in antimicrobial dryers create documentation burdens that delay EU market entry for smaller appliance makers.
Strategic Opportunities
- India residential electrification:Rural household appliance penetration remains below fifteen percent for footwear care devices, presenting first-mover positioning for solar-compatible low-wattage designs.
- Hotel chain standardization mandates:Mid-scale hospitality procurement departments are consolidating vendor lists around dual-function odor-neutralization units, favoring suppliers with ozone-ceramic hybrid platforms.
- Subscription filter replacement:Recurring revenue models for antimicrobial cartridge replenishment are expanding addressable lifetime value beyond hardware margins in institutional accounts.
Industry Challenges
- Thermal engineer talent scarcity:Cross-disciplinary expertise combining HVAC miniaturization with footwear biomechanics is concentrated among senior designers at legacy appliance manufacturers, constraining startup hiring pipelines.
- Multi-certification timelines:Simultaneous pursuit of UL thermal safety, CE electromagnetic compatibility, and BIS voltage standards extends product development cycles by eight to fourteen months for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Shoe Dryer Market |
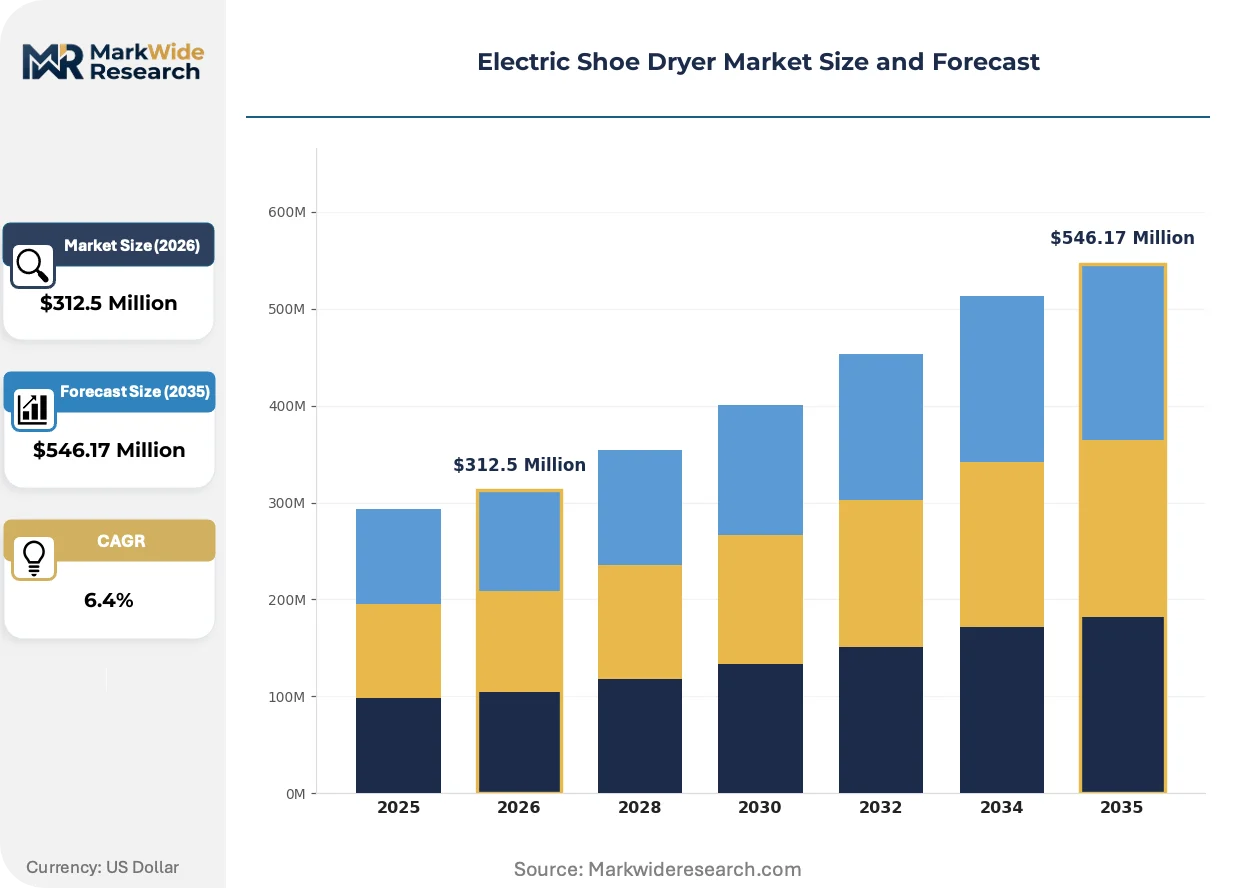
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dryers, Wall-mounted Dryers, Boot Dryers, Multi-purpose Dryers Technology: Convection, Infrared, UV Light, Fan-based End User: Home Users, Sports Teams, Retail Stores, Hotels Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | StinkBOSS, Housmile Electronics, Peet Shoe Dryer, Inc., KMS Designs Inc., Kendal, Danner, Inc., Caframo Limited, ROK Industries, Impulse LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Shoe Dryer Market Shifts & Advancements
Active convergence between antimicrobial efficacy claims and connected appliance architectures is redefining product roadmaps, with sensor-enabled moisture detection and automated cycle optimization emerging as baseline expectations rather than premium differentiators.
UV-C LED arrays integrated with forced convection chambers are expanding into ski resort rental operations and military barracks facilities where batch processing of heavy boots demands both speed and pathogen elimination. These installations prioritize throughput over unit economics, compressing payback period calculations for capital equipment procurement committees and favoring suppliers with field service networks.
REACH substance restrictions on halogenated flame retardants are compelling housing material substitutions toward glass-filled polyamides with inherent thermal resistance, elevating compound costs but eliminating downstream liability exposure for manufacturers distributing across the European Economic Area. German testing institutes report twelve-month backlogs for revised material safety dossier validation.
Facility managers at collegiate athletic departments are unbundling footwear hygiene from general equipment laundry contracts, creating standalone procurement categories with dedicated capital budgets and specialized vendor qualification criteria. This purchasing autonomy is most pronounced in the Mountain West and Pacific Northwest conference geographies where wet-climate training schedules accelerate equipment degradation.
Electric Shoe Dryer Market Segmentation
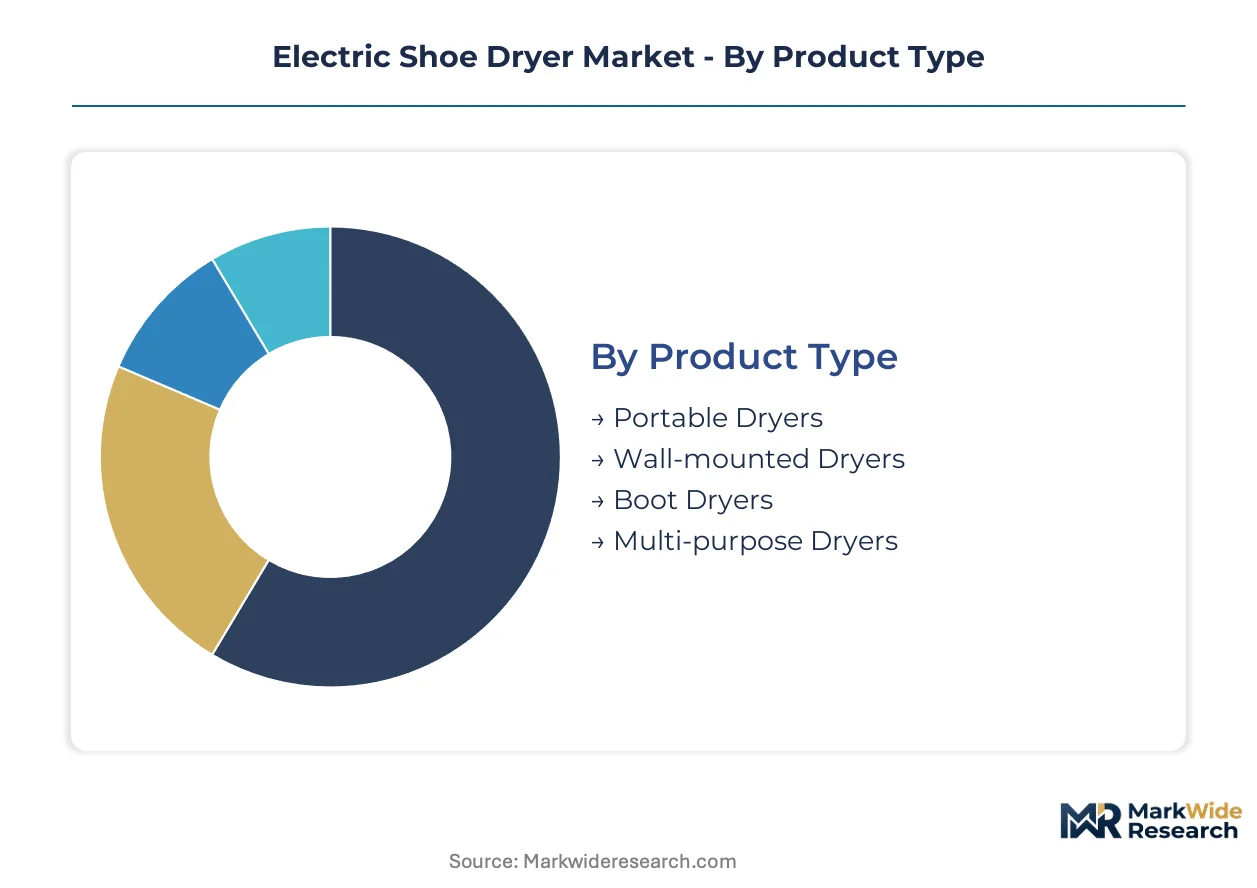
Segmentation in the electric shoe dryer market reveals how thermal engineering specifications and installation permanence split purchasing behavior across residential, commercial, and institutional buyers. Each axis—product form factor, heating modality, end-use environment, and wattage tier—carries distinct margin profiles and certification requirements that shape supplier strategy.
Product Type:
Thermal management architecture and installation permanence define competitive positioning across portable, fixed-mount, and specialized configurations.
- Portable Dryers:Compact units employing PTC heating elements or low-wattage convection modules, typically operating between 35 and 80 watts. Unit shipments concentrate in Germany and Austria where alpine recreation culture sustains replacement cycles for travel-compatible designs constrained by airline power limits.
- Wall-mounted Dryers:Permanent installations with higher thermal output and integrated timers, commanding premium positioning in commercial settings. Procurement committees at ski resort rental facilities and military barracks favor these units for batch-processing throughput and reduced floor-space occupation.
- Boot Dryers:Specialized form factors with extended drying tubes engineered for wader, ski boot, and tactical footwear geometries. Demand clusters in Pacific Northwest collegiate athletic departments where wet-climate training schedules accelerate equipment degradation.
- Multi-purpose Dryers:Modular platforms accommodating gloves, helmets, and protective gear alongside footwear. These configurations gain traction in fire stations and industrial safety programs seeking consolidated hygiene infrastructure.
Mature deployment sits with portable units in German residential channels. Newer deployment is concentrated in wall-mounted configurations at North American institutional facilities.
Technology:
Heat transfer mechanism determines energy efficiency certification trajectories and antimicrobial efficacy claims under tightening hygiene protocols.
- Convection:Forced-air circulation through heated coils, the incumbent architecture facing margin compression from EU Ecodesign Directive standby power limits below one watt. Manufacturers with convection-heavy portfolios accelerate retooling toward ceramic emitter alternatives.
- Infrared:Ceramic or quartz emitters penetrating dense boot materials without surface thermal degradation. German Federal Institute for Materials Research and Testing certification pathways increasingly treat infrared architectures as de facto requirements for premium residential positioning.
- UV Light:UV-C LED arrays integrated with drying chambers for pathogen elimination. Collegiate and professional athletic programs now mandate this specification for post-practice footwear sanitization, with Mountain West conference geographies leading procurement autonomy.
- Fan-based:Ambient air circulation without active heating, occupying entry price tiers where energy access constraints limit wattage tolerance. Sourcing clusters among East Asian contract manufacturers serving emerging market distributors.
Installed base concentration favors convection in legacy commercial installations. Steepest expansion trajectory belongs to UV Light configurations as institutional hygiene protocols tighten.
End User:
Purchasing autonomy and capital budget structures fragment demand across consumer, athletic, retail, and hospitality verticals with diverging specification priorities.
- Home Users:Individual consumers prioritizing travel compatibility and low entry price, with above-average price tolerance for energy-efficient models in German-speaking markets. Replacement cycles correlate with outdoor recreation participation rates.
- Sports Teams:Collegiate and professional athletic programs with dedicated capital budgets for standalone footwear hygiene procurement. Unbundling from general equipment laundry contracts creates specialized vendor qualification criteria most pronounced in wet-climate conference geographies.
- Retail Stores:Footwear merchants and outdoor equipment retailers offering drying as customer amenity or value-added service. Deployment concentrates in premium brand flagship locations where experiential investment supports margin architecture.
- Hotels:Mid-scale hospitality procurement departments consolidating vendor lists around dual-function odor-neutralization units. Chain standardization mandates favor suppliers with ozone-ceramic hybrid platforms and field service networks.
Volume concentration remains with home users in European residential channels. Margin expansion is concentrating in hotel procurement as chain-level standardization consolidates supplier relationships.
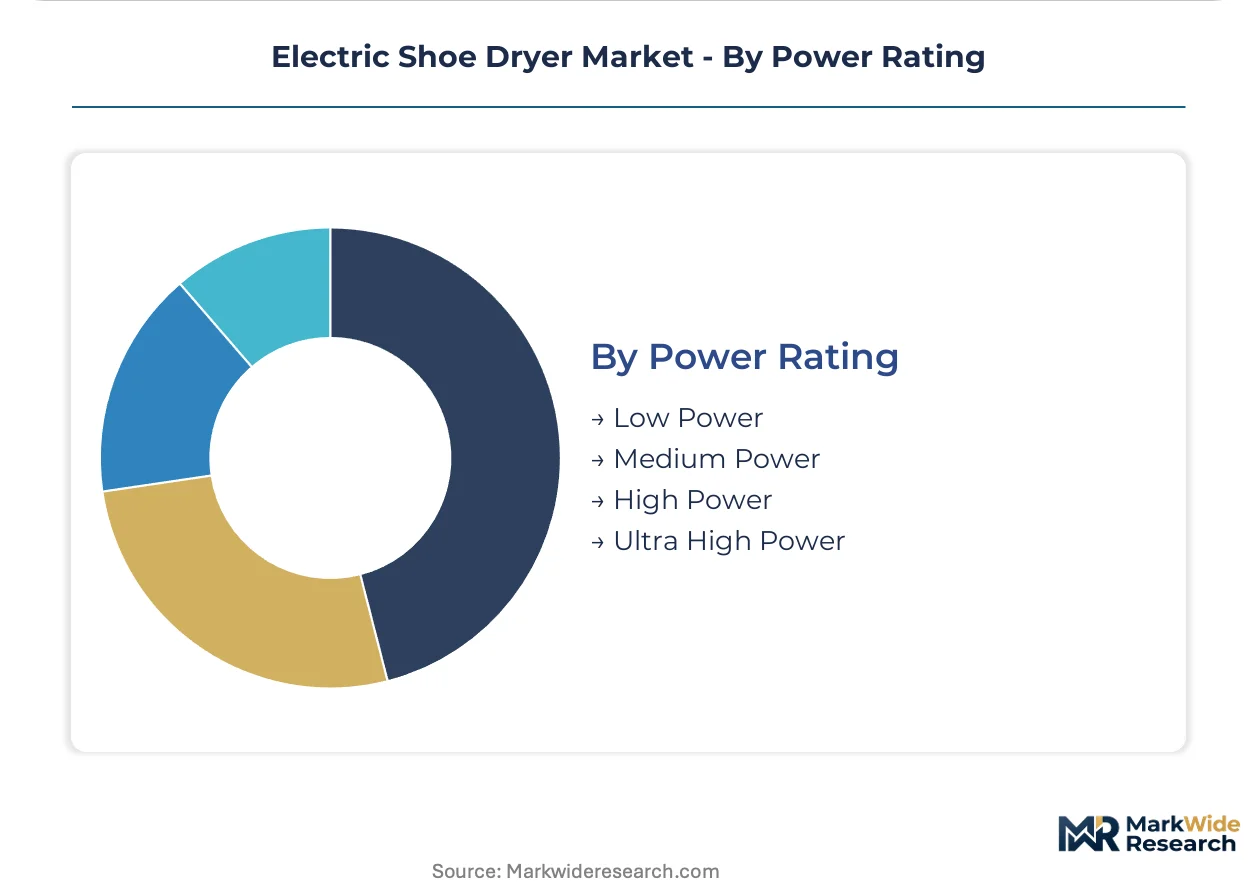
Power Rating:
Wattage tier alignment with grid infrastructure reliability and thermal output requirements segments markets by electrification maturity and use-case intensity.
- Low Power:Units operating below 50 watts, compatible with solar off-grid installations and airline power ports. First-mover positioning targets Indian rural household electrification where appliance penetration for footwear care devices remains under fifteen percent.
- Medium Power:50-150 watt range balancing drying speed with residential circuit capacity, dominating European mass-market channels. EU energy-labeling rule amendments recalibrate cost-competitiveness of architectures within this band.
- High Power:150-250 watt configurations for commercial batch processing and heavy boot materials. Ski resort rental operations prioritize throughput over unit economics, compressing payback period calculations for capital equipment committees.
- Ultra High Power:Specialized industrial units exceeding 250 watts for military, fire service, and emergency responder applications with accelerated drying mandates. Procurement requires MIL-SPEC or equivalent durability certification extending development timelines.
Revenue concentration aligns with medium power in European residential markets. Fastest share gains are occurring in low power designs targeting solar-compatible emerging market deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of electric shoe dryers concentrates in East Asian electronics clusters while consumption tilts toward alpine recreation markets and institutional hygiene adopters in North America and Europe. This geographic split shapes trade flows and certification requirements.
Germany
Outdoor recreation participation sustains replacement cycles for portable units with above-average price tolerance for energy-efficient models. The EU Ecodesign Directive mandates standby power ceilings below one watt, accelerating R&D investment in ceramic emitter designs. Bavaria hosts testing institutes reporting twelve-month backlogs for revised material safety dossier validation.
United States
Collegiate athletic programs in wet-climate conference geographies now mandate post-practice footwear sanitization with dedicated capital budgets. The US Consumer Product Safety Commission enforces thermal safety thresholds determining market access. Mountain West and Pacific Northwest facilities lead procurement autonomy for standalone hygiene infrastructure.
China
Contract manufacturers dominate entry-price fan-based dryer production for emerging market distributors. The country's national standards body governs electromagnetic compatibility certification for export-bound production. Guangdong and Zhejiang provinces concentrate substrate specialists supplying alumina-based infrared emitters to global brands.
India
Rural household appliance penetration for footwear care devices remains below fifteen percent, presenting first-mover positioning for solar-compatible low-wattage designs. The Bureau of Indian Standards voltage standards extend product development timelines for multi-territory launches. Maharashtra and Gujarat industrial corridors attract assembly operations targeting domestic electrification expansion.
Canada
Ski resort rental operations prioritize throughput over unit economics for commercial batch-processing installations. Health Canada product safety requirements align with UL thermal safety protocols for cross-border distribution. British Columbia and Alberta mountain clusters drive demand for heavy-boot drying cabinets with integrated UV-C arrays.
Electric Shoe Dryer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a fragmented vendor base where no single participant commands dominant share. The market structures around three tiers: legacy appliance manufacturers with established dealer networks, specialty thermal engineering firms with R&D intensity in low-wattage designs, and contract assemblers serving price-sensitive channels. Consolidation remains limited; competitive moves concentrate on geographic expansion through distributor partnerships and technology licensing for antimicrobial efficacy claims.
Within the legacy manufacturer tier, Peet Shoe Dryer, Inc. and Caframo Limited occupy positions anchored by established thermal management expertise and aftermarket service infrastructure. StinkBOSS exemplifies the specialist archetype pursuing differentiation through ozone-integration platforms. These three companies represent contrasting strategic postures: dealer-network scale, R&D-led efficiency optimization, and technology-driven addressable market expansion beyond moisture removal into odor neutralization.
| Leading Market Players |
|---|
| StinkBOSS |
| Housmile Electronics |
| Peet Shoe Dryer, Inc. |
| KMS Designs Inc. |
| Kendal |
| Danner, Inc. |
| Caframo Limited |
| ROK Industries |
| Impulse LLC |
| Others |
Supply & Pricing Matrix
Family-owned thermal engineering specialists in Germany and Austria anchor premium pricing discipline through direct-to-dealer relationships, insulating margin pools from the margin compression that contract assemblers in East Asia absorb. Their captive service networks sustain aftermarket attachment rates that offset hardware commoditization pressures elsewhere in the value chain.
Pricing Analysis
Margin tightening in convection-heavy portfolios reflects EU Ecodesign Directive standby power limits below one watt, accelerating migration toward ceramic emitter architectures with superior idle efficiency. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified institutional configurations from CE-marked residential units and unbranded fan-based imports. Price differentiation traces to certification grade and after-sales bundling, with field service networks commanding fifteen to twenty percent premiums over transactional hardware sales. Home users in German-speaking markets exhibit least price sensitivity for energy-efficient models, while emerging market distributors face acute cost-down pressure from silica gel substitute competition.
Supply Chain Analysis
Returns and refurbishment flows for institutional-grade UV-C cabinets concentrate servicing capacity around North American collegiate athletic hubs and Alpine ski resort clusters, creating regional aftermarket nodes. Manufacturing draws from China, Vietnam, and Malaysia for fan-based assemblies, while alumina-based infrared emitters source exclusively from Guangdong and Zhejiang substrate specialists. Raw material dependencies include ceramic substrates, UV-C LED arrays, and halogen-free polyamide housings compelled by REACH substance restrictions. Single-source vulnerability in ceramic emitter supply exposes manufacturers to freight cost volatility. Distribution runs through outdoor equipment retailers in European residential channels and direct procurement committees at North American institutional facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive constructs a barrier-to-entry moat where compliance investment separates viable competitors from marginal players, rewarding incumbents with certified product platforms and straining contract assemblers lacking R&D scale.
For Market Incumbents: Extend field service network density into Mountain West collegiate athletic corridors to capture unbundled footwear hygiene procurement migrating from general equipment laundry contracts. Deepen backward integration into ceramic emitter sourcing through exclusive offtake arrangements with Zhejiang substrate specialists, insulating margin pools from supply concentration risk. Ozone-generating component REACH documentation burdens threaten smaller appliance makers with eighteen-month market entry delays. For New Entrants and Emerging Players: The gap between premium infrared-certified residential units and economy fan-based imports opens white-space positioning for solar-compatible low-wattage designs targeting Indian rural electrification. First-mover advantage concentrates in Maharashtra and Gujarat industrial corridors where appliance penetration for footwear care devices remains under fifteen percent. Go-to-market execution partners with rural electrification programs and microfinance distributors rather than conventional retail channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light designers with ozone-ceramic hybrid platforms in German-speaking markets, where Bavarian testing institute backlogs strand non-compliant competitors. Long-term viability across the analysis window hinges on antimicrobial efficacy claim validation and connected appliance architecture integration. Acquisition target archetype: specialist thermal engineering firms with R&D intensity in sub-fifty-watt designs and established BIS certification pathways. Monitor pending EU energy-labeling rule amendments as inflection signal for infrared versus convection architecture cost-competitiveness recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Emitter R&D Investment | PTC heating element redesign secures EU Ecodesign Directive compliance below one-watt standby thresholds. |
| UV-C LED Array Integration | Antimicrobial efficacy claims satisfy collegiate athletic program post-practice sanitization mandates in wet-climate conferences. |
| Subscription Filter Replacement Launch | Recurring revenue models expand addressable lifetime value beyond hardware margins in institutional accounts. |
| Direct Procurement Committee Engagement | Unbundled footwear hygiene budgets at Pacific Northwest facilities bypass consolidated laundry contract gatekeepers. |
| Halogen-Free Polyamide Housing Transition | Glass-filled polyamide substitution eliminates downstream REACH liability exposure across the European Economic Area. |
Research Methodology
Document review covered customs and trade data, SEC appliance manufacturer filings, EU regulatory databases, and industry association technical standards, complemented by interviews with thermal engineering directors, collegiate athletic equipment managers, hospitality procurement officers, and outdoor retail category buyers. Secondary validation drew from BIS voltage standard documentation, German Federal Institute for Materials Research and Testing certification records, and REACH substance restriction updates. Bottom-up shipment modeling triangulated against top-down consumer expenditure surveys across residential and institutional channels.
Unit volume and value projections across the analysis window employed segmented modeling by product form factor, heating modality, end-use environment, and wattage tier, with regional regulatory cluster overlays for EU Ecodesign, UL thermal safety, and BIS electromagnetic compatibility trajectories. CAGRs derived from replacement cycle analysis correlated with outdoor recreation participation indices and institutional hygiene protocol adoption curves. Industry-specific inputs included ski resort rental operation throughput requirements and military barracks batch-processing specifications.
Inputs from collegiate athletic procurement committees and hospitality chain standardization departments were available through the study window; gaps in real-time ceramic emitter spot pricing and freight rate volatility introduce uncertainty bands around margin compression assumptions. Forecasts reflect documented regulatory amendment timelines and material substitution cost curves. Practitioners should monitor EU energy-labeling rule amendment publication and REACH substance restriction expansion for early signals of architecture cost-competitiveness shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cat Hair Remover Market
Household Items
Robot Mops Market
Household Items
Thermos Drinkware Market
Household Items
Sorting Hampers Market
Household Items
Hydration Containers Market
Household Items
Hands-Free Faucet Market
Household Items
Disposable Cutlery Market
Household Items
Smart Bathtub Market
Household Items
Smart Shower Market
Household Items
Electric Hedge Trimmer Market
Household Items
North America Tankless Water Heater Market
Household Items
Global Buddhist Supplies Market
Household Items
Multi Pocket Holders Market
Household Items
Portable Steam Cleaners Market
Household Items
Mosquito Repellent Candles Market
Household Items
India Non-Stick Cookware Market