
 Cooking Gloves Market | 2026-2036
Cooking Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Gloves Market Insights
Malaysian rubber-glove manufacturing capacity is shifting toward value-added kitchen applications after years of medical-glove dominance. Top Glove leverages its integrated nitrile supply chain to anchor heat-resistant product lines for North American distributors. Ansell Ltd competes through specialized silicone formulations that sustain premium positioning in European professional kitchens. Kossan Rubber Industries Bhd differentiates via palm-dipped Kevlar blends targeting cut-resistant segments.
Cooking gloves are personal protective equipment engineered from silicone, Kevlar, cotton, or neoprene with specified heat-resistance thresholds, designed to shield hands from thermal burns, cuts, and moisture during food preparation. Silicone variants now dominate home-chef channels due to dishwasher-safe properties and grip-pattern innovations, while Kevlar-reinforced gloves command the professional-kitchen margin pool where ANSI cut-level certification determines procurement eligibility. The functionality dimension splits cleanly: heat-resistance SKUs lead volume, but cut-resistant combinations represent the fastest-growing configuration as commercial insurers mandate higher hand-protection standards.
OSHA hand-protection guidelines, EU food-contact material frameworks under EFSA, and FDA indirect food-additive regulations collectively shape product formulation, labeling, and import clearance requirements for cooking glove suppliers. Compliance with REACH chemical restrictions and evolving PFAS limitations in Europe now forces reformulation of certain waterproof coatings, raising R&D costs but also creating barriers against low-cost uncertified imports. Stakeholders must monitor how pending updates to heat-resistance testing protocols will reshape competitive positioning between established North American brands and emerging Asian manufacturers.
Market Dynamics
Professional kitchen procurement now pivots on ANSI cut-level certification as commercial insurers rewrite liability policies, forcing distributors to abandon uncertified SKUs and consolidate supplier relationships around compliant manufacturers.
Growth Catalysts
- OSHA heat-resistance mandates:Updated hand-protection guidelines in foodservice establishments now require documented thermal-rating thresholds, driving replacement cycles for legacy cotton and neoprene inventory.
- Silicone dishwasher-safe formulations:Home-chef channels favor grip-pattern innovations that withstand repeated commercial dishwasher cycles, reducing replacement frequency and building brand loyalty.
- German professional-kitchen concentration:Michelin-starred restaurant density in Bavaria and Baden-Württemberg creates concentrated demand for Kevlar-reinforced gloves with EFSA food-contact compliance.
Market Restraints
- Natural rubber price volatility:Malaysian latex input costs fluctuate with monsoon patterns and palm-oil diversion, compressing margin predictability for nitrile-blend manufacturers.
- REACH chemical reformulation costs:ECHA restrictions on PFAS waterproof coatings force European suppliers to rebuild coating chemistry from raw-material stage, extending R&D timelines.
- Uncertified Asian import pressure:Low-cost silicone gloves lacking ANSI or CE markings capture price-sensitive home-kitchen segments, eroding mid-tier positioning.
Strategic Opportunities
- China's commercial-kitchen modernization:State-backed restaurant chain consolidation in Shanghai and Guangzhou creates first-mover advantage for heat-resistant glove suppliers with GB standards compliance.
- Direct-to-chef subscription channels:Monthly replenishment models bypass foodservice distributors and capture recurring revenue from high-turnover professional kitchens.
- EU Green Deal circularity incentives:Recyclable silicone recovery programs receive preferential procurement scoring in public-sector catering contracts across France and Italy.
Industry Challenges
- ANSI cut-level testing bottlenecks:Third-party certification backlogs extend product-launch timelines by four to six months for Kevlar-reinforced SKUs.
- Legacy distributor integration:Established foodservice supply houses resist SKU rationalization, forcing manufacturers to maintain parallel inventory systems for compliant and non-compliant product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Gloves Market |
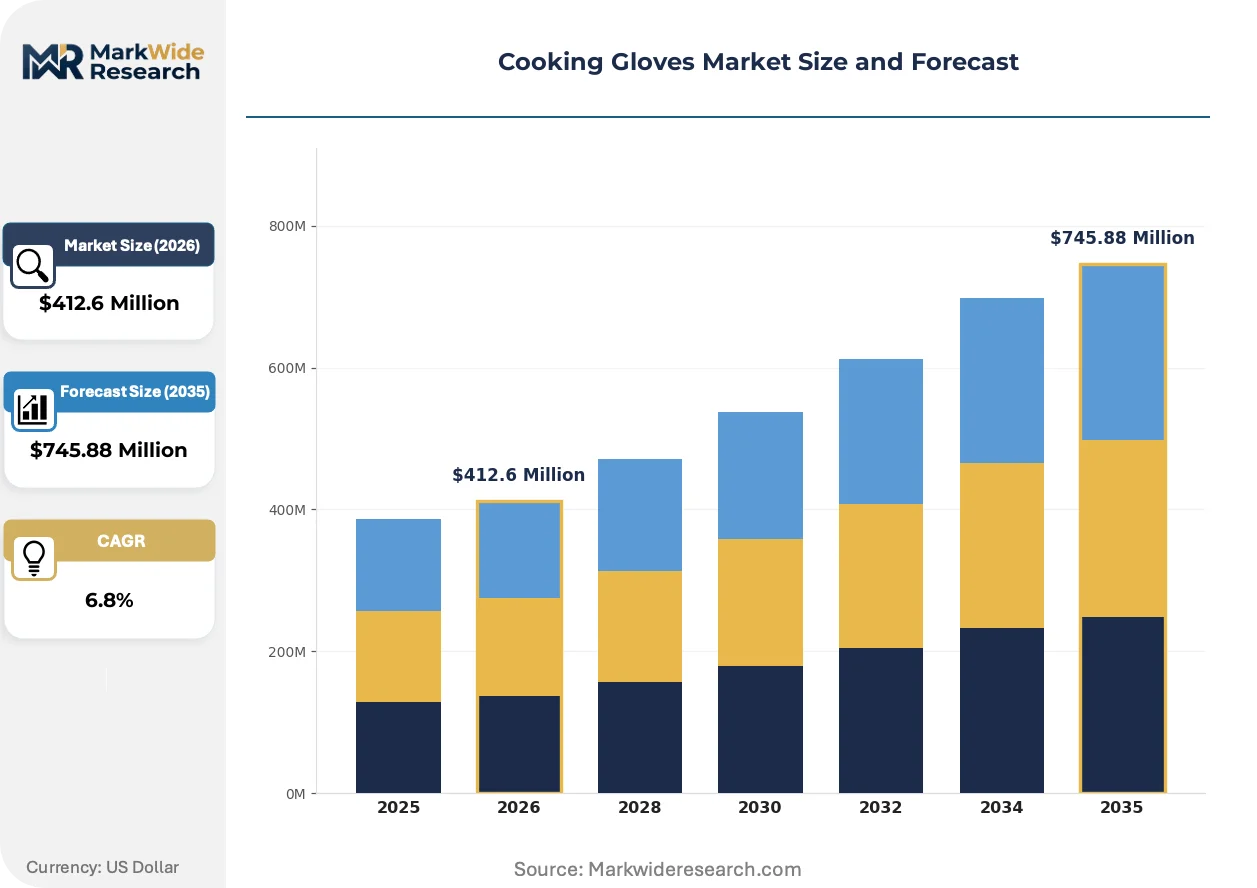
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Silicone, Kevlar, Cotton, Neoprene Functionality: Heat Resistance, Waterproof, Non-Slip, Cut Resistant Size: Small, Medium, Large, Extra Large End User: Home Chefs, Professional Kitchens, Food Trucks, Catering Services |
| Companies Covered | Superior Glove, RFB Gloves, Top Glove, Glovables, Cello World, Ansell Ltd, Kossan Rubber Industries Bhd, Globus Group, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Gloves Market Trends and Innovations
Material science convergence with food-safety compliance is rewriting product-development roadmaps, as manufacturers balance thermal performance against chemical migration limits and end-of-life recyclability.
Hybrid silicone-Kevlar laminates are expanding into professional-kitchen channels previously dominated by single-material gloves. Three-star restaurants in California and Tokyo now specify these composites for their combined heat and cut protection. The technology is expanding into premium home-chef segments as cooking-show visibility normalizes professional-grade hand protection.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing waterproof-coating reformulations across European supply chains. Manufacturers must validate new barrier chemistries through EFSA migration testing before market entry. German and Dutch distributors are responding by consolidating supplier bases to partners with in-house polymer laboratories.
Restaurant-group procurement offices now mandate consolidated PPE purchasing across multi-unit operations, displacing location-level autonomy. Foodservice management companies in the United States bundle cooking gloves with uniform and smallware contracts, squeezing standalone glove distributors. This concentration is most visible in fast-casual chain rollouts where standardized kitchen equipment extends to hand-protection specifications.
Cooking Gloves Market Segmentation
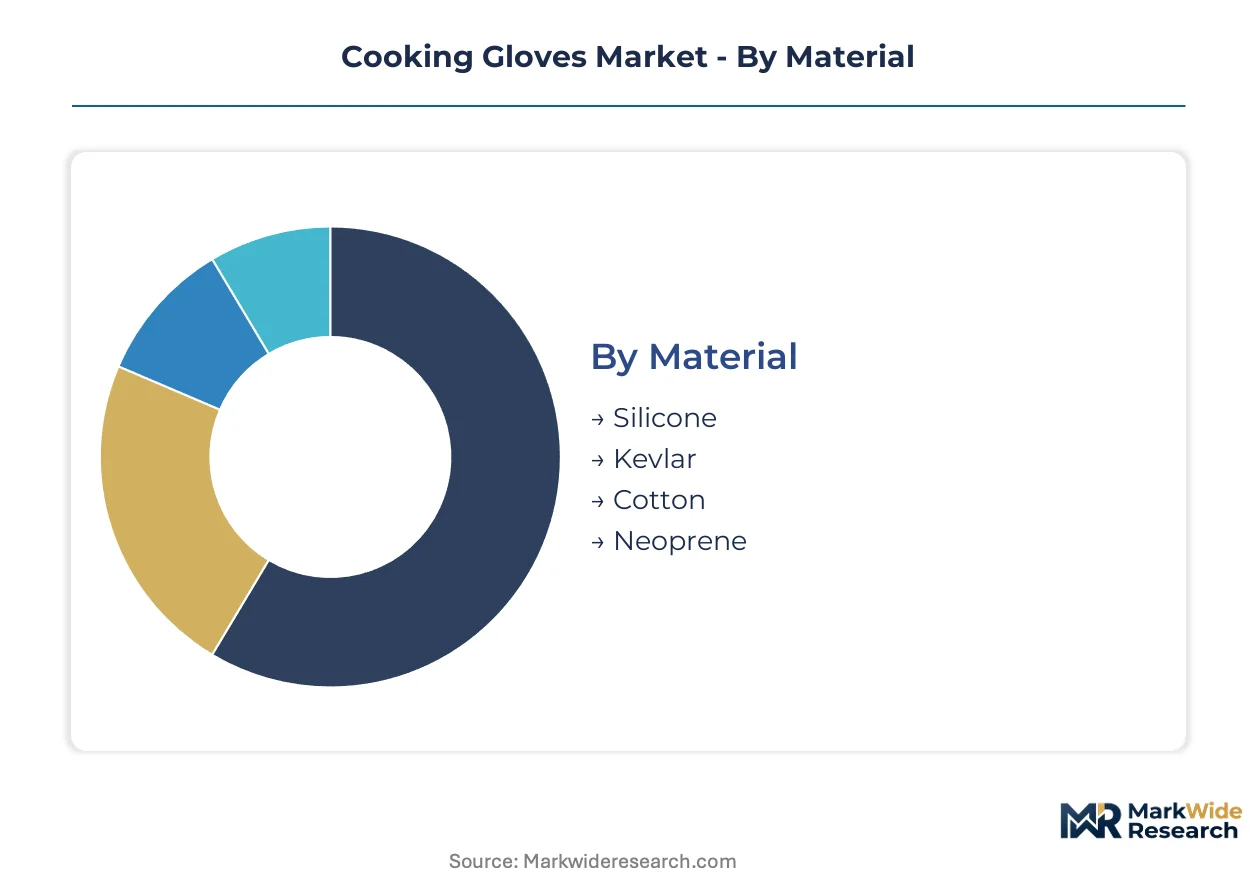
Cooking gloves segment across material science, protective function, dimensional fit, and end-use environment. Each axis shapes procurement priorities differently: commercial buyers prioritize ANSI certification and thermal ratings, while home-kitchen channels emphasize dishwasher durability and grip ergonomics.
Material:
Material selection determines thermal ceiling, cut protection, and compliance eligibility for target channels.
- Silicone:Platinum-cured formulations withstand sustained heat exposure up to 450°F while maintaining flexibility. Michelin-starred kitchens in California and Tokyo specify silicone-Kevlar laminates for combined protection. Dishwasher-safe properties drive repeat purchase cycles in premium home-chef segments.
- Kevlar:Aramid fiber reinforcement delivers ANSI Level A4-A9 cut resistance required by commercial insurers for professional kitchen liability coverage. Bavarian restaurant groups mandate EFSA-compliant Kevlar blends for high-throughput prep stations handling mandoline slicers and meat saws.
- Cotton:Quilted cotton layers provide baseline thermal insulation at entry price points. Legacy inventory still circulates in institutional cafeterias with limited procurement budgets.
- Neoprene:Synthetic rubber compounds offer chemical resistance and waterproofing for dishwashing and seafood processing tasks. REACH Annex XVII restrictions on PFAS coatings are forcing reformulation of neoprene barrier treatments.
Silicone leads on scale; Kevlar leads on momentum.
Functionality:
Protective specifications align with kitchen task hazards and insurer mandates.
- Heat Resistance:Thermal-rating documentation now required under OSHA guidelines for foodservice establishments. Replacement cycles accelerate as legacy cotton inventory phases out.
- Waterproof:Liquid barrier properties essential for sous-vide handling and ice bath operations. EFSA migration testing validates coating safety for European procurement.
- Non-Slip:Textured palm patterns engineered for wet protein handling and cast-iron maneuvering. Home-chef channels favor geometric grip innovations visible in cooking media.
- Cut Resistant:ANSI certification determines distributor eligibility as commercial liability policies tighten. Foodservice management companies bundle cut-resistant gloves with uniform contracts.
Heat resistance commands volume share; cut resistance is climbing the fastest.
Size:
Dimensional coverage spans hand anthropometry across gender and occupational demographics.
- Small:Targets foodservice workers with smaller hand profiles and adolescent culinary trainees. Limited SKU availability constrains penetration.
- Medium:Standard procurement default for mixed-gender kitchen staffs. Distributors maintain deepest inventory at this dimension.
- Large:Dominant specification for male-majority professional kitchens. Most frequent size in commercial replenishment orders.
- Extra Large:Serves institutional food production and butcher operations with above-average hand dimensions. Lower turnover due to smaller addressable population.
Medium and Large dominate procurement volume; Small is gaining share fastest as workforce demographics diversify.
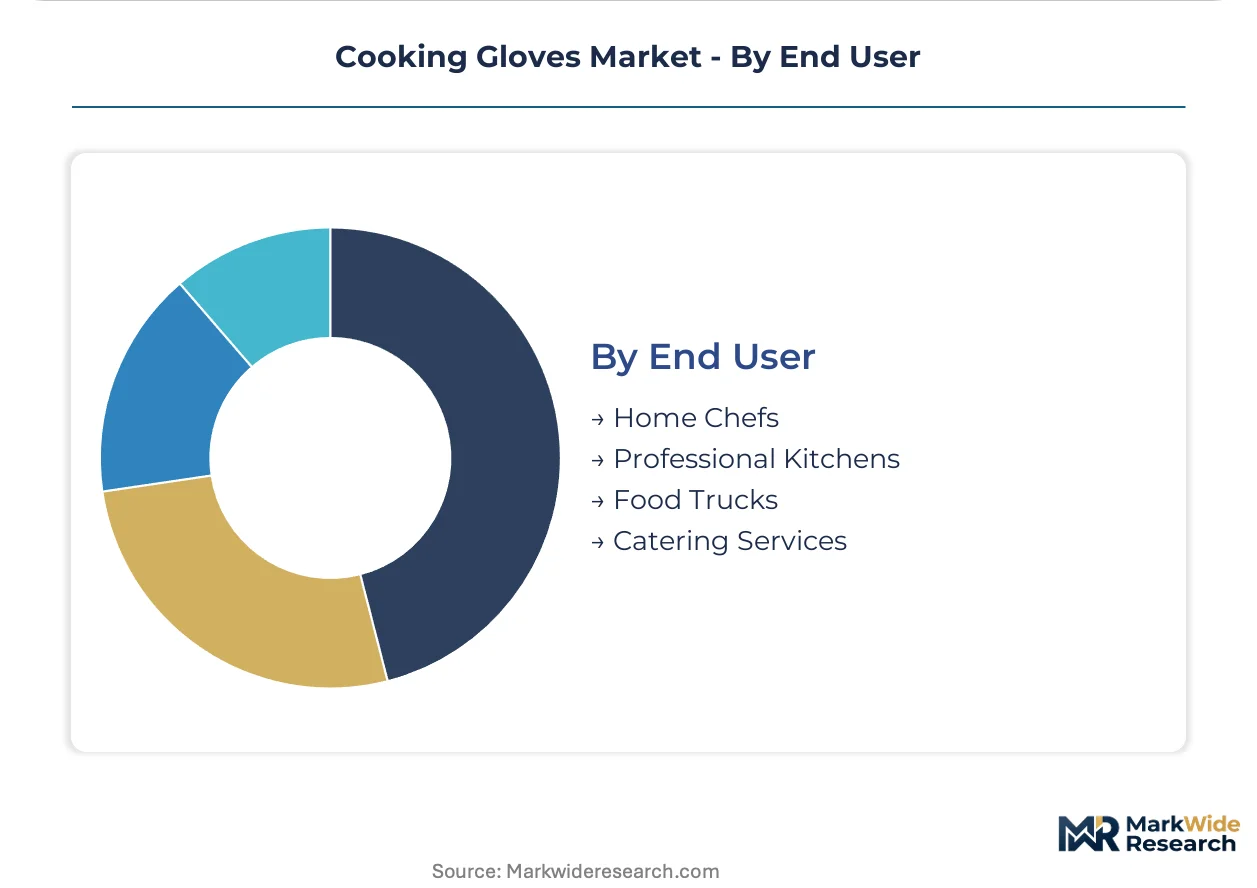
End User:
Channel-specific requirements separate premium specification from price-sensitive volume.
- Home Chefs:E-commerce and specialty retail channels favor aesthetic packaging and cooking-show visibility. Dishwasher-safe silicone with grip-pattern innovation builds brand loyalty.
- Professional Kitchens:Three-star restaurants and hotel chains demand dual-certified heat and cut protection. German and Japanese procurement offices consolidate supplier relationships around compliant manufacturers.
- Food Trucks:Mobile operations prioritize compact storage and multi-function gloves due to space constraints. Price sensitivity exceeds stationary foodservice.
- Catering Services:High-turnover temporary staffing drives disposable and low-unit-cost procurement. Event-volume volatility complicates inventory planning.
Professional kitchens anchor revenue concentration; home chefs represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement offices demand EFSA-compliant Kevlar blends at price premiums that Malaysian nitrile specialists struggle to match, while Chinese state-backed restaurant consolidation in Shanghai and Guangzhou creates volume opportunities for heat-resistant glove suppliers with GB standards certification.
United States
Commercial insurers now mandate ANSI cut-level certification for foodservice liability coverage, accelerating replacement cycles for legacy cotton inventory. OSHA hand-protection guidelines require documented thermal-rating thresholds in professional kitchens. Three-star restaurants in California specify silicone-Kevlar laminates for combined heat and cut protection.
Germany
Michelin-starred restaurant density in Bavaria and Baden-Württemberg concentrates demand for premium Kevlar-reinforced gloves with EFSA food-contact compliance. REACH Annex XVII restrictions on PFAS waterproof coatings force coating chemistry reformulations, extending R&D timelines for European suppliers. Procurement offices in Berlin consolidate supplier relationships around compliant manufacturers with in-house polymer laboratories.
China
State-backed restaurant chain consolidation in Shanghai and Guangzhou creates first-mover advantage for heat-resistant glove suppliers with GB standards compliance. SAMR oversight of food-contact materials shapes import clearance requirements and domestic formulation standards. Yangtze River Delta manufacturing clusters now produce dishwasher-safe silicone variants for both domestic and export markets.
Malaysia
Rubber-glove manufacturing capacity shifts toward value-added kitchen applications after years of medical-glove dominance. Monsoon patterns and palm-oil diversion create natural rubber price volatility, compressing margin predictability for nitrile-blend manufacturers. Penang and Selangor production facilities leverage integrated supply chains to anchor heat-resistant product lines for North American distributors.
Japan
Professional kitchens in Tokyo and Osaka specify hybrid silicone-Kevlar laminates for combined protection previously requiring separate gloves. METI industrial standards and JIS certification requirements create technical barriers against uncertified imports. Kansai region foodservice management companies bundle cooking gloves with uniform and smallware contracts, squeezing standalone distributors.
Cooking Gloves Market Competitive Landscape
Malaysian producers anchor one tier through integrated nitrile supply chains and scale economies; European specialists hold premium positioning via EFSA-compliant formulations and in-house polymer laboratories. The vendor base splits between medical-glove diversifiers entering kitchen applications and purpose-built cooking-glove fabricators. Three strategic archetypes dominate: heat-resistance specialists, cut-protection engineers, and hybrid-material innovators. Competitive moves concentrate on portfolio diversification into adjacent PPE categories and geographic expansion through distributor consolidation.
Among Malaysian-based fabricators, Top Glove and Kossan Rubber Industries Bhd exemplify the medical-to-kitchen diversification archetype, leveraging captive latex and nitrile supply to compete on input cost stability. Ansell Ltd occupies a position within the European premium tier, representing specialized silicone formulation capabilities that sustain positioning in professional kitchens demanding EFSA compliance. These three anchors illustrate how procurement consolidation around certified suppliers favors manufacturers with backward integration into raw-material production and in-house testing infrastructure.
| Leading Market Players |
|---|
| Superior Glove |
| RFB Gloves |
| Top Glove |
| Glovables |
| Cello World |
| Ansell Ltd |
| Kossan Rubber Industries Bhd |
| Globus Group |
| 3M |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal circularity requirements now gate both qualified supply and premium-tier pricing access, as recyclable silicone recovery programs receive preferential procurement scoring in public-sector catering contracts across France and Italy while forcing non-compliant manufacturers toward commodity price tiers.
Pricing Analysis
Capacity additions in Malaysia are reshaping price floors for nitrile-blend cooking gloves, compressing margin predictability for manufacturers tethered to natural rubber input volatility. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant Kevlar laminates from uncertified Asian imports. Price differentiation hinges on ANSI certification grade and volume scale. Pricing pressure stems from low-cost silicone imports lacking CE markings. Home-chef channels exhibit highest price sensitivity; three-star restaurant procurement offices show least.
Supply Chain Analysis
Platinum-cured silicone feedstock rests on Yangtze River Delta manufacturing clusters and Penang production facilities, with aramid fiber reinforcement drawing from specialty chemical producers in Germany and Japan. Raw material dependencies span Malaysian natural rubber latex, Chinese silicone precursors, and European Kevlar fiber. Single-source vulnerability concentrates in PFAS-free waterproof coating formulations facing REACH Annex XVII restrictions. Distribution runs through foodservice management companies bundling gloves with uniform contracts and direct-to-chef subscription channels bypassing traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
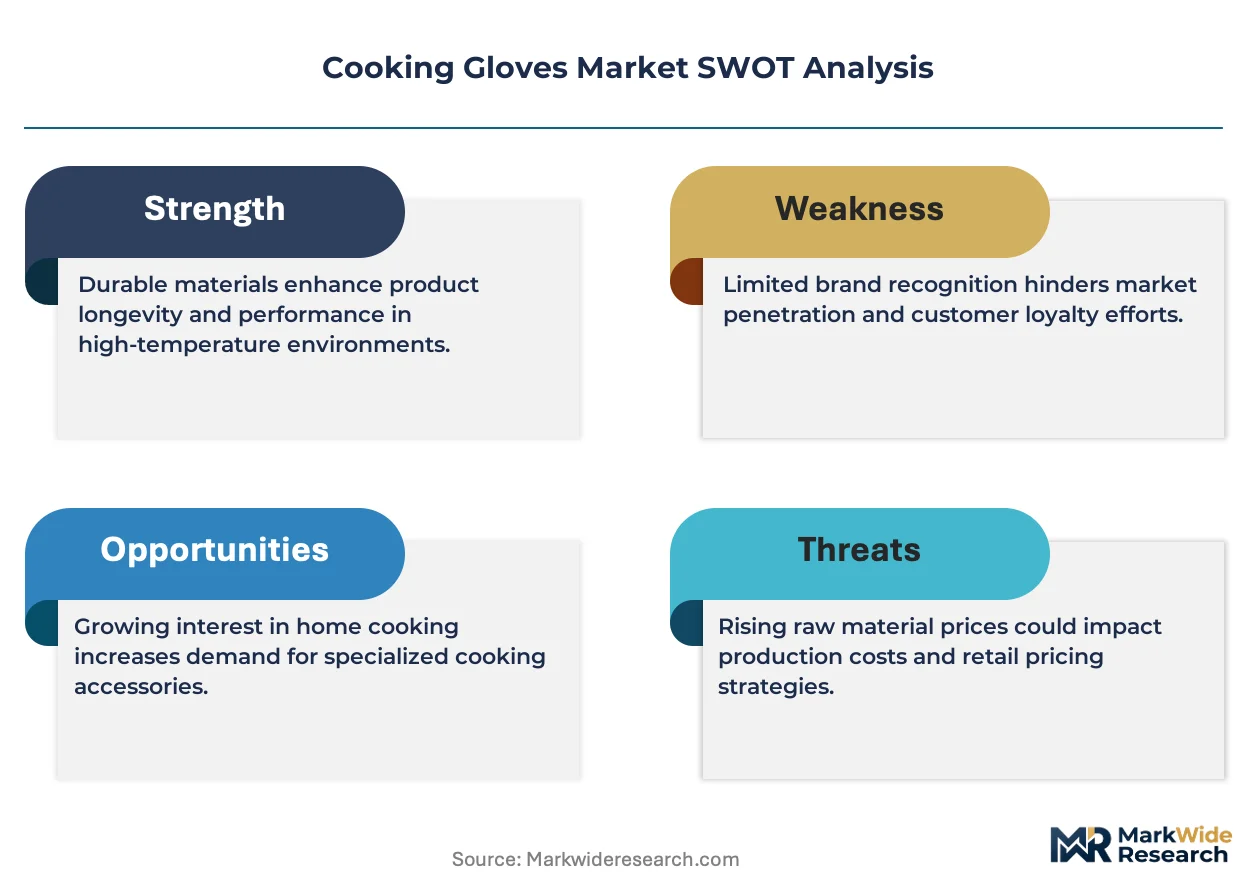
This market represents a late-cycle quality story as commercial insurer mandates for ANSI cut-level certification displace uncertified inventory and consolidate procurement around compliant manufacturers with in-house testing infrastructure.
For Market Incumbents: Anchor premium positioning through captive nitrile supply chains and EFSA-compliant formulation capabilities. Defensive consolidation moves center on acquiring distressed distributors with established three-star restaurant relationships and investing in hybrid silicone-Kevlar laminate R&D before certification backlogs extend. The threat of emerging Asian manufacturers with GB standards compliance and state-backed restaurant consolidation in China demands preemptive capacity positioning.
For New Entrants and Emerging Players: Launch via direct-to-chef subscription channels targeting high-turnover professional kitchens in fast-casual chain rollouts where standardized PPE specifications create first-mover advantage. White-space targets include China's commercial-kitchen modernization in Shanghai and Guangzhou, and food truck segments prioritizing compact storage multi-function gloves. The most penetrable segment combines dishwasher-safe silicone with cooking-show visibility for premium home-chef channels.
For Investors and Strategic Acquirers: Roll-up economics work for medical-glove diversifiers with integrated latex supply chains because procurement consolidation favors manufacturers with backward integration into raw-material production and in-house polymer laboratories. Long-term viability framing centers on five-to-ten year windows where regulatory compliance barriers deepen. Acquisition target archetype: Malaysian nitrile specialists with heat-resistant product line anchors for North American distributors. The signal to watch is pending OSHA updates to heat-resistance testing protocols reshaping competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Production | Yangtze River Delta clusters secure supply stability against import clearance volatility under SAMR oversight. |
| ANSI Cut-Level Certification Investment | Commercial insurer mandates in the United States displace uncertified SKUs and consolidate distributor relationships. |
| Direct-to-Chef Subscription Channel Launch | Monthly replenishment models bypass foodservice distributors and capture recurring revenue from high-turnover kitchens. |
| EFSA-Compliant Kevlar Blend Development | German procurement offices in Bavaria concentrate demand around compliant manufacturers with in-house polymer laboratories. |
| Recyclable Silicone Recovery Program | EU Green Deal circularity incentives receive preferential scoring in French and Italian public-sector catering contracts. |
Research Methodology
Direct dialogue with foodservice procurement directors, commercial insurance underwriters, restaurant group supply chain managers, and polymer R&D directors combined with secondary validation from FDA indirect food-additive filings, EFSA migration testing databases, OSHA hand-protection guideline updates, and customs trade data. Bottom-up segmentation modeling triangulated against top-down market sizing across material science, protective function, dimensional fit, and end-use environment dimensions.
Projected value outputs derive from a structured analytical framework spanning the analysis window, with segmentation dimensions covering silicone-Kevlar-cotton-neoprene material tiers, heat-cut-waterproof-non-slip functionality, small-medium-large-extra large dimensional coverage, and home chef-professional kitchen-food truck-catering service end-use channels. CAGRs emerge from elasticity modeling against professional kitchen expansion rates, insurer mandate adoption curves, and raw material input cost trajectories. Industry-specific forecast inputs include Malaysian natural rubber price volatility indices and REACH Annex XVII reformulation cost estimates.
Several conditions sit outside the modeled scope, including sudden monsoon disruptions to latex harvesting, unilateral tariff adjustments on Chinese silicone imports, and accelerated PFAS restriction timelines beyond current ECHA consultation periods. Forecasts reflect documented assumptions about certification backlog durations and procurement consolidation velocity. A small set of named triggers warrants ongoing watch: OSHA heat-resistance protocol updates, SAMR food-contact material enforcement shifts, and commercial insurer liability policy rewrite cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Personal Flotation Devices Market
Protective Gear
Pet Control Devices Market
Protective Gear
Helmets Market
Protective Gear
Tactical Boots Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Fluorescent Reflective Vest Market
Protective Gear
Military Boots Market
Protective Gear
Work Shoes Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Europe Lanyards Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Diving Suits Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Battery Heated Gloves Market