
 Disposable Cutlery Market | 2026-2036
Disposable Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Cutlery Market Analysis
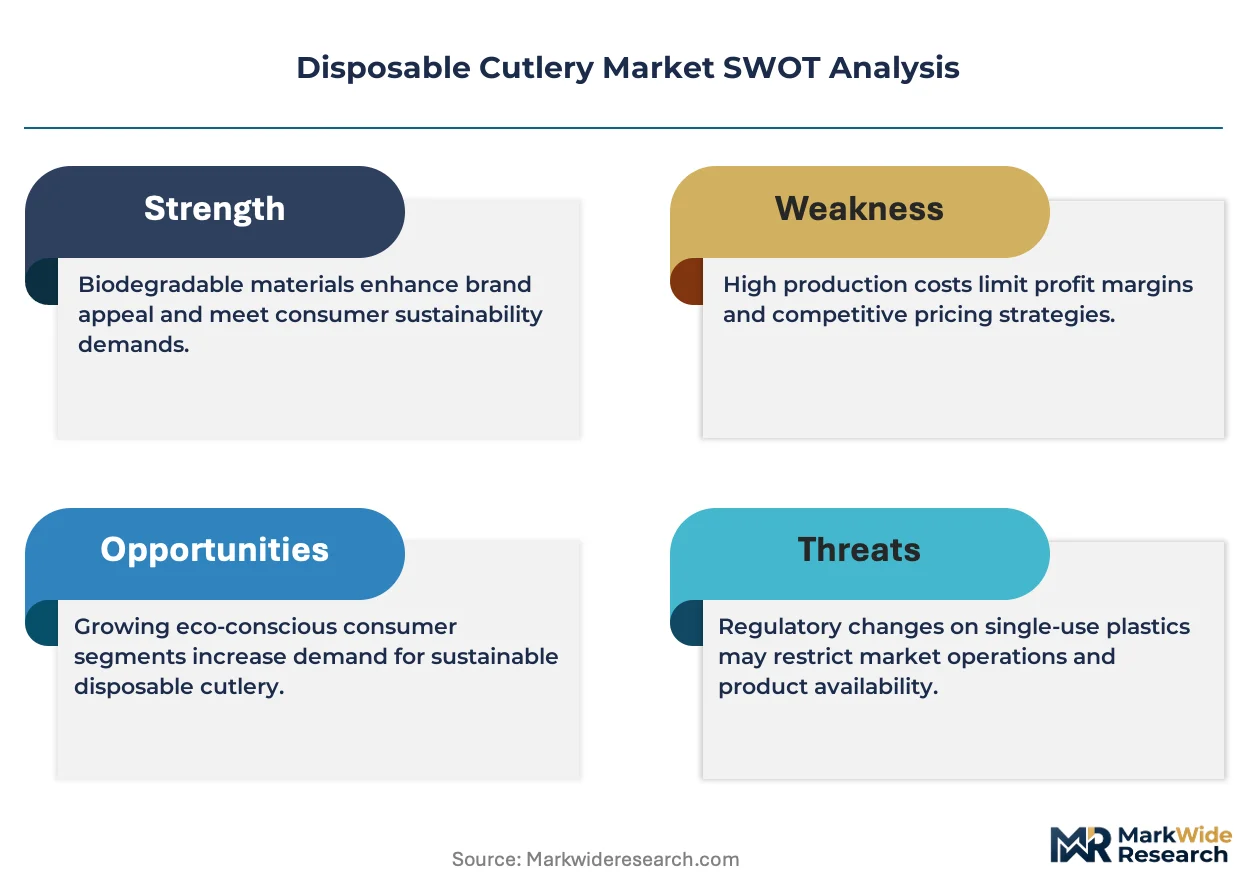
The EU Single-Use Plastics Directive is shifting procurement priorities across European foodservice channels, compelling distributors to source alternatives to conventional polystyrene cutlery. Huhtamäki leverages its molded fiber manufacturing footprint to supply major quick-service chains with compostable spoon and fork lines. Pactiv Evergreen anchors North American production through integrated resin-to-finished-goods operations across multiple US states. Novolex competes aggressively on private-label biodegradable formats for regional restaurant distributors.
Disposable cutlery encompasses single-use eating implements manufactured from thermoformed plastics, pressed wood fibers, molded bagasse, or compostable polymers, typically measuring 150-180mm in length and designed to withstand temperatures up to 85°C for hot food applications. The primary commercial purpose centers on hygienic, cost-efficient utensil provision in away-from-home eating environments where washing infrastructure is absent or impractical. Wood and biodegradable materials represent the fastest-expanding material type segment as foodservice buyers phase out petroleum-based options under buyer-side sustainability mandates. Takeaway application channels command disproportionate volume share due to sustained off-premise dining behavior, while direct sales distribution channels capture the most favorable margin pools through long-term institutional contracts.
The US Food and Drug Administration governs food-contact substance compliance for all disposable cutlery sold in American commerce, while the European Chemicals Agency enforces REACH restrictions on additives in plastic foodservice articles. California's state-level single-use plastics regulations and Germany's national packaging law are tightening compliance thresholds, effectively raising barriers for non-certified suppliers. Stakeholders must monitor evolving compostability certification requirements across multiple jurisdictions to preserve market access.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for petroleum-based cutlery while accelerating capital flows into molded fiber and compostable polymer production lines across European manufacturing clusters.
Growth Catalysts
- REACH additive restrictions:ECHA enforcement on plasticizers in food-contact articles is compelling quick-service chains to certify alternative material streams before 2026 compliance deadlines.
- Bagasse molding advances:Steam-pressed sugarcane fiber technology now achieves structural parity with polystyrene at equivalent unit economics for hot-food applications.
- California SB 54 implementation:Extended producer responsibility mandates are forcing national distributors to pre-qualify compostable suppliers for multi-state contract renewals.
Market Restraints
- Resin price volatility:Polypropylene and PLA feedstock costs fluctuate with crude oil and corn futures, compressing margin predictability for converters without backward integration into raw material sourcing.
- Molded fiber capacity concentration:European molded fiber utensil production clusters heavily in Finland and Sweden, creating geographic supply risk for southern European distributors.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse in eastern Germany and rural France, limiting end-of-life value proposition for certified biodegradable formats.
Strategic Opportunities
- India foodservice penetration:Quick-service restaurant expansion in Mumbai and Bangalore corridors lacks established cutlery supply partnerships, creating first-mover positioning for compostable-format entrants.
- Cloud kitchen specialization:Delivery-native restaurant operators require utensil kits optimized for 30-45 minute transport durability, a specification niche distinct from dine-in or traditional takeaway.
- German packaging law incentives:LUCID registration and recyclability labeling requirements favor suppliers with pre-certified circular material streams in institutional catering tenders.
Industry Challenges
- Compostability certification latency:TÜV Austria and BPI multi-jurisdiction approval timelines extend 14-18 months, delaying product launches beyond annual contract negotiation windows.
- Hot-food performance engineering:Maintaining structural integrity above 85°C without petroleum-based additives requires iterative material science investment that mid-scale converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Cutlery Market |
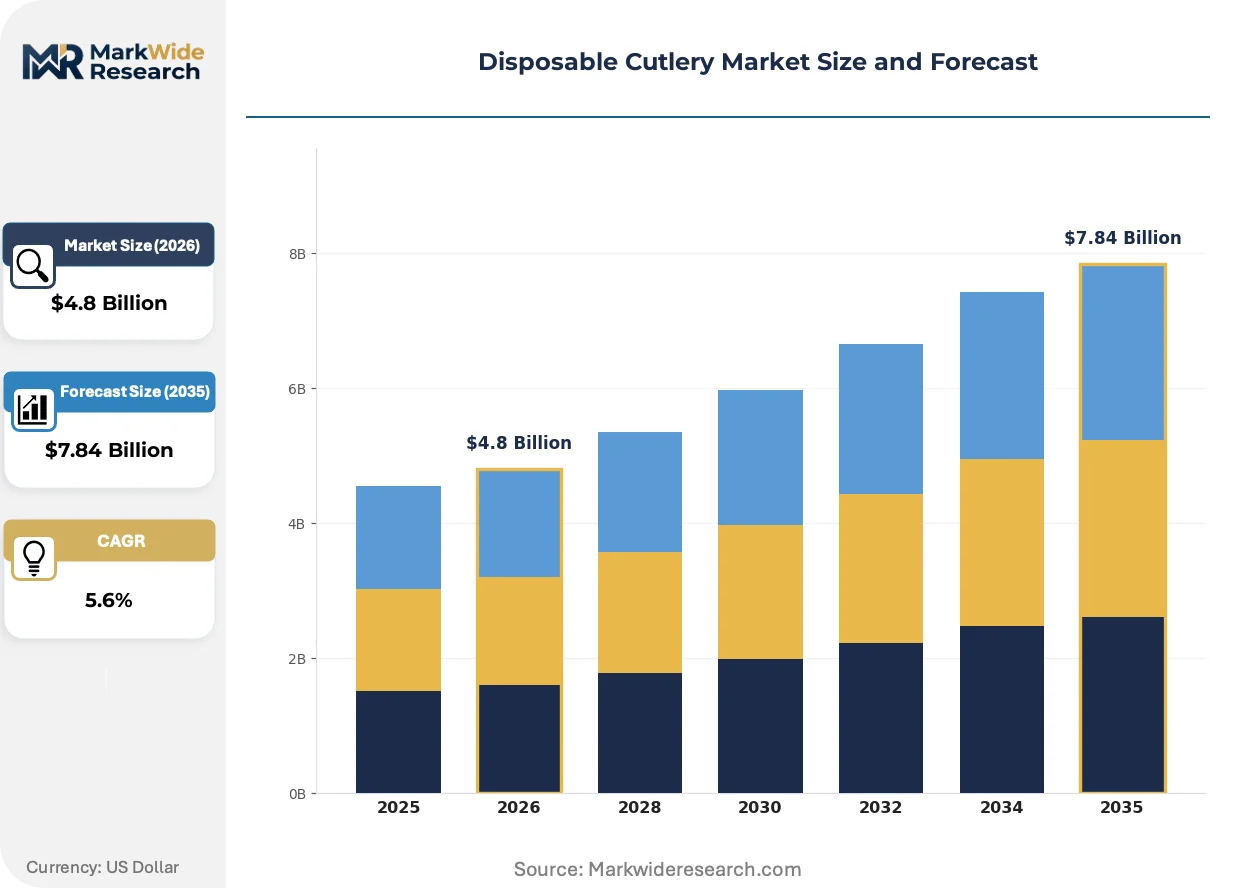
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood, Biodegradable, Metal Application: Food Service, Event Catering, Household Use, Takeaway End User: Restaurants, Cafes, Food Trucks, Households Distribution Channel: Retail Stores, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Huhtamäki, Dart Container Corporation, Pactiv Evergreen, Genpak, Novolex, Georgia-Pacific, BioPak, Vegware, Eco-Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Cutlery Market Emerging Trajectories
Material substitution is accelerating beyond simple polymer swaps toward engineered fiber architectures that satisfy both performance specifications and emerging compostability mandates.
Molded fiber utensil technology is overtaking conventional thermoformed polystyrene in quick-service procurement specifications. Chains with 500-plus unit footprints now mandate fiber-based defaults for new market entries. This transition is compressing polystyrene converter margins while expanding dedicated fiber molding capacity announcements across Nordic and North American production zones.
California's SB 54 extended producer responsibility framework is restructuring distributor-supplier contracting. Retailers and foodservice operators must now document source reduction and recyclability compliance across their private-label cutlery assortments. Multi-state distributors are responding by consolidating vendor panels to pre-qualified suppliers with existing LUCID-equivalent documentation systems.
Cloud kitchen operators are unbundling utensil inclusion from default meal packaging. Delivery-platform data shows 30-40% of urban consumers declining cutlery when explicit opt-out mechanisms exist. This behavioral shift is forcing format innovation toward compact, kit-optimized designs that reduce shipping cube without sacrificing functionality for the subset requesting utensils.
Disposable Cutlery Market Segmentation
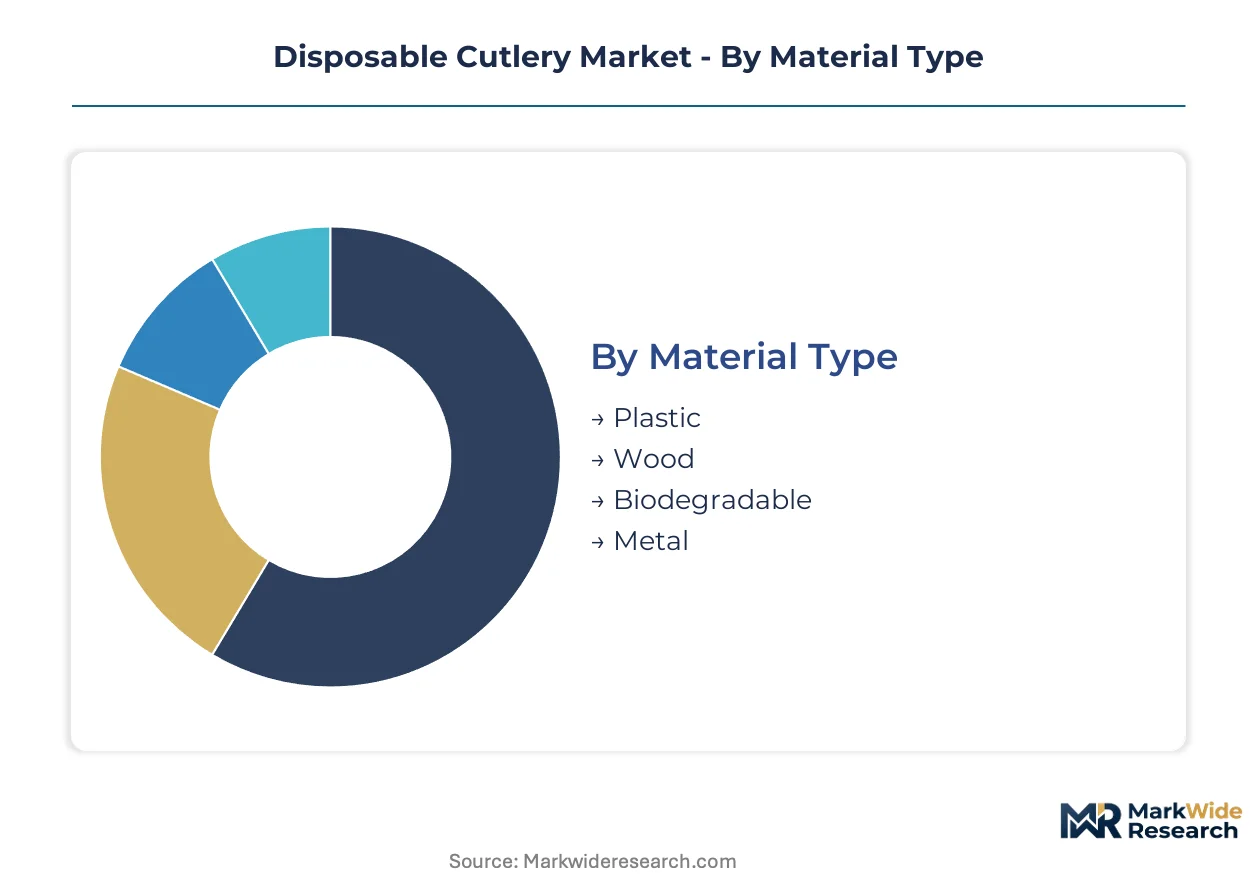
Material specifications drive procurement decisions in disposable cutlery as foodservice buyers balance structural performance against emerging compostability mandates. Segmentation reveals how sustainability transitions are reshaping supplier portfolios across manufacturing tiers and distribution channels.
Material Type:
Cost tiers separate commodity converters from certified sustainable suppliers in procurement specifications.
- Plastic:Thermoformed polystyrene and polypropylene utensils dominate legacy quick-service contracts due to sub-cent unit economics and established molding infrastructure. Demand is compressing in Germany and California as ECHA additive restrictions and SB 54 compliance deadlines force material transitions before contract renewals.
- Biodegradable:PLA and PHA polymer formulations achieve industrial compostability certification while maintaining temperature resistance to 85°C for hot-food applications. Procurement is concentrating among national distributors serving multi-state operators with documented LUCID-equivalent registration systems.
- Wood:Birch and bamboo pressed-fiber utensils satisfy EU Single-Use Plastics Directive exemptions without composting infrastructure dependency.
- Metal:Lightweight aluminum and stainless steel formats serve reusable-credit programs in Nordic institutional catering.
Volume sits with Plastic; growth tilts toward Biodegradable.
Application:
End-use environments dictate durability specifications and kit configuration requirements.
- Takeaway:Delivery-optimized utensil kits require 30-45 minute transport durability with compact shipping cube for platform logistics. Cloud kitchen operators in Mumbai and Bangalore corridors are unbundling cutlery inclusion from default packaging as opt-out rates reach 30-40% among urban consumers.
- Food Service:Quick-service chains with 500-plus unit footprints mandate molded fiber defaults for new market entries, compressing polystyrene converter margins while expanding Nordic and North American fiber molding capacity.
- Event Catering:Single-batch procurement favors private-label biodegradable formats for stadium and festival operators with visible sustainability commitments.
- Household Use:Retail-packaged assortments compete on price-per-piece against durable alternatives in mass-market channels.
Takeaway commands volume concentration; Food Service offers the steepest expansion trajectory as chain mandates proliferate.
End User:
Customer scale determines contract structure and supplier qualification requirements.
- Restaurants:National quick-service chains anchor procurement volume through integrated distributor relationships with multi-year sustainability roadmaps.
- Cafes:Independent coffeehouse networks favor compostable spoon and fork lines with visible fiber texture for brand differentiation.
- Food Trucks:Mobile operators prioritize kit-optimized designs with minimal storage footprint and weather-resistant packaging.
- Households:Occasional-use buyers drive retail channel assortment breadth without volume concentration.
Restaurants consolidate purchasing power; Cafes represent the most price-insensitive segment for certified sustainable formats.
Distribution Channel:
Channel selection locks in margin structure and customer access patterns.
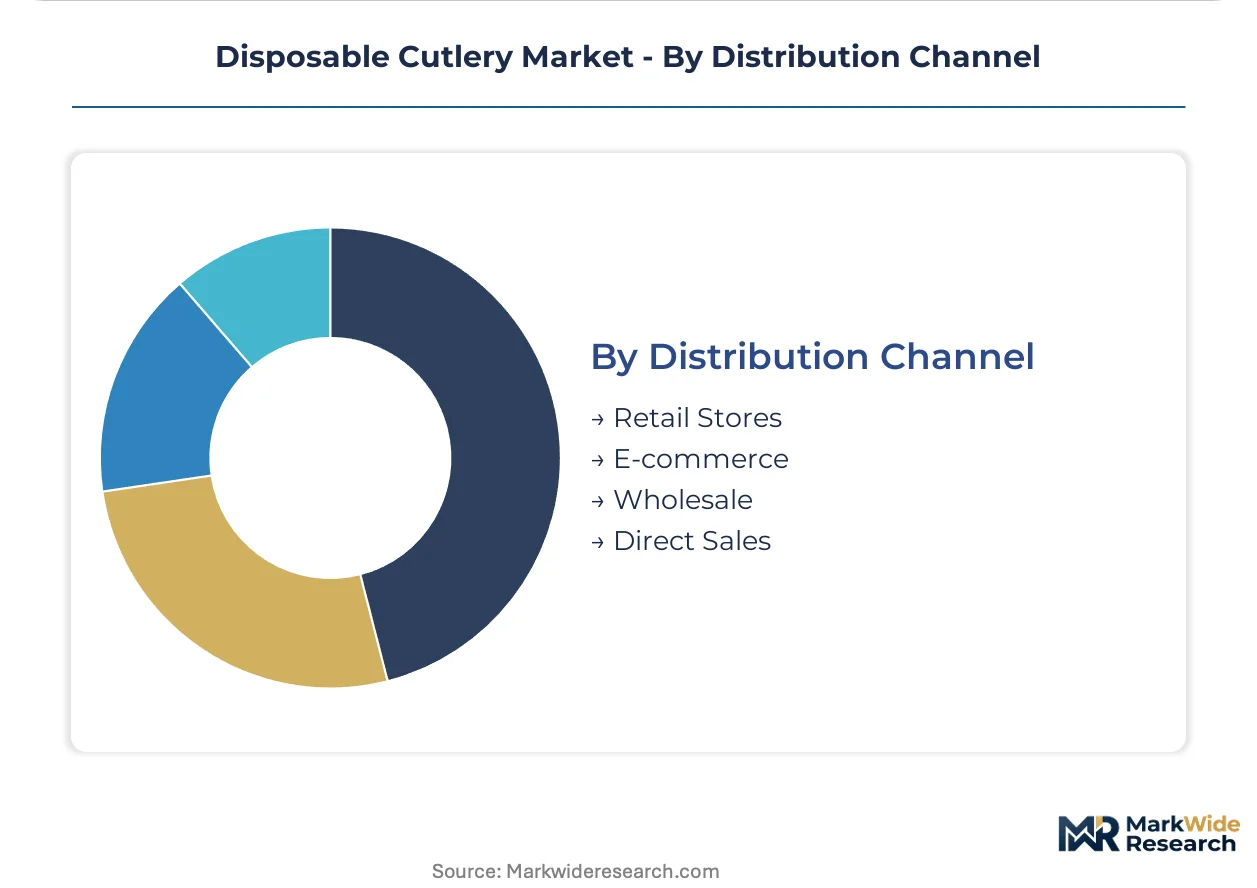
- Direct Sales:Long-term institutional contracts with pre-qualified compostable suppliers capture favorable margin pools through multi-year foodservice agreements with documented REACH and FDA compliance.
- Wholesale:Regional restaurant distributors compete aggressively on private-label biodegradable formats with consolidated vendor panels for California SB 54 compliance.
- E-commerce:Platform-native brands bypass traditional distribution through subscription and bulk-purchase models for cloud kitchen and small-format restaurant procurement.
- Retail Stores:Mass-market channels serve household demand with price-competitive plastic and wood assortments without certification premiums.
Direct Sales secures margin leadership; E-commerce is climbing the fastest as procurement digitization accelerates among independent operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland's Lahti-Kouvola industrial corridor anchors molded fiber production capacity for European quick-service chains transitioning from petroleum-based formats. This Nordic cluster supplies compostable utensil lines to distributors across Germany, France, and the Netherlands under tightening EU Single-Use Plastics Directive timelines.
United States
California's SB 54 extended producer responsibility mandates are restructuring national distributor contracting patterns. The FDA governs food-contact substance compliance for all disposable cutlery sold in American commerce. Midwestern manufacturing zones in Illinois and Ohio host integrated resin-to-finished-goods operations serving multi-state quick-service chains.
Germany
ECHA enforcement on REACH additive restrictions is compelling quick-service chains to certify alternative material streams before compliance deadlines. The national packaging law tightens LUCID registration and recyclability labeling requirements for institutional catering tenders. Western industrial regions around Cologne and Düsseldorf concentrate biodegradable converter capacity for Central European distribution.
India
Quick-service restaurant expansion in Mumbai and Bangalore corridors lacks established cutlery supply partnerships, creating positioning opportunities for compostable-format entrants. FSSAI regulates food-contact materials for domestic and imported disposable utensils. Gujarat's chemical manufacturing belt is attracting PLA polymer investments to serve anticipated foodservice procurement growth.
Sweden
Nordic institutional catering mandates favor reusable-credit programs and certified compostable formats over conventional plastics. REACH restrictions apply to all plastic foodservice articles imported or manufactured domestically. Stockholm-Uppsala manufacturing clusters export molded fiber technology and production equipment to converters in Germany and the UK.
Brazil
ANVISA governs food-contact substance safety for disposable cutlery sold in Brazilian commerce. São Paulo state's foodservice distribution networks are beginning to specify biodegradable alternatives for national quick-service chain contracts. Southeastern industrial zones around Campinas are developing bagasse molding capabilities to supply Latin American markets.
Disposable Cutlery Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and material technology dimensions. The vendor base separates into integrated resin-to-finished-goods operators, specialized molded fiber converters, and private-label biodegradable format suppliers. Three strategic archetypes dominate: backward-integrated polymer producers with captive raw material sourcing, Nordic fiber technology specialists with equipment export capabilities, and regional distributors consolidating vendor panels for multi-state compliance contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for post-2025 material transition deadlines.
Among the named participants, Huhtamäki and Pactiv Evergreen exemplify divergent geographic and integration strategies. Huhtamäki represents the Nordic fiber technology specialist archetype with established European production footprints. Pactiv Evergreen anchors North American positioning through multi-state manufacturing presence. Novolex occupies a position within the private-label tier competing on consolidated supplier qualification systems for California SB 54 compliance. These three illustrate how certification documentation and geographic coverage separate premium-tier positioning from commodity-margin competition.
| Leading Market Players |
|---|
| Huhtamäki |
| Dart Container Corporation |
| Pactiv Evergreen |
| Genpak |
| Novolex |
| Georgia-Pacific |
| BioPak |
| Vegware |
| Eco-Products |
| Others |
Supply Flow & Price Mechanics
Molded fiber tooling engineers concentrated in Finland's Lahti-Kouvola corridor command wage premiums that widen spreads between certified compostable and commodity plastic tiers. Labor-cost differentials between Nordic specialist clusters and Asian resin-processing zones translate into persistent pricing stratification across REACH-compliant and conventional supply alternatives.
Pricing Analysis
Outcome-based pricing tied to compostability certification throughput anchors premium tiers in institutional foodservice contracting. Three-tier pricing structure across certified compostable, transitional biodegradable, and commodity polystyrene levels separates buyers by documentation requirements and volume scale. Cost compression in conventional plastic tiers is intensifying because ECHA additive restrictions are forcing rapid material transitions before contract renewals. National quick-service chains exhibit lowest price sensitivity due to sustainability mandate compliance costs, while independent cafes and food trucks demonstrate highest elasticity to unit-cost fluctuations.
Supply Chain Analysis
Reverse-logistics flows for certified compostable formats remain underdeveloped, with industrial composting facility coverage gaps in eastern Germany and rural France limiting end-of-life value realization. Raw material sourcing draws from sugarcane bagasse plantations in Brazil, birch fiber forests in Nordic regions, and corn-derived PLA polymer production in the United States. Single-source vulnerability concentrates in European molded fiber capacity clustered in Finland and Sweden. Distribution runs through national foodservice distributors with pre-qualified supplier panels for multi-state compliance coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable cutlery market reads as a cost-of-compliance story where EU Single-Use Plastics Directive certification requirements erect barrier-to-entry moats favoring pre-qualified suppliers with documented LUCID-equivalent systems.
For Market Incumbents: Cement fiber molding capacity advantages in Nordic production zones before southern European distributors diversify sourcing. Expand backward integration into bagasse raw material streams to offset resin price volatility compressing converter margins. Prioritize TÜV Austria and BPI certification maintenance to defend against emerging Asian compostable-format entrants. For New Entrants and Emerging Players: Cloud kitchen operators in Mumbai and Bangalore corridors represent the most penetrable buyer archetype given absent established supply partnerships and unmet demand for kit-optimized transport-durable designs. Target delivery-native restaurant procurement through e-commerce platform integration rather than traditional distributor channel penetration. Lead with compact utensil configurations that reduce shipping cube for platform logistics economics. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic fiber technology specialists given EU regulatory deadlines accelerating procurement shifts away from petroleum-based formats. Acquisition focus should center on converters with existing multi-jurisdiction compostability certification and equipment export capabilities. Monitor industrial composting facility buildout rates in Germany and France as inflection indicator for certified biodegradable format demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Nordic fiber molding additions capture share as quick-service chains mandate compostable defaults. |
| Backward Integration | Captive bagasse sourcing insulates margins from corn futures volatility affecting PLA feedstock. |
| Certification Investment | TÜV Austria and BPI multi-jurisdiction approval preserves access to California SB 54 contract pools. |
| Channel Consolidation | Pre-qualified vendor panels strengthen positioning in national distributor RFP processes. |
| Geographic Expansion | India foodservice penetration exploits supply partnership gaps in Mumbai and Bangalore corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this disposable cutlery market assessment. Primary interviews with foodservice procurement directors, sustainability compliance officers at quick-service chains, molded fiber plant managers, and national distributor category buyers combined with secondary validation from FDA food-contact substance databases, ECHA REACH restriction updates, and EU customs trade statistics. Bottom-up volume modeling across material type and application segments triangulated against top-down market sizing from trade association revenue aggregates.
Granularity-level modeling operated at material-technology-by-application intersections, with separate CAGRs derived for plastic, biodegradable, wood, and metal formats across takeaway, food service, event catering, and household channels. Forecast inputs incorporated EU Single-Use Plastics Directive implementation timelines, California SB 54 extended producer responsibility phase-ins, and cloud kitchen operator expansion trajectories throughout the projection horizon.
Revisions become necessary when industrial composting infrastructure buildout lags certified biodegradable supply growth, or when resin feedstock volatility exceeds modeled ranges. Forecasts reflect assumptions regarding regulatory enforcement consistency and foodservice buyer sustainability mandate adherence. Practitioners should monitor TÜV Austria and BPI certification approval timelines, ECHA additive restriction enforcement actions, and quick-service chain procurement policy announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Commercial Locker Market
Household Items
Insulated Water Bottles Market
Household Items
Canada Digital Showers Market
Household Items
Electric Shoe Polisher Market
Household Items
Dishwashing Products Market
Household Items
GCC Gas Hobs Market
Household Items
North America Glassware Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Thermos Bottle Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Range Hood Cleaning Service Market
Household Items
India Digital Showers Market
Household Items
Plastic Bathtub Market
Household Items
Umbrella Market
Household Items
Laundry Detergent Sheets Market