
 Mason Jars and Canning Supplies Market | 2026-2036
Mason Jars and Canning Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Mason Jars and Canning Supplies Market Foresight
The EU Green Deal is pivoting European glass packaging demand toward lower-carbon furnace technologies and closed-loop recycling systems. Ball Corporation leverages its North American manufacturing scale to supply volume retailers with standardized jar formats. Newell Brands sustains household penetration through multi-channel distribution of heritage canning kits. Owens-Illinois anchors industrial supply relationships with commercial food processors requiring thermal-shock-resistant containers.
Mason jars and canning supplies comprise hermetically sealable glass or plastic vessels with threaded necks, paired with metal bands and replaceable lids, engineered to achieve vacuum seals through heat-processing methods such as water-bath or pressure canning. Their primary purpose spans anaerobic food preservation, shelf-stable storage, and anaerobic fermentation control across home and commercial environments. Glass mason jars dominate margin pools due to premium positioning in retail channels, while silicone accessories represent the fastest-expanding material segment as consumers seek reusable, heat-tolerant alternatives to disposable components. Home preservation leads application volume, though commercial canning commands higher per-unit value through customized lid specifications and pallet-scale procurement.
The FDA governs food-contact surface standards for metal lids and plastisol sealing compounds under 21 CFR regulations, while the EPA monitors emissions from glass furnace operations that shape manufacturing location decisions. BIS certification requirements in India and GB standards in China add compliance layers for exporters targeting those domestic canning supply markets. Stakeholders must track evolving extended producer responsibility frameworks that could mandate post-consumer recycled content thresholds in jar glass formulations.
Market Dynamics
The EU Green Deal is compressing manufacturing location decisions for glass furnace operators, forcing capital reallocation toward lower-emission production technologies while farmhouse-to-table retail channels in North America expand shelf space for heritage-format containers.
Growth Catalysts
- EU Green Deal compliance mandates:European regulators are accelerating furnace upgrades toward closed-loop recycling systems. Manufacturers retrofitting facilities capture preferential procurement contracts from sustainability-focused retailers.
- Home preservation culture resurgence:Food security consciousness drives hobbyist adoption of water-bath and pressure canning methods. Kitchenware retailers report expanded SKU allocations for starter kits and accessory bundles.
- Silicone material substitution:Heat-tolerant reusable gaskets and bands displace single-use metal components. Consumers in premium segments prioritize lifecycle cost over upfront expenditure.
Market Restraints
- Natural gas price volatility:Glass furnace operations remain energy-intensive. Input cost swings compress margin stability for container manufacturers operating continuous-batch production.
- Single-source lid supply concentration:Two-component plastisol sealing compound production concentrates among specialty chemical suppliers. Disruption risk elevates procurement contingency costs for jar assemblers.
- Thermal shock performance ceiling:Soda-lime glass formulations face hard limits in pressure canning applications. Commercial processors requiring extended cycle durability must specify borosilicate alternatives at substantial cost premiums.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging mandates for post-consumer recycled content thresholds create first-mover advantage for operators with cullet preprocessing capabilities.
- Commercial fermentation control:Craft beverage producers and specialty food manufacturers adopt hermetic vessels for anaerobic process management. Custom lid specifications command pallet-scale procurement premiums.
- Direct-to-consumer subscription channels:Heritage canning kit bundling bypasses traditional retail slotting fee structures. Seasonal harvest cycles align with replenishment-driven revenue models.
Industry Challenges
- Certification timeline compression:BIS certification requirements in India and GB standards in China impose multi-quarter approval delays. Exporters face working capital strain from inventory staging during regulatory review.
- Legacy equipment integration friction:Automated filling lines designed for standardized jar formats require substantial retooling to accommodate heritage mouth diameters. Capital expenditure thresholds deter mid-volume processors from format diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mason Jars and Canning Supplies Market |
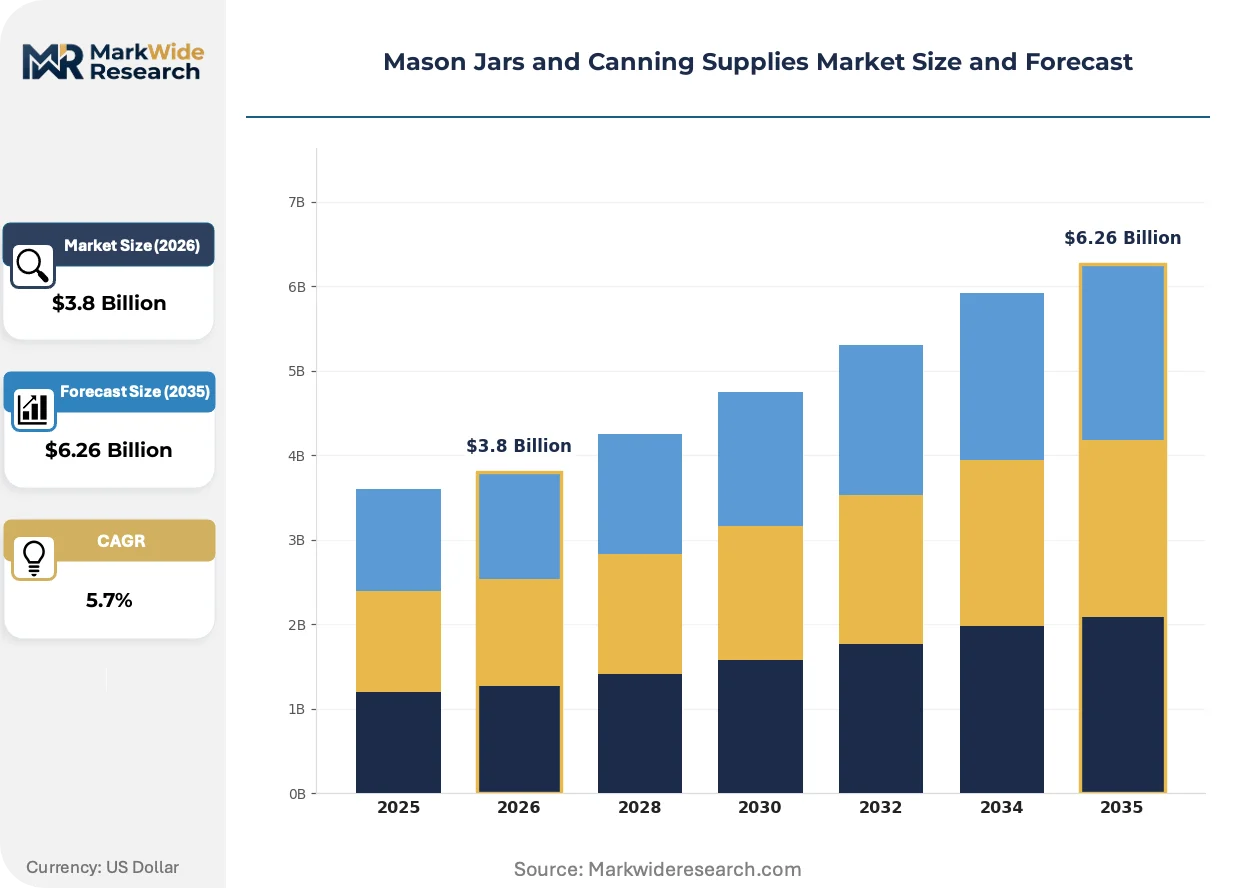
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mason Jars, Lids, Bands, Accessories Application: Home Preservation, Commercial Canning, Food Storage, DIY Projects Material: Glass, Plastic, Metal, Silicone End User: Home Canners, Restaurants, Farmers, Food Processors |
| Companies Covered | Fillmore Container, Owens-Illinois, Newell Brands, Berlin Packaging, Ardagh Group, Ball Corporation, The Jar Store, Plasdene Glass-Pak Pty Ltd, Kerr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mason Jars and Canning Supplies Market Shifts & Advancements
Material science advances and regulatory emissions frameworks are restructuring competitive position in container manufacturing, while procurement behavior shifts reward suppliers with circular economy credentials.
Borosilicate glass formulations are consolidating position in premium thermal-shock applications. Commercial food processors operating pressure canning lines specify these materials for extended cycle durability. The technology is consolidating margin pools away from commodity soda-lime suppliers unable to meet performance specifications.
REACH substance restrictions and EU Green Deal carbon accounting rules are tightening compliance scope for metal lid plastisol compounds. Manufacturers face reformulation deadlines for sealing gasket chemistries. European export-oriented suppliers are accelerating substitution trials to maintain market access.
Buyers are unbundling after-sales service from hardware procurement, treating lids and bands as consumable replenishment categories. Farmhouse-to-table retail channels and direct subscription platforms capture this disaggregation. The United States exhibits the clearest channel bifurcation between heritage-format premium positioning and standardized volume retail.
Mason Jars and Canning Supplies Market Segmentation
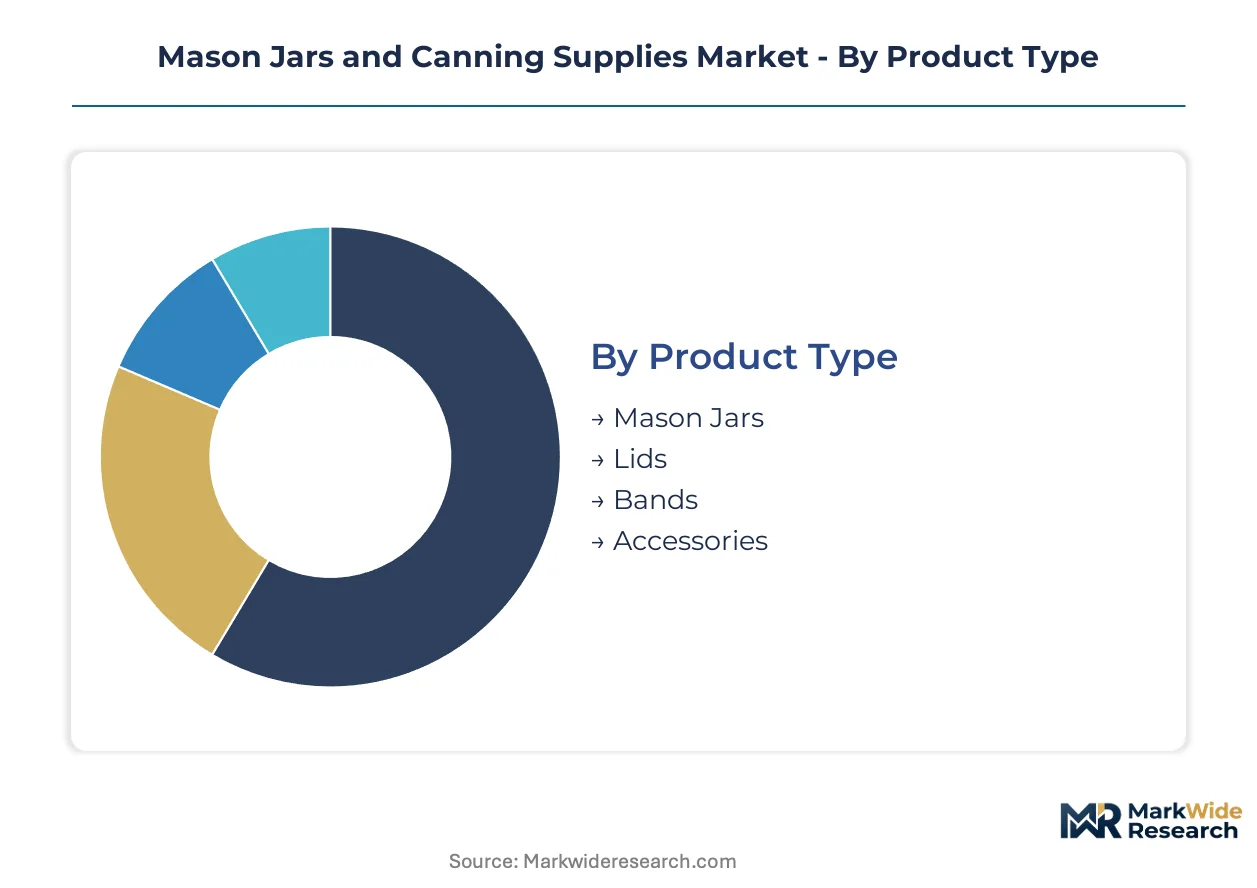
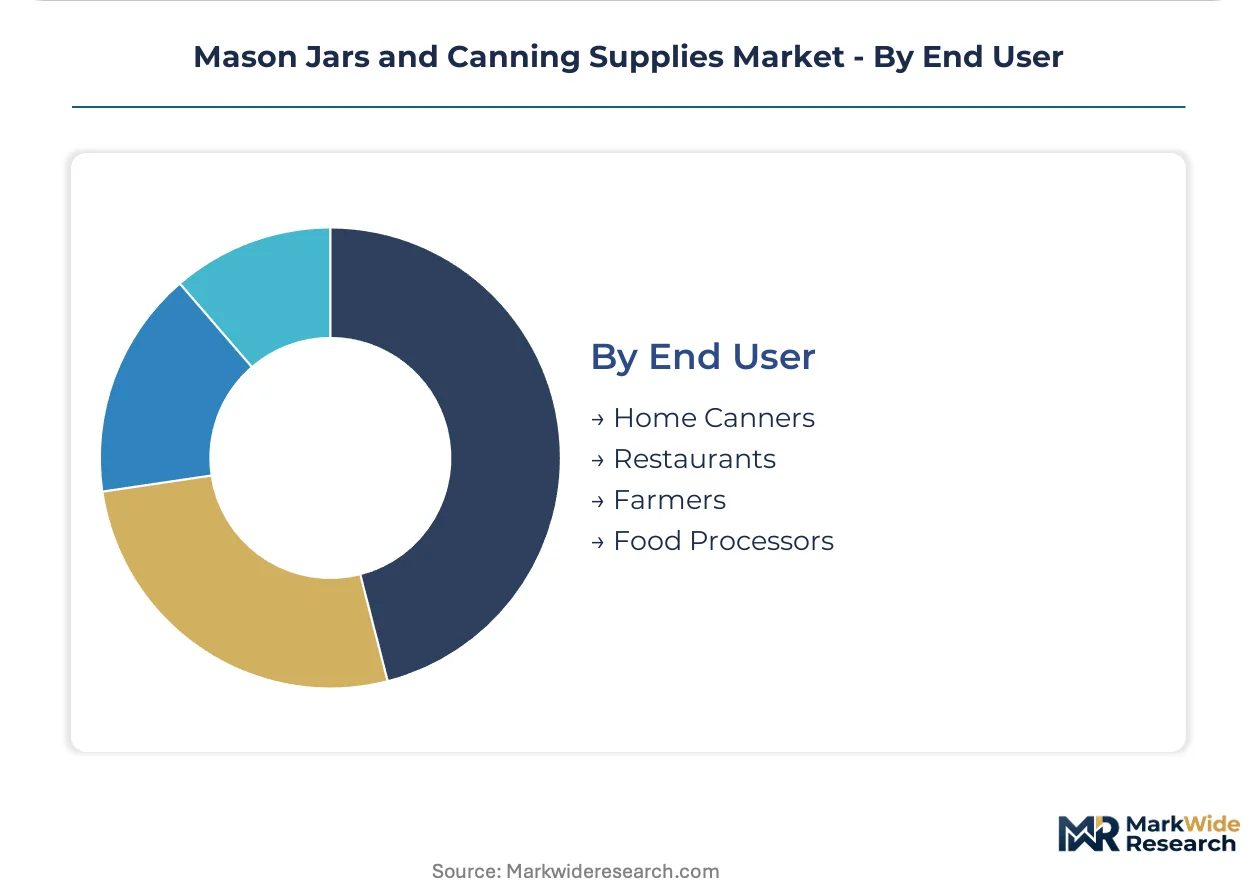
Mason jars and canning supplies fragment across four distinct dimensions that reshape procurement behavior and margin capture. Product format determines replacement frequency and bundling economics. Application context separates hobbyist volume from commercial value concentration.
Product Type:
Buyers differentiate primarily by replacement cycle length and bundling flexibility rather than unit cost alone.
- Mason Jars:Soda-lime and borosilicate glass vessels with threaded necks engineered for vacuum seal integrity. Heritage-format wide-mouth variants command shelf space in United States farmhouse-to-table retail channels as food security consciousness drives hobbyist stockpiling.
- Lids:Two-component metal discs with plastisol sealing compounds designed for single-use heat activation. Supply concentrates among specialty chemical formulators, elevating procurement contingency costs for jar assemblers facing REACH substance restrictions.
- Bands:Threaded metal rings that secure lids during thermal processing. Reusable across multiple canning cycles, bands generate lower replenishment velocity than consumable lids.
- Accessories:Funnels, jar lifters, bubble removers, and magnetic lid lifters that reduce handling contamination risk. Silicone-based tools displace metal counterparts in premium kit bundling.
Mason jars lead volumes today; accessories are gaining share fastest.
Application:
Volume concentration diverges sharply from value capture across use cases.
- Home Preservation:Water-bath and pressure canning of seasonal harvests for shelf-stable storage. United States enthusiasts drive SKU expansion in kitchenware retail as farmhouse-to-table channels allocate expanded shelf space to starter kits.
- Commercial Canning:Pallet-scale thermal processing by food manufacturers requiring customized lid specifications and thermal-shock-resistant borosilicate formulations. Per-unit values substantially exceed home-use equivalents.
- Food Storage:Dry goods containment and refrigerator storage without thermal processing. Standardized jar formats dominate this lower-margin adjacent use.
- DIY Projects:Decorative and organizational applications including candle vessels, bathroom storage, and craft containers. Heritage aesthetic positioning supports premium pricing in direct-to-consumer channels.
Home preservation leads volumes today; commercial canning is climbing the fastest.
Material:
Performance specifications and regulatory compliance separate material tiers.
- Glass:Soda-lime formulations dominate commodity production; borosilicate variants capture premium thermal-shock applications. EU Green Deal emissions frameworks compress manufacturing location decisions for furnace operators.
- Plastic:BPA-free polyethylene and polypropylene jars for cold-storage and non-thermal applications. Lower unit weights reduce shipping costs in e-commerce fulfillment.
- Metal:Tinplate and aluminum lids and bands with corrosion-resistant coatings. REACH reformulation deadlines force substitution trials for plastisol sealing compounds.
- Silicone:Heat-temperature reusable gaskets and bands displacing single-use metal components. Lifecycle cost economics attract premium segment buyers despite higher upfront expenditure.
Glass leads volumes today; silicone is expanding most quickly.
End User:
Procurement scale and specification complexity segment the buyer base.
- Home Canners:Hobbyist practitioners purchasing through retail and direct subscription channels. Seasonal harvest cycles align with replenishment-driven revenue models.
- Restaurants:Farm-to-table establishments sourcing heritage-format containers for in-house preservation and table presentation. Smaller lot sizes than commercial processors.
- Farmers:Direct-market producers packaging value-added products for farmers market and CSA distribution. Price sensitivity elevates with input cost volatility.
- Food Processors:Industrial-scale operators requiring automated filling line compatibility and pallet-scale procurement. Custom mouth diameters and lid specifications command substantial premiums.
Home canners lead volumes today; food processors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan food preservation communities in the United States anchor skilled hobbyist demand, while European glass furnace operators face workforce retraining imperatives under decarbonization mandates. Asian manufacturing clusters supply component volumes to export markets. Regional regulatory divergence shapes capital allocation and procurement patterns.
United States
Farmhouse-to-table retail channels in the Midwest and Pacific Northwest allocate expanded shelf space to heritage-format wide-mouth jars as home food security consciousness rises. The FDA governs metal lid and plastisol sealing compound standards under 21 CFR regulations. Ball Corporation's North American manufacturing footprint supplies standardized formats to volume retailers from Indiana and Colorado facilities.
Germany
EU Green Deal carbon accounting rules compress manufacturing location decisions for glass furnace operators in Bavaria and North Rhine-Westphalia. REACH substance restrictions force reformulation deadlines for plastisol sealing gasket chemistries. Ardagh Group's German facilities retrofit toward closed-loop recycling systems to capture sustainability-focused procurement contracts.
China
GB standards compliance requirements and dual carbon goals reshape export-oriented glass container production in Shandong and Jiangsu provinces. The country's national quality regulator enforces certification timelines that impose multi-quarter approval delays for foreign market access. Zhengzhou and Guangzhou clusters specialize in metal lid and band component manufacturing for global supply chains.
India
BIS certification requirements for food-contact surfaces create working capital strain for exporters staging inventory during regulatory review in Maharashtra and Gujarat. FSSAI standards govern domestic food packaging safety. Mumbai and Ahmedabad industrial zones host glass furnace operations supplying both domestic preservation culture growth and Middle East export demand.
France
ANSM oversight of food-contact materials intersects with EU Green Deal emissions frameworks for furnace operations in Île-de-France and Hauts-de-France. Artisan food producers in Provence-Alpes-Côte d'Azur drive heritage-format container demand for direct-market value-added products. Lille and Paris basin logistics clusters facilitate pallet-scale distribution to European farmhouse-to-table retail networks.
Mason Jars and Canning Supplies Market Competitive Landscape
Capital-heavy glass furnace operators compete with asset-light lid and accessory specialists for margin capture across the value chain. The vendor base stratifies across integrated container manufacturers, component specialists, and heritage-format niche suppliers. Three archetypes dominate: scale-driven volume producers, premium heritage-positioned brands, and flexible component assemblers. Competitive moves center on furnace technology licensing partnerships and direct-to-consumer subscription channel development.
Among North American integrated manufacturers, Ball Corporation and Newell Brands occupy positions representing scale-driven and heritage-brand archetypes respectively. Owens-Illinois anchors industrial supply relationships with commercial food processors. Fillmore Container exemplifies the flexible component assembler model serving mid-volume regional processors. Berlin Packaging and Ardagh Group represent European-origin diversified packaging conglomerates with glass container capabilities spanning multiple end-use categories.
| Leading Market Players |
|---|
| Fillmore Container |
| Owens-Illinois |
| Newell Brands |
| Berlin Packaging |
| Ardagh Group |
| Ball Corporation |
| The Jar Store |
| Plasdene Glass-Pak Pty Ltd |
| Kerr |
| Others |
Supply & Pricing Matrix
Skilled glassblower concentrations in Bohemia and Murano anchor artisan-tier pricing spreads, with labor-cost differentials between heritage European furnace sites and automated Asian facilities separating premium heritage jars from commodity soda-lime volumes by three-to-fivefold at wholesale.
Pricing Analysis
Three-tier pricing structure across heritage artisan, commercial-grade, and economy private-label levels governs procurement contracts. Price differentiation rests on borosilicate thermal-shock certification against commodity soda-lime grades, plus brand heritage premiums for Ball and Kerr legacy positioning. Pricing pressure stems from natural gas cost volatility compressing furnace operator margins. Home canners exhibit highest price sensitivity, while commercial food processors accept substantial premiums for customized lid specifications.
Supply Chain Analysis
Extended producer responsibility mandates in Germany and France are reshaping sourcing decisions toward closed-loop cullet preprocessing capabilities. Manufacturing gravity centers on China for metal lid and band components, the United States for standardized jar formats, and the Czech Republic for heritage mouth-diameter specialty production. Raw material dependencies encompass silica sand, soda ash, limestone, and tinplate steel. Single-source vulnerability concentrates in two-component plastisol sealing compound formulators. Distribution runs through farmhouse-to-table retail channels and direct subscription platforms capturing replenishment-driven lid demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal functions as a regulatory compounder, with carbon accounting rules and REACH reformulation deadlines accelerating furnace retrofit investments and sealing chemistry substitutions across European supply chains.
For Market Incumbents: Cement market position by retrofitting facilities toward closed-loop recycling systems ahead of post-consumer recycled content mandates. Acquire specialty chemical formulators facing REACH substitution deadlines to secure plastisol supply continuity. Channel control through direct-to-consumer subscription platforms defends margin against retail slotting fee compression. For New Entrants and Emerging Players: Capture white-space opportunity in silicone reusable gasket segments displacing single-use metal bands. Target craft beverage producers requiring hermetic fermentation vessels with custom lid specifications. Go-to-market through pallet-scale procurement relationships with regional commercial processors bypasses entrenched retail distribution. For Investors and Strategic Acquirers: Packaging conglomerates with diversified glass container capabilities are the most active acquirer in this space, seeking heritage-format niche suppliers to fill portfolio gaps. Long-term viability favors operators with cullet preprocessing infrastructure and borosilicate technical capabilities. Watch EU Green Deal implementation timelines as inflection indicator for capital reallocation toward lower-emission furnace technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Technology Licensing Partnership | Ball Corporation leverages Indiana manufacturing scale to transfer closed-loop recycling expertise to European operators facing EU Green Deal deadlines. |
| Direct-to-Consumer Subscription Launch | Newell Brands bypasses traditional retail slotting structures through seasonal harvest-aligned replenishment kits capturing recurring lid revenue. |
| Backward Integration into Silicone Gaskets | Heritage-format specialists secure heat-tolerant reusable component supply chains against metal band price volatility. |
| Commercial Fermentation Vessel Customization | Mid-volume processors command pallet-scale premiums from craft beverage producers requiring anaerobic process control specifications. |
| Extended Producer Responsibility Pre-Compliance | Ardagh Group captures sustainability-focused procurement contracts through Bavarian facility retrofits ahead of mandated recycled content thresholds. |
Research Methodology
Direct dialogue with glass furnace operations managers, metal lid procurement leads at jar assemblers, farmhouse-to-table retail category buyers, and commercial food processing engineers grounded qualitative assessment. Secondary validation drew from FDA 21 CFR filings, EPA emissions disclosures, EU ETS carbon accounting records, and customs trade data for silica sand and tinplate steel flows. Bottom-up SKU-level demand modeling and top-down glass container production capacity analysis provided triangulation checks.
Segment-level value outputs across product type, application context, material formulation, and end-user procurement scale were generated through the analytical framework. CAGRs were derived from trend extrapolation against EU Green Deal implementation pace and home preservation culture indicators. Forecast inputs incorporated natural gas price volatility scenarios and REACH substance restriction timelines affecting plastisol sealing compound availability.
Natural gas price spikes, REACH reformulation delays, and BIS certification timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about furnace technology adoption rates and consumer willingness to pay lifecycle-cost premiums for silicone alternatives. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Laundry Detergent Sheets Market
Household Items
Kuwait Gas Hobs Market
Household Items
Collapsible Water Bottle Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Permanent Marker Market
Household Items
Domestic Sauna Heaters Market
Household Items
Nebulizing Diffuser Market
Household Items
Luxury Massage Chair Market
Household Items
Infrared Sauna Heaters Market
Household Items
Global Paper Towels Market
Household Items
Leaf Blower Market
Household Items
United States Smart Shower Market
Household Items
Latex Mattress Market
Household Items
Thermos Bottle Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Aquarium Heaters and Chillers Market