
 South Africa Cookware Market | 2026-2036
South Africa Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Cookware Market Insights
South African foundries and metal-forming facilities is hardening domestic supply capacity for cast iron and stainless steel cookware. Meyer International Holdings Limited leverages backward integration into forged aluminum production to secure cost advantages. Le Creuset sustains premium positioning through enameled cast iron specialization. Ener-G-Africa anchors local manufacturing with energy-efficient cookware lines designed for South African cooking patterns.
Cookware encompasses vessels and containers used for food preparation through direct heat transfer, typically fabricated from metals with thermal conductivity ratings between 15-400 W/m·K or engineered ceramic composites. Stainless steel cookware dominates commercial kitchens due to corrosion resistance and compatibility with induction cooktops, while non-stick coatings reduce fat requirements in health-conscious households. Cast iron retains thermal mass advantages for slow-cooking traditions, whereas copper offers precise temperature control in professional restaurant environments. Online retail channels capture growing share as delivery logistics improve across South African metropolitan areas.
South Africa's National Regulator for Compulsory Specifications enforces SANS standards for food-contact materials, while the country's central bank monitors import duties that affect cookware pricing structures. The International Organization for Standardization provides ISO 8442 benchmarks for cutlery and holloware that exporters must satisfy for market access. Stakeholders must track evolving energy-efficiency labeling requirements and local content thresholds under industrial policy frameworks.
Market Dynamics
Urbanization across Gauteng and Western Cape provinces is compressing household formation timelines and accelerating premium cookware replacement cycles in South African metropolitan kitchens.
Growth Catalysts
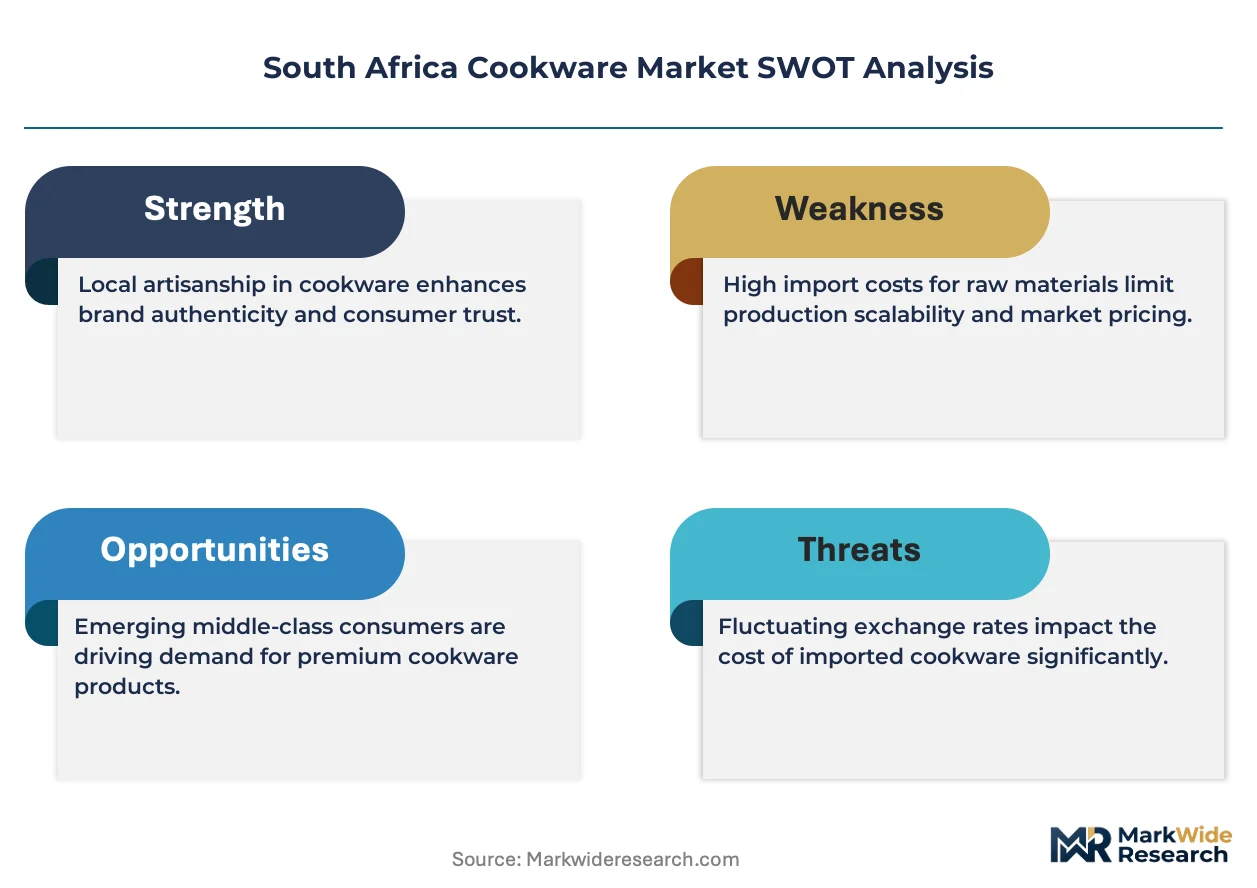
- Induction cooktop adoption:Energy-efficiency mandates from the Department of Mineral Resources and Energy are accelerating induction-compatible cookware demand in Johannesburg and Cape Town residential developments.
- Restaurant sector expansion:Gauteng's food service industry is consolidating purchasing power for professional-grade stainless steel collections, creating volume pull-through for domestic distributors.
- SANS 50136 enforcement:South Africa's National Regulator for Compulsory Specifications is elevating import quality thresholds, filtering substandard products and protecting compliant domestic manufacturers.
Market Restraints
- Aluminum ingot price volatility:Raw material input swings from LME-linked suppliers compress margin predictability for forged aluminum cookware producers.
- Import dependency concentration:Chinese-origin cookware dominates mid-market shelf space, exposing distributors to shipping cost spikes and currency fluctuation risk.
- PTFE coating technical limitations:Non-stick degradation above 260°C restricts high-heat cooking applications in traditional South African braai-prepared dishes.
Strategic Opportunities
- Eastern Cape underpenetration:Port Elizabeth and East London retail infrastructure gaps create first-mover advantage for direct-to-consumer cookware brands with localized logistics.
- Energy-efficiency labeling tailwind:South African Bureau of Standards' expanding appliance efficiency program will differentiate certified cookware in retail environments.
- Social commerce convergence:WhatsApp Business integration with last-mile delivery networks is opening informal settlement market access previously blocked by traditional retail.
Industry Challenges
- Artisan foundry skill scarcity:Cast iron cookware production requires specialized mold-making expertise that technical training institutions are not replenishing at replacement rates.
- SANS certification timeline compression:Extended laboratory testing queues at accredited facilities delay product launch windows for seasonal cookware introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Cookware Market |
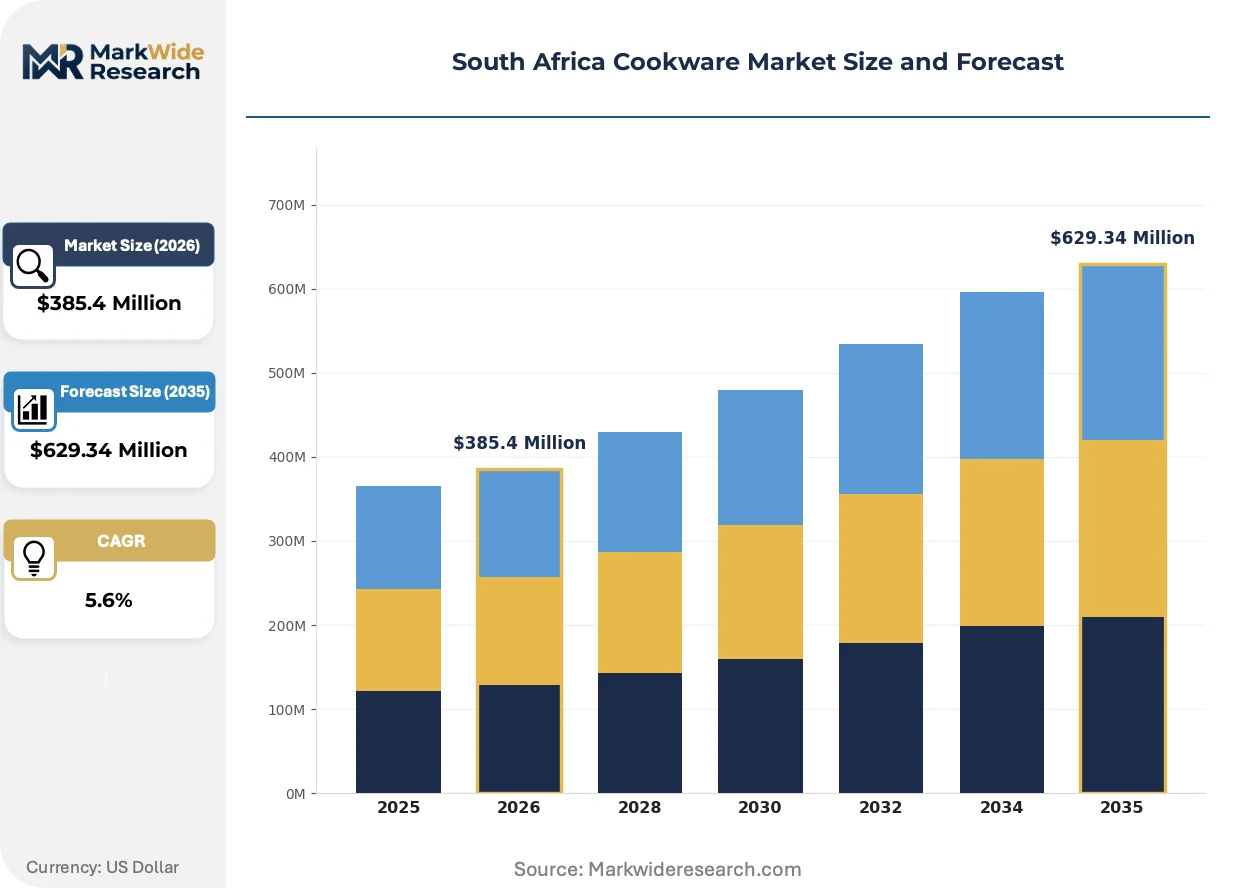
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware Sets, Frying Pans, Saucepans, Woks Material: Stainless Steel, Cast Iron, Non-Stick, Copper End User: Households, Restaurants, Catering Services, Hotels Sales Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Meyer International Holdings Limited, The Vollrath Company, LLC, Le Creuset, Hamilton Beach Brands Holding Company, Lifetime Brands, Newell Brands, Tramontina, Ener-G-Africa, Groupe SEB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Cookware Market Trends and Innovations
Material science advances and regulatory pressure on energy efficiency are reshaping how South African households and commercial kitchens select heat-transfer equipment.
Tri-ply stainless steel construction is consolidating position in premium residential segments. Johannesburg's upper-middle-class households are adopting clad cookware for its induction compatibility and even heat distribution. This construction method is consolidating market share from single-ply alternatives by satisfying dual demands for durability and energy efficiency.
South Africa's National Regulator for Compulsory Specifications is tightening food-contact material surveillance under SANS 50136. The industrial consequence is elevated compliance costs for imported ceramic-coated and aluminum products. Retailers in Western Cape provinces are responding by shifting shelf space toward certified domestic and European-origin inventory with established testing documentation.
Direct-to-kitchen demonstration models are disrupting traditional retail cookware distribution. Independent sales agents operating in Gauteng townships are replacing department store purchases with in-home product trials. This channel compression is most visible in Soweto and Tembisa, where word-of-mouth validation outperforms advertising spend for first-time premium cookware buyers.
South Africa Cookware Market Segmentation
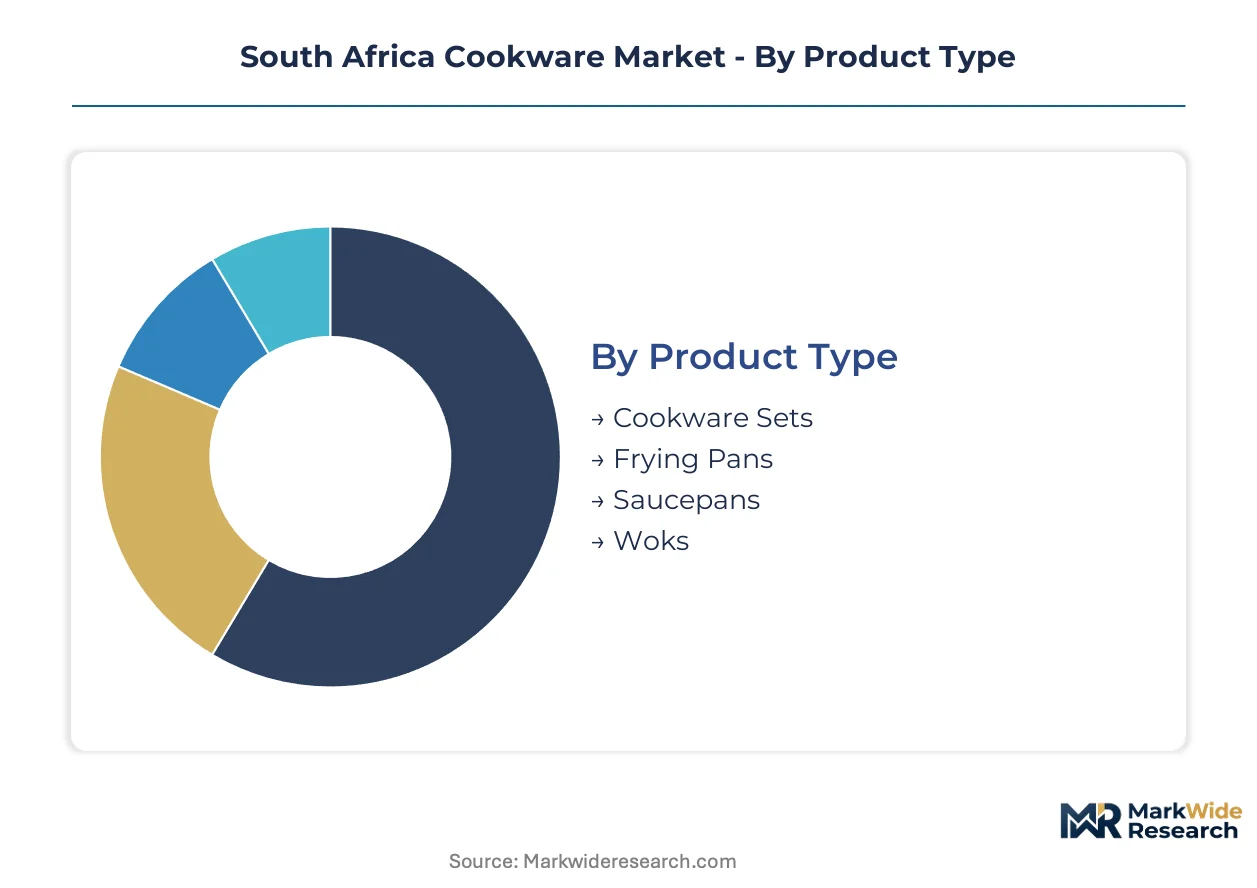
South Africa's cookware market fragments across four critical dimensions that shape procurement patterns and margin structures. Material composition and sales channel dynamics exert the strongest influence on pricing power, while end-user concentration in Gauteng's food service sector redirects supply chain investments.
Product Type:
Standalone cookware pieces dominate replacement purchases, whereas integrated cookware sets anchor new household formation and gift-giving occasions across South African metropolitan markets.
- Cookware Sets:Bundled configurations of 5-12 pieces with coordinated lids and nesting storage profiles. Demand concentrates in Johannesburg's upper-middle-class residential developments where induction-compatible tri-ply construction commands shelf space at specialty retailers.
- Frying Pans:Flat-bottomed skillets with 20-32cm diameters, typically featuring forged aluminum or stainless steel bases. Western Cape health-conscious households drive non-stick coated variants for reduced-oil cooking, though PTFE temperature limitations restrict traditional braai applications.
- Saucepans:Medium-capacity vessels with long handles and tight-fitting lids for liquid-based preparations. Standard equipment in South African catering college training programs.
- Woks:High-walled carbon steel or cast iron vessels engineered for high-heat stir-fry techniques. Port Elizabeth's Asian restaurant community sustains specialized import demand.
Cookware Sets lead volumes today; Frying Pans are gaining share fastest through standalone replacement cycles.
Material:
Cost tier stratification separates premium-clad stainless steel from commodity aluminum, with material selection directly determining compatibility with South Africa's accelerating induction cooktop mandates.
- Stainless Steel:Austenitic 304-grade or tri-ply clad construction with aluminum or copper cores. Johannesburg restaurant kitchens specify SANS-compliant grades for corrosion resistance under commercial dishwasher cycles.
- Cast Iron:Pre-seasoned or enameled ferrous vessels with thermal mass exceeding 3.5 kg for 26cm skillets. Artisan foundry capacity constraints in South Africa limit domestic supply expansion.
- Non-Stick:PTFE or ceramic-coated aluminum substrates requiring sub-260°C operating temperatures. Health-conscious Western Cape households favor ceramic alternatives despite shorter service lifespans.
- Copper:2.5mm gauge solid or tin-lined construction for precise thermal response. Professional chef demand in Cape Town fine-dining establishments sustains niche import volumes.
Stainless Steel dominates installed base; Non-Stick coatings show steepest expansion trajectory in residential replacement purchases.
End User:
Volume concentration versus margin capture splits the market, with food service procurement emphasizing durability certifications and household segments prioritizing aesthetic coordination with kitchen renovations.
- Households:Individual consumers purchasing 1-5 piece configurations for residential kitchens. Gauteng urbanization compresses replacement timelines as apartment dwellers downsize from extended-family cookware inventories.
- Restaurants:Licensed dining establishments with SANS 50136 compliance requirements for food-contact surfaces. Johannesburg's Sandton and Rosebank clusters consolidate purchasing power through group procurement consortia.
- Catering Services:Mobile and event-based food operators requiring lightweight, high-volume aluminum stockpots and serving vessels. Eastern Cape wedding seasonality drives peak Q3 demand spikes.
- Hotels:Hospitality groups with standardized kitchen specifications across property portfolios. Cape Town's Atlantic seaboard boutique properties specify copper showpieces for open-kitchen theater.
Households anchor volume absorption; Restaurants deliver highest per-transaction value with professional-grade specifications.
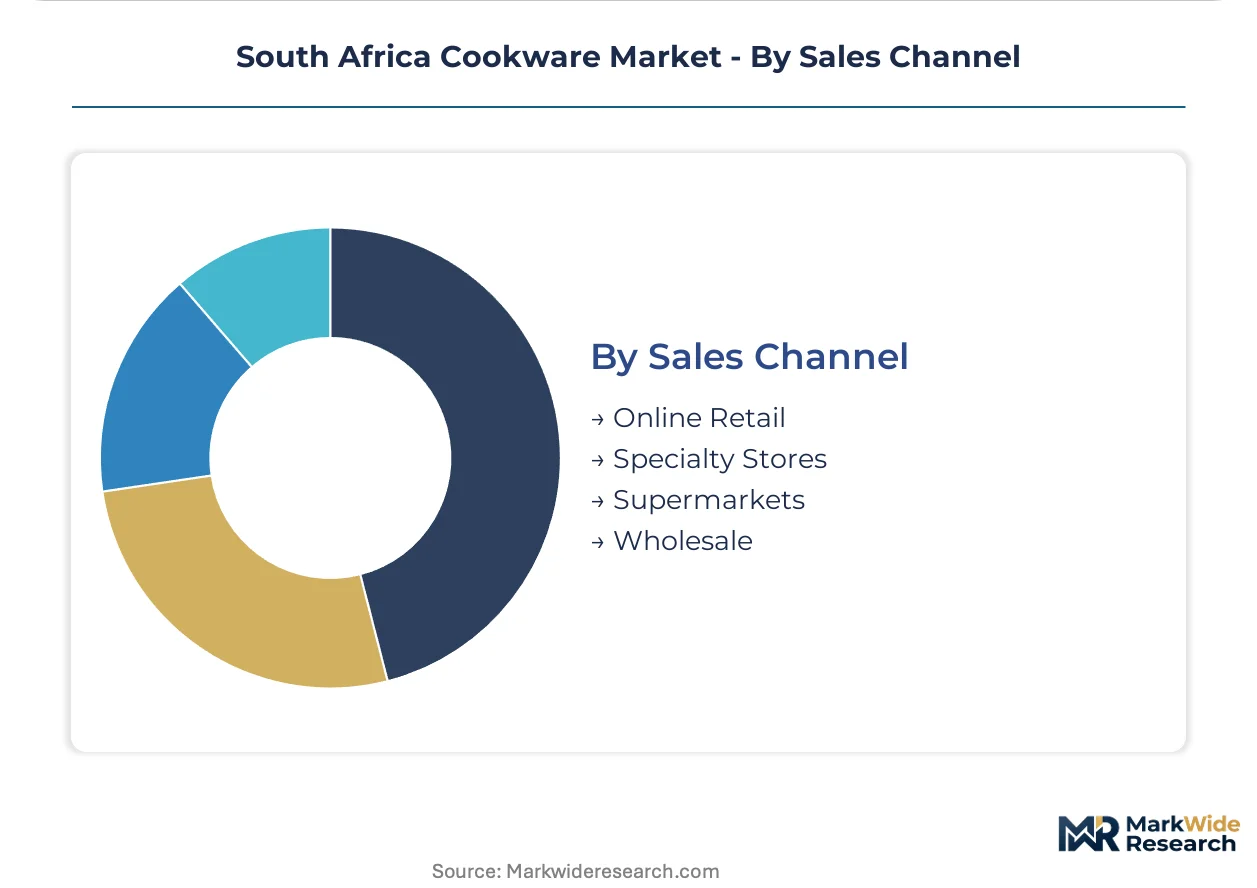
Sales Channel:
Physical retail retains cookware's tactile evaluation requirement, though logistics improvements and WhatsApp-enabled social commerce are compressing traditional distribution layers in informal settlement markets.
- Online Retail:E-commerce platforms with augmented reality visualization tools and 30-day return policies. Cape Town's last-mile delivery density supports premium cookware trials without showroom visits.
- Specialty Stores:Kitchenware boutiques with in-house demonstration chefs and induction test stations. Johannesburg's Mall of Africa and V&A Waterfront locations sustain Le Creuset and Meyer flagship presence.
- Supermarkets:Mass-market retailers with seasonal promotional cycles and private-label aluminum collections. Checkers and Pick n Pay dominate mid-market saucepan and frying pan distribution.
- Wholesale:Cash-and-carry and restaurant supply depots serving Gauteng's independent food service operators. Johannesburg's City Deep logistics hub concentrates import clearance and redistribution.
Specialty Stores capture premium pricing; Online Retail is climbing the fastest as delivery infrastructure penetrates secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between domestic SANS certification requirements and import testing protocols are redirecting manufacturing investment toward South African foundries with established laboratory relationships.
Gauteng
Johannesburg's restaurant density and Sandton retail clusters concentrate demand for professional-grade stainless steel and induction-compatible cookware. The National Regulator for Compulsory Specifications maintains SANS 50136 enforcement offices in Pretoria, streamlining certification for domestic producers. The Vaal Triangle manufacturing corridor hosts metal-forming facilities serving both household and food-service procurement channels.
Western Cape
Cape Town's Atlantic seaboard hospitality sector specifies copper and enameled cast iron for open-kitchen theater applications. The South African Bureau of Standards operates testing facilities in Bellville, reducing lead times for Western Cape-based cookware distributors. Stellenbosch wine route estates are consolidating group purchasing for premium kitchenware collections.
KwaZulu-Natal
Durban's port infrastructure handles bulk aluminum ingot imports for forged cookware production serving mid-market retail channels. The provincial environmental affairs department enforces industrial emissions standards affecting foundry operations in Pinetown. Umhlanga's emerging retail corridor is attracting specialty kitchenware flagships targeting coastal tourism expenditure.
Eastern Cape
Port Elizabeth's automotive supplier base is diversifying into aluminum cookware fabrication using existing metalworking capacity. Nelson Mandela Bay's industrial development zone offers tariff incentives for manufacturers meeting local content thresholds. East London's retail infrastructure gaps are forcing direct-to-consumer brands to develop independent logistics networks.
Free State
Bloemfontein's central location positions distribution hubs for cookware redistribution to Lesotho and northern Cape markets. The provincial agriculture department's food processing support programs are stimulating commercial kitchen equipment demand among agribusiness operators. Welkom's mining heritage has left a legacy of metalworking skills applicable to cast iron cookware production.
South Africa Cookware Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue energy-efficient specialization and social commerce distribution. The market structures around three concentration nodes: multinational portfolio companies with broad material coverage, regional fabricators leveraging backward integration into primary metal production, and domestic specialists targeting compliance-advantaged local manufacturing. Strategic moves center on certification pre-positioning ahead of SANS enforcement tightening and logistics partnerships with last-mile delivery networks in informal settlement markets.
Among premium-positioned specialists, Le Creuset exemplifies heritage-brand anchoring through enameled cast iron specialization, while Meyer International Holdings Limited represents scale-driven integration into forged aluminum production. Ener-G-Africa occupies a position within the domestic manufacturing tier, targeting energy-efficiency differentiation aligned with South African cooking patterns. These three anchors illustrate the competitive spectrum from global heritage positioning through integrated cost leadership to locally optimized product development.
| Leading Market Players |
|---|
| Meyer International Holdings Limited |
| The Vollrath Company, LLC |
| Le Creuset |
| Hamilton Beach Brands Holding Company |
| Lifetime Brands |
| Newell Brands |
| Tramontina |
| Ener-G-Africa |
| Groupe SEB |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between SANS 50136-compliant domestic production and import-dependent mid-market supply concentrates pricing power with accredited South African foundries while compressing margins for distributors managing Chinese-origin inventory through Johannesburg's City Deep logistics hub. This tier divergence manifests in divergent supply chain configurations: premium channels anchor in Pretoria-certified domestic metal-forming facilities, whereas price-driven segments remain tethered to aluminum ingot shipments through Durban port.
Pricing Analysis
Distributor margin layers separate specialty retailers commanding 35-45% markups on tri-ply stainless steel from supermarket channels pushing 18-22% on private-label aluminum. Three-tier pricing structure across premium, standard, and economy levels reflects SANS certification status, induction compatibility, and brand heritage. Cost compression in the mid-market intensifies because Chinese-origin supply faces rand-dollar volatility and shipping cost spikes. Households in Gauteng townships exhibit highest price sensitivity, while Sandton restaurant procurement consortia prioritize durability certifications over unit cost.
Supply Chain Analysis
Freight cost differentials between Durban container handling and overland trucking to Eastern Cape retail gaps disadvantage import-dependent distributors against Western Cape-based domestic fabricators. Manufacturing concentration spans China for forged aluminum substrates, South Africa for stainless steel fabrication, and limited domestic artisan foundry capacity for cast iron. Raw material dependencies include LME-linked aluminum ingots, nickel-alloyed stainless steel sheet, and ceramic coating chemicals. Single-source vulnerability concentrates in Chinese PTFE-coated supply for non-stick segments. Distribution runs through Johannesburg wholesale depots, Cape Town specialty retail flagships, and emerging WhatsApp-enabled direct-to-kitchen networks in informal settlements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's cookware market functions as a regulatory compounder where SANS 50136 enforcement timelines accelerate demand migration toward certified domestic production and European-origin imports with established testing documentation.
For Market Incumbents: Extend certification pre-positioning ahead of National Regulator for Compulsory Specifications tightening by securing laboratory queue priority at accredited Pretoria and Bellville facilities. Defend against emerging direct-to-kitchen demonstration models by anchoring flagship presence at Mall of Africa and V&A Waterfront with in-house induction test stations. Deepen backward integration into forged aluminum production to offset LME price volatility. For New Entrants and Emerging Players: Launch via WhatsApp Business integration with last-mile delivery networks targeting Port Elizabeth and East London retail infrastructure gaps. Eastern Cape underpenetration offers first-mover advantage for energy-efficient cookware lines aligned with provincial industrial development zone incentives. Social commerce convergence in Gauteng townships provides lowest customer acquisition cost for premium trial conversion. For Investors and Strategic Acquirers: Consolidation pressure builds where artisan foundry skill scarcity meets SANS certification timeline compression, favoring targets with captive mold-making expertise and established laboratory relationships. Long-term viability centers on domestic manufacturing assets with local content threshold compliance under industrial policy frameworks. Watch for energy-efficiency labeling program expansion by the South African Bureau of Standards as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SANS Certification Pre-Positioning | Secures laboratory queue priority at Pretoria and Bellville testing facilities ahead of enforcement tightening. |
| Backward Integration into Forged Aluminum | Meyer International Holdings Limited model reduces LME-linked input cost volatility exposure. |
| WhatsApp-Enabled Direct Distribution | Opens informal settlement market access previously blocked by traditional retail infrastructure gaps. |
| Energy-Efficiency Labeling Alignment | Differentiates certified cookware as South African Bureau of Standards expands appliance efficiency program. |
| Eastern Cape Logistics Network Buildout | Captures first-mover advantage in Port Elizabeth and East London retail infrastructure gaps. |
Research Methodology
Bottom-up household and restaurant procurement modeling reconciled against top-down foundry output and import clearance tracking forms the analytical core of this study. Primary interviews with category buyers at Checkers and Pick n Pay, procurement managers at Johannesburg restaurant consortia, technical directors at South African metal-forming facilities, and distribution heads at City Deep logistics depots combined with secondary validation from customs records, South African Bureau of Standards certification databases, and Department of Mineral Resources and Energy appliance efficiency disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrix framing connects aluminum ingot import volumes through Durban, stainless steel sheet consumption at Vaal Triangle facilities, and induction cooktop penetration rates in Gauteng residential developments to cookware replacement cycle projections. Segmentation dimensions modeled include material composition, end-user category, sales channel, and provincial demand concentration. CAGRs were derived from curve-fitting historical replacement patterns against urbanization timelines and regulatory milestone schedules across the projection horizon. Industry-specific forecast inputs incorporate SANS 50136 enforcement phase-ins and energy-efficiency labeling adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rand-dollar volatility spikes or accelerated SANS laboratory testing queue congestion. Model outputs reflect assumptions regarding induction cooktop mandate implementation speed and artisan foundry skill replenishment rates. A model refresh is warranted upon material change in National Regulator for Compulsory Specifications enforcement calendar or aluminum ingot price regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Vacuum Cleaner Market
Household Items
Compressed Tablet Towel Market
Household Items
Shower Caddies Market
Household Items
Facial Tissue Market
Household Items
Electric Brooms Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Portable Humidifiers Market
Household Items
Non-Stick Cookware Market
Household Items
Dry Cleaning and Laundry Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
North America Glassware Market
Household Items
Electric Air Freshener Market
Household Items
Home Use Air Purifiers Market
Household Items
Japan Faucets Market
Household Items
Dryer Sheets Market
Household Items
Electric Mop Market