
 Global Aluminum Cookware Market | 2026-2036
Global Aluminum Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Cookware Market Analysis
Stainless steel is hardening its position as a premium substitute in professional kitchen environments, yet aluminum retains cost advantages in volume segments. Groupe SEB leverages European manufacturing scale to sustain margin pools across hard-anodized product lines. Meyer Corporation Limited anchors North American distribution through specialty retail partnerships. Hawkins Cookers Limited dominates South Asian pressure-cooker demand with localized alloy formulations.
Aluminum cookware comprises vessels fabricated from aluminum sheet or cast alloys, typically alloyed with magnesium, silicon, or manganese to enhance thermal conductivity and structural integrity, with wall thicknesses ranging from 2.5mm to 5mm depending on application stress. Its primary commercial purpose centers on rapid, uniform heat distribution for domestic food preparation and high-throughput commercial cooking operations. Fry pans and saucepans command the largest revenue share within product type segmentation, while hard-anodized coating types capture expanding margin pools due to durability premiums. Online retail channels represent the fastest-growing distribution pathway, though supermarkets sustain the highest transaction volumes in emerging economies.
EU REACH restrictions on perfluorinated compounds and FDA food-contact surface regulations in the United States constrain non-stick coating formulations, redirecting R&D investment toward ceramic and silicone-based alternatives. China's GB standards for heavy metal migration and India's BIS certification requirements for pressure cookware shape regional market access conditions. Stakeholders must monitor evolving coating chemistry regulations and induction-base compatibility standards as purchase criteria shift across consumer segments.
Market Dynamics
Hard-anodizing technology advances and REACH-mandated coating reformulations are compressing legacy manufacturing margins while rewarding capital-intensive process upgrades across European and North American production bases.
Growth Catalysts
- Energy efficiency mandates:Commercial kitchen operators in the United States face state-level energy codes that favor aluminum's thermal conductivity over heavier alternatives. Restaurant chains accelerate fleet replacement cycles to comply.
- Induction compatibility standards:India's urban households drive demand for ferromagnetic-base aluminum cookware as induction stove penetration rises in metropolitan markets. BIS certification requirements validate product safety claims.
- Hard-anodizing process maturation:Advanced electrolytic surface treatments extend product lifecycles by 40-60% versus conventional coatings. Premium kitchenware retailers capture durability premiums through extended warranty positioning.
Market Restraints
- Alumina price volatility:Primary aluminum smelter energy costs in China and Russia transmit directly to cookware alloy pricing. Smaller fabricators lack hedging mechanisms to absorb input spikes.
- Stainless steel substitution:Professional kitchens in Germany and France specify 18/10 chromium-nickel alloys for acidic food preparation environments. Aluminum loses share in high-margin institutional procurement.
- REACH perfluorinated compound restrictions:ECHA classification of long-chain PFAS compounds forces coating reformulation. R&D timelines extend 18-24 months for compliant non-stick alternatives.
Strategic Opportunities
- India's tier-2 urban expansion:Cities including Pune, Ahmedabad, and Kochi show underpenetrated aluminum cookware adoption relative to metro saturation. Organized retail expansion creates shelf access.
- Ceramic-silicone hybrid coatings:Convergence of sol-gel ceramic matrices with food-grade silicone topcoats eliminates PFAS dependency. Early movers capture regulatory-compliant positioning.
- Direct-to-consumer channel development:Specialty cookware brands bypass supermarket margin stacking through owned e-commerce platforms. Subscription-based replacement programs lock recurring revenue.
Industry Challenges
- Hard-anodizing technician scarcity:Electrolytic bath chemistry expertise concentrates in legacy European and Japanese facilities. New production lines face 12-18 month staffing delays.
- Multi-jurisdiction certification complexity:Simultaneous FDA, EFSA, and BIS food-contact approvals require parallel testing protocols. Launch timelines stretch across regulatory calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Cookware Market |
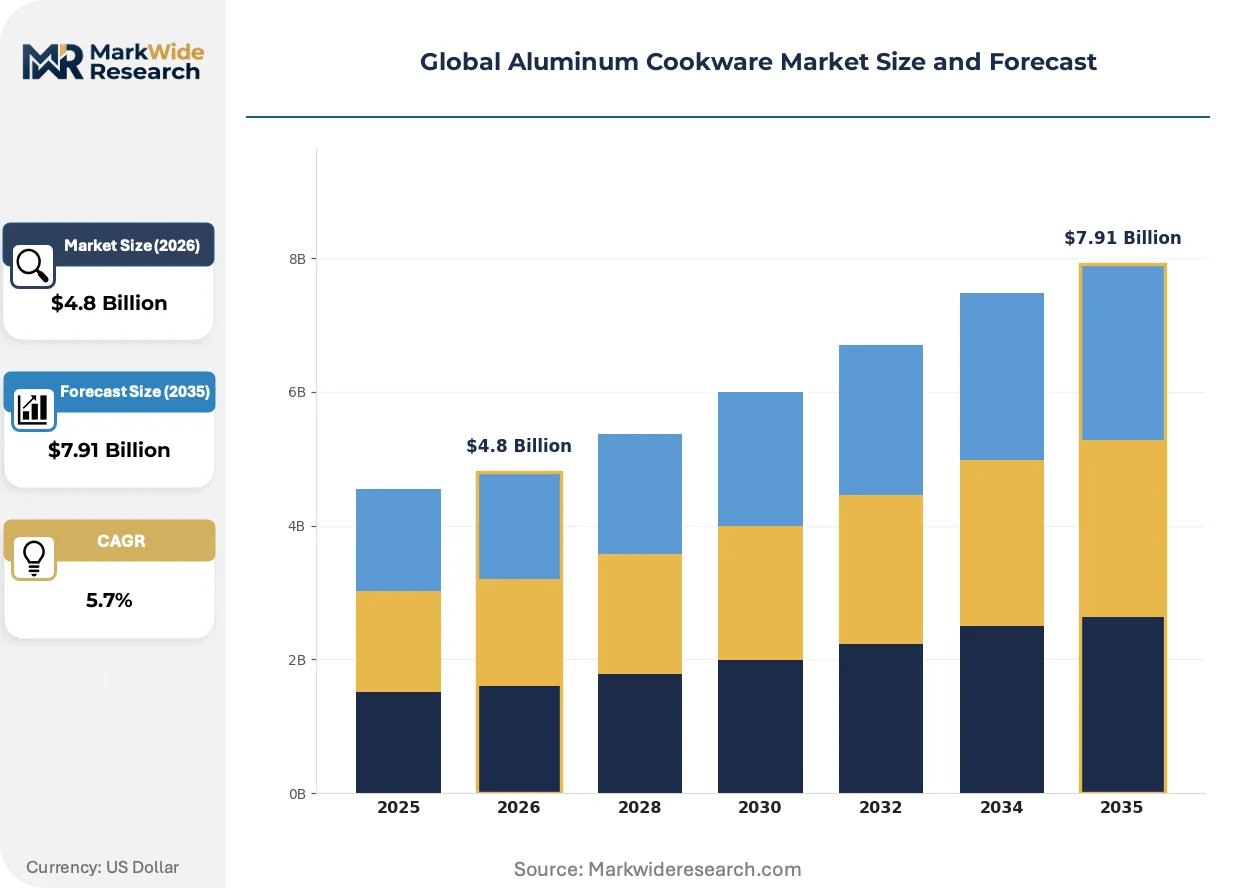
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fry Pans, Saucepans, Stock Pots, Griddles End User: Households, Restaurants, Hotels, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Coating Type: Non-stick, Anodized, Hard Anodized, Others |
| Companies Covered | Tramontina S.A. Cutelaria, Scanpan A/S, Groupe SEB, Le Creuset Group AG, TTK Prestige Ltd., Meyer Corporation Limited, All-Clad Metalcrafters, LLC, Hawkins Cookers Limited, Newell Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Cookware Market Emerging Trajectories
Surface engineering breakthroughs and coating chemistry pivots are redefining product differentiation axes. Channel structures fragment as digital-native entrants bypass traditional retail gatekeepers.
Hard-anodized aluminum substrates are expanding into premium consumer segments previously dominated by clad stainless steel constructions. Specialty retailers in France and Italy now stock 4-5mm wall-thickness anodized ranges at price points matching tri-ply competitors. The technology is expanding into gift-market positioning where durability signaling commands 25-35% price premiums over conventional aluminum.
EU REACH Annex XVII restrictions on perfluorooctanoic acid (PFOA) and related perfluorinated compounds have eliminated conventional PTFE coating pathways for European-market cookware. Manufacturers redirect formulation investment toward ceramic-reinforced sol-gel systems and plasma-sprayed silicone matrices. German and Italian coating houses now dominate compliant technology licensing to Asian fabricators seeking European market access.
Restaurant chain procurement departments consolidate vendor relationships around lifecycle cost metrics rather than unit purchase price. North American multi-unit operators specify induction-compatible aluminum with 5-year replacement guarantees. Foodservice distributors respond with consolidated SKU rationalization programs that displace fragmented regional supplier networks.
Global Aluminum Cookware Market Segmentation
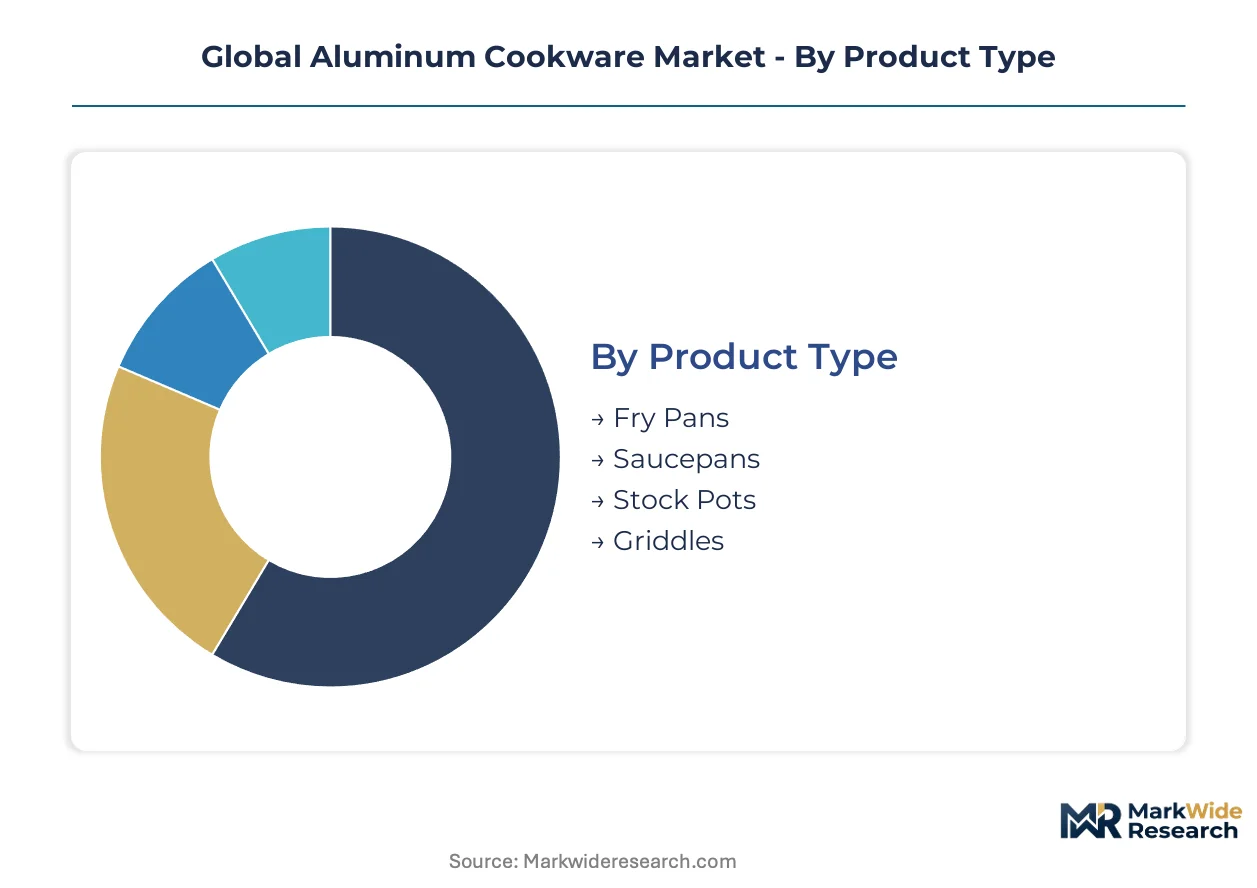
Aluminum cookware segmentation reveals divergent performance requirements across thermal stress profiles and regulatory exposure. Product specifications must align with end-use intensity, coating durability mandates, and channel margin structures.
Product Type:
Standalone cooking vessels dominate residential procurement, while embedded multi-piece configurations serve commercial kitchen system builds.
- Fry Pans:Flat-bottomed vessels with 2.5-4mm wall thickness optimize rapid heat response for sautéing and searing. Restaurant chains in the United States specify induction-compatible bases to meet California and New York state energy codes.
- Saucepans:Medium-walled constructions with pouring lips and fitted lids concentrate liquid-based cooking tasks. India's urban households drive replacement cycles as BIS-certified induction models displace traditional gas-compatible units.
- Stock Pots:High-capacity vessels for batch boiling carry premium wall thickness specifications. Commercial catering operators in Germany favor anodized variants for acidic broth preparation.
- Griddles:Broad surface-area designs with integrated grease channels serve breakfast-service volume. North American foodservice distributors consolidate SKUs around 5-year lifecycle guarantees.
Fry pans lead volumes today; hard-anodized stock pots are gaining share fastest in commercial procurement.
End User:
Cost tiers separate price-sensitive mass consumption from durability-premium institutional specifications.
- Households:Individual consumers prioritize weight reduction and storage efficiency in constrained kitchen spaces. India's tier-2 cities including Pune and Ahmedabad show underpenetrated organized retail access relative to metro saturation.
- Restaurants:High-throughput operators demand thermal shock resistance and rapid recovery times. EFSA-compliant coating reformulations redirect European procurement toward ceramic-reinforced alternatives.
- Hotels:Branded hospitality chains standardize across property portfolios for supply chain efficiency. French and Italian luxury properties specify 4-5mm wall-thickness anodized ranges at tri-ply price parity.
- Catering Services:Mobile food preparation requires lightweight stackability and transport durability. Wholesale distributors in the United Kingdom bundle replacement programs with volume commitments.
Households anchor volume absorption; restaurant procurement is climbing the fastest on energy mandate compliance.
Distribution Channel:
Volume concentration versus margin capture defines channel strategy divergence across geographies.
- Online Retail:Digital-native brands bypass supermarket margin stacking through owned e-commerce platforms. Subscription-based replacement programs lock recurring revenue in North American and Western European markets.
- Specialty Stores:Curated assortments with extended warranty positioning capture durability premiums. French cookware retailers stock hard-anodized gift-market ranges at 25-35% price elevation over conventional aluminum.
- Supermarkets:Mass-market shelf access sustains highest transaction volumes in emerging economies. India's organized retail expansion creates new points of sale in Kochi and comparable tier-2 urban centers.
- Wholesale:Foodservice distributors consolidate fragmented regional supplier networks around lifecycle cost metrics. North American multi-unit operators specify induction-compatible SKUs with guaranteed replacement cycles.
Supermarkets dominate transaction counts today; online retail shows steepest expansion trajectory on direct-to-consumer development.
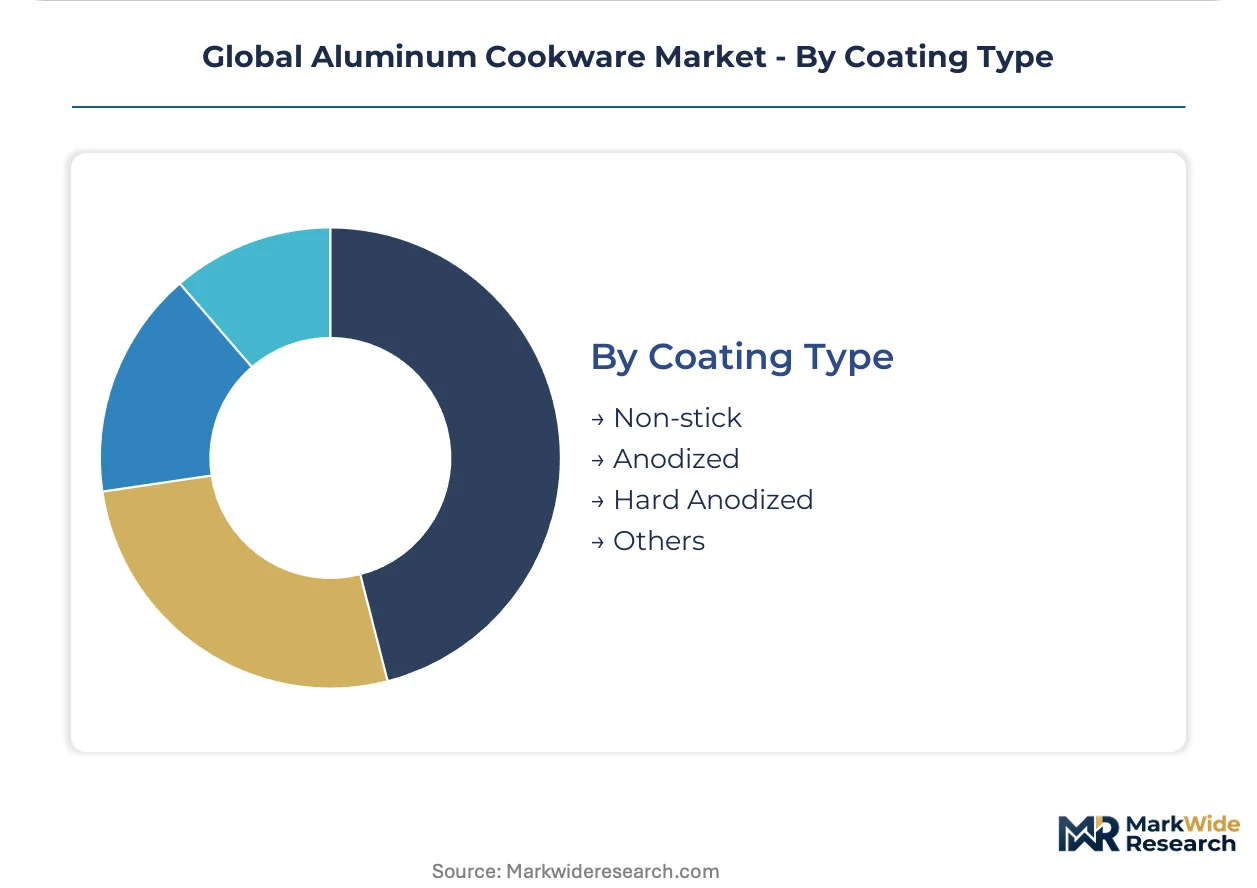
Coating Type:
Regulatory maturity separates compliant coating pathways from legacy formulation obsolescence.
- Non-stick:PTFE-based systems face REACH Annex XVII restrictions on perfluorinated compounds in European markets. R&D timelines extend 18-24 months for ECHA-compliant reformulation.
- Anodized:Conventional electrolytic surface treatments provide moderate corrosion resistance for standard domestic use. Asian fabricators license German and Italian coating technology for European market access.
- Hard Anodized:Advanced electrolytic processing extends product lifecycles by 40-60% versus conventional coatings. Technician scarcity at legacy European and Japanese facilities delays new production line staffing by 12-18 months.
- Others:Ceramic-silicone hybrid matrices and sol-gel systems eliminate PFAS dependency. Early movers capture regulatory-compliant positioning as FDA and EFSA parallel testing protocols stretch launch timelines.
Non-stick retains volume leadership today; hard-anodized coatings are expanding most quickly on durability premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cookware fabricators anchor European hard-anodizing capacity as REACH Annex XVII coating reformulations redirect procurement toward ceramic-reinforced alternatives. Restaurant chains in the United States accelerate aluminum fleet replacement under state-level energy codes. Indian metropolitan households drive induction-compatible demand as BIS certification validates safety claims.
United States
California and New York state energy codes favor aluminum thermal conductivity in commercial kitchen procurement. FDA food-contact surface regulations constrain non-stick coating formulations toward silicone-based alternatives. Meyer Corporation Limited anchors North American distribution through specialty retail partnerships in Chicago and Dallas-Fort Worth corridors.
Germany
Professional kitchens in Bavaria and North Rhine-Westphalia specify 18/10 stainless steel for acidic food preparation, compressing aluminum share in institutional procurement. ECHA classification of long-chain PFAS compounds forces 18-24 month R&D timelines for compliant coatings. Solingen and Bergisch Gladbach industrial clusters concentrate electrolytic bath chemistry expertise for hard-anodizing technology licensing.
India
Pune, Ahmedabad, and Kochi show underpenetrated organized retail access relative to Mumbai and Delhi saturation. BIS certification requirements for pressure cookware shape regional market access conditions. Hawkins Cookers Limited dominates South Asian pressure-cooker demand with localized alloy formulations from Thane and Bangalore facilities.
China
GB standards for heavy metal migration constrain coating chemistry pathways for export-bound fabricators. Primary aluminum smelter energy costs transmit directly to cookware alloy pricing without hedging mechanisms for smaller operators. Zhejiang and Guangdong provinces concentrate induction-base compatibility manufacturing for European and North American private-label contracts.
France
Luxury hospitality chains in Île-de-France standardize 4-5mm wall-thickness anodized ranges at tri-ply stainless price parity. EFSA-compliant coating reformulations redirect procurement toward ceramic-reinforced sol-gel systems. Groupe SEB leverages European manufacturing scale to sustain margin pools across hard-anodized product lines from Lyon-region facilities.
Global Aluminum Cookware Market Vendor Landscape
Global majors compete with regional champions across coating technology and distribution channel access. The vendor base separates into three tiers: European hard-anodizing specialists with process licensing revenue, North American foodservice distributors with lifecycle guarantee programs, and Asian fabricators competing on induction-base volume scale. Strategic moves concentrate on ceramic-silicone hybrid coating R&D partnerships and direct-to-consumer channel bypass of supermarket margin stacking.
Within the European specialist tier, Groupe SEB and Scanpan A/S exemplify hard-anodizing technology licensors to Asian fabricators seeking REACH-compliant market access. Among North American distributors, Meyer Corporation Limited anchors specialty retail positioning. Hawkins Cookers Limited occupies a dominant position in South Asian pressure-cooker segments through BIS-certified localized production.
| Leading Market Players |
|---|
| Tramontina S.A. Cutelaria |
| Scanpan A/S |
| Groupe SEB |
| Le Creuset Group AG |
| TTK Prestige Ltd. |
| Meyer Corporation Limited |
| All-Clad Metalcrafters, LLC |
| Hawkins Cookers Limited |
| Newell Brands Inc. |
| Others |
Supply Flow & Price Mechanics
State-level energy codes in California and New York are forcing restaurant chains to specify induction-compatible aluminum cookware with extended lifecycle guarantees, compelling suppliers to absorb hard-anodizing technician premiums and ceramic-coating R&D costs that compress margins on mid-tier contract bids.
Pricing Analysis
Primary aluminum smelter energy costs in China and Russia transmit directly to cookware alloy pricing through commodity pass-through clauses. Three-tier pricing structure across premium hard-anodized, standard anodized, and economy uncoated levels separates buyers by durability requirements and certification tier. Cost compression in economy segments is intensifying because smaller fabricators lack hedging mechanisms against alumina volatility. Quick-service restaurant procurement departments show lowest price sensitivity due to lifecycle cost accounting, while Indian tier-2 household segments exhibit highest sensitivity to unit price.
Supply Chain Analysis
India's phased manufacturing program and local-content rules for BIS-certified pressure cookware are redirecting component sourcing toward Thane and Bangalore alloy facilities. Raw material flows draw from Chinese primary aluminum, German electrolytic bath chemistry, and Italian ceramic-coating intermediates. Single-source vulnerability concentrates in hard-anodizing technician expertise at legacy European and Japanese facilities. Distribution runs through foodservice distributors consolidating fragmented regional networks in North America and organized retail expansion in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as restaurant procurement shifts from unit-price bidding to lifecycle cost metrics that reward durability-certified hard-anodized specifications.
For Market Incumbents: Anticipate stainless steel substitution pressure in German and French professional kitchens by deepening captive supply of ceramic-silicone hybrid coating capacity. Secure hard-anodizing technician pipelines through apprenticeship partnerships with Solingen and Bergisch Gladbach industrial clusters before staffing delays extend to 24 months. For New Entrants and Emerging Players: India's tier-2 urban households in Pune, Ahmedabad, and Kochi represent an underserved buyer archetype with underpenetrated organized retail access relative to metro saturation. White-space capture demands BIS-certified induction-base aluminum cookware distributed through supermarket shelf-space expansion rather than e-commerce premium positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with European hard-anodizing specialists possessing process licensing revenue from Asian fabricators seeking REACH-compliant market access. Long-term viability hinges on coating chemistry R&D partnerships eliminating PFAS dependency. Watch ECHA regulatory calendar acceleration as the inflection signal for compliant formulation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Silicone Coating R&D Partnership | Eliminates PFAS dependency ahead of ECHA Annex XVII enforcement timelines. |
| Hard-Anodizing Technician Apprenticeship Program | Addresses 12-18 month staffing delays at European and Japanese facilities. |
| Direct-to-Consumer E-Commerce Launch | Bypasses supermarket margin stacking through owned platform subscription models. |
| Induction-Base Manufacturing Scale-Up | Captures California and New York state energy code compliance demand. |
| BIS Certification Investment for Pressure Cookware | Unlocks organized retail shelf access in Indian tier-2 urban expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cookware procurement directors at North American restaurant chains, coating R&D leads at German and Italian technology licensors, and category buyers at Indian organized retail expansions with secondary validation from FDA food-contact filings, ECHA REACH Annex XVII updates, BIS certification registries, and customs trade data. Bottom-up alloy fabrication capacity estimates triangulated against top-down consumer expenditure tracking.
Historical reference periods anchored the projection horizon through segmented modeling across product type, coating chemistry tier, end-use intensity, and distribution channel. CAGRs derived from elasticity-adjusted volume forecasts incorporating primary aluminum price volatility coefficients and regulatory compliance cost schedules.
Underlying measurement precision varies by segment; hard-anodized and ceramic-silicone coating categories carry tighter precision than conventional non-stick given clearer regulatory compliance boundaries. Forecasts reflect assumptions about ECHA enforcement timing and Indian induction stove penetration curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Deodorizer Bag Market
Household Items
Plastic Carafe Market
Household Items
North America Car Air Freshener Market
Household Items
Remote Control Holder Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Ironing Boards Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Snow Blower Market
Household Items
Facial Tissue Market
Household Items
Alarm Clocks Market
Household Items
Beach Towel Market
Household Items
Command Hooks Market
Household Items
Home Use Air Purifiers Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Netherlands Cookware Market