
 Automatic Dishwashing Products Market | 2026-2036
Automatic Dishwashing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Dishwashing Products Market Outlook
The EU Green Deal is repositioning surfactant chemistry across European formulation houses. Procter & Gamble Co. leverages its captive enzyme supply chain to meet tightened biodegradability thresholds. Henkel AG & Co. KGaA anchors its position through concentrated pod formats that reduce packaging intensity. Unilever plc differentiates via refill systems designed for commercial dishwasher fleets.
Automatic dishwashing products are alkaline cleaning formulations engineered with enzymes, surfactants, and builders to remove food soils from dishware in mechanized wash cycles operating at 55–65°C. Their primary commercial purpose is to deliver spot-free sanitation at throughput rates exceeding manual washing by an order of magnitude. Pods now command the leading share of residential value pools due to dosing precision and storage convenience. The commercial application segment generates the fastest growth as foodservice operators automate back-of-house operations. Eco-friendly formulations capture expanding shelf space in European retail channels where REACH compliance functions as a de facto quality gate.
REACH in Europe and EPA Safer Choice in the United States both restrict phosphates and volatile organic compounds in rinse aid and detergent formulations. These frameworks compel reformulation cycles that favor suppliers with in-house toxicology and regulatory affairs capabilities. Stakeholders must monitor pending amendments to the EU Detergents Regulation that could mandate digital product passport disclosure for surfactant origin and biodegradation test results.
Market Dynamics
Formulation houses face simultaneous pressure from the EU Green Deal's biodegradability mandates and the operational throughput demands of automated commercial kitchens. This tension compresses R&D timelines while expanding the performance gap between legacy chemistries and next-generation enzyme-surfactant systems.
Growth Catalysts
- REACH compliance thresholds:Tightened surfactant biodegradability requirements under the EU Detergents Regulation are forcing incumbent suppliers to upgrade formulation capabilities, creating replacement demand for compliant chemistries.
- Foodservice automation:Industrial catering operators in Germany and France are retrofitting back-of-house operations with mechanized wash systems that require specialized alkaline formulations.
- Enzyme engineering advances:Protease and amylase stabilization at high-temperature wash cycles is enabling concentrated pod formats that reduce packaging mass and logistics costs.
Market Restraints
- Phosphate substitution costs:Builders derived from zeolites and citrates carry raw material premiums of 15-40% versus phased-out phosphate systems, compressing margin structures for mid-tier suppliers.
- Concentrated supplier base:Captive enzyme production is concentrated among three multinational chemical houses, creating supply security risks for independent formulation brands.
- Rinse aid performance gaps:Volatile organic compound restrictions under EPA Safer Choice limit solvent-based sheeting agents, leaving water-spot performance inferior to legacy formulations in hard-water regions.
Strategic Opportunities
- Digital product passport mandates:Pending EU Detergents Regulation amendments will require surfactant origin disclosure, favoring suppliers with blockchain-traceable supply chains and in-house toxicology databases.
- Commercial fleet refill systems:Unbundled concentrate delivery to institutional dishwasher fleets reduces per-wash packaging waste while locking in volume commitments through dispensing equipment contracts.
- Biotechnology convergence:CRISPR-engineered extremophile enzymes operating at 70°C+ wash temperatures enable sanitation claims without chlorine bleach, opening healthcare and childcare institutional segments.
Industry Challenges
- Formulation-toxicology talent scarcity:REACH registration dossier preparation requires specialized regulatory affairs capabilities that command salary premiums and extended recruitment timelines.
- Legacy equipment compatibility:Concentrated pod chemistries can damage older commercial dishwasher seals and heating elements, requiring field service retrofit programs that strain technical support organizations.
- Biodegradation testing bottlenecks:OECD 301B ready biodegradability certification timelines stretch 28-60 days, delaying product launches during peak seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Dishwashing Products Market |
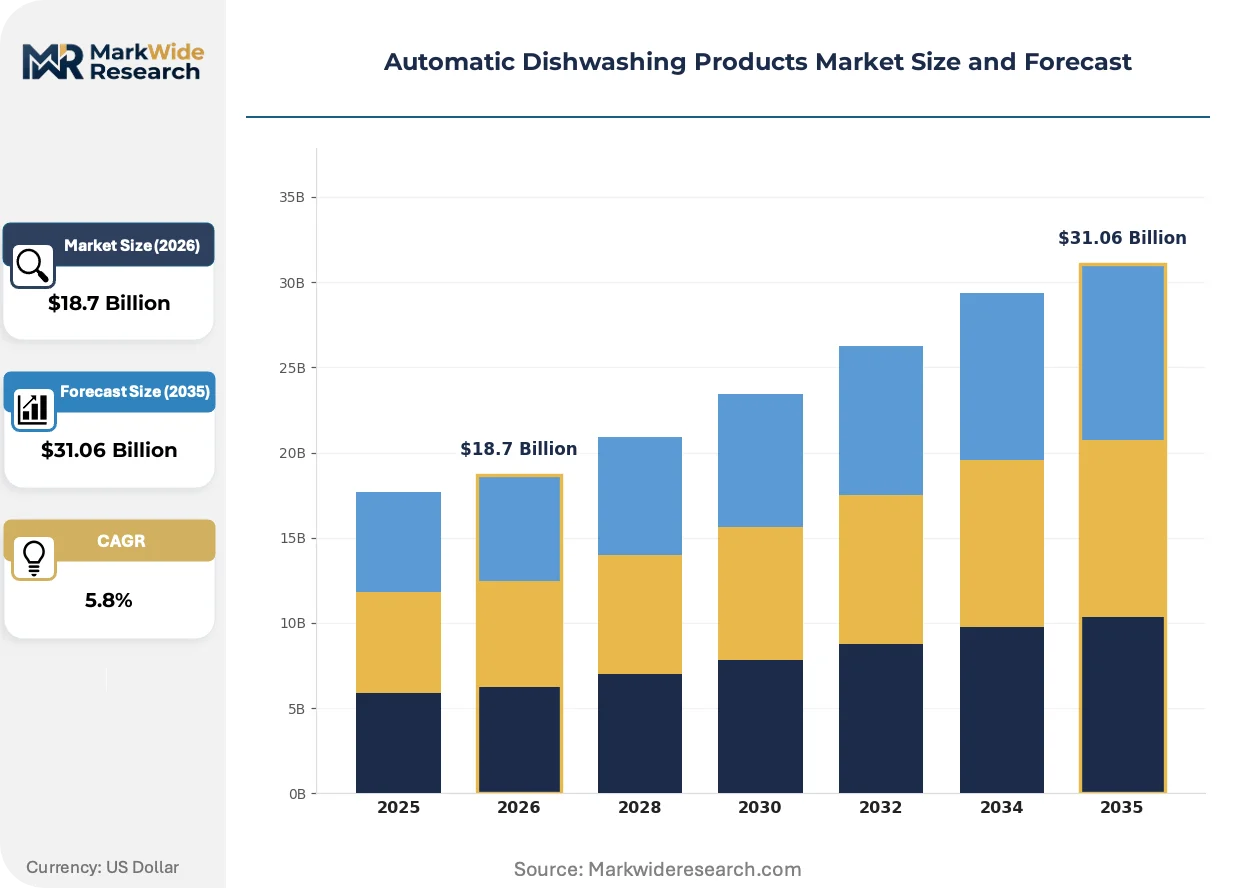
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergents, Powder Detergents, Pods, Rinse Aids Application: Residential, Commercial, Industrial, Institutional Form: Concentrated, Standard, Eco-friendly, High-Performance Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Henkel AG & Co. KGaA, Colgate-Palmolive Company, Procter & Gamble Co., Kao Corporation, The Clorox Company, Reckitt Benckiser Group plc, Church & Dwight Co., Inc., Godrej Consumer Products Limited, Unilever plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Dishwashing Products Market Strategic Shifts
Electrochemical activation systems are displacing traditional chemical dosing in premium commercial installations. This hardware-chemistry convergence is redrawing competitive boundaries between equipment OEMs and formulation suppliers.
Electrolyzed water generation is electrifying sanitation chemistry in high-throughput foodservice operations. Miele and Winterhalter are embedding on-site sodium hypochlorite generators into flight-type dishwashers, eliminating bulk chemical storage and delivery logistics. This technology is compressing the addressable market for conventional rinse aid formulations in institutional segments.
The EU Green Deal's Chemicals Strategy for Sustainability is accelerating substance restriction schedules ahead of REACH sunset dates. ECHA's microplastic labeling requirements for polymer-based encapsulation technologies are forcing pod manufacturers toward water-soluble film alternatives. German retail chains are responding by delisting non-compliant SKUs ahead of mandatory deadlines, concentrating shelf space among reformulation-capable suppliers.
Buyer consolidation among contract foodservice management companies is consolidating procurement authority at headquarters level. Sodexo and Compass Group are mandating corporate sustainability scorecards that weight cradle-to-gate carbon intensity above unit price. This behavioral shift is visible across Northern European catering contracts, where multi-year supply agreements now specify renewable surfactant content minimums and packaging recyclability thresholds.
Automatic Dishwashing Products Market Segmentation
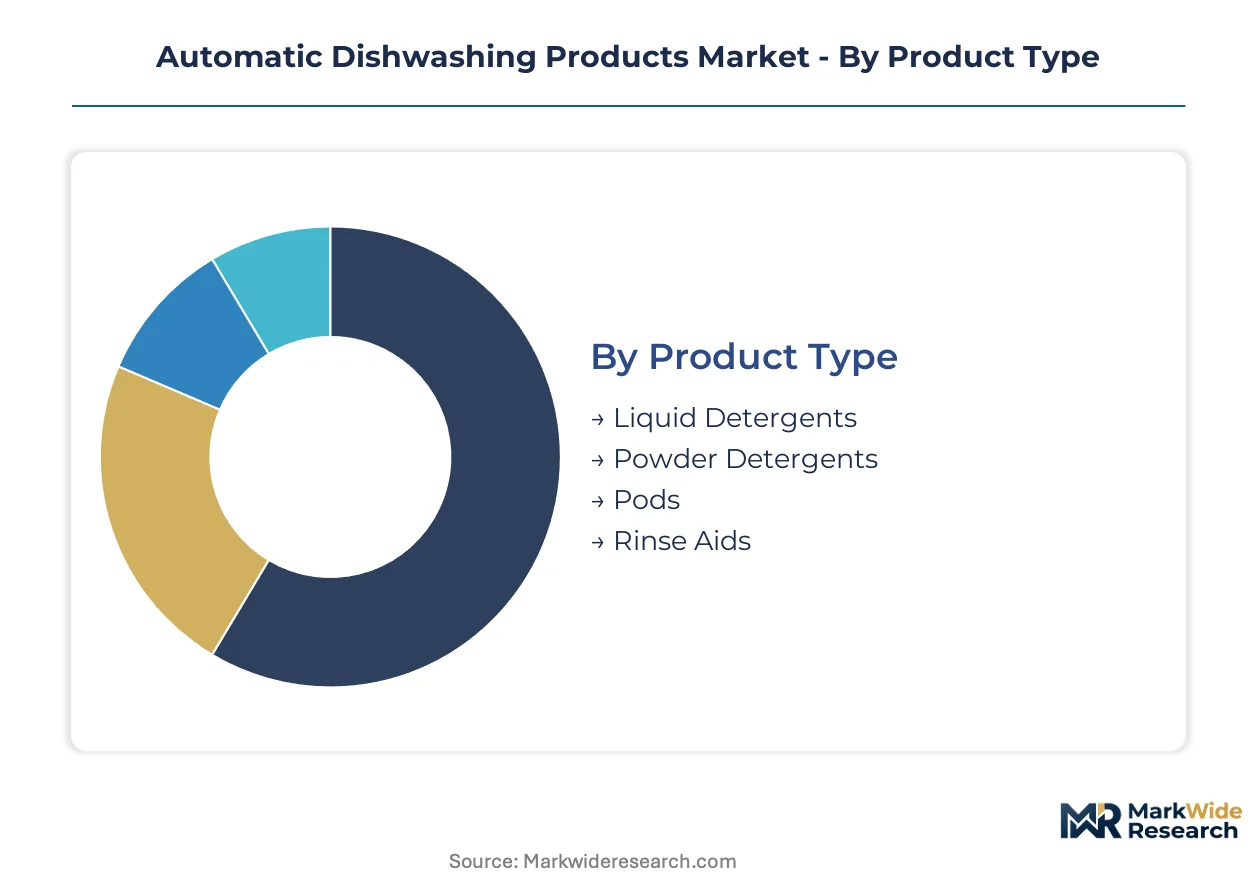
Automatic dishwashing products fragment across formulation chemistry, end-use intensity, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities.
Product Type:
Pods command premium shelf positioning while powders retain volume dominance in price-sensitive channels.
- Pods:Water-soluble PVA film encapsulates concentrated enzyme-surfactant blends for precise dosing. German and French retail chains are expanding facings for pod formats as ECHA microplastic labeling deadlines approach, favoring compliant film technologies.
- Liquid Detergents:Pump-dispensed alkaline formulations dominate commercial dishwasher installations requiring programmable dosing integration. Foodservice automation in Germany's industrial catering sector is concentrating procurement of bulk liquid systems with IoT-connected dispensers.
- Powder Detergents:Legacy builder-enzyme blends retain cost advantage in emerging markets with manual dosing equipment.
- Rinse Aids:Surfactant-based sheeting agents face EPA Safer Choice VOC restrictions that degrade hard-water performance.
Today's leader: Pods. Tomorrow's challenger: Liquid Detergents.
Application:
Commercial throughput requirements are diverging formulation specifications from residential convenience priorities.
- Commercial:Flight-type and rack conveyor systems in hospitality operations demand high-alkalinity formulations with rapid soil penetration at 60-65°C cycles. Procurement consolidation among contract foodservice operators is locking suppliers into multi-year dispensing equipment contracts.
- Residential:Pod and liquid formats compete on storage footprint and dosing error elimination. REACH-compliant surfactant biodegradability is becoming a de facto quality gate for shelf placement in EU retail.
- Industrial:Centralized kitchen operations in manufacturing and logistics facilities require bulk concentrate delivery with automated dilution systems.
- Institutional:Healthcare and childcare segments are specifying chlorine-free sanitation claims enabled by CRISPR-engineered extremophile enzymes operating above 70°C.
Commercial applications are expanding most quickly as back-of-house automation accelerates across Northern European foodservice.
Form:
Concentration intensity determines packaging mass, logistics cost, and compatibility risk with legacy equipment.
- Concentrated:Reduced water content formulations cut transport emissions and storage footprint. German industrial catering operators are mandating concentrated delivery to meet corporate carbon scorecard thresholds.
- Eco-friendly:Zeolite and citrate builders replace phosphates at 15-40% raw material premiums. EU Green Deal surfactant mandates are compressing R&D timelines for biodegradable alternatives.
- Standard:Conventional dilution levels retain equipment compatibility with older commercial dishwasher seals and heating elements.
- High-Performance:Enzyme-dense formulations target protein-heavy soil loads in protein-processing facilities and institutional kitchens.
Eco-friendly formulations are gaining share fastest as retail delisting of non-compliant SKUs concentrates shelf space among reformulation-capable suppliers.
Distribution Channel:
Procurement authority is shifting from decentralized store-level ordering to headquarters-negotiated supply agreements.
- Wholesale:Institutional and commercial volume flows through janitorial supply houses and foodservice distributors. Sodexo and Compass Group sustainability scorecards are embedding renewable surfactant minimums into contract terms.
- Online:Direct-to-consumer subscription models for pod refills are capturing urban households with storage constraints. E-commerce penetration is climbing fastest in markets with dense last-mile delivery infrastructure.
- Supermarkets:Mass retail remains the primary trial channel for new pod formats and eco-labeled variants.
- Specialty Stores:Premium appliance retailers bundle formulation trials with Miele and Winterhalter dishwasher sales.
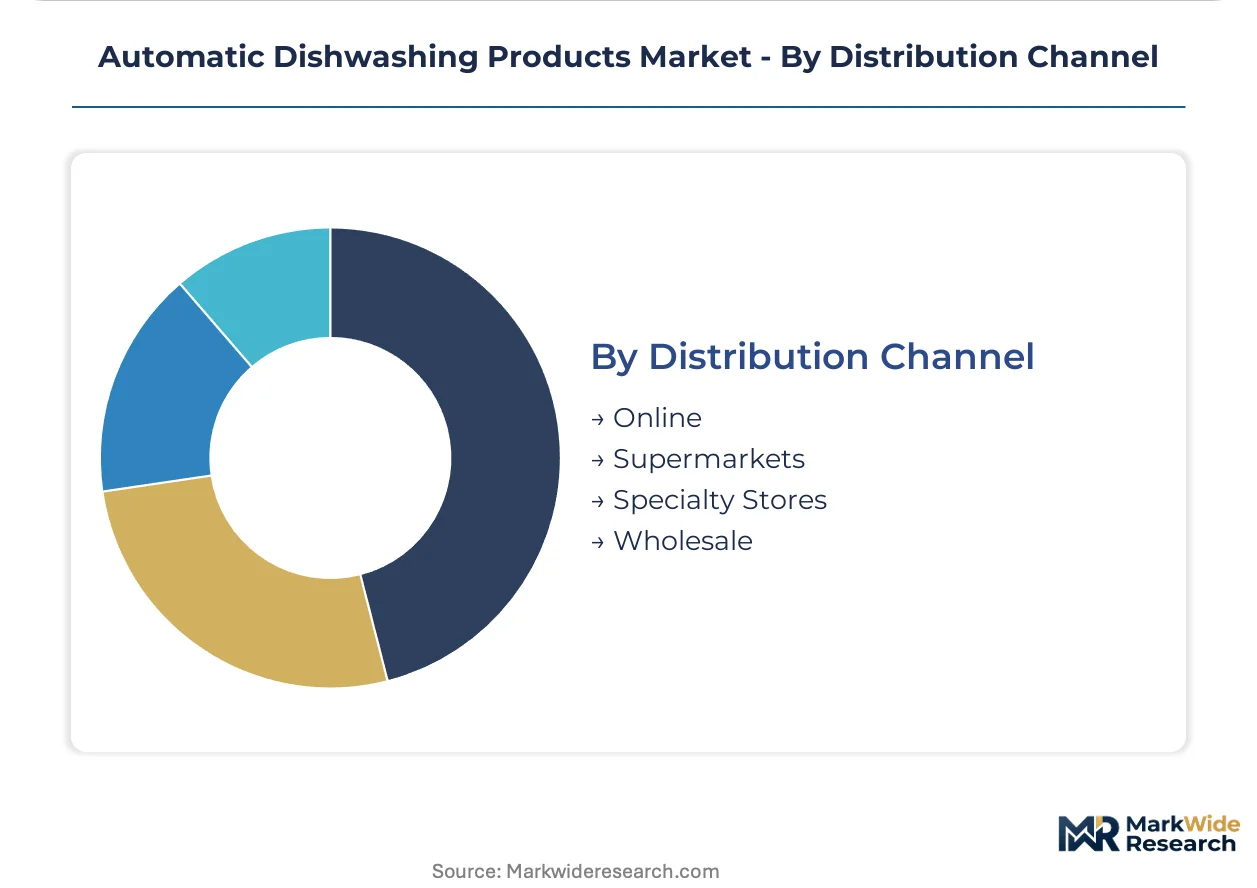
Wholesale retains volume leadership. Online is the steepest expansion trajectory as fleet refill systems lock in recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automatic dishwashing products industry traces its modern formulation roots to post-war Germany, where industrial chemical engineering scaled enzyme-surfactant systems for mechanized cleaning. Today, procurement patterns and regulatory frameworks diverge sharply across major national markets.
Germany
Industrial catering automation drives concentrated procurement of alkaline formulations for flight-type systems. ECHA's microplastic labeling requirements for polymer films are accelerating water-soluble pod adoption ahead of mandatory deadlines. The Rhine-Ruhr chemical corridor houses formulation R&D clusters where REACH dossier preparation capabilities concentrate.
United States
Foodservice management companies consolidate procurement through headquarters-level sustainability scorecards. EPA Safer Choice VOC restrictions on rinse aid formulations create performance gaps in hard-water regions. The Chicago metropolitan area anchors institutional catering contracts specifying renewable surfactant minimums.
France
Contract foodservice operators mandate cradle-to-gate carbon thresholds in multi-year supply agreements. ANSM maintains pharmaceutical-grade sanitation standards for healthcare institutional segments. The Lyon-Grenoble corridor specializes in high-temperature enzyme engineering for protein-heavy soil applications.
China
Dual carbon goals under MEE frameworks are tightening biodegradability disclosure for imported surfactant formulations. Manufacturing and logistics facilities automate centralized kitchen operations requiring bulk concentrate delivery. The Yangtze River Delta houses equipment OEMs embedding electrochemical activation systems into flight-type dishwashers.
United Kingdom
Post-Brexit regulatory divergence from REACH is creating parallel registration requirements for cross-channel suppliers. Compass Group headquarters in London negotiate sustainability-weighted procurement terms favoring refill system adoption. The Midlands industrial belt concentrates commercial dishwasher fleet operations for contract catering networks.
Automatic Dishwashing Products Market Competitive Environment
Capital-heavy producers with captive enzyme supply chains compete with asset-light formulation houses dependent on third-party biotechnology inputs. The market structure consolidates around three multinational chemical houses controlling protease and amylase production, while mid-tier suppliers face margin compression from phosphate substitution costs. Strategic archetypes span vertically integrated enzyme manufacturers, pod-format specialists, and commercial fleet service operators. Dominant competitive moves include dispensing equipment contract lock-ins and blockchain-traceable supply chain certification.
Among European-based formulation houses, Henkel AG & Co. KGaA and Unilever plc exemplify the pod-format and refill-system archetypes respectively. Procter & Gamble Co. occupies a position representing captive enzyme integration. These three entities anchor the premium-tier competitive vector where REACH compliance capabilities function as entry barriers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Colgate-Palmolive Company |
| Procter & Gamble Co. |
| Kao Corporation |
| The Clorox Company |
| Reckitt Benckiser Group plc |
| Church & Dwight Co., Inc. |
| Godrej Consumer Products Limited |
| Unilever plc |
| Others |
Value Chain & Pricing Dynamics
REACH dossier preparation specialists concentrated in Germany's Rhine-Ruhr chemical corridor command salary premiums that widen pricing spreads between compliant premium tiers and cost-optimized economy formulations. Labor-cost differentials in regulatory affairs capabilities directly feed into tiered pricing architectures across European formulation markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified enzyme-surfactant blends from phosphate-legacy formulations and generic builder systems. Price differentiation hinges on biodegradability certification tier and captive enzyme integration depth. Cost compression in mid-tier supply is intensifying because zeolite and citrate builder substitution erodes margin structures. Contract foodservice operators exhibit lowest price sensitivity due to sustainability scorecard mandates, while independent janitorial distributors face acute cost pressure.
Supply Chain Analysis
Biodegradability certification gating under OECD 301B protocols restricts supplier qualification timelines and concentrates procurement authority among dossier-capable houses. Protease and amylase production anchors in Germany, Denmark, and the Netherlands, while surfactant feedstocks draw from Belgium and France. Single-source vulnerability in extremophile enzyme strains sourced from specialized biotechnology houses elevates supply security risk. Distribution runs through janitorial supply houses and foodservice distributors with IoT-connected dispensing equipment contracts locking in recurring volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Detergents Regulation amendments mandating digital product passport disclosure are accelerating replacement demand for traceable supply chains.
For Market Incumbents: To counter electrochemical activation systems displacing conventional rinse aid formulations, deepen backward integration into CRISPR-engineered enzyme platforms and secure blockchain-traceable surfactant sourcing. Capacity addition in France's Lyon-Grenoble corridor addresses high-temperature protein-soil applications while building regulatory dossier depth. For New Entrants and Emerging Players: Independent contract caterers in Central and Eastern Europe represent the most penetrable buyer archetype underserved by incumbent dispensing equipment contracts. White-space targets include bulk concentrate delivery with automated dilution systems for manufacturing facility kitchens and chlorine-free sanitation claims for childcare institutional segments. Direct fleet refill subscriptions bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Specialty chemical houses with captive biotechnology assets are the most active acquirer in this space, consolidating formulation capabilities and enzyme supply security. Long-term viability favors targets with in-house REACH registration infrastructure and established dispensing equipment installed bases. The signal to monitor is ECHA microplastic labeling enforcement timing triggering retail delisting waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Biotechnology | Captive protease supply secures formulation autonomy against three-house concentration risk. |
| Digital Product Passport Compliance Infrastructure | Blockchain-traceable surfactant origin disclosure satisfies pending EU Detergents Regulation amendments. |
| Commercial Fleet Refill System Deployment | Unbundled concentrate delivery locks volume through dispensing equipment contracts with Sodexo and Compass Group. |
| High-Temperature Enzyme Engineering Investment | CRISPR-engineered extremophile strains enable chlorine-free sanitation claims in healthcare segments. |
| Water-Soluble Film Technology Transition | PVA alternatives to polymer encapsulation preempt ECHA microplastic labeling delisting risk. |
Study Parameters
Direct dialogue with formulation R&D directors, regulatory affairs leads at REACH-registered houses, procurement managers at contract foodservice operators, and distribution channel partners grounded qualitative assessment. Secondary validation drew from ECHA substance registration databases, EU Detergents Regulation amendment tracking, customs trade flows for surfactant feedstocks, and SEC filings of listed chemical houses. Bottom-up volume modeling across pod, liquid, powder, and rinse aid formats triangulated against top-down value estimates from wholesale and retail channel audits.
Top-down macroeconomic anchoring informed bottom-up segment projections across the analysis window. Segmentation dimensions modeled include formulation chemistry type, end-use intensity tier, procurement channel structure, and regional regulatory cluster alignment. CAGRs were derived from slope-intercept analysis of historical trajectory and policy-driven inflection points. Industry-specific forecast inputs incorporated biodegradability certification timelines and foodservice automation penetration curves.
Underlying measurement precision varies by segment; commercial application data carries tighter precision than emerging market residential estimates due to procurement concentration. Forecasts reflect assumptions regarding ECHA enforcement timelines and enzyme stabilization technology maturation. A model refresh is warranted upon material change in EU Detergents Regulation amendment adoption schedules or electrochemical activation system cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Commercial Lawnmower Market
Household Items
Insulated Drinkware Market
Household Items
Asean Cookware Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Fine Mist Sprayer Market
Household Items
Drinkware Accessories Market
Household Items
Global Rimless Toilets Market
Household Items
Neck Pillows Market
Household Items
France Digital Showers Market
Household Items
Alarm Clocks Market
Household Items
Robotic Pool Cleaner Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Bristle Brush Market
Household Items
Nebulizing Diffuser Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Hangers Market