
 Barbecue Grill Market | 2026-2036
Barbecue Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Barbecue Grill Market Analysis
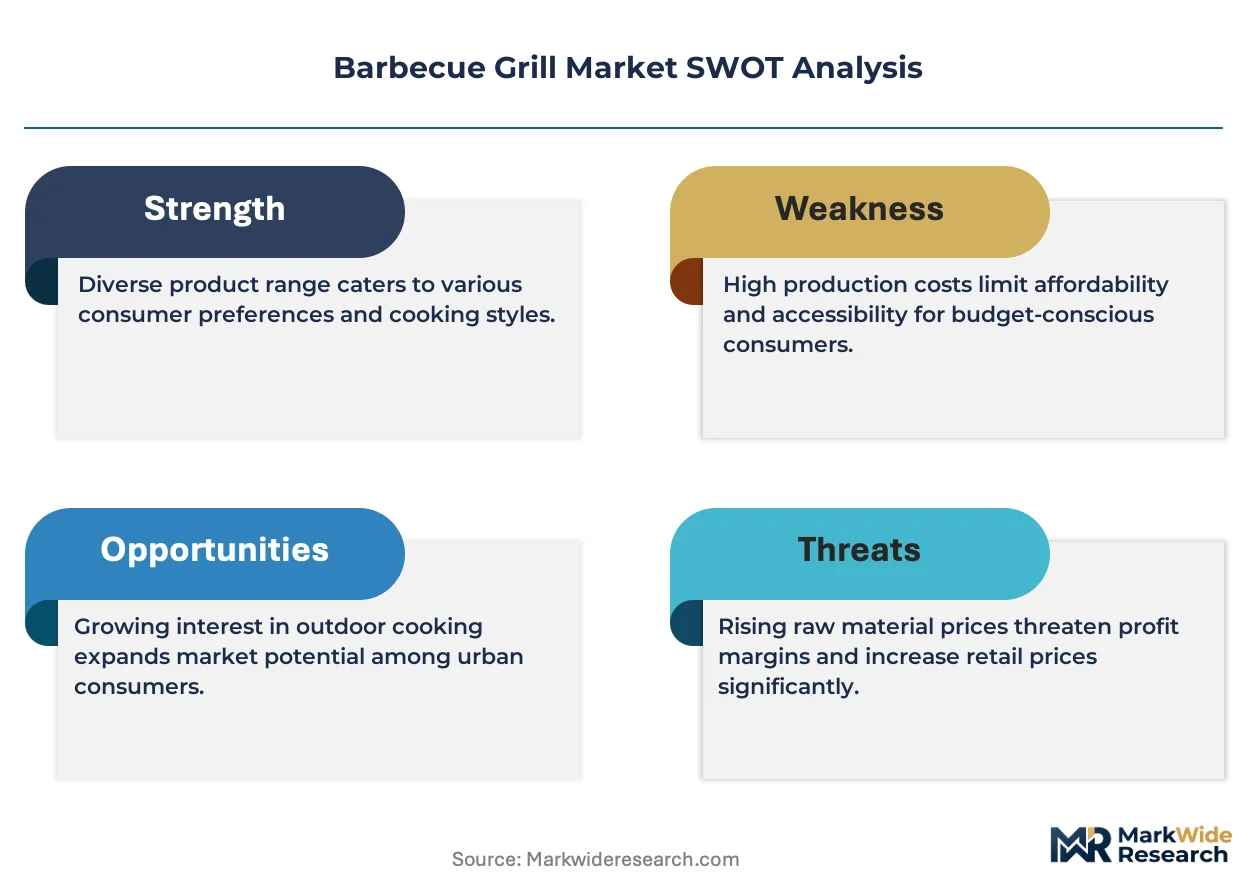
Skilled metal fabrication labor availability is reorganizing production capacity across the barbecue grill industry. Weber sustains brand dominance through dedicated channel partnerships with home improvement retailers. Napoleon leverages in-house stainless steel forming to control cost structures. Kamado Joe specializes in ceramic kamado construction, occupying a defensible premium niche against commodity competitors.
A barbecue grill is a cooking appliance designed for outdoor use, typically constructed from cast iron, stainless steel, or ceramic with temperature control ranging from low smoking at 225°F to searing above 500°F. Its primary purpose is to prepare food through direct radiant heat or indirect convection for residential entertainment and commercial foodservice operations. Gas grills lead volume sales due to convenience, while charcoal and kamado variants command the highest margin pools among enthusiast buyers. Electric grills represent the fastest-growing product type as urban fire codes and balcony restrictions proliferate across dense metropolitan housing.
EPA standards on volatile organic compound emissions affect gas grill burner design and certification requirements for US manufacturers. CE marking under EU safety directives governs electrical grill exports into European markets, while Australia's ACCC product safety mandates shape import compliance for international brands. Stakeholders must monitor evolving municipal fire ordinances and energy efficiency labeling programs that will determine which fuel types retain market access in key metropolitan zones.
Market Dynamics
Skilled metal fabrication labor availability is reorganizing production capacity across the barbecue grill industry. EPA emissions guidelines and evolving state-level carbon thresholds are reshaping gas-to-electric migration paths. Residential outdoor kitchens are driving stronger unit demand across suburban North America.
Growth Catalysts
- EPA Volatile Organic Compound Standards:Emissions guidelines on gas grill burner design are accelerating certification investments among US manufacturers seeking compliant product lines.
- Ceramic Kamado Construction:Premium ceramic insulation technology commands enthusiast buyer loyalty through superior heat retention and smoking precision.
- Suburban Patio Culture:Residential outdoor kitchen installations in the United States are expanding addressable unit demand for built-in grill configurations.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 430 stainless price swings compress margin predictability for manufacturers dependent on commodity metal sourcing.
- Fire Code Fragmentation:Municipal balcony restrictions and urban fire ordinances in dense metropolitan zones limit gas grill access and complicate distribution planning.
- Electric Grill Performance Ceiling:Wattage constraints on residential circuits cap sear temperatures below 450°F, restricting electric adoption among serious outdoor cooks.
Strategic Opportunities
- German Premium Patio Expansion:Underpenetrated outdoor kitchen penetration in German suburban developments offers white space for built-in grill system suppliers.
- EU Energy Efficiency Labeling:The EU Green Deal appliance standards create regulatory tailwind for electric grill certification and retail placement advantages.
- Direct-to-Consumer Assembly Models:Modular flat-pack shipping formats are opening e-commerce channels previously blocked by freight costs for assembled units.
Industry Challenges
- Welding and Metal Forming Talent Scarcity:Skilled stainless steel fabrication labor shortages constrain production scaling in traditional manufacturing clusters.
- Multi-Jurisdiction Certification Timelines:CE marking, EPA certification, and ACCC compliance create overlapping testing requirements that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barbecue Grill Market |
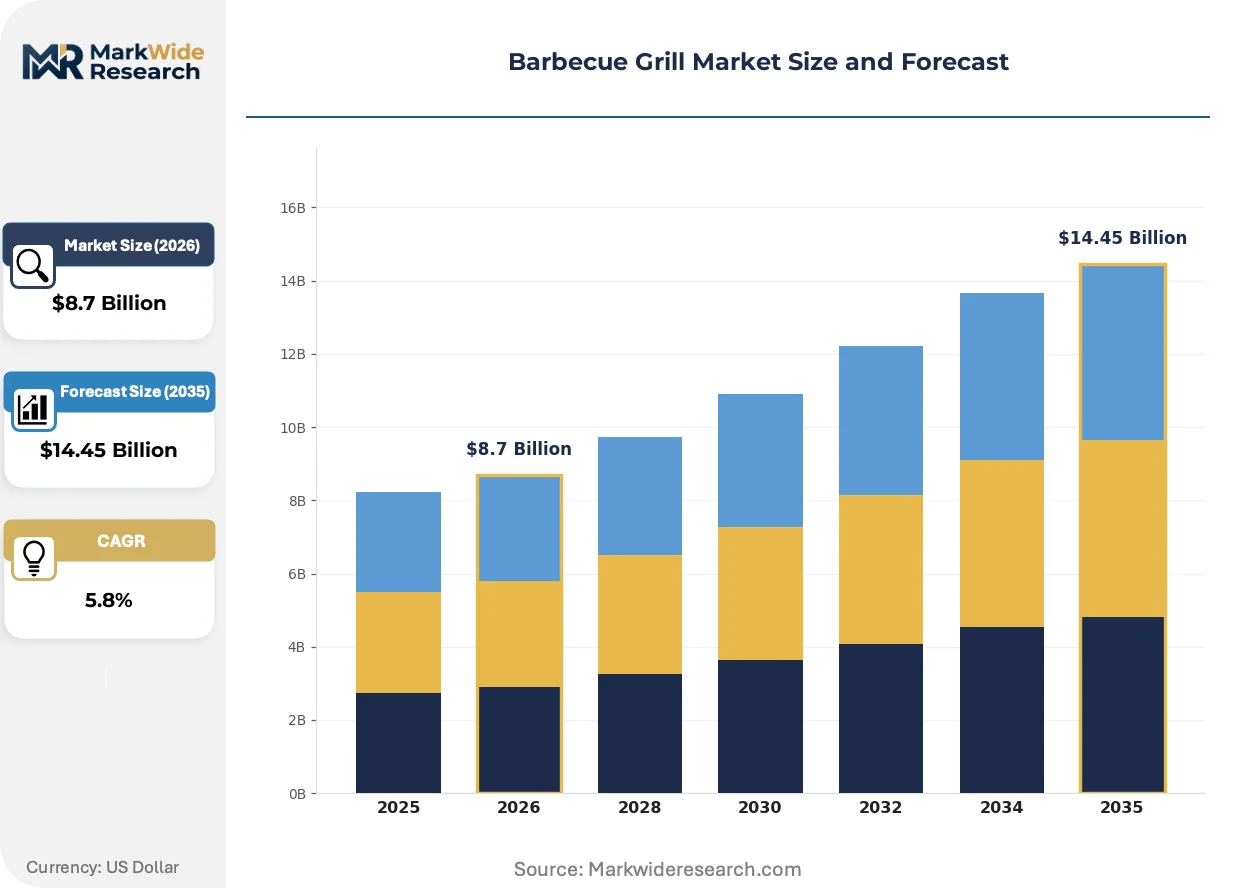
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charcoal Grills, Gas Grills, Electric Grills, Portable Grills Fuel Type: Natural Gas, Propane, Wood, Charcoal End User: Residential, Commercial, Catering, Outdoor Enthusiasts Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Napoleon, Fire Magic, Weber, Kamado Joe, Lynx Grills, Traeger, Big Green Egg, Masterbuilt Grills, Char-Broil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barbecue Grill Market Emerging Trajectories
Smart temperature control systems and connected cooking platforms are transforming how enthusiasts interact with outdoor appliances. Fuel type diversification is accelerating as regulatory pressure and urban density reshape permissible equipment categories.
Infrared sear burner technology is decomposing the traditional gas grill category by enabling restaurant-grade crust formation at residential price points. Enthusiast buyers in the United States and Australia are adopting hybrid infrared-convection configurations at accelerated replacement cycles. This thermal engineering shift is compressing the performance gap between premium gas systems and commercial equipment.
CE marking under EU safety directives is tightening electrical grill export requirements into European markets. Manufacturers must now demonstrate electromagnetic compatibility and thermal safety beyond prior voluntary standards. German and French importers are demanding pre-certified platforms to avoid customs detention and retailer liability exposure.
Subscription-based fuel and accessory replenishment is altering how kamado and pellet grill owners maintain equipment. Direct-to-consumer consumables programs are displacing seasonal retail purchasing patterns among high-engagement user segments. This behavioral shift is most visible in US metropolitan markets where balcony restrictions have already driven electric and compact fuel system adoption.
Barbecue Grill Market Segmentation
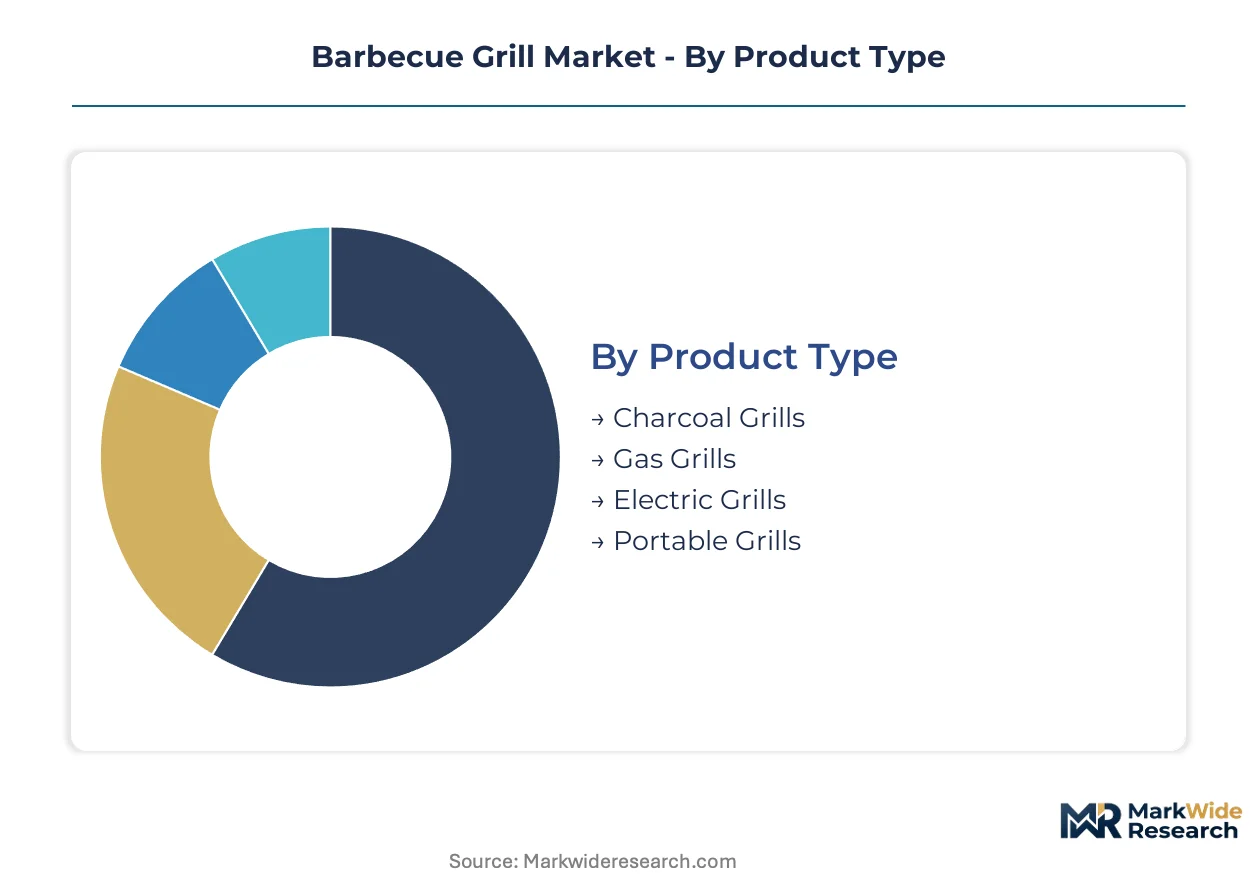
Barbecue grill segmentation reveals how fuel regulations, cooking performance expectations, and installation constraints partition buyers into distinct procurement groups. Each dimension carries different margin profiles and replacement cycle dynamics that reshape manufacturer prioritization.
Product Type:
Gas grills face the most acute substitution pressure from electric alternatives as municipal fire codes tighten across dense metropolitan housing stock.
- Gas Grills:Burner systems fueled by propane or natural gas deliver ignition convenience and temperature precision through control valve engineering. Demand concentrates in United States suburban developments where outdoor kitchen installations require built-in configurations and natural gas line connectivity. EPA volatile organic compound standards are accelerating burner redesign investments among domestic manufacturers seeking compliant certification.
- Electric Grills:Resistive heating elements powered by standard residential circuits eliminate combustion emissions and satisfy balcony restrictions in high-rise buildings. Demand concentrates in German and French urban centers where EU energy efficiency labeling programs create retail placement advantages for certified platforms. Wattage constraints on residential circuits cap sear temperatures below 450°F, restricting adoption among serious outdoor cooks seeking crust formation performance.
- Charcoal Grills:Combustion of lump hardwood or briquettes generates radiant heat for traditional smoking and searing applications with minimal mechanical complexity.
- Portable Grills:Compact folding designs with reduced cooking surface area target camping, tailgating, and balcony deployments where storage constraints dominate purchase criteria.
Gas grills retain volume leadership; electric grills hold the steepest expansion curve.
Fuel Type:
Supply concentration and infrastructure availability determine which fuel types retain market access in key metropolitan zones.
- Propane:Liquefied petroleum gas in portable cylinder format enables grill deployment without fixed infrastructure, dominating United States residential replacement cycles.
- Natural Gas:Permanent utility line connections eliminate cylinder exchange logistics and fuel cost volatility for dedicated outdoor kitchen installations.
- Wood:Hardwood logs and pellets deliver smoke flavor compounds prized by enthusiast segments for barbecue competitions and precision smoking applications.
- Charcoal:Carbonized wood briquettes or lump hardwood provide high-heat searing capability with minimal equipment cost, retaining strong share in emerging markets.
Propane dominates transaction volume; natural gas captures the highest attachment rates in new construction.
End User:
Application requirements diverge sharply between entertainment-focused residential buyers and throughput-optimized commercial operators.
- Residential:Homeowners prioritize aesthetic integration with patio architecture and cooking versatility for entertainment occasions across suburban United States markets.
- Commercial:Restaurants and foodservice operations demand stainless steel construction, high-BTU output, and rapid recovery times for sustained production volumes.
- Catering:Mobile foodservice providers require transportable equipment with quick setup protocols and multi-fuel flexibility for venue restrictions.
- Outdoor Enthusiasts:Camping and tailgating participants prioritize weight reduction and packed volume over cooking surface area or temperature precision.
Residential commands absolute unit volume; commercial generates the highest revenue per transaction.
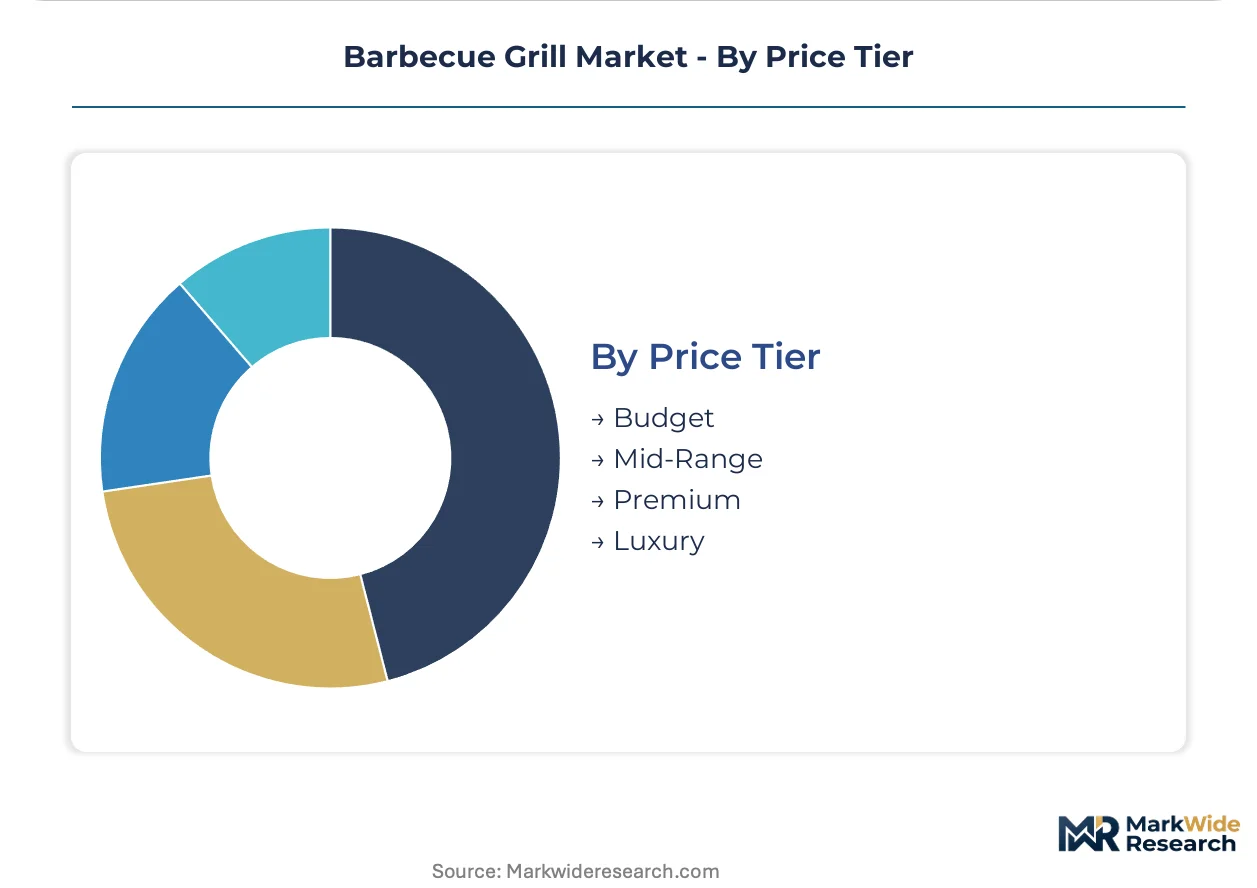
Price Tier:
Certification grade and material specification stratify pricing across performance and durability expectations.
- Premium:304-grade stainless steel construction, infrared sear zones, and smart temperature connectivity target enthusiast buyers in Australian and German markets.
- Mid-Range:Porcelain-enameled steel or 430-grade stainless components balance weather resistance with accessible price points for replacement-driven purchases.
- Budget:Painted carbon steel and simplified burner configurations serve infrequent users and price-sensitive first-time buyers.
- Luxury:Custom fabrication, integrated refrigeration, and outdoor kitchen system integration command project-based specification in high-end residential construction.
Mid-Range captures the largest transaction count; Premium climbs the fastest on replacement cycle compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions guidelines on volatile organic compounds are reshaping burner certification requirements across United States manufacturing clusters. Suburban outdoor kitchen installations in North America, German premium patio developments, and Australian enthusiast markets are concentrating unit demand.
United States
Residential outdoor kitchen installations in Texas and Florida suburbs are expanding demand for built-in natural gas configurations. EPA volatile organic compound standards are accelerating burner redesign investments among domestic manufacturers seeking compliant certification. Manufacturing capacity concentrates in Illinois and Wisconsin metal fabrication clusters where skilled welding labor availability constrains production scaling.
Germany
Underpenetrated suburban developments in Bavaria and Baden-Württemberg offer white space for premium built-in grill system suppliers. EU Green Deal appliance standards under the EU energy efficiency labeling program create regulatory tailwind for electric grill certification and retail placement advantages. Stuttgart and Munich metropolitan zones are witnessing accelerated patio culture adoption among high-income households.
Australia
Enthusiast buyers in Sydney and Melbourne are adopting hybrid infrared-convection configurations at compressed replacement cycles. ACCC product safety mandates shape import compliance requirements for international brands entering Australian distribution channels. Queensland and Western Australia mining corridor communities sustain strong demand for heavy-duty stainless steel construction.
Canada
Urban balcony restrictions in Toronto and Vancouver high-rise developments are accelerating electric grill adoption among metropolitan households. Health Canada product safety regulations govern electrical appliance certification for residential outdoor equipment. Ontario manufacturing clusters near Kitchener-Waterloo retain metal fabrication capacity serving North American supply chains.
France
Paris metropolitan balcony fire ordinances are limiting gas grill access and complicating distribution planning for combustion-based equipment. CE marking requirements under EU safety directives tighten electrical grill export compliance for manufacturers targeting French retail channels. Lyon and Marseille suburban developments are emerging as secondary demand centers for compact electric configurations.
Barbecue Grill Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the barbecue grill industry. The market structure stratifies into three tiers: mass-market volume players, premium enthusiast specialists, and luxury outdoor kitchen system integrators. Ceramic kamado constructors, infrared thermal engineering specialists, and stainless steel fabrication scale operators represent the dominant strategic archetypes. Competitive moves concentrate on channel partnership exclusivity with home improvement retailers and backward integration into in-house stainless steel forming capacity.
Among North American heritage brands, Weber exemplifies the mass-market volume archetype through dedicated retail channel anchoring. Napoleon represents the fabrication-integrated specialist model with captive stainless steel forming operations. Kamado Joe occupies the premium ceramic construction niche against commodity competitors. These three anchors illustrate how brand positioning, manufacturing control, and thermal engineering specialization segment competitive terrain.
| Leading Market Players |
|---|
| Napoleon |
| Fire Magic |
| Weber |
| Kamado Joe |
| Lynx Grills |
| Traeger |
| Big Green Egg |
| Masterbuilt Grills |
| Char-Broil |
| Others |
Supply Flow & Price Mechanics
Stainless steel fabrication scale in Illinois and Wisconsin metalworking clusters concentrates cost-efficient burner housing production among established manufacturers, while smaller competitors absorb margin compression from commodity grade 304 and 430 price swings. This capacity concentration creates asymmetric pricing power where scale operators defend floor prices through captive forming operations, and volume buyers extract concessions through multi-year procurement commitments.
Pricing Analysis
United States premium patio installations command 40-60% price spreads over German compact electric configurations due to built-in natural gas infrastructure and outdoor kitchen system bundling. Three-tier pricing structure across premium, standard, and economy levels separates 304-grade stainless infrared systems from porcelain-enameled replacement units and painted carbon steel entry products. Cost compression in mid-range tiers is intensifying because of Chinese import competition and freight-normalized flat-pack assembly models. Budget-tier residential buyers in North American suburbs exhibit highest price sensitivity, while Australian enthusiast segments accept premium positioning for ceramic kamado construction and hybrid thermal engineering.
Supply Chain Analysis
Shanghai-Ningbo port congestion and trans-Pacific container volatility constrain just-in-time delivery schedules for Asian-sourced burner valves and ignition components. Manufacturing gravity centers on China for stamped steel components, Italy for precision gas valves, and domestic Illinois-Wisconsin clusters for stainless steel welding and final assembly. Raw material dependencies span Indonesian nickel for 304-grade stainless, Australian iron ore for carbon steel housings, and Taiwanese electronic ignition modules. Single-source vulnerability concentrates in precision gas valve machining where European specialty suppliers dominate certification-compliant production. Distribution runs through home improvement retail anchoring in the United States, specialized outdoor living dealers in Germany, and direct-to-consumer flat-pack e-commerce channels accelerating across metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Welding and metal forming talent scarcity in traditional manufacturing clusters constrains production scaling for premium stainless construction, creating defensive moats for incumbents with captive fabrication capacity and entry barriers for capital-constrained challengers.
For Market Incumbents: Shield margin structures through backward integration into stainless steel forming operations in Illinois and Wisconsin fabrication clusters, locking in burner housing supply against commodity metal volatility. Accelerate EPA-compliant burner certification investments ahead of state-level carbon threshold tightening to preempt regulatory displacement by electric alternatives. Channel control through exclusive home improvement retail partnerships remains the priority lever against direct-to-consumer entrants. For New Entrants and Emerging Players: CE marking fast-track for electric grill platforms opens regulatory-compliant entry into German and French metropolitan markets where balcony restrictions already constrain gas equipment access. Target underpenetrated Bavarian and Baden-Württemberg suburban developments for premium built-in system deployment, leveraging modular flat-pack shipping formats to bypass freight-cost barriers that block assembled unit e-commerce. Direct-to-consumer assembly models with subscription-based consumables replenishment capture high-engagement kamado and pellet grill owners. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic insulation specialists and infrared thermal engineering platforms over commodity gas burner assemblers as enthusiast replacement cycles compress and performance differentiation intensifies. Long-term viability over the next decade hinges on regulatory optionality across fuel types and manufacturing footprint flexibility between domestic fabrication and Asian component sourcing. The signal to watch is municipal fire ordinance proliferation in dense metropolitan zones, which will determine whether electric-certified portfolios command valuation premiums against gas-dependent legacy assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forming | Captive 304-grade supply shields margins against commodity volatility in Illinois-Wisconsin clusters. |
| EPA-Compliant Burner Certification Investment | Volatile organic compound standards from EPA secure market access as state carbon thresholds tighten. |
| Direct-to-Consumer Flat-Pack Assembly Launch | Modular shipping formats bypass freight cost barriers blocking e-commerce for assembled grill units. |
| Electric Grill CE Marking Fast-Track | EU safety directive compliance unlocks German and French metropolitan retail placement advantages. |
| Subscription-Based Consumables Program | Recurring fuel and accessory revenue displaces seasonal retail patterns among high-engagement kamado owners. |
Methodological Framework
The analysis maps gas grill burner systems, electric resistive heating platforms, ceramic kamado construction, and portable folding configurations, each validated through fabrication plant managers, home improvement retail category buyers, outdoor kitchen installation contractors, and EPA regulatory affairs specialists. Primary interview data from these stakeholder roles triangulates against customs and trade records for stainless steel and aluminum import flows, SEC 10-K disclosures from listed appliance manufacturers, EPA certification registry databases, and EU energy efficiency labeling program documentation. Bottom-up unit demand modeling across suburban housing starts and replacement cycle analysis reconciles with top-down manufacturer revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation dimensions spanning fuel type, installation configuration, price tier, and metropolitan regulatory environment. CAGRs derive from fitted growth curves incorporating housing construction permits, patio culture adoption indices, and municipal fire ordinance diffusion patterns. Industry-specific forecast inputs include skilled welding labor availability constraints in traditional manufacturing clusters and evolving EPA volatile organic compound compliance timelines.
Underlying assumptions cover sustained suburban outdoor kitchen installation rates, stable stainless steel commodity price bands, and gradual electric grill performance improvement, with deviation risk concentrated in accelerated municipal fire code tightening and trans-Pacific logistics disruption. Practitioners should keep alternative scenarios live as EPA state-level carbon threshold evolution and EU Green Deal appliance standard implementation trajectories clarify.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Tablet Tissue Paper Market
Household Items
Electric Air Freshener Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Acrylic Aquarium Market
Household Items
Portable Car Vacuum Market
Household Items
Infrared Sauna Heaters Market
Household Items
Fan Market
Household Items
Toilet Care Wipes Market
Household Items
Disposable Napkins Market
Household Items
Air Purifier Market
Household Items
Massage Pillow Market
Household Items
Insulated Tumblers Market
Household Items
North America Water Purifier Market
Household Items
Smart Bathtub Market
Household Items
Consumerware Market
Household Items
Dry and Wet Wipes Market