
 Egypt Major Home Appliances Market | 2026-2036
Egypt Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Major Home Appliances Market Foresight
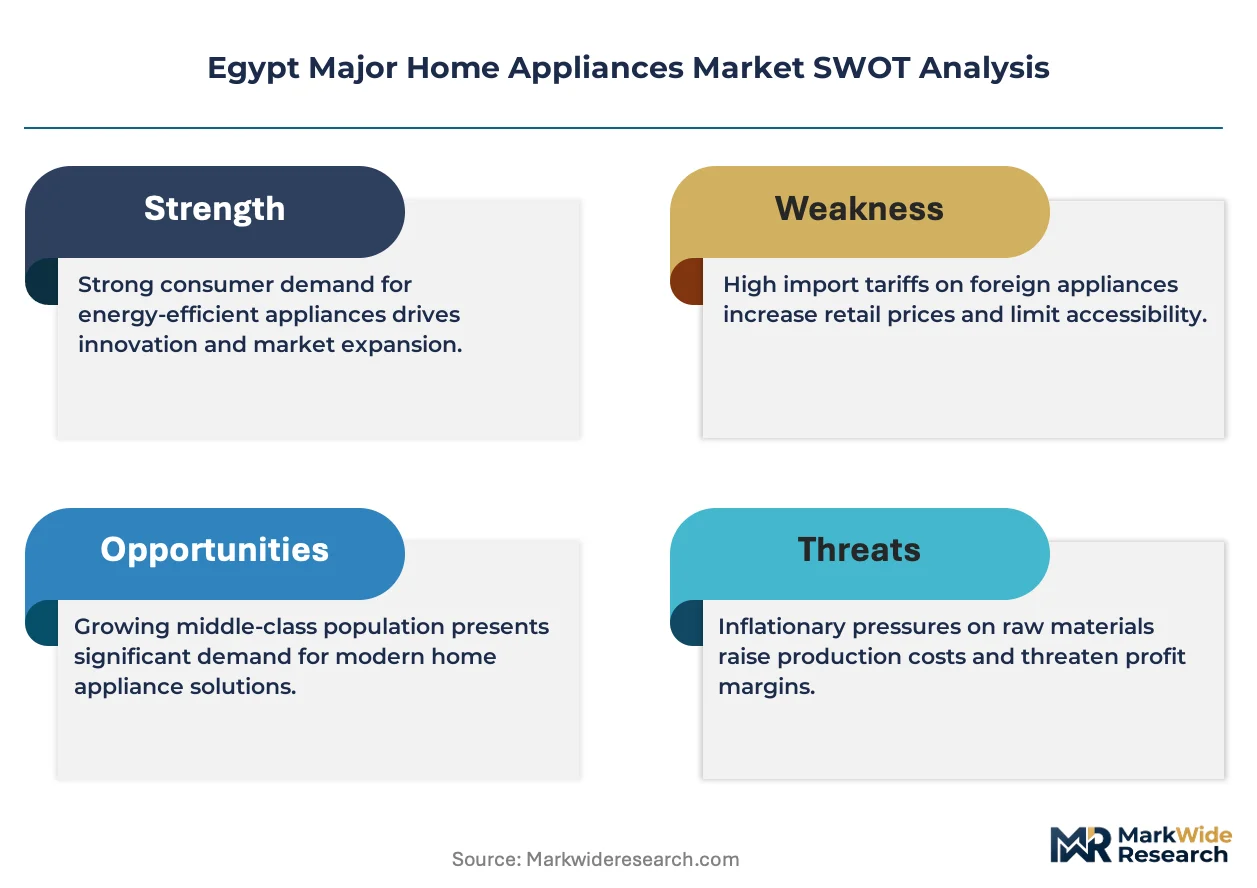
A capital-intensity divergence between local assembly operations and fully integrated manufacturing is redrawing competitive boundaries in Egypt's major home appliances sector. LG Electronics leverages its inverter compressor R&D to sustain technology leadership in air conditioner segments. Fresh Electric anchors its position through geographic dominance in Upper Egypt distribution networks. Elaraby Group competes by controlling localized assembly lines that reduce import duty exposure.
Egypt major home appliances encompass electrically powered durable goods designed for domestic and commercial environments, typically operating on 220-240V/50Hz single-phase supply with energy efficiency ratings governed by mandatory labeling protocols. Refrigerators and air conditioners represent the largest product type segments, with inverter-based cooling systems capturing margin pools as electricity tariffs escalate. Smart appliances and IoT-enabled units constitute the fastest-growing technology segment, though conventional models still dominate volume in budget and discount price tiers across residential end users.
The Egyptian Organization for Standardization and Quality enforces mandatory energy performance standards, while the Industrial Development Authority regulates local content requirements for assembly operations. These frameworks shape demand by restricting non-compliant imports and incentivizing domestic manufacturing investment. Stakeholders must monitor regulatory adjustments to appliance efficiency thresholds and local sourcing mandates as determinants of market access and cost structures.
Market Dynamics
Inverter compressor technology is compressing margins for conventional fixed-speed manufacturers while Egyptian energy-efficiency mandates accelerate the obsolescence of legacy cooling systems across residential and commercial procurement channels.
Growth Catalysts
- Urban residential expansion:Cairo and Alexandria corridor developments are standardizing appliance-inclusive unit sales, embedding durable goods into mortgage financing structures.
- Egyptian Organization for Standardization and Quality labeling mandates:Mandatory energy performance thresholds are filtering import flows and redirecting procurement toward certified inverter-based systems.
- Inverter compressor R&D spillover:Variable-speed cooling technology is migrating from air conditioners into refrigerator segments, opening cross-category efficiency positioning.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations and permanent magnet materials face price instability from concentrated Chinese processing capacity.
- Import duty exposure on fully assembled units:The Industrial Development Authority's local content thresholds penalize non-compliant manufacturers with tariff disadvantages.
- Grid voltage fluctuation tolerance:Rural distribution infrastructure outside Greater Cairo limits smart appliance functionality and warranty coverage scope.
Strategic Opportunities
- Upper Egypt distribution white space:Fresh Electric's established networks demonstrate viable logistics models for appliance penetration in under-retailed governorates.
- IoT-enabled predictive maintenance:Connected compressor diagnostics are creating aftermarket revenue streams independent of unit replacement cycles.
- Industrial Development Authority assembly incentives:Localized production qualification unlocks preferential land allocation and customs facilitation.
Industry Challenges
- Inverter control firmware specialization:Variable-speed algorithm development requires embedded systems talent scarce in Egyptian technical institutes.
- Multi-standard certification timelines:Egyptian Organization for Standardization and Quality testing queues extend product launch windows by four to six months.
- Legacy distributor credit risk:Traditional trade channel inventory financing faces non-performing exposure from currency devaluation impacts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Major Home Appliances Market |
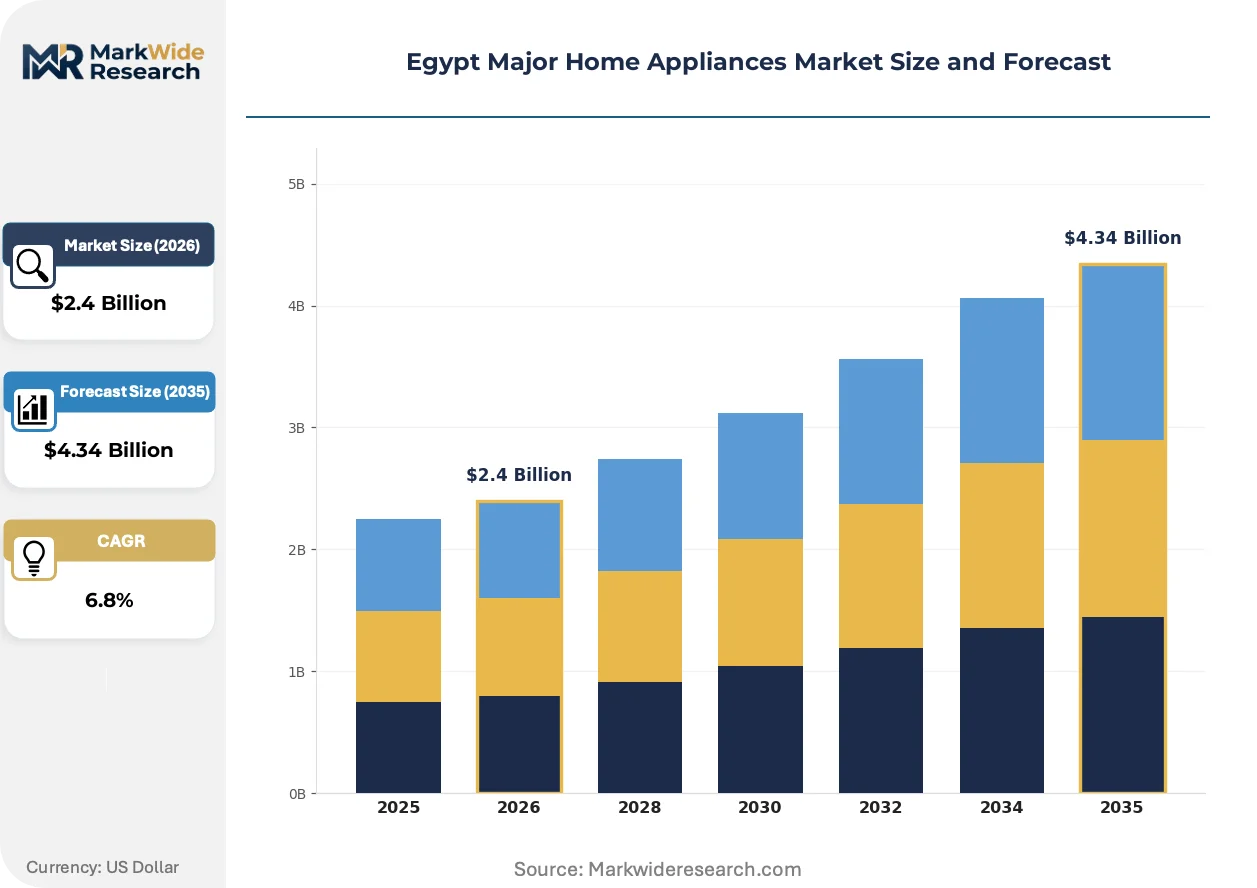
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Air Conditioners End User: Residential, Commercial, Hospitality, Retail Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Beko, LG Electronics, Fresh Electric, Bosch, Electrolux, Unionaire, Samsung Electronics, Haier, Elaraby Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Major Home Appliances Market Shifts & Advancements
Refrigeration and climate control technology is fragmenting into modular, software-defined systems that separate thermal performance from hardware enclosure, enabling subscription-based cooling service models.
Inverter-driven variable-speed compression is decomposing the traditional fixed-speed compressor market by allowing precise load matching rather than binary on-off cycling. Hospitality operators in Alexandria's coastal corridor are specifying these units for duty-cycle flexibility. The technology is compressing aftermarket service revenue by reducing mechanical failure rates and extending maintenance intervals.
Egyptian Organization for Standardization and Quality efficiency labeling protocols are tightening allowable energy consumption bands for imported cooling appliances. Manufacturers must redesign heat exchanger geometries and insulation specifications to maintain market access. Air conditioner segments face the steepest compliance cost escalation, accelerating local assembly investment to bypass fully-built-unit tariff exposure.
Appliance procurement through developer bulk contracts is displacing traditional retail channel dominance in new residential construction. Cairo's master-planned communities are negotiating direct manufacturer relationships for standardized unit specifications. This concentration is visible across sixth-of-October City and New Cairo developments where finish-package appliance inclusion reaches eighty percent of unit deliveries.
Egypt Major Home Appliances Market Segmentation
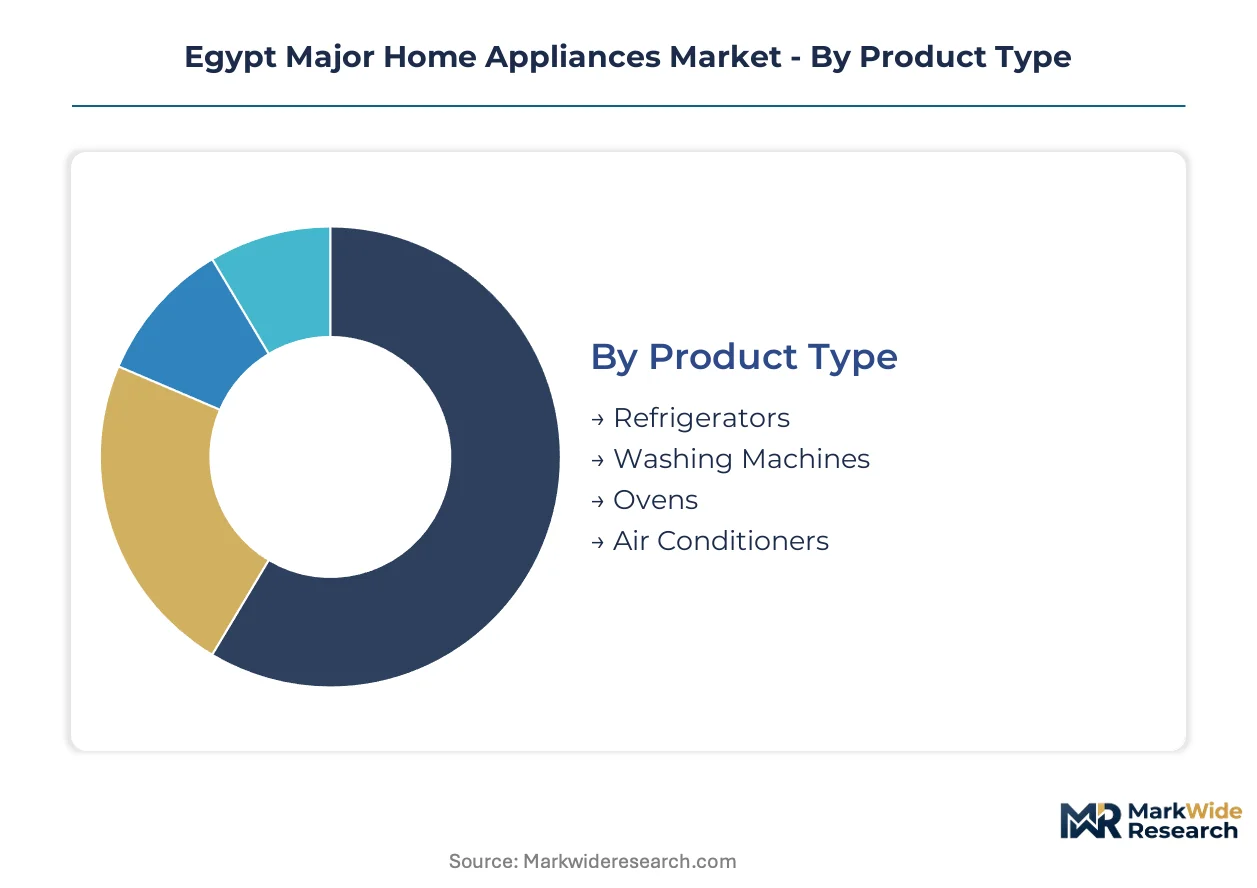
Segmentation in Egypt's major home appliances market exposes how inverter compressor substitution and smart connectivity are fragmenting traditional category boundaries. Procurement patterns diverge sharply between Cairo's mortgage-embedded bulk contracts and Upper Egypt's cash-driven retail channels.
Product Type:
Air conditioners and refrigerators face the most intense substitution pressure from inverter-based alternatives, while washing machines and ovens retain longer replacement cycles that buffer technology displacement.
- Refrigerators:Compression systems with variable-speed inverter drives now dominate premium positioning, reducing energy consumption through load-matching algorithms rather than binary cycling. Cairo's master-planned communities specify these units in eighty percent of finish-package deliveries, driven by Egyptian Organization for Standardization and Quality labeling thresholds that filter non-compliant imports.
- Air Conditioners:Inverter compressor R&D from adjacent electronics sectors has compressed margins for fixed-speed manufacturers, with Alexandria's coastal hospitality corridor specifying duty-cycle-flexible units for seasonal load variation. The technology migration from air conditioning into refrigeration is accelerating cross-category efficiency competition.
- Washing Machines:Drum-drive motor efficiency varies across direct-drive and belt-driven architectures, with demand concentrating in Greater Cairo's retail corridors where developer bulk procurement has yet to penetrate.
- Ovens:Convection and conventional heating elements split the market, with commercial end-users in hospitality segments prioritizing throughput capacity over residential energy-efficiency metrics.
Air conditioners retain volume leadership among cooling appliances; smart-enabled refrigerators hold the steepest expansion curve as IoT connectivity migrates from climate control into food preservation systems.
End User:
Procurement concentration varies by financing structure, with mortgage-embedded residential channels displacing traditional retail dominance in new construction corridors.
- Residential:Unitary household demand splits between Cairo-Alexandria mortgage-financed new construction and cash purchases in legacy urban housing, with inverter adoption rates diverging sharply across these financing modes.
- Commercial:Office and retail fit-out specifications prioritize warranty coverage and voltage fluctuation tolerance, constraining smart appliance deployment outside Greater Cairo's grid-stable zones.
- Hospitality:Alexandria's coastal hotel operators specify inverter air conditioners for seasonal duty-cycle flexibility, while Cairo business hotels standardize on energy-efficient refrigerator-minibar combinations.
- Retail:Appliance showroom and supermarket chains drive mid-range volume through trade credit relationships with distributors, exposing inventory financing to currency devaluation risk.
Residential channels command absolute unit volume; hospitality applications are climbing fastest as Alexandria's tourism corridor expands climate-controlled room stock.
Technology:
Cost tier stratification determines technology penetration, with premium positioning enabling smart feature sets that remain uneconomical at budget price points.
- Smart Appliances:Wi-Fi-enabled control interfaces and predictive diagnostics require embedded systems firmware specialization scarce in Egyptian technical institutes, limiting local development capacity.
- Energy-Efficient:Inverter compressor platforms and enhanced insulation specifications dominate this category, with Egyptian Organization for Standardization and Quality labeling mandates accelerating obsolescence of legacy cooling systems.
- Conventional:Fixed-speed compression and mechanical controls persist in budget and discount tiers across cash-constrained residential segments, particularly in Upper Egypt distribution networks.
- IoT-Enabled:Connected compressor diagnostics create aftermarket revenue streams independent of unit replacement cycles, though rural grid infrastructure limits functionality outside Greater Cairo.
Energy-efficient systems anchor current volume; IoT-enabled units are expanding most quickly as predictive maintenance models mature.
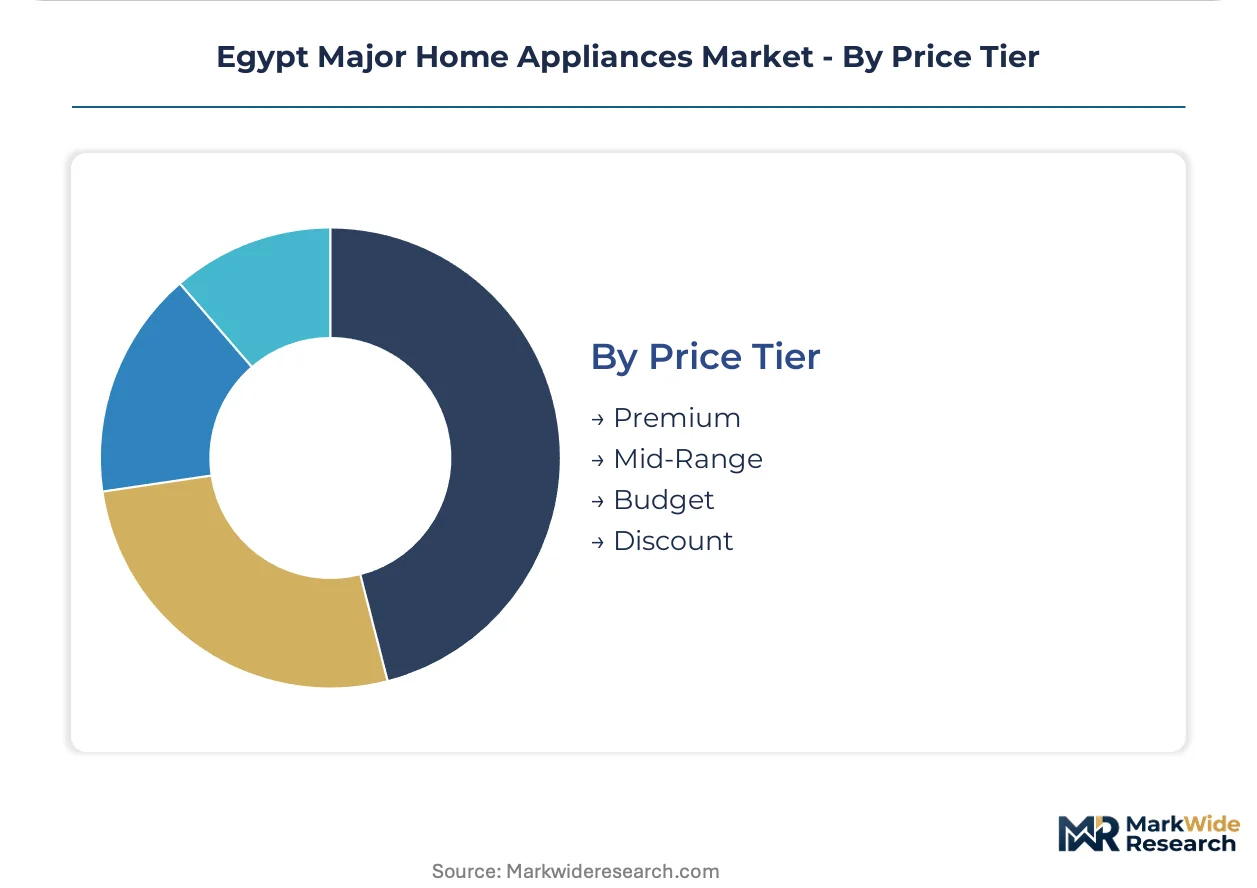
Price Tier:
Margin structure fragments across certification grades and local content compliance, with Industrial Development Authority assembly incentives reshaping cost positioning at premium and mid-range levels.
- Premium:Inverter-driven climate systems with smart connectivity and extended warranty coverage target Cairo's sixth-of-October City and New Cairo developments where finish-package inclusion is standard.
- Mid-Range:Energy-efficient labeling compliance without full IoT integration captures mortgage-embedded procurement in Alexandria's expanding residential corridors.
- Budget:Conventional fixed-speed appliances dominate cash purchases in legacy urban housing and Upper Egypt governorates where import duty exposure on fully assembled units inflates landed costs.
- Discount:Basic functionality units with minimal energy-efficiency certification serve price-sensitive segments, facing regulatory risk from tightening Egyptian Organization for Standardization and Quality thresholds.
Mid-range positioning captures the broadest demand base; premium tiers are gaining share fastest as developer bulk contracts standardize higher specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Greater Cairo's mortgage-financed developments while Upper Egypt's cash-driven channels absorb margin compression from import duty exposure and currency volatility.
Greater Cairo
Master-planned communities in New Cairo and sixth-of-October City standardize appliance-inclusive finish packages in eighty percent of unit deliveries. Egyptian Organization for Standardization and Quality labeling mandates filter non-compliant imports, redirecting procurement toward certified inverter-based systems. Mortgage-embedded financing structures embed durable goods into long-term payment schedules, insulating demand from immediate price shocks.
Alexandria
Coastal hospitality operators specify inverter air conditioners for seasonal duty-cycle flexibility, driving premium-tier volume in climate-controlled room stock. The Egyptian Industrial Development Authority's local content thresholds incentivize assembly qualification to bypass fully-built-unit tariff exposure. Alexandria's retail and hospitality corridors concentrate distribution infrastructure for northern Mediterranean-facing governorates.
Upper Egypt
Cash purchases dominate legacy urban housing and governorates where import duty exposure on fully assembled units inflates landed costs. Fresh Electric's established distribution networks demonstrate viable logistics models for appliance penetration in under-retailed territories. Asyut and Luxor anchor regional demand nodes, though grid voltage fluctuation tolerance constrains smart appliance deployment.
Suez Canal Zone
Industrial zone proximity creates assembly cost advantages for manufacturers qualifying under Industrial Development Authority local content protocols. Port infrastructure facilitates component import for localized production lines. Ismailia and Port Said host emerging manufacturing footprints targeting re-export positioning toward African and Levantine markets.
Egypt Major Home Appliances Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where inverter compressor R&D capabilities separate premium positioning from price-driven volume capture. The vendor base spans multinational electronics conglomerates, regional assembly specialists, and local distribution-anchored operators. Three strategic archetypes dominate: technology licensors leveraging proprietary inverter platforms, local assemblers exploiting customs facilitation through Industrial Development Authority compliance, and distribution-integrated players controlling Upper Egypt channel access. Competitive moves concentrate on local content qualification for tariff avoidance and geographic expansion into under-retailed governorates.
Among multinational electronics manufacturers, LG Electronics and Samsung Electronics occupy positions defined by inverter compressor R&D spillover from adjacent technology sectors. Fresh Electric exemplifies the distribution-anchored archetype, with geographic concentration in Upper Egypt networks. Elaraby Group represents localized assembly specialists, controlling production lines that reduce import duty exposure. Beko, Bosch, and Electrolux sit within European-origin premium positioning, while Haier anchors Chinese-scale manufacturing archetypes. Unionaire occupies mid-market positioning through regional production footprints.
| Leading Market Players |
|---|
| Beko |
| LG Electronics |
| Fresh Electric |
| Bosch |
| Electrolux |
| Unionaire |
| Samsung Electronics |
| Haier |
| Elaraby Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Cairo master-planned developers and inverter compressor suppliers lock in both component access and price visibility across multi-year appliance procurement cycles, insulating procurement costs from copper and rare-earth volatility while exposing non-contracted assemblers to spot market swings.
Pricing Analysis
The customization-premium spread between developer-configured finish packages and standard retail units runs wide in Greater Cairo's mortgage-embedded channels. Pricing stratifies across premium inverter-driven systems, mid-range energy-efficient labeling compliance, and economy fixed-speed tiers. Cost compression in the budget segment is intensifying because import duty exposure on fully assembled units inflates landed costs for non-compliant manufacturers. Cash purchasers in Upper Egypt governorates exhibit the highest price sensitivity, while hospitality operators in Alexandria's coastal corridor show the least.
Supply Chain Analysis
China and South Korea anchor compressor motor lamination and permanent magnet material supply for Egyptian assembly operations. The supply chain draws from concentrated Chinese processing capacity for rare-earth inputs and Taiwanese semiconductor foundries for inverter control firmware. Single-source vulnerability in permanent magnet supply creates exposure to export restriction shocks. Distribution runs through Fresh Electric's Upper Egypt networks and Elaraby Group's localized assembly lines that reduce tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where IoT-enabled predictive maintenance ecosystems are decoupling revenue from unit replacement cycles, creating interoperability standards that favor first-movers in connected compressor diagnostics.
For Market Incumbents: Secure inverter control firmware specialization through embedded systems talent acquisition in Greater Cairo technical corridors. Lock in permanent magnet supply agreements with Chinese processors to defend against rare-earth export restriction shocks. Localize assembly qualification under Industrial Development Authority protocols to bypass fully-built-unit tariff exposure.
For New Entrants and Emerging Players: Lead with Upper Egypt distribution white space where Fresh Electric's established networks demonstrate viable logistics models for under-retailed governorates. Target Asyut and Luxor cash-purchase segments with conventional fixed-speed appliances. Pursue direct distributor credit relationships bypassing legacy trade channel inventory financing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled predictive maintenance platform operators with connected compressor diagnostics. Long-term viability over a multi-year window favors acquisition targets with localized assembly qualification and embedded systems firmware development capacity. Watch Egyptian Organization for Standardization and Quality efficiency threshold tightening as the inflection signal for inverter technology substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Qualification | Industrial Development Authority compliance unlocks preferential customs facilitation and land allocation. |
| Inverter Compressor R&D Investment | Variable-speed algorithm development captures margin pools as Egyptian energy-efficiency mandates tighten. |
| Upper Egypt Distribution Expansion | Fresh Electric's logistics models demonstrate viable appliance penetration in under-retailed governorates. |
| IoT Platform Integration | Predictive maintenance ecosystems create aftermarket revenue independent of unit replacement cycles. |
| Permanent Magnet Supply Agreement | Long-term offtake contracts with Chinese processors reduce rare-earth price volatility exposure. |
Research Methodology
Desk research of customs and trade databases, Egyptian Organization for Standardization and Quality regulatory filings, and Industrial Development Authority local content protocols preceded structured interviews with compressor technology R&D directors, appliance procurement managers at Cairo master-planned developers, Upper Egypt distribution channel heads, and hospitality fit-out specification consultants. Primary intelligence combined with secondary validation from Egyptian customs records and energy-efficiency labeling databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, technology tier, end-user financing structure, and regional grid infrastructure stability shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included inverter adoption curves responsive to Egyptian Organization for Standardization and Quality threshold adjustments and mortgage-embedded procurement penetration in new residential construction corridors.
The analysis sits within stated boundaries; outcomes outside sustained Egyptian energy-efficiency mandate enforcement or stable copper and rare-earth input pricing would require recalibration. Forecasts reflect assumptions regarding Industrial Development Authority local content protocol continuity and grid infrastructure investment pacing in Upper Egypt governorates. Recalibration cycles align with material shifts in Egyptian Organization for Standardization and Quality labeling thresholds and rare-earth export policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Canada Home Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Household Refrigerator Market
Home Appliances
Washing Machine Market
Home Appliances
Italy Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
France Home Appliances Market