
 Smart Air Purifier Market | 2026-2036
Smart Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Air Purifier Market Intelligence
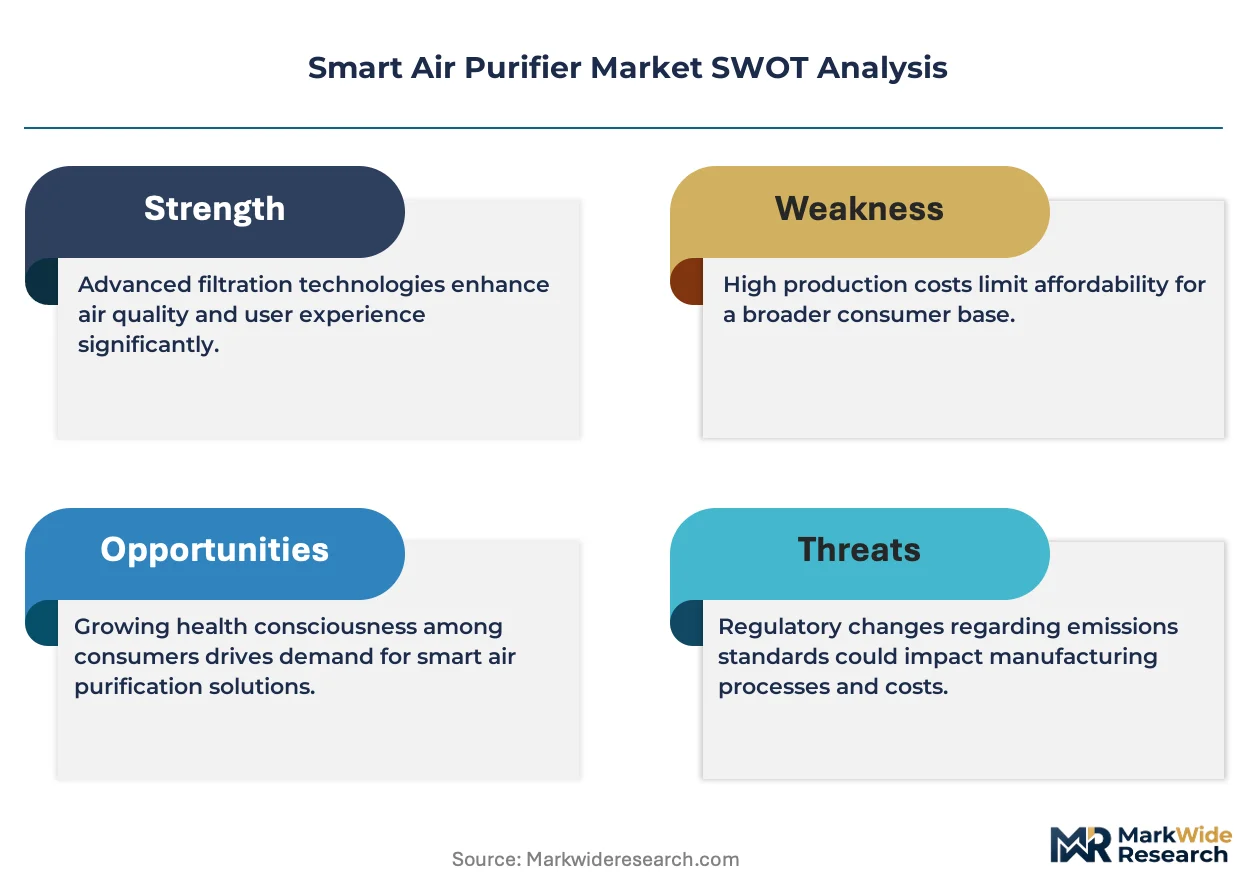
The integration of multi-sensor fusion platforms, combining PM2.5, VOC, and CO2 detectors, is tilting product development towards autonomous, predictive air quality management. Dyson Limited leverages its expertise in fluid dynamics and filtration to create premium, design-forward units. Samsung Electronics integrates its purifiers into the broader SmartThings ecosystem, emphasizing whole-home connectivity. Coway sustains a strong market presence through its rental and service-based business models, particularly in South Korea.
A smart air purifier is an electronic appliance that removes airborne contaminants using filtration media and network connectivity. These devices enable remote control and automated operation based on real-time data from internal air quality sensors, such as those detecting PM2.5 levels. The residential end-user segment constitutes the largest source of demand. Within technology, HEPA filters remain the standard for particulate capture, while activated carbon is essential for adsorbing odors and volatile organic compounds.
Product standards are influenced by frameworks like the US EPA's ENERGY STAR program and AHAM's Clean Air Delivery Rate (CADR) verification. In Europe, CE marking and RoHS directives govern electronic safety and material composition. These regulations define performance benchmarks and market access requirements. Future competitive advantage will be determined by the ability to demonstrate verifiable health outcomes beyond simple particulate reduction.
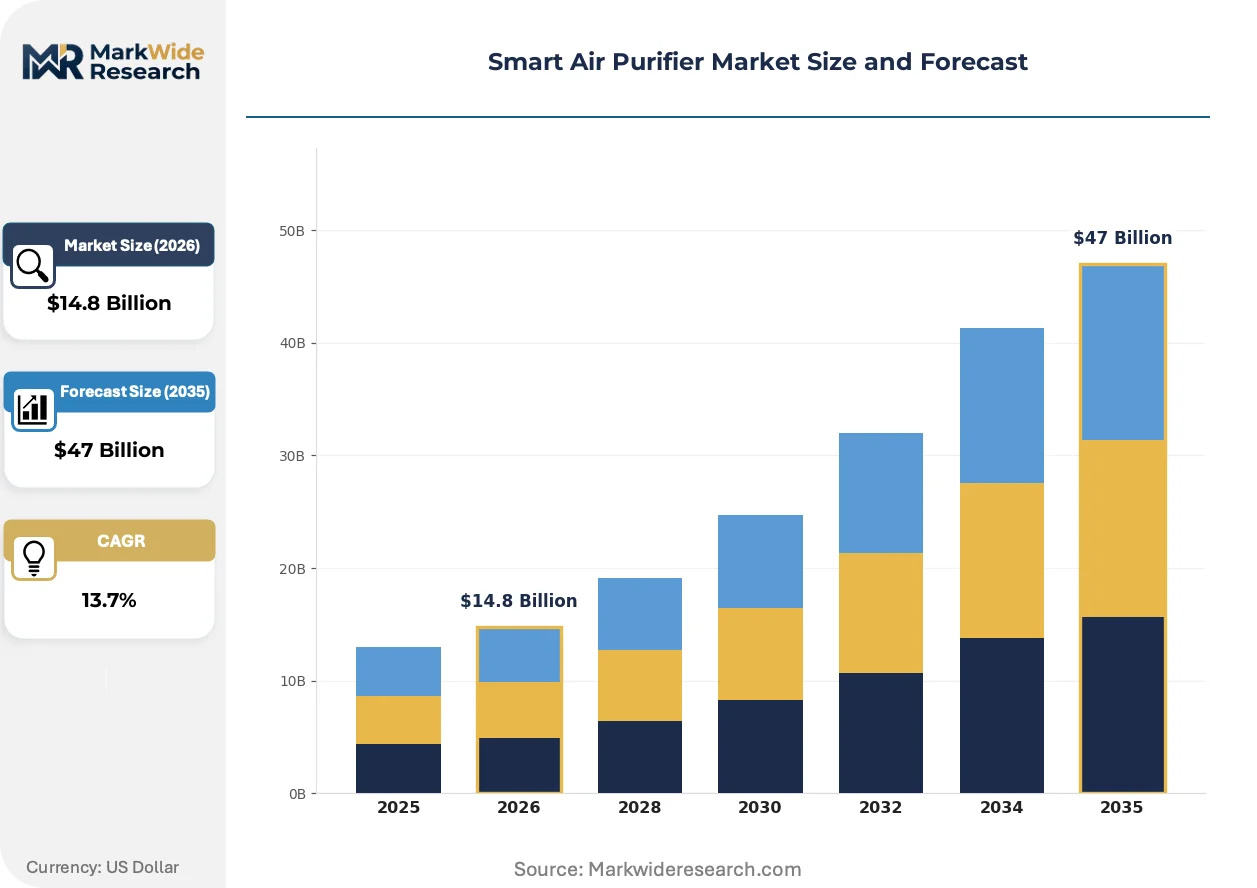
Market Dynamics
The central structural force shaping the market is the convergence of consumer health data with environmental control. This shift transforms purifiers from standalone appliances into nodes within a personalized health ecosystem, driven by AI-powered sensor platforms and demand for verifiable air quality improvement.
Growth Catalysts
- Regulatory Frameworks:China's updated GB standards for air purifiers mandate higher efficiency and lower noise levels, compelling manufacturers to innovate and raising the performance baseline for products sold in the region.
- Technology Proliferation:The falling cost and miniaturization of PM2.5 and VOC sensors enable their integration into a wider range of products, making automated, real-time air quality response accessible to the mass residential market.
- Urbanization Patterns:Concentrated demand in high-density cities, particularly in India and China, stems from severe ambient air pollution, driving household investment in indoor air quality as a non-discretionary health expenditure.
Market Restraints
- High Unit Cost:The premium pricing of models with advanced sensor suites, AI capabilities, and robust connectivity acts as a barrier to entry for price-sensitive consumers in emerging markets.
- Filter Replacement Burden:The recurring cost and logistical hassle of replacing HEPA and activated carbon filters deter some consumers and contribute to a significant total cost of ownership over the device's lifespan.
- HVAC System Competition:In new construction and high-end renovations, integrated whole-home HVAC systems with advanced filtration offer a competing solution that can obviate the need for standalone room purifiers.
Strategic Opportunities
- Geographic Expansion:Significant growth potential exists in Southeast Asian and Latin American megacities where air quality is deteriorating and a new middle class is emerging with disposable income for health-related appliances.
- Commercial Verticals:Targeting B2B applications in schools, small medical clinics, and hospitality sectors with devices that provide data-logging and compliance reporting for indoor air quality standards.
- Ecosystem Integration:Developing deeper API-level integrations with major smart home platforms and building management systems (BMS) to position purifiers as essential components of automated, energy-efficient building operations.
Industry Challenges
- Data Privacy Concerns:Collecting and transmitting detailed indoor environmental data from homes raises significant privacy and security challenges, requiring compliance with frameworks like GDPR and building consumer trust.
- Health Claim Substantiation:Moving beyond engineering metrics like CADR to prove verifiable health outcomes, such as reduced allergen sensitivity or improved sleep, requires clinical validation that is both costly and complex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Air Purifier Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $47 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-mounted, Ceiling-mounted, Tabletop Technology: HEPA, Activated Carbon, UV-C, Ionizer End User: Residential, Commercial, Industrial, Healthcare Installation: DIY, Professional, Integrated, Standalone |
| Companies Covered | Koninklijke Philips, Sharp, Honeywell International, Samsung Electronics, Blueair, Dyson Limited, LG Electronics, IQAir, Coway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Air Purifier Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards integrated environmental intelligence. This transition moves devices from reactive appliances to proactive components of a connected, health-focused home ecosystem, emphasizing data-driven automation over manual control.
Multi-gas sensor modules now combine PM2.5, VOC, and CO2 detection into a single platform. The residential segment is the primary adopter, seeking a more holistic view of indoor air quality beyond just particulates. This convergence of sensing technologies is hybridizing the device's function from a simple filter into a predictive environmental management hub that can anticipate and react to pollution events.
The US EPA's ENERGY STAR program is setting more stringent energy consumption criteria for connected appliances, including smart air purifiers. This policy directly impacts hardware and software design, forcing manufacturers to optimize power usage in both standby and active modes. The portable room air purifier category is most affected, with compliance becoming a critical market access requirement and a key differentiator for consumers in North America.
Subscription-based models for filter replacement and performance monitoring are gaining traction over traditional one-time hardware sales. This business model shift disrupts standard retail channels by creating a direct, recurring revenue relationship between the manufacturer and the end-user. The trend is most prominent in mature markets like South Korea and is expanding as brands seek to capture long-term customer value.
Smart Air Purifier Market Segmentation
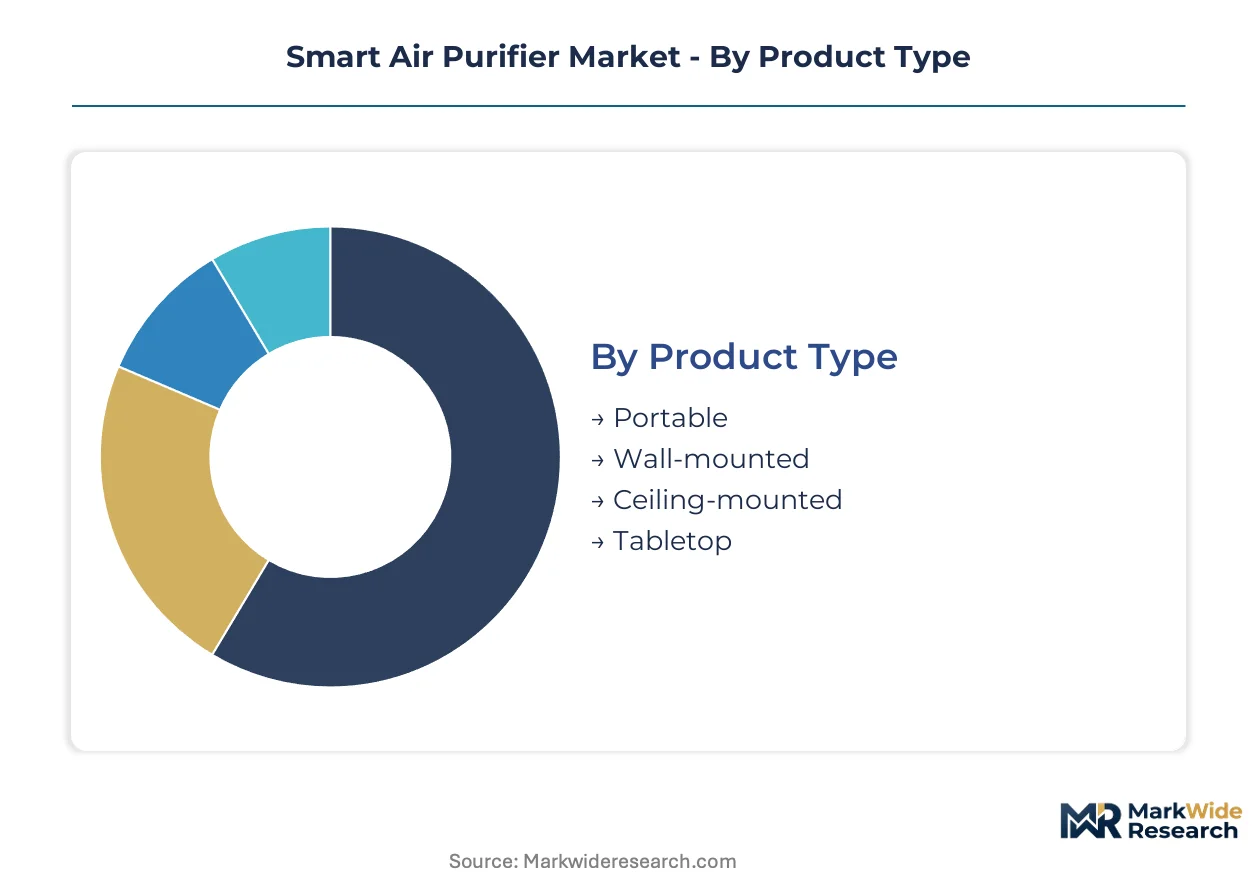
The smart air purifier market categorizes products and services based on distinct functional attributes and end-user requirements. This segmentation highlights diverse technological applications and deployment methods, enabling manufacturers to tailor solutions for specific indoor environments. Understanding these divisions helps identify areas of concentrated demand and emerging growth opportunities across various consumer and commercial settings.
Product Type:
The after-sales service intensity varies significantly across different product types, impacting the long-term customer relationship and operational costs.
- Portable:These units are designed for easy relocation between rooms, offering flexible air purification. Demand concentrates in residential settings, driven by consumers seeking adaptable solutions for smaller spaces or multi-room use.
- Wall-mounted:Permanently affixed to a wall, these purifiers optimize space utilization and can be integrated into interior design. Demand is strong in commercial offices and healthcare facilities, where aesthetics and consistent air quality in fixed locations are priorities.
- Ceiling-mounted:Integrated into ceiling structures, these systems provide discreet, whole-room air circulation and filtration. Commercial and industrial applications favor these units for their unobtrusive nature and ability to cover large open-plan areas efficiently.
- Tabletop:Compact devices designed for personal spaces like desks or small bedrooms, offering localized air purification.
By volume, Portable units lead the market. By growth pace, Wall-mounted purifiers are ahead.
Technology:
Functional differentiation drives technology adoption, with each method targeting specific airborne contaminants and offering distinct performance characteristics.
- HEPA:High-efficiency particulate air filters capture 99.97% of airborne particles 0.3 microns in size, including dust, pollen, and pet dander. Residential and healthcare sectors exhibit high demand for HEPA filters due to their proven efficacy in allergen and particulate removal.
- Activated Carbon:These filters use a porous carbon structure to adsorb volatile organic compounds (VOCs), odors, and gases from the air. Commercial kitchens and industrial facilities widely adopt activated carbon for effective mitigation of chemical pollutants and strong smells.
- UV-C:Ultraviolet-C light technology inactivates airborne microorganisms like bacteria and viruses by disrupting their DNA. Healthcare environments and schools increasingly deploy UV-C for enhanced sterilization and pathogen control.
- Ionizer:This technology releases charged ions into the air, causing airborne particles to clump together and settle, improving air clarity.
HEPA filtration technology represents the foundational standard for particulate capture. Ionizer technology is gaining share fastest in budget-conscious residential applications.
End User:
Customer type dictates the scale, feature set, and regulatory compliance requirements for smart air purifiers, influencing product development cycles.
- Residential:This segment includes individual households and multi-family dwellings, where purifiers enhance indoor air quality for personal health and comfort. Demand is concentrated in urban areas of China and India, driven by high ambient air pollution levels.
- Commercial:Offices, retail spaces, and hospitality venues utilize smart purifiers to create healthier environments for employees and customers. These applications prioritize quiet operation and integration with building management systems.
- Industrial:Factories, manufacturing plants, and workshops deploy robust air purification systems to protect workers from airborne pollutants and adhere to occupational safety standards. These units often require specialized filtration for specific industrial emissions.
- Healthcare:Hospitals, clinics, and laboratories rely on advanced air purifiers to maintain sterile environments and prevent the spread of airborne pathogens.
The Residential end-user segment commands the largest market share by volume. The Commercial sector is experiencing the steepest expansion trajectory.
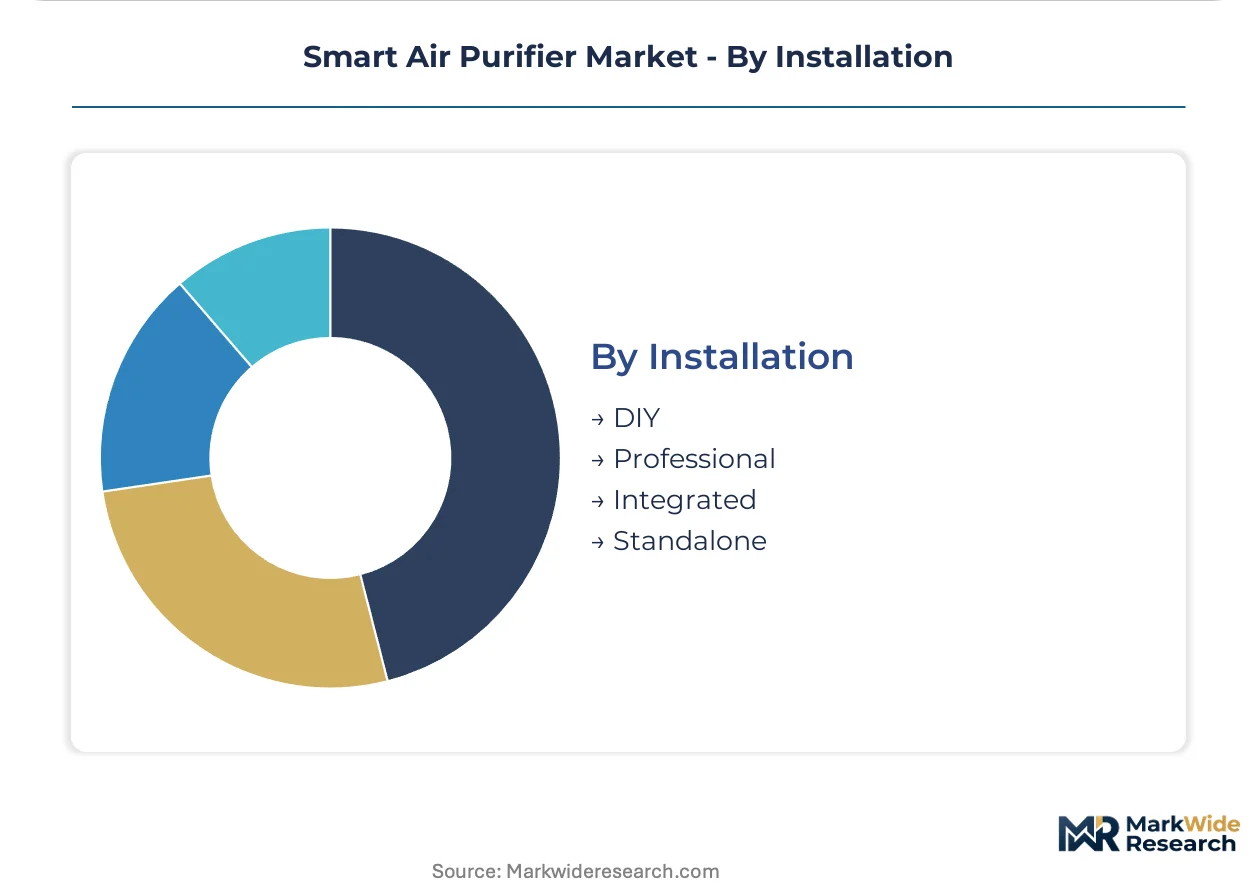
Installation:
The skill requirement for installation significantly impacts product accessibility and the overall cost of ownership for end-users.
- DIY:Do-It-Yourself installation involves consumer-friendly setup, typically for portable or tabletop units, requiring minimal technical expertise. This approach appeals to price-sensitive residential consumers seeking immediate and flexible solutions without professional assistance.
- Professional:These installations require trained technicians, often for wall-mounted, ceiling-mounted, or integrated systems, ensuring proper placement and system calibration. Commercial and healthcare facilities frequently opt for professional installation to guarantee optimal performance and compliance.
- Integrated:Air purification systems built directly into HVAC infrastructure or smart home ecosystems during construction or major renovation. This method offers seamless operation and whole-home coverage.
- Standalone:Devices that operate independently without requiring integration into larger building systems, often portable or tabletop models.
Standalone devices dominate the market due to their ease of deployment. Integrated solutions are climbing the fastest, especially in new construction projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regional dynamics of the smart air purifier market are profoundly influenced by the interplay between local manufacturing capabilities and consumer demand, dictating the flow of finished goods across borders. Regions with high domestic production often serve as export hubs, while areas facing severe air quality challenges and limited local supply represent significant import markets. This export-import balance shapes market penetration strategies and supply chain configurations for manufacturers.
China
Concentrated demand in high-density cities like Beijing and Shanghai stems from severe ambient air pollution, driving household investment in indoor air quality as a non-discretionary health expenditure. China's updated GB standards for air purifiers mandate higher efficiency and lower noise levels, compelling manufacturers to innovate. The Yangtze River Delta region, with its dense urban population, experiences particularly strong adoption of advanced purification systems.
India
Deteriorating air quality in megacities and an emerging middle class with disposable income for health-related appliances fuel significant demand for smart air purifiers. The Bureau of Indian Standards (BIS) influences product quality and safety for electronic goods sold in the country. Urban centers such as Delhi and Mumbai exhibit high household investment in indoor air quality solutions due to persistent pollution challenges.
United States
A strong consumer focus on healthier indoor environments and allergy concerns drives the adoption of smart air purifiers, especially those with advanced sensor suites. The US EPA's ENERGY STAR program sets stringent energy consumption criteria for connected appliances, impacting hardware and software design. Major metropolitan areas like Los Angeles and New York show strong market penetration of connected air purification systems.
Germany
European health standards and a preference for design-forward, energy-efficient units stimulate demand for premium smart air purifiers. CE marking and RoHS directives govern electronic safety and material composition for products within the European Union. Urban centers such as Munich and Berlin prioritize advanced air purification systems for both residential and commercial applications.
South Korea
High consumer awareness of indoor air quality and widespread smart home ecosystem adoption contribute to a mature market for air purifiers. The Ministry of Food and Drug Safety (MFDS) oversees certain product safety aspects for consumer electronics. The Seoul Metropolitan Area exhibits high penetration of subscription-based models for filter replacement and performance monitoring.
Smart Air Purifier Market Key Industry Players
On the supply side, the industry is moderately fragmented, characterized by a mix of established consumer electronics giants, specialized air quality technology firms, and traditional appliance manufacturers. Strategic archetypes include premium design-focused brands, mass-market connected appliance providers, and service-oriented specialists. Dominant competitive moves involve portfolio diversification into broader smart home ecosystems and targeted geographic expansion into emerging markets.
Among technology leaders, Samsung Electronics and Dyson Limited exemplify brands leveraging existing consumer electronics expertise. Samsung Electronics, a South Korea-based multinational conglomerate, integrates its purifiers into the broader SmartThings ecosystem, emphasizing whole-home connectivity. Dyson Limited, a UK-headquartered technology company, leverages its expertise in fluid dynamics and filtration to create premium, design-forward units. Coway, another South Korea-based company, sustains a strong market presence through its rental and service-based business models, particularly in its home market.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Sharp |
| Honeywell International |
| Samsung Electronics |
| Blueair |
| Dyson Limited |
| LG Electronics |
| IQAir |
| Coway |
| Others |
Cost & Logistics Intelligence
Commodity volatility in specialized filtration media, particularly activated carbon and HEPA-grade materials, determines both pricing tier spreads and supply chain shape. This volatility directly influences manufacturing costs and product availability for smart air purifiers globally.
Pricing Analysis
Commercial OEM buyers anchor subscription-based models, especially for large-scale deployments requiring ongoing service. Price differentiation stems from brand premium for design-forward units and the depth of integrated after-sales service packages. Pricing softness reflects intense competition in the mass residential segment. Residential consumers in emerging markets exhibit high price sensitivity, while commercial and healthcare buyers prioritize performance and compliance with indoor air quality standards.
Supply Chain Analysis
Export-control regimes on advanced sensor components could limit flows, impacting manufacturing and availability. Supply for smart air purifiers concentrates heavily in China and Southeast Asia, driven by established electronics manufacturing ecosystems. Raw material dependencies include HEPA filtration media, activated carbon granules, and miniaturized PM2.5/VOC/CO2 sensors. Single-source vulnerability for specialized sensor components presents a structural risk. Distribution runs through a dual model of established retail channels and expanding direct-to-consumer sales platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is experiencing a buyer-power shift as residential end-users increasingly demand verifiable health outcomes, leading to fragmentation in consumer preferences.
For Market Incumbents: Insulate core market share by investing heavily in clinical validation for health claims, moving beyond engineering metrics like CADR. Deepen integration into broader smart home ecosystems through open APIs and platform partnerships. This strategy addresses the growing threat from HVAC system manufacturers offering integrated whole-home filtration. Focus R&D on multi-sensor fusion platforms to maintain technological leadership.
For New Entrants and Emerging Players: Build out specialized offerings for commercial verticals, such as schools and small medical clinics, where data-logging and compliance reporting are critical. Target underpenetrated megacities in Southeast Asia and Latin America with localized product development tailored to regional pollutant profiles. A strong go-to-market angle involves offering flexible subscription-based models for filter replacement and preventative maintenance, reducing upfront consumer burden.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized technology firms with strong intellectual property in sensor development. Long-term viability hinges on companies demonstrating verifiable health outcomes and seamless smart home integration, rather than just particulate reduction. Acquisition targets should include mid-cap specialists with established recurring revenue models or disruptive sensor technology. The signal to watch is regulatory tightening on health claim substantiation, which will consolidate competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Verifies health outcomes beyond CADR metrics, building consumer trust. |
| Multi-Sensor Platform Integration | Enhances predictive air quality management, differentiating product offerings. |
| Subscription Service Expansion | Secures recurring revenue streams and long-term customer relationships. |
| Smart Home Ecosystem Partnerships | Positions purifiers as essential components within connected living environments. |
| Geographic Expansion into Southeast Asia | Captures demand from emerging middle classes facing deteriorating air quality. |
Research Approach
Operator-level perspectives from product development engineers, supply chain managers, retail channel partners, and smart home platform developers anchored the qualitative base for this analysis. This primary research was triangulated with extensive secondary data from regulatory filings (US EPA, EU CE marking), patent databases, academic research on indoor air quality, and company annual reports. Both bottom-up and top-down approaches were employed to ensure comprehensive market sizing and validation.
Scenario-bracketing framed the analytical framework, integrating historical market data with projected market drivers across the analysis window. Segmentation dimensions modeled included product type, technology, end-user, installation method, and regional regulatory adherence. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical trends, expert interviews, and macroeconomic forecasts. Key industry-specific forecast inputs included urbanization rates, ambient air pollution levels, and consumer health expenditure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large HVAC manufacturers or disruptive sensor technology startups would shift outcomes significantly. Forecasts reflect assumptions regarding technological evolution and regulatory stability. Cross-checking against third-party market reports and government environmental agency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Infrared Sauna Heaters Market
Household Items
Smart Bath Heater Market
Household Items
Smart Memory Foam Market
Household Items
Disposable Cutlery Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
US Hand Dryers Market
Household Items
Integrated Smart Toilet Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Indoor Humidifier Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Knife Set Market
Household Items
Tiki Torch Market
Household Items
Laundry Detergent Sheets Market
Household Items
Mosquito Trap Market
Household Items
Water Purifier Market