
 Facial Tissue Market | 2026-2036
Facial Tissue Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Tissue Market Analysis
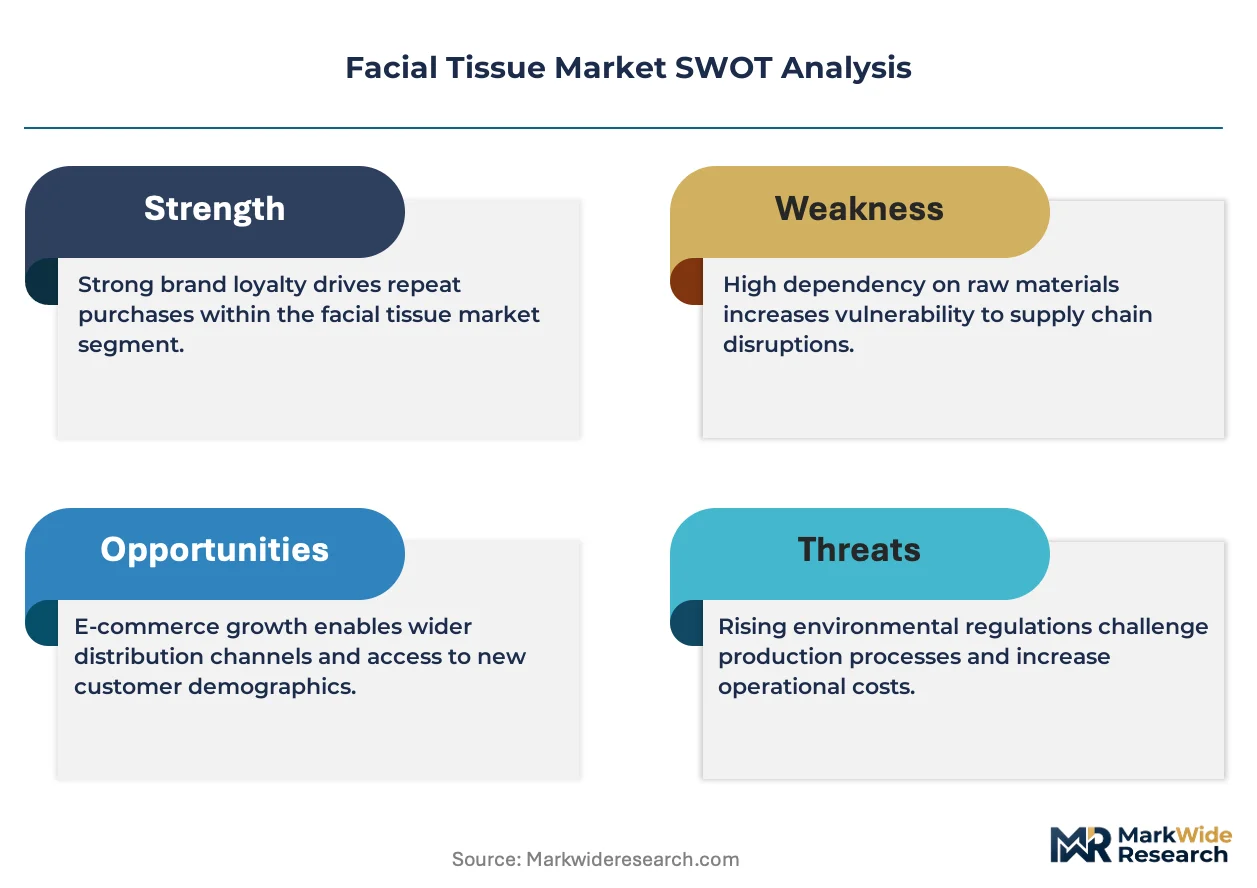
Plant-based fiber substitution is tilting facial tissue manufacturing away from virgin pulp toward bamboo and agricultural residue blends. Kimberly-Clark Corporation leverages its North American R&D infrastructure to pilot enzymatic bleaching processes that cut chemical inputs. Essity AB anchors European production through integrated pulp-to-tissue mills in Sweden and Germany. Procter & Gamble Company differentiates via fragrance-free and dermatologist-tested lines that command shelf space in pharmacy channels.
Facial tissue denotes soft, disposable paper sheets engineered from wood pulp or alternative cellulose fibers, typically two to four plies thick and sized between 200 and 220 millimeters per sheet, designed for nasal and facial hygiene. The product serves household, commercial, healthcare, and hospitality end users requiring convenient, sanitary moisture absorption. Box packaging dominates retail volume in North American and European supermarkets, while pocket packs capture impulse purchases at transit hubs and convenience stores. Eco-friendly material segments, including bamboo and recycled pulp, are expanding fastest as retailers in Germany and France impose plastic-free aisle requirements that reshape procurement criteria.
EPA guidelines govern chlorine discharge from U.S. pulp mills, while REACH and the EU Green Deal restrict chemical additives and mandate recycled content thresholds in European facial tissue products. FDA oversight applies to tissues marketed with antimicrobial or medicated claims, creating compliance gates that favor established manufacturers with regulatory affairs teams. Stakeholders must track evolving biodegradability certifications and retailer-specific sustainability scorecards that will determine shelf access without warning periods.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing production timelines for facial tissue manufacturers, forcing accelerated migration from virgin pulp toward certified agricultural residue blends and enzymatic processing methods.
Growth Catalysts
- REACH chemical restrictions:European mandates on additive transparency are pulling reformulated, dermatologist-tested SKUs into pharmacy and specialty retail channels.
- Bamboo fiber processing:Mechanical refining advances are cutting energy inputs for alternative pulp, expanding viable feedstock beyond Nordic softwood.
- German retail consolidation:Discounter and drugstore chains are standardizing plastic-free aisle requirements, creating procurement volume for biodegradable packaging formats.
Market Restraints
- Softwood pulp concentration:Swedish and Finnish integrated mills control premium fiber supply, exposing converters to input cost volatility during boreal harvest disruptions.
- EPA chlorine discharge limits:U.S. pulp mill effluent rules are raising compliance capital requirements for bleached tissue lines without grandfathering provisions.
- Wet wipe substitution:Polypropylene-based moist towelettes are capturing facial hygiene occasions in transit and foodservice settings.
Strategic Opportunities
- France plastic-free retail mandates:Supermarket chain sustainability scorecards are opening shelf space for unbleached, agricultural-residue tissue in urban centers.
- Healthcare antimicrobial claims:FDA-cleared tissue formulations can access clinical procurement channels currently served by reusable linens.
- Enzymatic bleaching convergence:Biotechnology platforms are merging with tissue finishing lines to eliminate elemental chlorine while preserving softness metrics.
Industry Challenges
- Biodegradability certification timelines:Third-party compostability validations for bamboo-residue blends require 18-24 month testing windows that outpace retailer deadline shifts.
- Legacy pulping asset integration:Conventional kraft mills face retrofit complexity when adapting enzymatic pre-treatment stages without production line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Tissue Market |
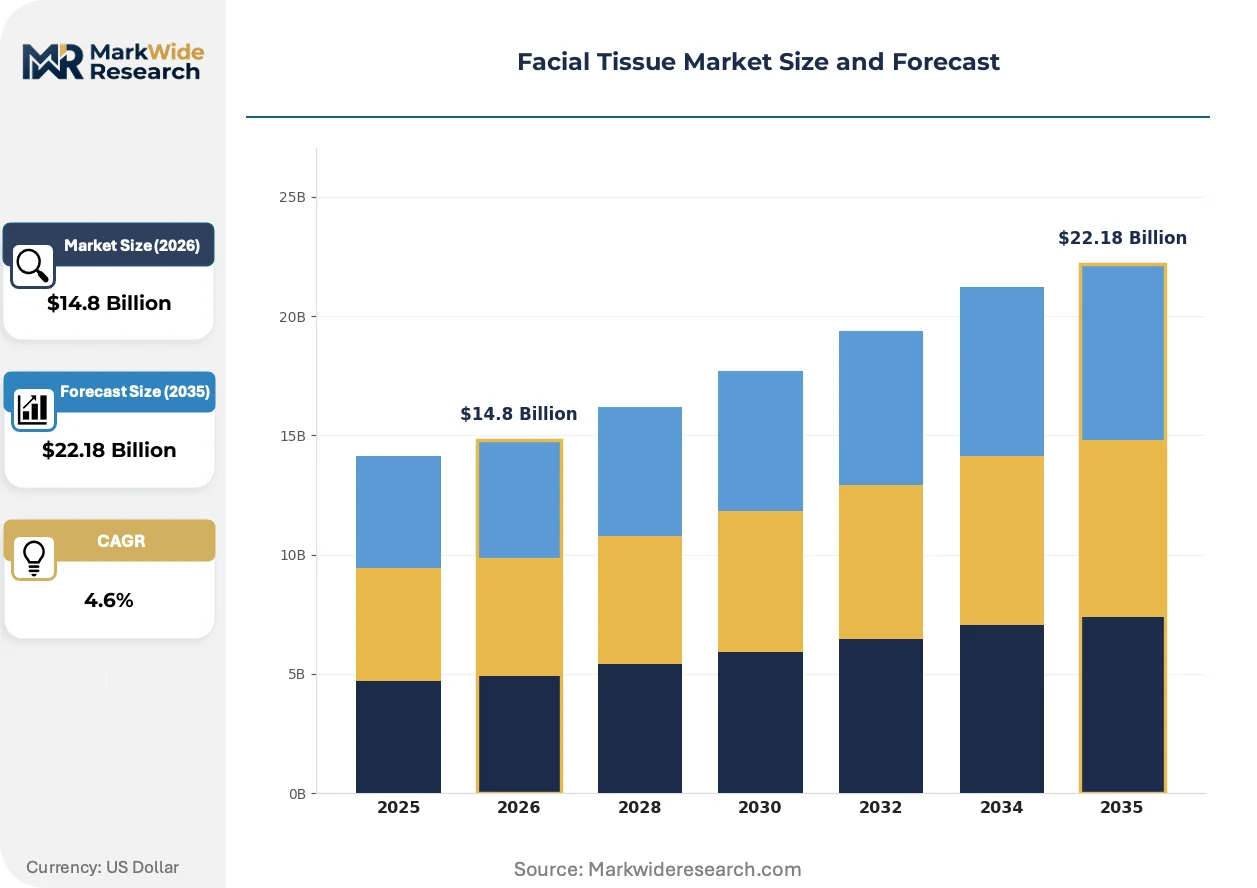
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Moist, Travel, Eco-Friendly Material: Pulp, Recycled, Bamboo, Synthetic Packaging Type: Box, Pocket Pack, Flat Pack, Dispenser End User: Household, Commercial, Healthcare, Hospitality |
| Companies Covered | Kimberly-Clark Corporation, Procter & Gamble Company, Essity AB, Georgia-Pacific LLC, Hengan International Group Company Limited, Sofidel Group, WEPA Hygieneprodukte GmbH, Asia Pulp and Paper Group Sinar Mas, Cascades Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Tissue Market Emerging Trajectories
Enzymatic processing and digitized quality control are compressing the gap between alternative fiber development and mass-market facial tissue production, while regulatory chemical restrictions and retail sustainability mandates are rewriting procurement specifications.
Near-infrared spectroscopy coupled with machine vision is digitizing real-time fiber composition verification on tissue converting lines. Premium household buyers in Germany and France are demanding batch-level traceability data that legacy manual sampling cannot deliver. This sensor integration is digitizing quality assurance workflows, compressing defect response times from hours to seconds while enabling agricultural-residue blend ratios previously deemed unverifiable.
The EU F-Gas Regulation and accompanying Green Deal implementation frameworks are phasing out fluorinated greenhouse gases used in certain tissue softening chemistries. Manufacturers serving German and French retail channels must reformulate wet-end additives before 2027 without performance degradation. Tissue lines marketed with dermatological certifications are absorbing disproportionate compliance costs, creating segmentation between pharmacy-grade and mass-market positioning.
Pharmacy and clinic buyers are consolidating facial tissue procurement around bundled hygiene contracts that unbundle after-sales service from product supply. Hospital systems in Sweden and Germany are replacing ward-level purchasing with centralized sustainability scorecard evaluations. This concentration is most visible in Nordic healthcare networks, where Essity and Kimberly-Clark compete on total-cost-of-ownership metrics rather than per-box pricing.
Facial Tissue Market Segmentation
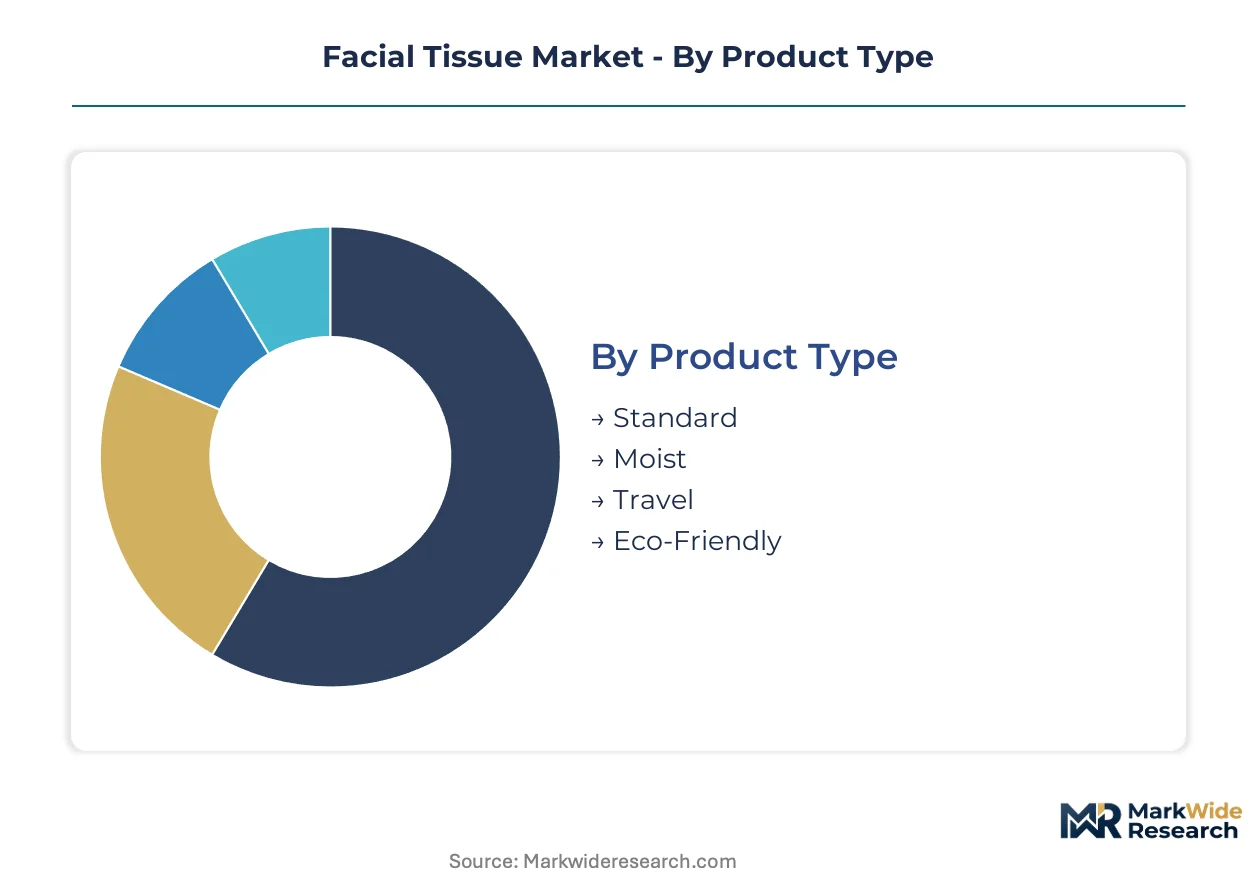
Facial tissue segmentation reflects divergent consumer priorities across hygiene occasions, material ethics, and channel formats. Manufacturers must align fiber sourcing, packaging engineering, and certification claims to capture value in each slice.
Product Type:
Cost tier stratification separates mass-market functional products from premium-positioned variants commanding pharmacy and specialty retail placement.
- Standard:Two-to-four-ply virgin or recycled pulp sheets in 200-220mm dimensions serve baseline nasal and facial hygiene. Household demand concentrates in German and French supermarkets where private-label competition compresses margins.
- Moist:Pre-moistened formulations with dermatologist-tested additives target cold-and-flu seasons and cosmetic removal occasions. Pharmacy channel placement in Sweden and Germany absorbs disproportionate compliance costs for preservative transparency under REACH.
- Travel:Compressed pocket formats sized for transit and impulse purchase capture convenience store volume.
- Eco-Friendly:Unbleached agricultural-residue and bamboo blends meet retailer plastic-free aisle mandates in urban France.
Standard tissues command the established base. The steepest expansion runs through Eco-Friendly variants.
Material:
Supply concentration in Nordic softwood regions shapes converter procurement strategies and alternative fiber investment timelines.
- Pulp:Virgin softwood fibers from Swedish and Finnish integrated mills deliver premium softness metrics. Boreal harvest disruptions expose converters to input cost volatility without long-term supply contracts.
- Recycled:Post-consumer fiber streams processed to FDA and EPA effluent standards serve institutional procurement in U.S. healthcare systems.
- Bamboo:Mechanical refining advances cut energy inputs for alternative pulp expansion beyond Nordic supply dependence.
- Synthetic:Polypropylene-based wet-laid nonwovens face substitution pressure from biodegradable mandates.
Pulp maintains volume leadership. Bamboo-residue blends are gaining share fastest.
Packaging Type:
Channel format requirements dictate structural engineering decisions from retail shelf presence to dispenser compatibility.
- Box:Rigid cardboard housings with flip-top apertures dominate North American and European supermarket volume. German discounters standardize plastic-free specifications that reshape converter procurement.
- Pocket Pack:Slim polyethylene or paper-wrapped formats sized for transit hub impulse purchase. Convenience channel placement in France and Germany absorbs premium unit economics.
- Flat Pack:Space-efficient refills for hospitality and institutional dispensers.
- Dispenser:Wall-mounted or countertop units for healthcare and foodservice settings.
Box packaging commands the established base. Pocket Pack formats are climbing the fastest.
End User:
Customer type determines performance specifications, certification requirements, and procurement concentration patterns.
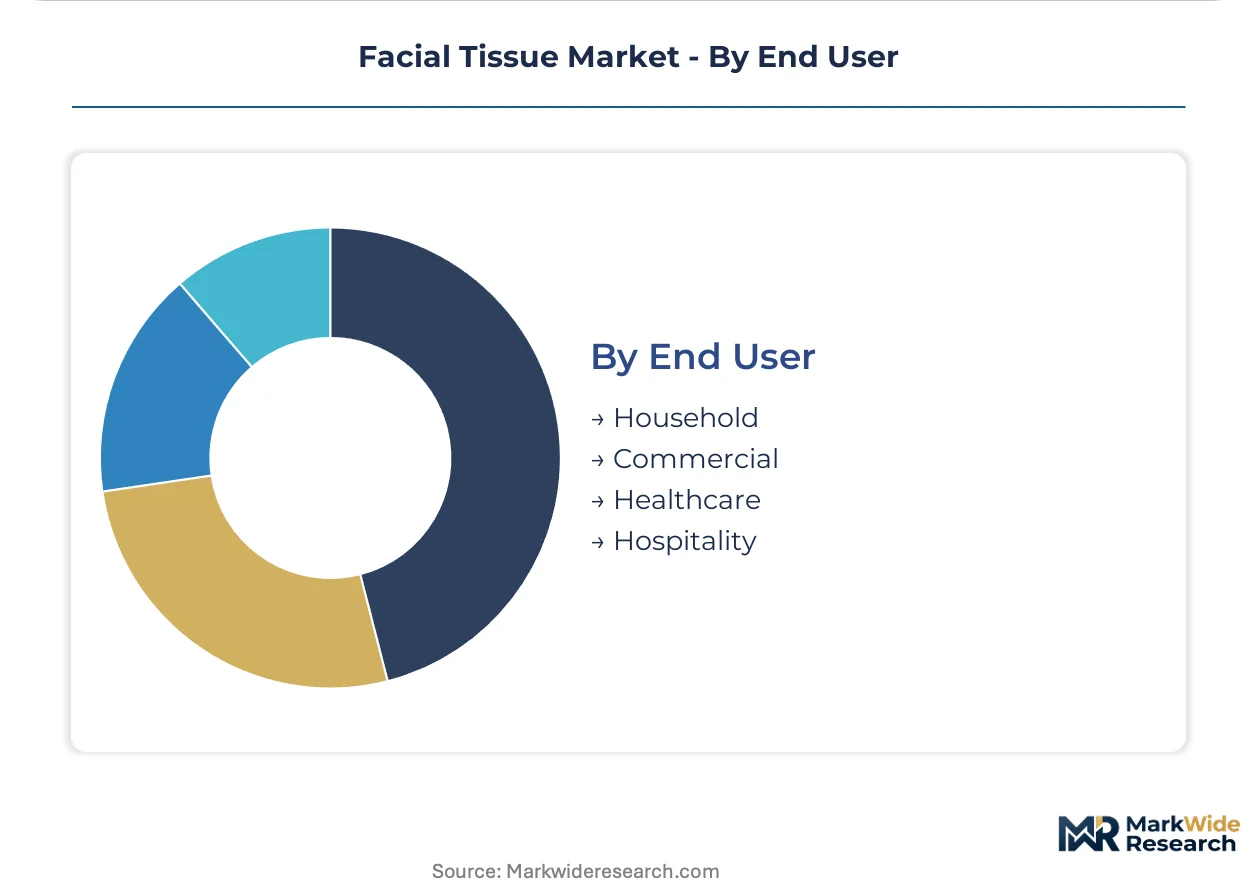
- Household:Individual consumers selecting on softness, fragrance, and sustainability claims. Premium positioning in Germany and France absorbs dermatologist-tested and plastic-free certifications.
- Healthcare:Hospital systems in Sweden and Germany consolidate procurement around bundled hygiene contracts with total-cost-of-ownership metrics. FDA-cleared antimicrobial formulations access clinical channels.
- Commercial:Office and institutional buyers prioritizing unit cost and dispenser compatibility.
- Hospitality:Hotel and foodservice operators balancing guest experience with operational efficiency.
Household consumption commands the established base. Healthcare procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in Germany and France absorb disproportionate compliance costs for dermatologist-tested and plastic-free certifications. Healthcare procurement concentrates in Sweden and Germany around bundled hygiene contracts. Retail consolidation in German discounters and French supermarkets reshapes converter sourcing requirements.
Germany
WEPA Hygieneprodukte GmbH anchors production in North Rhine-Westphalia. The EU Green Deal and F-Gas Regulation mandate enzymatic processing migration by 2027. Discounter chains in the Ruhr industrial cluster standardize plastic-free aisle specifications that reshape converter procurement.
France
Pharmacy channel placement absorbs premium positioning for preservative-transparent formulations. REACH chemical restrictions pull reformulated SKUs into specialty retail. Supermarket sustainability scorecards in Île-de-France open shelf space for unbleached agricultural-residue tissue.
Sweden
Integrated pulp-to-tissue mills in Värmland and Västra Götaland deliver premium softness metrics. EPA-equivalent effluent standards govern chlorine discharge from boreal fiber processing. Hospital systems in Stockholm consolidate procurement around total-cost-of-ownership metrics.
United States
North American R&D infrastructure pilots enzymatic bleaching for chemical input reduction. FDA oversight applies to antimicrobial tissue claims creating compliance gates. Georgia-Pacific LLC operates integrated mills in the Southeast serving institutional healthcare procurement.
China
Hengan International Group Company Limited scales production for domestic household consumption. The country's dual carbon goals pressure mills toward agricultural residue fiber adoption. Yangtze River Delta converters experiment with bamboo-residue blend ratios for export markets.
Facial Tissue Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base separates into three tiers: integrated pulp-to-tissue operators, branded consumer goods conglomerates, and regional private-label converters. Strategic archetypes include sustainability-certification specialists, pharmacy-channel premium positioners, and discounter-scale cost leaders. Competitive moves concentrate on enzymatic processing licensing and backward integration into alternative fiber supply.
Within the integrated operator tier, Kimberly-Clark Corporation and Essity AB exemplify archetypes that combine pulp captive supply with pharmacy-channel certification depth. Procter & Gamble Company occupies a position on the branded premium vector. WEPA Hygieneprodukte GmbH anchors the regional specialist archetype with concentrated German retail relationships. These three represent distinct competitive positioning geometries without overlapping strategic territory.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Procter & Gamble Company |
| Essity AB |
| Georgia-Pacific LLC |
| Hengan International Group Company Limited |
| Sofidel Group |
| WEPA Hygieneprodukte GmbH |
| Asia Pulp and Paper Group Sinar Mas |
| Cascades Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals from Chinese bamboo-residue processing facilities are compressing converter margins while simultaneously enabling aggressive pricing postures in European retail channels. This utilization dynamic forces Nordic integrated mills to defend softness premiums through long-term supply contracts indexed to boreal pulp benchmarks.
Pricing Analysis
Cost-plus contracts with NBSK pulp indexation dominate procurement between Swedish integrated mills and German retail chains. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-certified dermatologist-tested lines from mass-market private-label SKUs. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard tiers is intensifying because private-label competition absorbs shelf space at German discounters. Household buyers in France absorb the least price sensitivity due to plastic-free mandate compliance premiums.
Supply Chain Analysis
Upstream feedstock selection centers on Swedish and Finnish softwood plantations, Chinese bamboo processing clusters, and German agricultural residue collection networks. Virgin pulp draws from boreal kraft mills while alternative fibers rest on Yangtze River Delta refining capacity. Single-source vulnerability concentrates in Nordic premium fiber supply during harvest disruption periods. Distribution runs through German discounter consolidation and French supermarket sustainability scorecard channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial tissue markets sit in early-cycle expansion as enzymatic bleaching adoption accelerates reformulation timelines and opens pharmacy-channel access for certified players.
For Market Incumbents: Pre-empt wet wipe substitution threats by accelerating FDA-cleared antimicrobial tissue development for healthcare procurement consolidation. Anchor backward integration into bamboo-residue supply through Yangtze River Delta partnerships before 2027 F-Gas compliance deadlines compress formulation windows.
For New Entrants and Emerging Players: Mid-market eco-friendly segments in urban France represent the most penetrable entry point given supermarket plastic-free aisle mandates and unmet agricultural-residue blend demand. Target pharmacy-channel placement through preservative-transparent formulations that absorb REACH compliance costs incumbent brands hesitate to shoulder.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic processing infrastructure as biotechnology platforms merge with tissue finishing lines. Five-to-ten year viability favors acquisition targets with captive alternative fiber supply and dermatologist-tested SKU portfolios. Watch enzymatic bleaching licensing deal velocity as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Licensing | Biotechnology platforms merging with tissue finishing lines eliminate elemental chlorine while preserving softness metrics for German retail compliance. |
| Backward Integration into Bamboo Supply | Yangtze River Delta refining capacity secures alternative fiber feedstock beyond Nordic softwood concentration vulnerability. |
| Pharmacy Channel Certification Investment | FDA-cleared antimicrobial formulations access clinical procurement channels replacing reusable linens in Swedish hospital systems. |
| Sustainability Repositioning | Unbleached agricultural-residue blends capture shelf space under French supermarket plastic-free aisle mandates. |
| Long-term Retail Supply Agreement | German discounter consolidation rewards converters with volume guarantees against private-label margin compression. |
Methodological Framework
A spread of perspectives from tissue converting line engineers, German retail category buyers, pulp procurement directors, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from EU F-Gas Regulation implementation documents, REACH chemical restriction databases, and Nordic trade association production statistics. Bottom-up fiber demand modeling and top-down retail channel value estimation triangulated segment outputs.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tiers, material feedstock categories, packaging formats, and end-user procurement concentration patterns. CAGRs derived from historical volume elasticities projected against regulatory compliance deadline effects. Industry-specific forecast inputs incorporated enzymatic processing adoption curves and retailer sustainability scorecard implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income trajectories and boreal harvest yield volatility would shift the trajectory. Forecasts reflect assumptions around F-Gas Regulation enforcement consistency and bamboo-residue blend certification approval pacing. Cross-checking against EU Green Deal implementation progress reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Mattress Market
Household Items
Permanent Marker Market
Household Items
Robot Mops Market
Household Items
Commercial Lawnmower Market
Household Items
UK Digital Showers Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Titanium Thermos Cup Market
Household Items
North America Water Purifier Market
Household Items
India POU Water Purifiers Market
Household Items
Remote Control Holder Market
Household Items
Toilet Rim Blocks Market
Household Items
Dryer Sheets Market
Household Items
Window Rain Guards Market
Household Items
Disposable Napkins Market
Household Items
Kuwait Gas Hobs Market
Household Items
Bottle Openers Market