
 Mini Security Camera Market | 2026-2036
Mini Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Security Camera Market Analytics
Residential smart home adoption is expanding as the fastest-growing end-use vertical for mini security cameras, displacing traditional commercial-first deployment patterns. Hikvision Digital Technology Co. Ltd. dominates domestic manufacturing scale across Asia, while Axis Communications AB differentiates through channel control in European professional installation markets. Arlo Technologies Inc. specializes in wireless DIY ecosystems for North American consumers, leveraging direct-to-consumer distribution against legacy dealer networks.
Mini security cameras are compact surveillance devices typically weighing under 250 grams, incorporating CMOS sensors, infrared LEDs for low-light operation, and Wi-Fi or Ethernet connectivity for real-time video transmission to local or cloud-based storage systems. Their primary purpose spans intrusion detection, remote property monitoring, and automated alert generation for residential, commercial, and institutional security operations. Wireless cameras lead product type growth due to falling lithium battery costs and simplified retrofit installation, while cloud storage technology captures expanding recurring revenue pools as HD recording bitrates drive local storage limitations. IP cameras maintain professional installation dominance where ONVIF interoperability and Power-over-Ethernet reliability outweigh consumer convenience priorities.
FCC certification governs radio frequency emissions for US market entry, while GDPR and the EU AI Act constrain facial recognition deployment and cloud data residency across European jurisdictions. China's MIIT enforces GB standards for network-connected cameras, creating divergent compliance burdens for manufacturers serving multiple geographies. Stakeholders must monitor evolving encryption mandates and cross-border data transfer restrictions as regulatory fragmentation intensifies product development complexity.
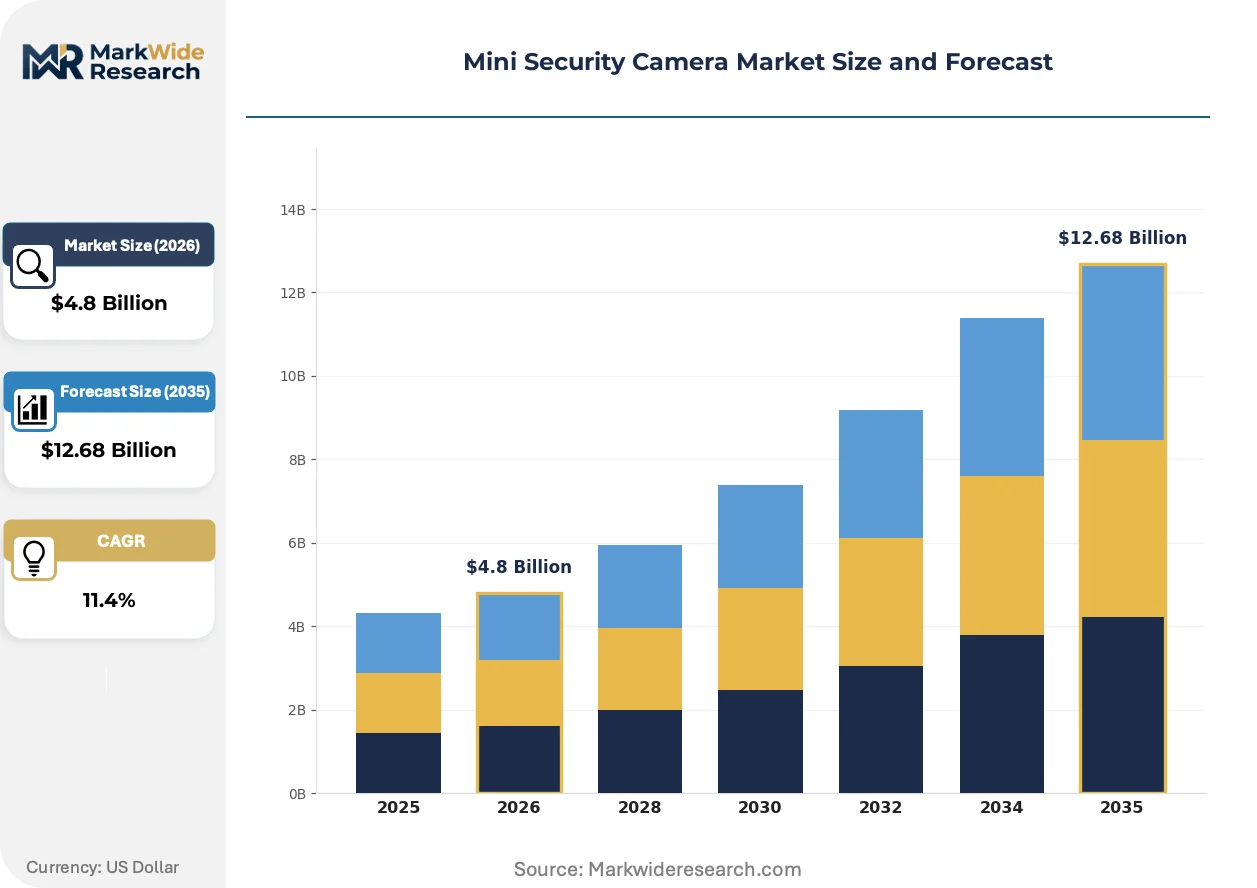
Market Dynamics
Residential DIY installation is compressing dealer margins and forcing incumbents to restructure channel economics around direct-to-consumer fulfillment and subscription software services.
Growth Catalysts
- EU AI Act compliance pathways:Manufacturers embedding privacy-by-design architectures capture professional installation contracts in European markets where GDPR data residency mandates disqualify non-compliant competitors.
- Power-over-Ethernet reliability:Commercial security integrators specify PoE mini cameras for campus and retail deployments where wireless signal interference risks operational continuity.
- Lithium battery cost curves:Falling cell prices enable wire-free form factors that penetrate rental housing and heritage building retrofits where conduit installation is prohibited.
Market Restraints
- CMOS sensor supply concentration:Sony and OmniVision anchor image sensor fabrication, creating input vulnerability for mid-tier camera assemblers during foundry allocation cycles.
- Cross-border data transfer friction:China's Cybersecurity Law and EU GDPR create divergent cloud storage architectures that fragment R&D budgets across incompatible regional product variants.
- Smartphone-based monitoring substitution:Doorbell cameras and mobile-integrated sensors capture perimeter security demand that previously flowed to standalone mini camera installations.
Strategic Opportunities
- India's Smart Cities Mission:Municipal surveillance tenders specify compact form factors for street furniture integration, opening public-sector procurement channels previously dominated by full-size dome cameras.
- Edge AI inference chips:On-device person detection and anomaly classification reduce cloud egress costs while enabling offline operation in bandwidth-constrained rural and industrial sites.
- Insurance premium discounts:North American property underwriters increasingly mandate verified video alarm systems for commercial policy renewals, creating specification pull-through from risk managers.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency authorization for new Wi-Fi 6E and Thread radio modules extends product launch windows by four to six months.
- Legacy analog infrastructure integration:Hybrid DVR compatibility requirements consume engineering resources for retrofit projects where coaxial cable reuse is specified.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Security Camera Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Cameras, Wireless Cameras, IP Cameras, PTZ Cameras Technology: Night Vision, Motion Detection, Cloud Storage, HD Recording Installation: Indoor Installation, Outdoor Installation, DIY Setup, Professional Setup End User: Residential Users, Commercial Establishments, Government Projects, Retail Outlets |
| Companies Covered | Bosch Security Systems, FLIR Systems, Hikvision Digital Technology Co. Ltd., Dahua Technology Co. Ltd., Axis Communications AB, Sony Corporation, Hanwha Vision, Arlo Technologies Inc., Reolink Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Security Camera Market Evolving Landscape
Computational imaging and on-device processing are redefining hardware-software boundaries, while regulatory fragmentation and channel restructuring force simultaneous adaptation across multiple operational dimensions.
Edge-based neural processing units are overtaking cloud-dependent analytics for real-time threat detection. These dedicated inference engines execute person, vehicle, and package classification locally without transmitting raw video streams. Residential installers and small commercial integrators specify NPU-equipped models to eliminate latency and reduce recurring SaaS fees. Battery-powered wireless cameras with sub-500 milliwatt inference workloads are compressing the addressable market for cloud-only subscription tiers.
GDPR Article 35 data protection impact assessments and the EU AI Act's high-risk system classification are mandating algorithmic transparency documentation for facial recognition deployments. Manufacturers must submit conformity assessments to notified bodies before placing products with biometric capabilities on the European market. Professional installation channels in Germany and France now require vendor-supplied DPIA templates and data processing agreements as standard procurement preconditions.
Subscription unbundling is fragmenting traditional hardware-plus-service bundles into component pricing. North American consumers increasingly purchase cameras through retail channels and separately evaluate cloud storage, local NVR software, or peer-to-peer mobile viewing without recurring fees. This pattern concentrates in the residential segment where Amazon and Best Buy shelf space drives price transparency and erodes proprietary ecosystem lock-in that sustained incumbent margins.
Mini Security Camera Market Segmentation
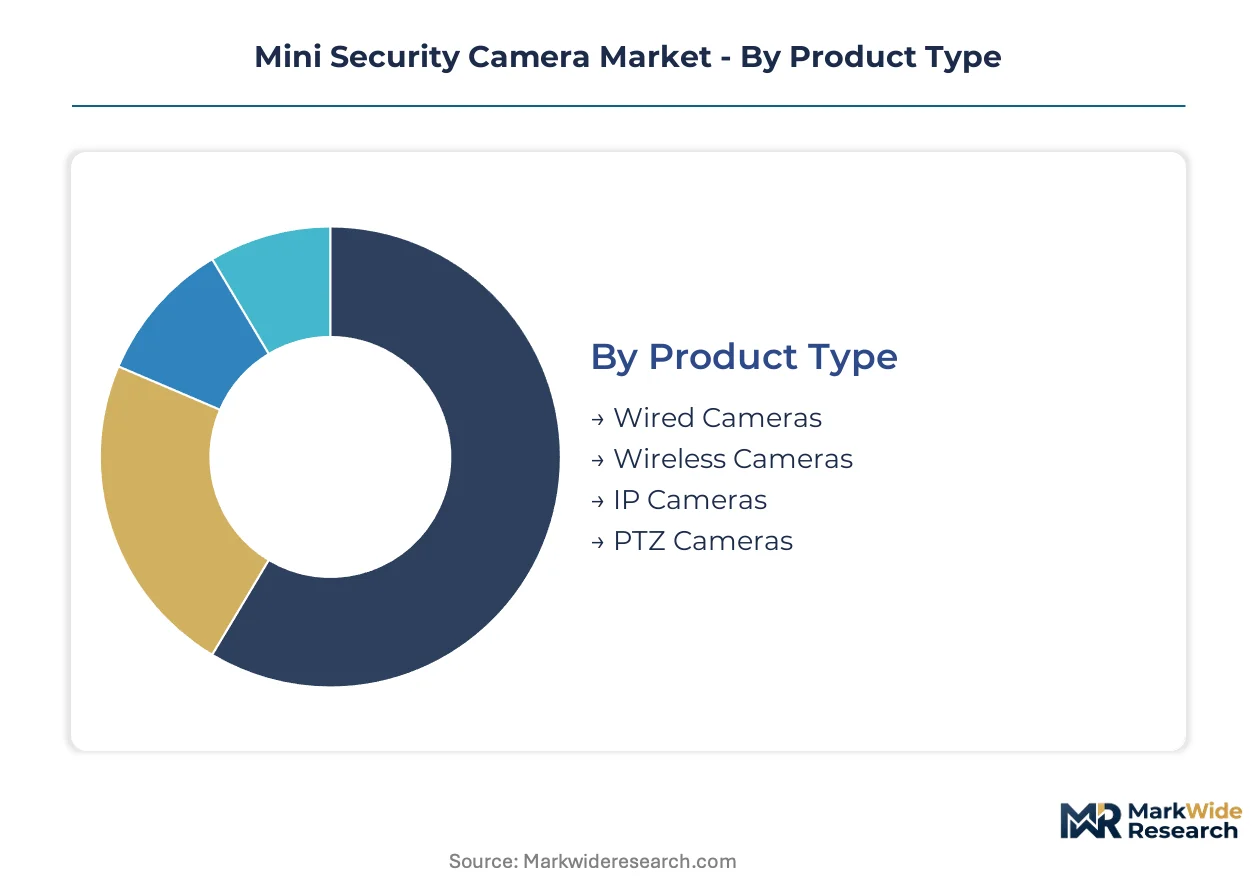
Mini security camera purchasing decisions split across four distinct configuration axes. Product type determines power infrastructure and network reliability. Technology selection governs recurring cost structures and offline capability. Installation mode channels margin capture between manufacturers and service providers. End-user classification shapes regulatory compliance burdens and procurement cycle length.
Product Type:
Customization intensity spans from plug-and-play consumer units to engineered PoE systems requiring site-specific cable runs.
- Wireless Cameras:Battery-powered units with Wi-Fi backhaul dominate rental housing retrofits where landlords prohibit wall penetration. Lithium cell cost declines enable multi-month operation between charges, accelerating adoption in heritage buildings and temporary construction site monitoring across Germany and Japan.
- IP Cameras:ONVIF-compliant Power-over-Ethernet devices anchor campus security specifications where signal reliability outweighs installation convenience. Professional integrators in France and South Korea specify these for retail chains and logistics facilities requiring centralized VMS integration.
- Wired Cameras:Coaxial or DC-powered analog-hybrid units serve budget-conscious retrofit projects reusing existing cable infrastructure.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms concentrate in perimeter defense and large-area coverage applications requiring active operator control.
Most installed capacity flows through IP Cameras. Expansion is steepest in Wireless Cameras.
Technology:
Feature bundling intensity correlates with customer technical sophistication and subscription revenue tolerance.
- Cloud Storage:Encrypted offsite recording with tiered retention periods generates recurring SaaS revenue streams. North American consumers and small commercial operators in Canada accept monthly fees for remote access convenience, though GDPR data residency requirements force European vendors to maintain regional server infrastructure.
- Motion Detection:PIR and pixel-change algorithms trigger recording conservation and mobile push notifications. This capability penetrates fastest in residential DIY markets where users prioritize battery preservation over continuous archive completeness.
- Night Vision:Infrared LED arrays and starlight sensors extend operational hours without visible illumination.
- HD Recording:1080p and 4K resolution options strain storage budgets and network bandwidth.
Volume concentrates in Motion Detection-enabled units. Steepest expansion trajectory belongs to Cloud Storage as vendors pivot from hardware margins to subscription economics.
Installation:
Channel control and margin capture diverge sharply between self-service retail and contracted professional deployment.
- DIY Setup:Magnetic mounts, adhesive strips, and app-guided configuration target consumers through Amazon and home improvement retail. This segment compresses dealer margins while expanding addressable market reach to technically confident homeowners in Australia and the United Kingdom.
- Professional Setup:Certified installer networks handle cable routing, network segmentation, and compliance documentation for commercial and government clients. Japanese and Swiss integrators command premium pricing for GDPR and data protection impact assessment support.
- Indoor Installation:Climate-controlled environments permit lighter ingress protection ratings and plastic housings.
- Outdoor Installation:IP65+ sealing and extended temperature tolerance specifications withstand environmental exposure.
Professional Setup commands highest per-unit revenue. DIY Setup is gaining share fastest as direct-to-consumer brands bypass traditional distribution.
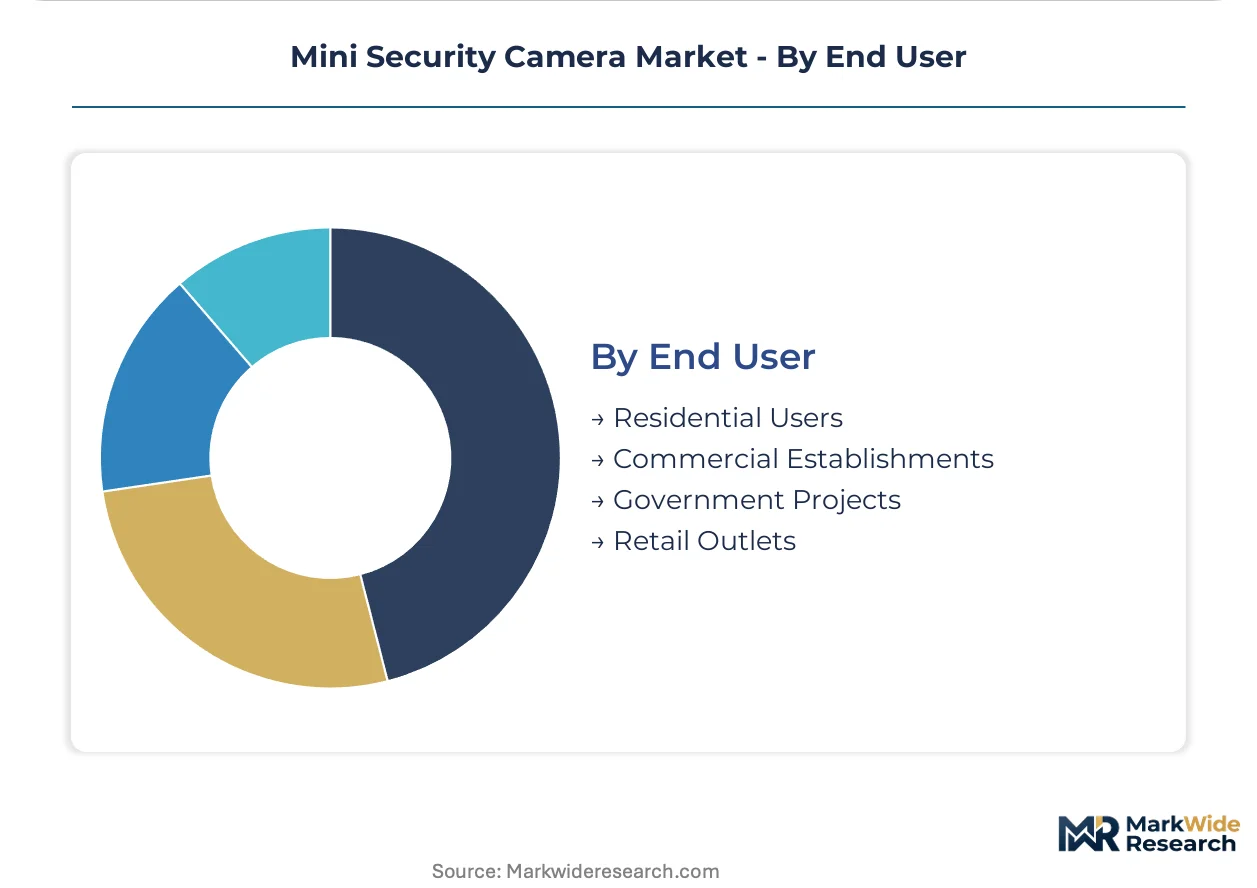
End User:
Procurement sophistication and compliance stringency escalate from individual consumers to institutional buyers.
- Residential Users:Individual homeowners and renters prioritize smartphone integration, voice assistant compatibility, and subscription flexibility. Demand concentrates in single-family detached housing across the United States and suburban developments in Saudi Arabia.
- Government Projects:Municipal surveillance tenders specify cybersecurity certification, domestic content requirements, and audit trail capabilities. India's Smart Cities Mission and Brazil's public safety programs drive formal procurement with extended vendor qualification timelines.
- Commercial Establishments:Offices, warehouses, and hospitality venues balance coverage density with insurance policy requirements.
- Retail Outlets:Loss prevention and customer flow analytics drive camera density in high-shrink merchandise categories.
Commercial Establishments represent largest installed base. Government Projects are expanding most quickly as public sector digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers migrate assembly to jurisdictions with lower compliance costs for data residency and cybersecurity certification. The divergence between China's MIIT GB standards and Europe's GDPR-EU AI Act dual framework creates a cost-of-compliance gap that favors regionalized manufacturing strategies.
China
Domestic installation growth and export manufacturing scale concentrate in Hangzhou and Shenzhen. MIIT enforces GB/T 28181 network security standards for connected cameras, forcing firmware segmentation for domestic versus export variants. Hikvision and Dahua anchor production clusters in Zhejiang and Guangdong provinces where component ecosystems and foundry partnerships minimize logistics costs.
United States
DIY residential penetration and insurance-mandated commercial specifications drive volume in California and Texas. FCC Part 15 certification governs radio frequency emissions for Wi-Fi 6E and Thread modules, extending product launch timelines by four to six months. Arlo Technologies exemplifies direct-to-consumer distribution models that bypass legacy dealer networks in suburban markets across Florida and Arizona.
Germany
Professional installation channels and GDPR Article 35 data protection impact assessments dominate procurement in Bavaria and North Rhine-Westphalia. The EU AI Act's high-risk system classification mandates notified body conformity assessments for facial recognition capabilities. Axis Communications occupies positioning within European professional integrator networks serving retail chains and logistics facilities.
India
Municipal surveillance tenders under the Smart Cities Mission specify compact form factors for street furniture integration in Maharashtra and Karnataka. BIS certification requirements and domestic content preferences create procurement barriers for non-local manufacturers. Delhi-NCR and Hyderabad emerge as installation hubs where system integrators bundle cameras with command center software for public safety deployments.
Japan
Heritage building retrofits and rental housing restrictions favor battery-powered wireless units in Tokyo and Osaka metropolitan areas. METI guidelines on IoT cybersecurity and JIS standards for ingress protection shape product specifications. Local integrators command premium pricing for compliance documentation and network segmentation services in Swiss-influenced regulatory-adjacent markets.
Mini Security Camera Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with residential DIY channels favoring direct-to-consumer brands while commercial installations privilege established security integrator relationships. The vendor base organizes into three tiers: vertically integrated component-to-system producers, software-centric platform operators, and regional assembly specialists serving price-sensitive procurement. Consolidation pressure concentrates in the mid-tier where scale disadvantages collide with R&D fragmentation across incompatible regional certification regimes. Dominant competitive moves include backward integration into image sensor sourcing and strategic partnerships with cloud infrastructure providers for data residency compliance.
Among vertically integrated Asian manufacturers, Hikvision Digital Technology Co. Ltd., Dahua Technology Co. Ltd., and Hanwha Vision occupy positions exemplifying scale-driven production archetypes with captive component supply and foundry relationships. These entities represent manufacturing gravity centers where domestic installation demand and export capacity expansion coexist. Within the wireless DIY specialist tier, Arlo Technologies Inc. and Reolink Technology Co. Ltd. exemplify direct-to-consumer distribution models that bypass traditional security dealer networks. Bosch Security Systems and Axis Communications AB anchor European professional installation channels where GDPR compliance documentation and data processing agreements serve as procurement preconditions. Sony Corporation represents component-level positioning through image sensor supply to downstream assemblers, capturing value upstream of finished system integration.
| Leading Market Players |
|---|
| Bosch Security Systems |
| FLIR Systems |
| Hikvision Digital Technology Co. Ltd. |
| Dahua Technology Co. Ltd. |
| Axis Communications AB |
| Sony Corporation |
| Hanwha Vision |
| Arlo Technologies Inc. |
| Reolink Technology Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Edge AI inference chip integration is compressing hardware margins while fragmenting supplier power across CMOS sensor foundries and lithium battery cell manufacturers. This technology shift simultaneously elevates R&D amortization burdens for NPU-equipped models and concentrates procurement leverage among Sony and OmniVision for image sensors.
Pricing Analysis
Retailer markup compression in DIY channels is forcing manufacturers toward direct-to-consumer fulfillment with subscription-anchored revenue. Pricing stratifies across premium PoE systems with ONVIF certification, standard wireless units with cloud bundling, and economy wired cameras for analog retrofit projects. Cost compression in the wireless tier intensifies as falling lithium cell prices enable aggressive hardware subsidization. Residential consumers exhibit highest price sensitivity, while commercial integrators purchasing through professional channels prioritize reliability specifications over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs is amplifying inventory carrying costs for North American and European distributors. Component sourcing concentrates in China for final assembly, Taiwan for CMOS wafer fabrication, and South Korea for lithium-ion cells. Supply chain vulnerability rests on single-source dependency for Sony image sensors during foundry allocation cycles. Distribution runs through hybrid models: direct-to-consumer platforms for residential DIY, authorized integrator networks for commercial PoE deployments, and municipal procurement channels for government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mini security camera market functions as a stable compounder where recurring SaaS revenue from cloud storage subscriptions generates predictable cash flow streams alongside hardware replacement cycles.
For Market Incumbents: To counter direct-to-consumer entrants eroding dealer margins, Hikvision and Dahua should deepen backward integration into CMOS sensor supply through foundry partnerships, while Axis Communications must fortify GDPR compliance documentation as a procurement precondition for European professional integrators. For New Entrants and Emerging Players: Launch via insurance-backed specification channels targeting North American commercial policy renewals that mandate verified video alarm systems, while exploiting India's Smart Cities Mission tenders for compact street furniture integration where domestic content requirements favor local system integrators. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier assemblers lacking captive cloud infrastructure but holding regional certification expertise. Long-term viability hinges on subscription attach rates and data residency compliance capabilities. The signal to watch is edge AI inference workload migration compressing addressable market for cloud-only analytics tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | On-device NPU deployment reduces cloud egress costs for bandwidth-constrained industrial sites. |
| GDPR Compliance Certification | Notified body assessments for facial recognition capabilities unlock German and French procurement channels. |
| Direct-to-Consumer Platform Launch | Amazon and Best Buy shelf space bypasses legacy dealer networks in suburban US markets. |
| Domestic Content Partnership | India BIS certification and local assembly requirements satisfy Smart Cities Mission tender specifications. |
| Insurance Channel Specification | Verified video alarm mandates from North American property underwriters create pull-through demand. |
Research Methodology
Multiple input streams — primary interviews with security integrators and procurement officers, regulatory filing analysis, and trade flow databases — were reconciled to construct segment-level demand estimates. Conversations with professional installers in Germany, municipal tender administrators in India, and cloud platform engineers informed technology adoption assumptions. Secondary validation drew from FCC certification records, EU AI Act conformity assessment documentation, MIIT GB standard filings, and customs data for CMOS sensor and lithium cell imports. Bottom-up unit economics and top-down macroeconomic indicators were triangulated to anchor volume projections.
Data-stream reconciliation across product type, installation mode, technology tier, and end-user classification generated the analytical framework. Segmentation dimensions modeled include wireless versus PoE power infrastructure, DIY versus professional deployment, cloud versus local storage architectures, and residential versus commercial versus government procurement channels. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating lithium battery cost decline trajectories and regulatory compliance timeline assumptions as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU AI Act enforcement or extended CMOS foundry allocation constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market