
 India Surveillance Camera Market | 2026-2036
India Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
India Surveillance Camera Market Insights
High-resolution 4K and AI-integrated specification tiers is bifurcating the India Surveillance Camera Market into premium enterprise contracts and price-sensitive mass installations. Hikvision India leverages its domestic manufacturing footprint under PLI incentives to sustain cost competitiveness in government tenders. Godrej Security Solutions anchors its position through deep channel control across tier-two and tier-three cities. CP Plus differentiates via aggressive pricing in the small commercial segment while maintaining BIS compliance.
India surveillance cameras encompass electro-optical imaging devices with sensors ranging from 2MP to 12MP resolution, designed for continuous video capture, storage, and remote monitoring across commercial, institutional, and residential environments. These systems employ H.265+ compression codecs and edge-computing chipsets to enable real-time facial recognition and behavioral analytics at the device level. IP cameras now lead product type dynamics as enterprises abandon coaxial analog infrastructure for Power-over-Ethernet deployments that reduce cabling costs and enable centralized management. Cloud-based technology represents the fastest-growing architecture segment, though margin pools remain concentrated in hybrid on-premise installations serving banking and critical infrastructure clients. Dome cameras dominate indoor commercial applications where discrete positioning matters, while bullet cameras and PTZ units capture outdoor transportation and perimeter security contracts.
BIS certification requirements and CEA electrical safety standards shape product eligibility for government procurement, forcing import-dependent brands to localize testing and assembly. The PLI scheme for IT hardware extends to surveillance equipment, conditioning subsidy access on domestic value-add thresholds and export obligations. Stakeholders must monitor how TRAI's data localization directives and proposed drone integration rules reshape video storage architectures and edge-to-cloud data flows.
Market Dynamics
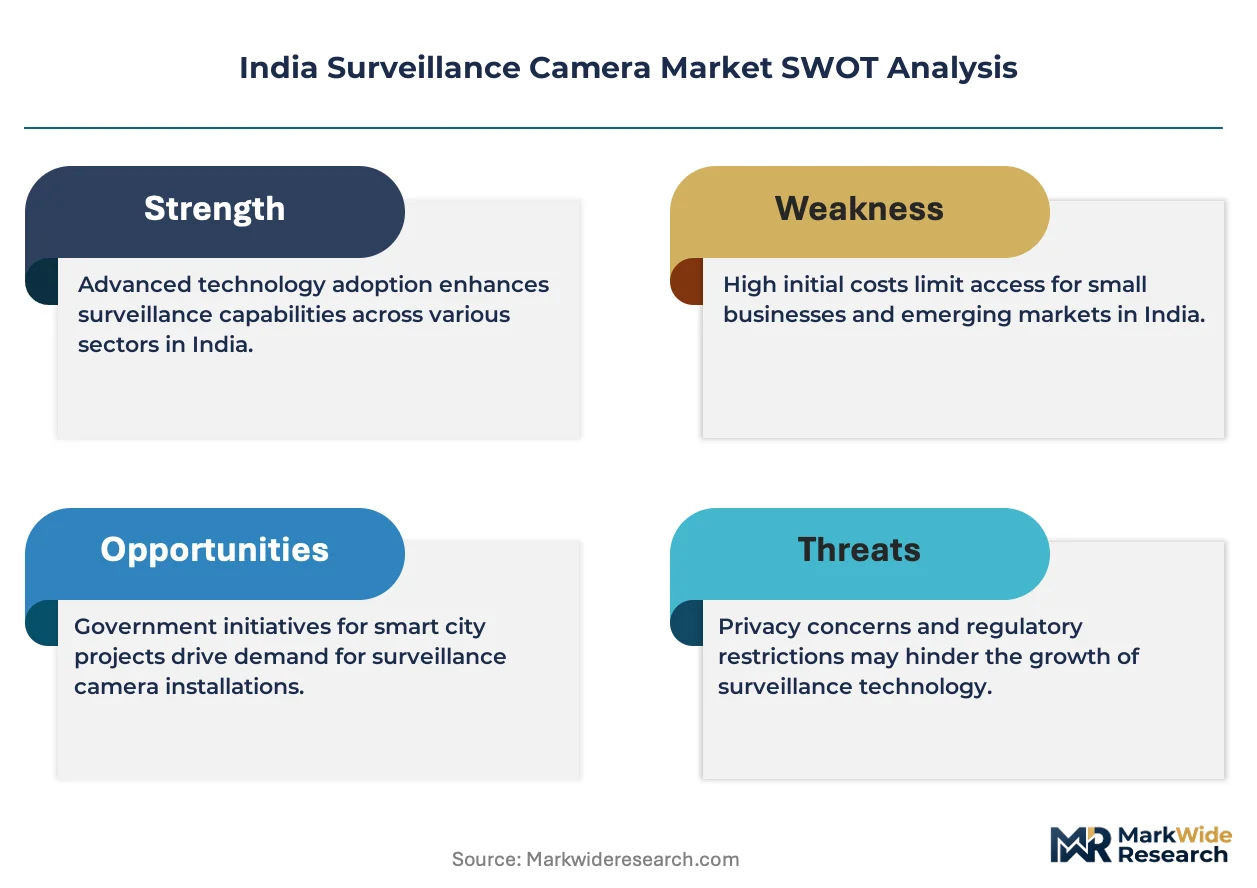
The India Surveillance Camera Market is undergoing structural compression as BIS certification mandates and PLI localization requirements force import-dependent vendors to rebuild supply chains around domestic assembly and testing infrastructure.
Growth Catalysts
- Smart city infrastructure mandates:Municipal corporations in Maharashtra, Karnataka, and Telangana are deploying AI-enabled video analytics systems for traffic management and public safety monitoring.
- Metro rail expansion programs:Urban transit authorities require high-density camera networks for platform surveillance and crowd flow analysis across new corridor constructions.
- PLI scheme subsidies:The IT hardware production-linked incentive scheme conditions subsidy access on domestic value-add thresholds, accelerating local manufacturing investments.
Market Restraints
- CMOS sensor import dependency:Domestic manufacturers rely on concentrated East Asian suppliers for image sensor modules, exposing margins to currency volatility and shipping disruptions.
- BIS certification timelines:The Bureau of Indian Standards testing protocols for electronic security products create 4-6 month product launch delays for new entrants.
- Coaxial infrastructure lock-in:Legacy analog installations in tier-three cities and public institutions resist full IP migration due to rewiring costs and technical staff retraining requirements.
Strategic Opportunities
- Drone integration frameworks:Proposed DGFT and civil aviation regulations for unmanned aerial vehicle surveillance are creating demand for airborne camera stabilization and real-time video downlink systems.
- Edge-to-cloud hybrid architectures:Banking and critical infrastructure clients are adopting distributed storage models that combine on-premise NVR retention with cloud analytics.
- Tier-two city channel penetration:Underpenetrated markets in Madhya Pradesh, Rajasthan, and Uttar Pradesh present whitespace for organized brands with service network capabilities.
Industry Challenges
- Video analytics engineering talent scarcity:Machine learning model optimization for Indian facial recognition datasets requires specialized computer vision expertise that domestic technical institutes have not scaled.
- Multi-vendor integration complexity:Enterprise clients demand unified management platforms across Hikvision, Dahua, and domestic brand installations, forcing systems integrators to build middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Surveillance Camera Market |
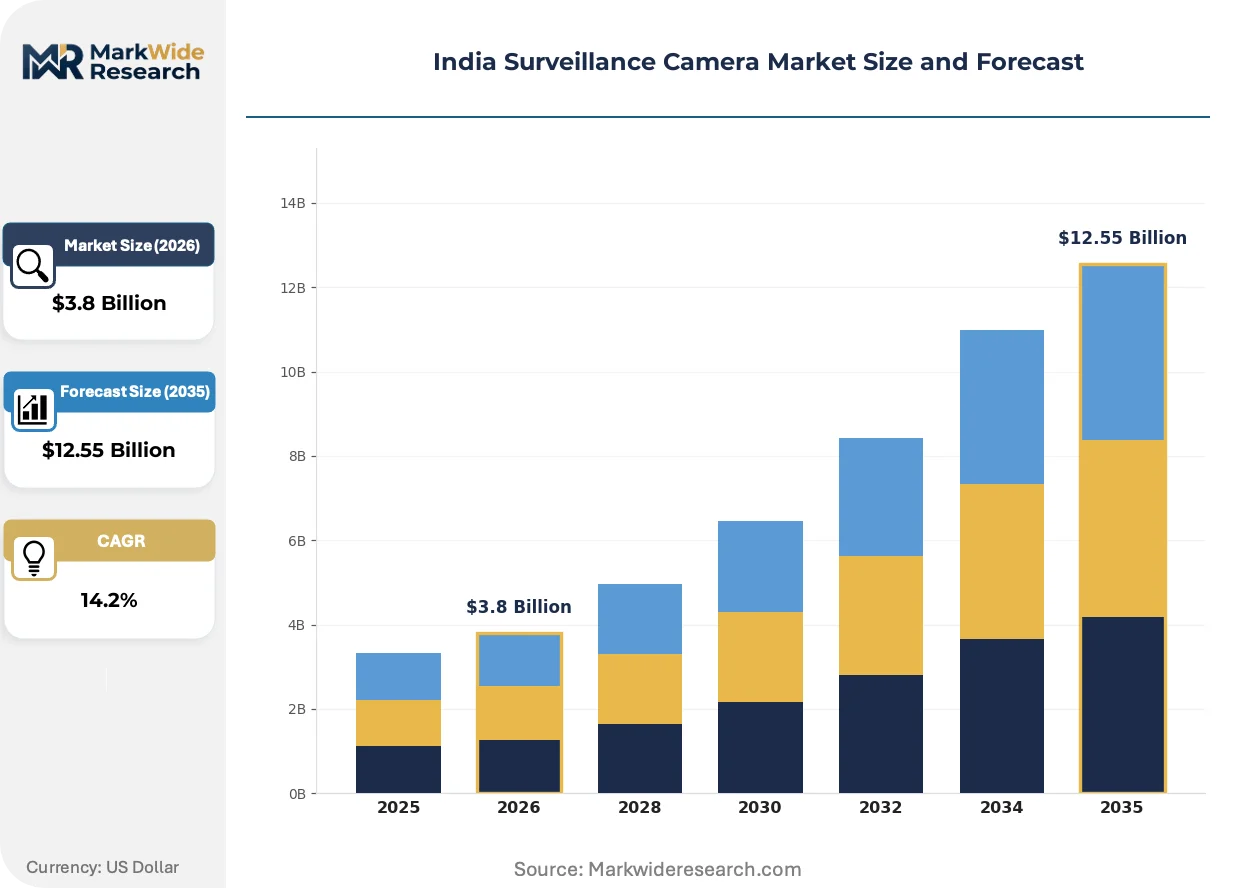
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, IP Cameras End User: Retail Stores, Public Infrastructure, Residential, Transportation Technology: Analog, IP, Wireless, Cloud-Based Installation Type: Indoor, Outdoor, Hybrid, Covert |
| Companies Covered | Godrej Security Solutions, Axis Video Systems India Pvt. Ltd, HIKVISION Digital Technology Co. Ltd (Hikvision India), Vintron Informatics Ltd, D-Link India Limited, Dahua Technology India Pvt. Ltd, Honeywell Commercial Security, Vantage Security Ltd, Aditya Infotech Ltd (CP Plus), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Surveillance Camera Market Trends and Innovations
Technology convergence between edge computing silicon and compression codecs is compressing hardware replacement cycles while regulatory pressure on data localization is reshaping storage architecture decisions.
AI-accelerated chipsets with dedicated neural processing units are bifurcating the specification landscape. Premium enterprise contracts now demand on-device facial recognition and behavioral analytics, while price-sensitive mass installations in residential and small commercial segments retain basic motion detection. This technical stratification enables vendors to defend margin pools in banking and critical infrastructure while competing aggressively on unit economics in standardized tenders.
TRAI data localization directives are forcing cloud-dependent architectures toward domestic server deployments. The regulatory friction most affects hybrid installations serving financial services clients, where video retention compliance intersects with RBI cybersecurity guidelines. Vendors are responding by certifying local data center partnerships and edge-heavy designs that minimize cross-border transmission.
Buying patterns among municipal corporations are consolidating around integrated command center contracts. Systems integrators now capture camera supply, installation, and multi-year maintenance within single tender awards, displacing the previous model of discrete hardware procurement. This bundling is most visible in Telangana and Karnataka smart city deployments, where annual maintenance contracts now exceed 15% of initial capital outlay in total project valuation.
India Surveillance Camera Market Segmentation
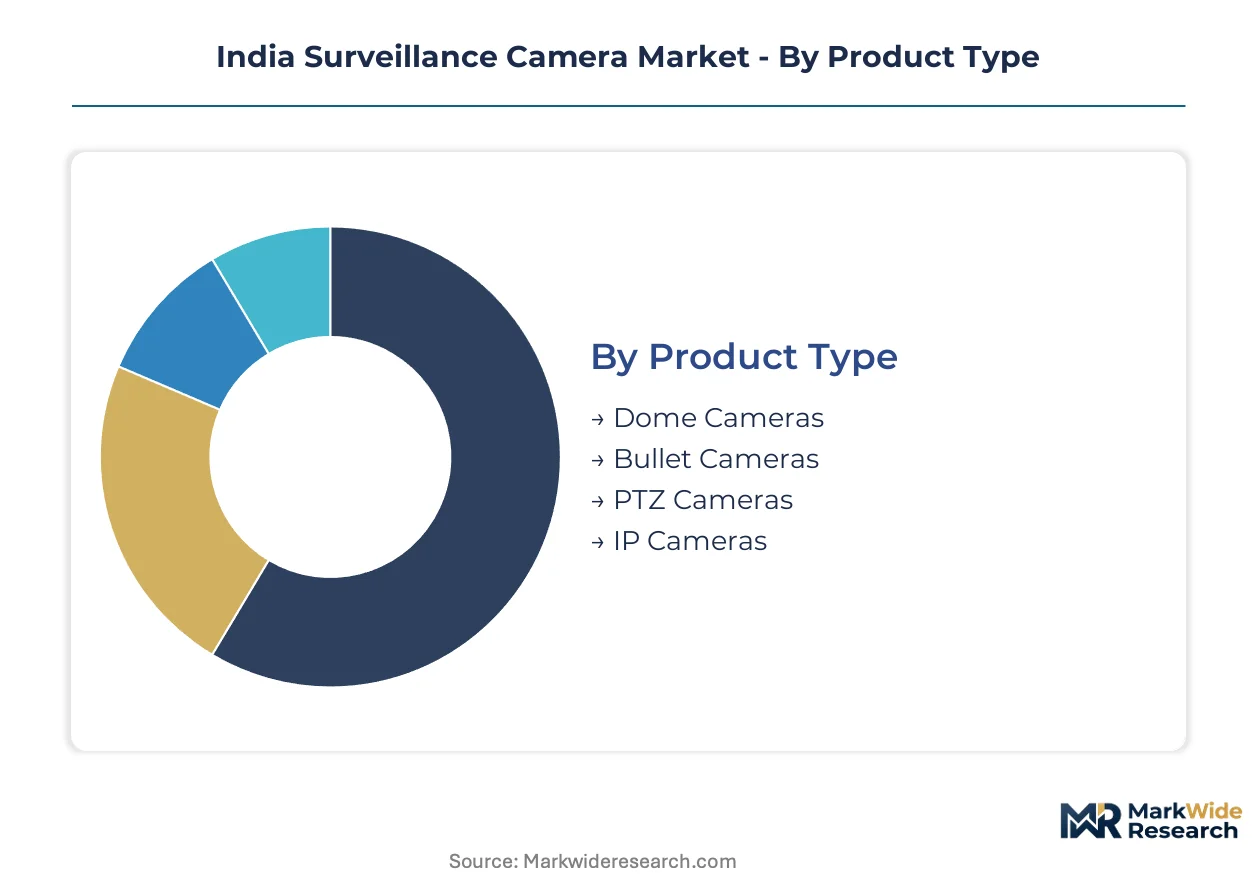
Segmentation in the India Surveillance Camera Market reveals how BIS certification tiers and PLI localization thresholds are redistributing procurement budgets across product architectures. Procurement officers in Maharashtra municipal corporations and Karnataka metro rail authorities now weight compliance grade as heavily as resolution specifications when evaluating vendor bids.
Product Type:
IP cameras face the most intense substitution pressure from legacy analog stockpiles in tier-three cities, while dome and bullet formats compete for share in new smart city deployments where discrete positioning versus perimeter visibility drives selection.
- IP Cameras:Power-over-Ethernet architectures with H.265+ compression codecs enable centralized management and reduce cabling costs. Demand concentrates in Telangana banking sector and Karnataka commercial real estate where enterprises abandon coaxial infrastructure for scalable network video recorder integration.
- Dome Cameras:Vandal-resistant housings with 360-degree coverage suit discrete indoor positioning in Maharashtra retail clusters and hotel lobbies. Discrete form factors capture premium enterprise contracts where aesthetic integration matters alongside AI-enabled facial recognition capabilities.
- Bullet Cameras:Weather-sealed housings with infrared arrays serve perimeter security and outdoor transportation corridors across Telangana and Karnataka metro expansions.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with optical zoom ranges support traffic management and crowd flow analysis in smart city command centers.
IP cameras anchors the volume base while PTZ cameras gains share at the steepest rate in municipal and transportation tenders requiring remote operability.
End User:
Cost tier stratification separates premium enterprise installations with multi-year maintenance contracts from price-sensitive residential deployments where basic motion detection suffices.
- Public Infrastructure:Municipal corporations in Maharashtra, Karnataka, and Telangana deploy AI-enabled video analytics for traffic management and public safety monitoring. Smart city mandates require BIS-certified equipment with edge-computing chipsets capable of real-time behavioral analytics.
- Transportation:Metro rail authorities demand high-density camera networks for platform surveillance and passenger flow optimization across new corridor constructions in Hyderabad and Bengaluru. Integrated command center contracts bundle supply, installation, and maintenance exceeding fifteen percent of initial capital outlay.
- Retail Stores:Loss prevention systems with facial recognition integration serve organized retail in tier-one and tier-two cities.
- Residential:Basic Wi-Fi enabled units with cloud storage subscriptions penetrate apartment complexes and gated communities.
Public infrastructure commands the highest average contract value while residential expands most quickly through channel penetration in Madhya Pradesh and Uttar Pradesh.
Technology:
Application requirements dictate architecture selection, with financial services demanding hybrid edge-to-cloud models and small commercial settling for standalone wireless deployments.
- Cloud-Based:Distributed storage architectures with domestic server partnerships address TRAI data localization directives and RBI cybersecurity guidelines. Banking clients in Mumbai and Hyderabad adopt hybrid models combining on-premise retention with cloud analytics.
- IP:Network-based transmission with Power-over-Ethernet reduces infrastructure costs and enables centralized management across enterprise campuses.
- Wireless:Wi-Fi and cellular backhaul serve temporary installations and retrofit scenarios where cabling is impractical.
- Analog:Coaxial infrastructure persists in tier-three cities and legacy public institutions resisting full migration due to rewiring costs.
IP technology retains the largest installed base while cloud-based climbs the fastest as regulatory pressure reshapes storage decisions.
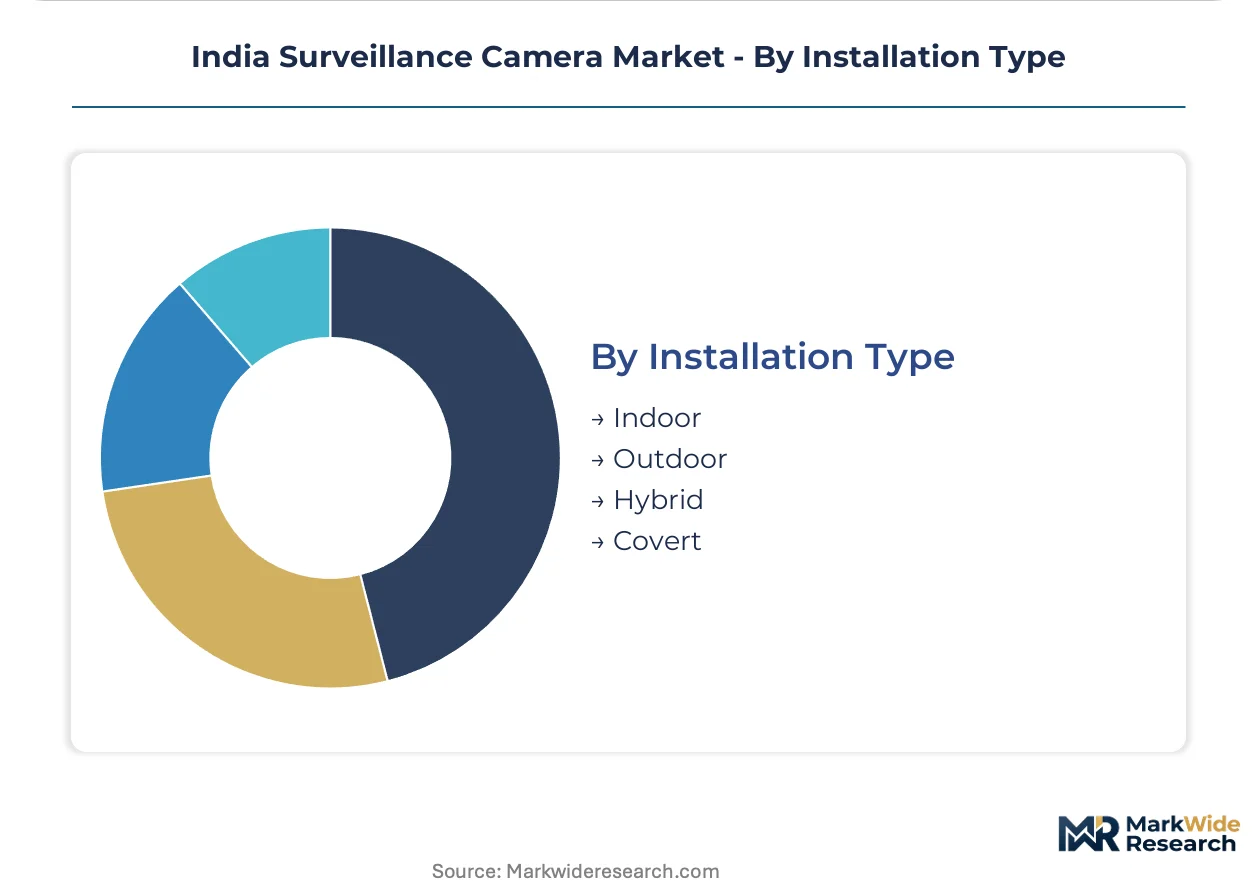
Installation Type:
Geography within India determines environmental hardening requirements, with coastal Maharashtra demanding corrosion resistance and northern plains requiring dust sealing.
- Outdoor:Weatherproof housings with IP66 ratings and infrared illumination serve perimeter security and transportation corridors across Karnataka and Telangana metro networks. Thermal cycling resistance and moisture sealing add cost premiums over indoor equivalents.
- Indoor:Climate-controlled environments enable lighter housings and lower power consumption in Maharashtra commercial real estate and retail clusters.
- Hybrid:Mixed indoor-outdoor deployments with unified management platforms serve campus-style installations.
- Covert:Disguised housings for investigative and specialized security applications in banking and government facilities.
Outdoor installations generate the highest per-unit revenue while hybrid configurations are expanding most quickly in integrated smart city tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing clusters under PLI incentives concentrate assembly capacity in western and southern India, while procurement demand concentrates in Maharashtra, Karnataka, and Telangana where smart city mandates and metro rail expansions drive large-scale installations.
Maharashtra
Mumbai municipal corporations deploy AI-enabled video analytics for traffic management and crowd monitoring across dense urban corridors. BIS certification requirements for electronic security products shape vendor eligibility in state government tenders. Pune and Thane industrial clusters host domestic assembly operations serving western India distribution networks.
Karnataka
Bengaluru metro rail authorities procure high-density camera networks for platform surveillance and passenger flow optimization across new corridor constructions. The state's PLI scheme beneficiaries localize testing and assembly to meet domestic value-add thresholds. Mysuru and Hubballi smart city deployments bundle hardware supply with multi-year maintenance contracts exceeding fifteen percent of initial capital outlay.
Telangana
Hyderabad municipal corporations integrate command center contracts that combine camera supply, installation, and maintenance within single tender awards. TRAI data localization directives push banking sector clients toward hybrid edge-to-cloud architectures with domestic server partnerships. Cyberabad technology corridor drives demand for facial recognition-enabled enterprise installations.
Gujarat
Surat and Ahmedabad municipal corporations implement perimeter security systems for port infrastructure and commercial real estate clusters. CEA electrical safety standards shape product eligibility for state government procurement. Vadodara industrial zones attract PLI scheme investments in surveillance equipment assembly serving northwestern markets.
Tamil Nadu
Chennai metro rail expansion programs require weather-sealed bullet cameras and PTZ units for outdoor transportation corridors. The state's manufacturing ecosystem supports component localization for import-dependent sensor modules. Coimbatore and Madurai tier-two markets present whitespace for organized brands with service network capabilities.
India Surveillance Camera Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the India Surveillance Camera Market. Domestic manufacturers leverage PLI subsidies and BIS certification proximity to anchor government tender participation, while multinational subsidiaries import advanced chipsets and compression technologies through established East Asian supply channels. Three archetypes dominate: scale-driven fabricators with integrated domestic assembly, technology licensors with premium enterprise positioning, and price-focused distributors with deep tier-two channel penetration. Competitive moves center on backward integration into sensor module sourcing and strategic partnerships with systems integrators bundling hardware with multi-year maintenance contracts.
Among domestic security conglomerates, Godrej Security Solutions exemplifies channel control archetypes with established tier-two and tier-three city networks. Hikvision India and Dahua Technology India Pvt. Ltd represent multinational technology licensors that have localized assembly operations under PLI incentives to sustain cost competitiveness in standardized government tenders. These three anchors illustrate how vendor positioning splits between domestic manufacturing scale and imported technology premiumization.
| Leading Market Players |
|---|
| Godrej Security Solutions |
| Axis Video Systems India Pvt. Ltd |
| HIKVISION Digital Technology Co. Ltd (Hikvision India) |
| Vintron Informatics Ltd |
| D-Link India Limited |
| Dahua Technology India Pvt. Ltd |
| Honeywell Commercial Security |
| Vantage Security Ltd |
| Aditya Infotech Ltd (CP Plus) |
| Others |
Pricing and Supply Chain Analysis
CMOS sensor import substitution from East Asian suppliers to domestic assembly operations simultaneously redistributes manufacturing geography toward Maharashtra and Karnataka industrial corridors and compresses margin structures for vendors competing in BIS-certified government tenders. PLI scheme localization thresholds force import-dependent brands to absorb higher domestic value-add costs, creating pricing divergence between subsidy-eligible fabricators and technology licensors sourcing advanced chipsets through established offshore channels.
Pricing Analysis
BIS certification dictates the pricing tier structure across the India Surveillance Camera Market, separating premium enterprise contracts with AI-enabled edge analytics from price-sensitive mass installations serving residential and small commercial segments. Certification grade and after-sales service bundling drive price differentiation, with integrated command center contracts capturing annual maintenance exceeding fifteen percent of initial capital outlay. Pricing pressure stems from aggressive government tender competition among PLI beneficiaries, while residential buyers in tier-two cities exhibit highest price sensitivity and banking sector clients show lowest.
Supply Chain Analysis
Malacca Strait transit and Singapore port congestion expose Indian surveillance equipment supply chains to logistics chokepoints affecting CMOS sensor modules from Taiwan, South Korea, and Japan. Domestic assembly draws from concentrated East Asian sources for image sensors, neural processing units, and H.265+ compression chipsets, creating single-source vulnerability for high-specification components. Distribution runs through systems integrators bundling hardware with multi-year maintenance contracts, displacing discrete procurement in municipal and metro rail tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Surveillance Camera Market functions as a service-attach opportunity where integrated command center contracts and annual maintenance agreements expand faster than standalone hardware sales, rewarding vendors with field service network density across tier-two and tier-three cities.
For Market Incumbents: Fortify channel control through backward integration into domestic sensor module testing and certification infrastructure under PLI scheme thresholds. Deepen service network penetration in underpenetrated Madhya Pradesh and Uttar Pradesh markets to defend margin pools against price-focused distributors. Prioritize BIS certification proximity as competitive moat against emerging entrants facing four-to-six month approval timelines. For New Entrants and Emerging Players: Anchor in tier-two city whitespace where organized brands lack service coverage, targeting Rajasthan and Tamil Nadu municipal corporations with simplified dome camera portfolios. Pursue drone integration frameworks as regulatory clarity emerges from DGFT and civil aviation authorities. Lead with cloud-native architectures addressing TRAI data localization directives to differentiate from legacy on-premise incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors systems integrators with multi-year maintenance contract backlogs and BIS certification capabilities. Long-term viability over a five-to-ten year window rests on service revenue attachment rates rather than hardware shipment volumes. Monitor PLI scheme beneficiary lists as inflection indicator for domestic manufacturing scale advantages shifting competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Localization | PLI scheme certification unlocks subsidy access and government tender eligibility for Maharashtra and Karnataka facilities. |
| Edge-to-Cloud Hybrid Architecture | Domestic server partnerships address TRAI data localization mandates for Mumbai and Hyderabad banking sector clients. |
| Channel Network Expansion | Service density in tier-two cities captures whitespace as municipal procurement consolidates around integrated contracts. |
| AI Chipset Integration | Neural processing unit adoption bifurcates specifications between premium facial recognition and basic motion detection tiers. |
| Drone Surveillance Partnership | DGFT regulatory frameworks create demand for airborne camera stabilization and real-time video downlink systems. |
Research Methodology
Desk research of BIS certification databases, PLI scheme beneficiary disclosures, and municipal corporation tender archives preceded structured interviews with systems integration directors, municipal procurement officers, banking sector security heads, and channel distribution partners. Secondary validation drew from TRAI regulatory circulars, CEA electrical safety standards, and state smart city mission documentation. Bottom-up shipment estimates from vendor production data triangulated against top-down procurement budget allocations across Maharashtra, Karnataka, and Telangana.
Variance decomposition across product architecture, end-user vertical, and technology deployment model shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include camera form factor, installation environment, compression codec tier, and state-level regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle compression, incorporating edge-computing adoption curves and cloud storage penetration rates as industry-specific forecast inputs.
Underlying assumptions cover BIS certification timeline stability, PLI scheme continuity, and CMOS sensor supply chain resilience, with deviation risk concentrated in import tariff fluctuations and TRAI data localization enforcement intensity. Practitioners should keep alternative scenarios live as DGFT drone integration rules and state-level smart city funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Smart Home Security Camera Market