
 Security Camera Software Market | 2026-2036
Security Camera Software Market Size, Share, and Industry Trends Forecast 2026-2036
Security Camera Software Market Insights
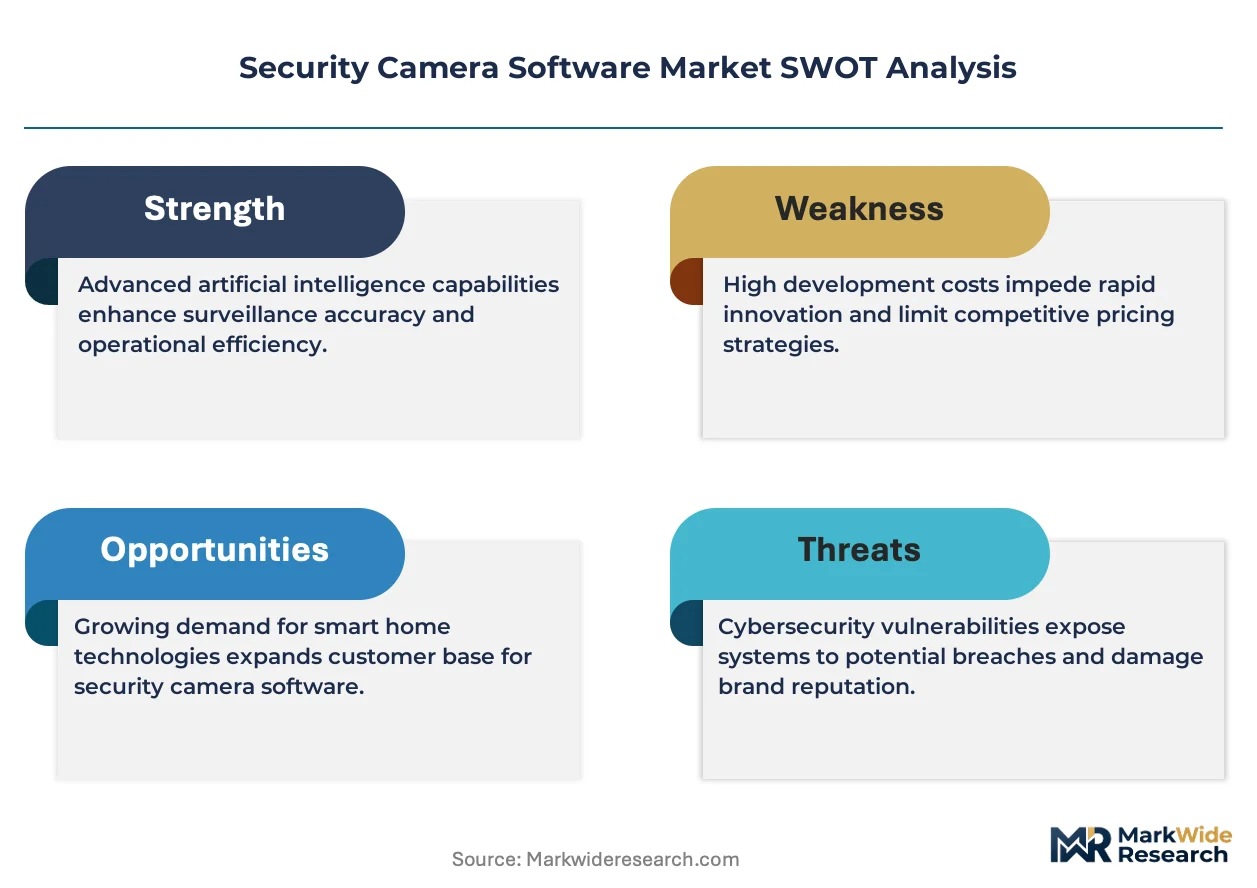
GPU-accelerated inference silicon is pivoting the cost structure of real-time video analytics, displacing CPU-bound processing in high-channel-count deployments. Genetec leverages its unified security platform to anchor enterprise accounts across transportation and government verticals. Axis Communications competes through open-architecture camera-to-cloud integration, while Verkada sustains growth via vertically integrated hardware-software subscriptions with minimal on-premise infrastructure.
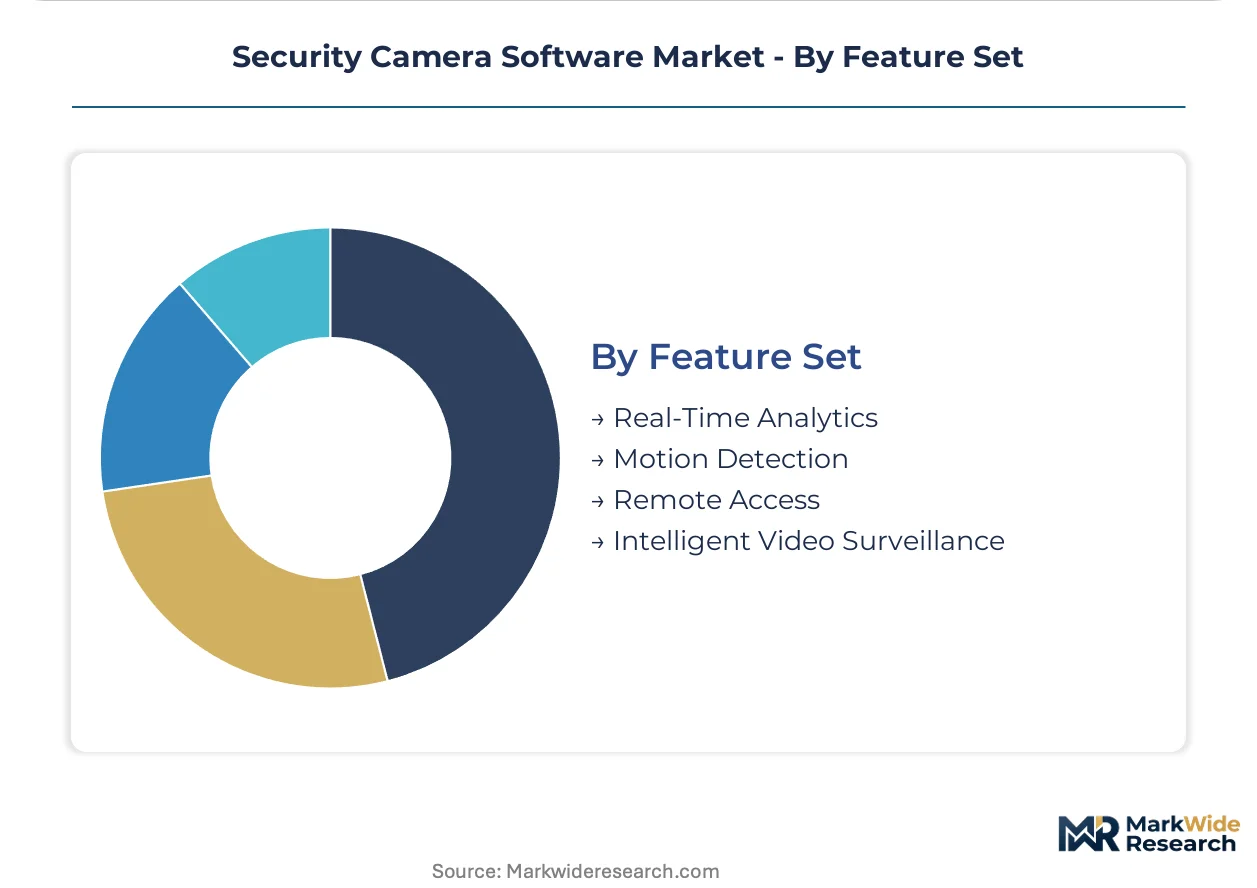
Security camera software encompasses video management systems, analytics engines, and remote access platforms that process, store, and interpret surveillance feeds from IP and analog camera networks, typically operating at 30 frames per second with H.265 compression to minimize bandwidth and storage overhead. Cloud-based solutions lead the solution type category due to lower upfront capital requirements and centralized update management, while edge computing represents the fastest-growing segment as on-camera inference reduces latency for motion detection and real-time analytics. The feature set dimension shows intelligent video surveillance capturing the deepest margin pools, since AI-powered object classification and behavioral analysis command premium licensing tiers.
FCC guidelines govern wireless transmission protocols for remote access deployments, while the EU AI Act imposes conformity assessments on biometric identification systems sold into European member states. GDPR data retention limits and the EU Green Deal's energy efficiency directives are reshaping storage architectures and hardware refresh cycles. Stakeholders must weigh the trade-off between cloud analytics scalability and edge autonomy as regulatory fragmentation around biometric data intensifies compliance complexity.
Market Dynamics
GPU-accelerated inference silicon is compressing the cost-per-channel economics of real-time video analytics, forcing legacy CPU-bound architectures into obsolescence across high-density surveillance deployments.
Growth Catalysts
- FCC wireless protocol guidelines:Remote access deployments for critical infrastructure now operate under clearer transmission standards, accelerating municipal and utility sector adoption of cloud-connected camera networks.
- EU AI Act conformity assessments:Biometric identification systems sold into European member states face mandatory certification, creating a compliance-driven upgrade cycle for existing facial recognition installations.
- Edge inference silicon:On-camera processing for motion detection and object classification eliminates round-trip latency to cloud servers, enabling real-time alerting for transportation and logistics security teams.
Market Restraints
- GPU supply concentration:NVIDIA and AMD fabrication capacity constraints create procurement bottlenecks for analytics appliance manufacturers, extending lead times for high-channel-count deployments.
- GDPR data retention limits:European storage architectures must purge footage within defined windows, forcing shorter retention policies that conflict with insurance and legal hold requirements in other jurisdictions.
- Legacy analog infrastructure:Hybrid IP-analog transition costs deter mid-market facilities from full platform migrations, preserving lower-margin DVR-based revenue streams.
Strategic Opportunities
- EU Green Deal energy directives:Hardware refresh cycles now prioritize low-power edge devices, opening procurement windows for thermal-efficient camera systems with embedded inference engines.
- Behavioral analytics convergence:Integration of video feeds with access control and identity management platforms creates unified physical security suites commanding premium licensing.
- India smart city mandates:Urban surveillance modernization programs under the Ministry of Home Affairs are tendering large-scale intelligent video management installations.
Industry Challenges
- ISO/IEC 27001 certification timelines:Cloud platform providers face extended audit cycles for information security management, delaying go-to-market for new SaaS analytics offerings.
- Multi-vendor integration complexity:ONVIF Profile compliance varies across camera manufacturers, requiring custom middleware development for unified command center deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Camera Software Market |
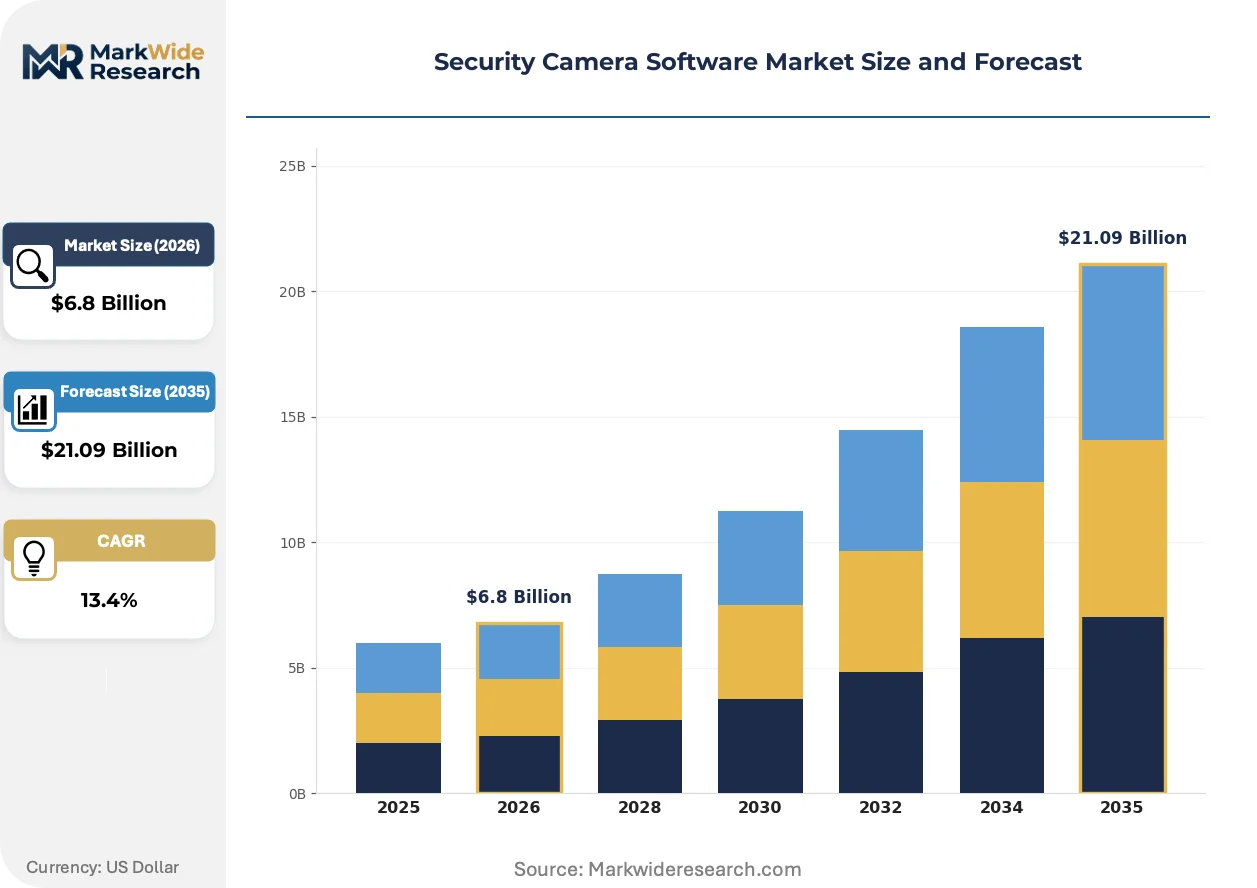
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, Edge Computing Deployment Model: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant End User: Retail Stores, Transportation Hubs, Residential, Enterprises Feature Set: Real-Time Analytics, Motion Detection, Remote Access, Intelligent Video Surveillance |
| Companies Covered | Genetec, Avigilon, Axis Communications, Verkada, Milestone, Lumana, Rhombus, Eagle Eye Networks, Hanwha Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Camera Software Market Trends and Innovations
Three forces are restructuring competitive advantage: silicon economics favoring edge compute, biometric compliance frameworks fragmenting product roadmaps, and procurement models shifting from capital expenditure to operational subscription structures.
Edge-native AI inference is rewriting the architecture of real-time surveillance systems. NVIDIA Jetson and Ambarella CVflow silicon now embed directly into IP camera housings, processing 30 frames per second of H.265 streams without external compute appliances. Large transportation hubs and critical facility operators are standardizing on these devices to eliminate single points of failure in centralized server rooms.
GDPR Article 9 restrictions on biometric data processing are forcing product segmentation between European and non-European deployments. Vendors must maintain parallel software branches: one with facial recognition modules disabled for EU markets, another with full analytics stacks for jurisdictions without comparable prohibitions. This regulatory divergence inflates engineering overhead and complicates global account management for multinational security teams.
Subscription-based video surveillance as a service is displacing perpetual license models in mid-market commercial real estate. Property management firms now prioritize vendors offering bundled hardware, software, and cloud storage with predictable monthly fees rather than upfront capital commitments. This preference shift is most pronounced in United States multi-site retail and hospitality portfolios, where IT staffing constraints favor fully managed solutions.
Security Camera Software Market Segmentation
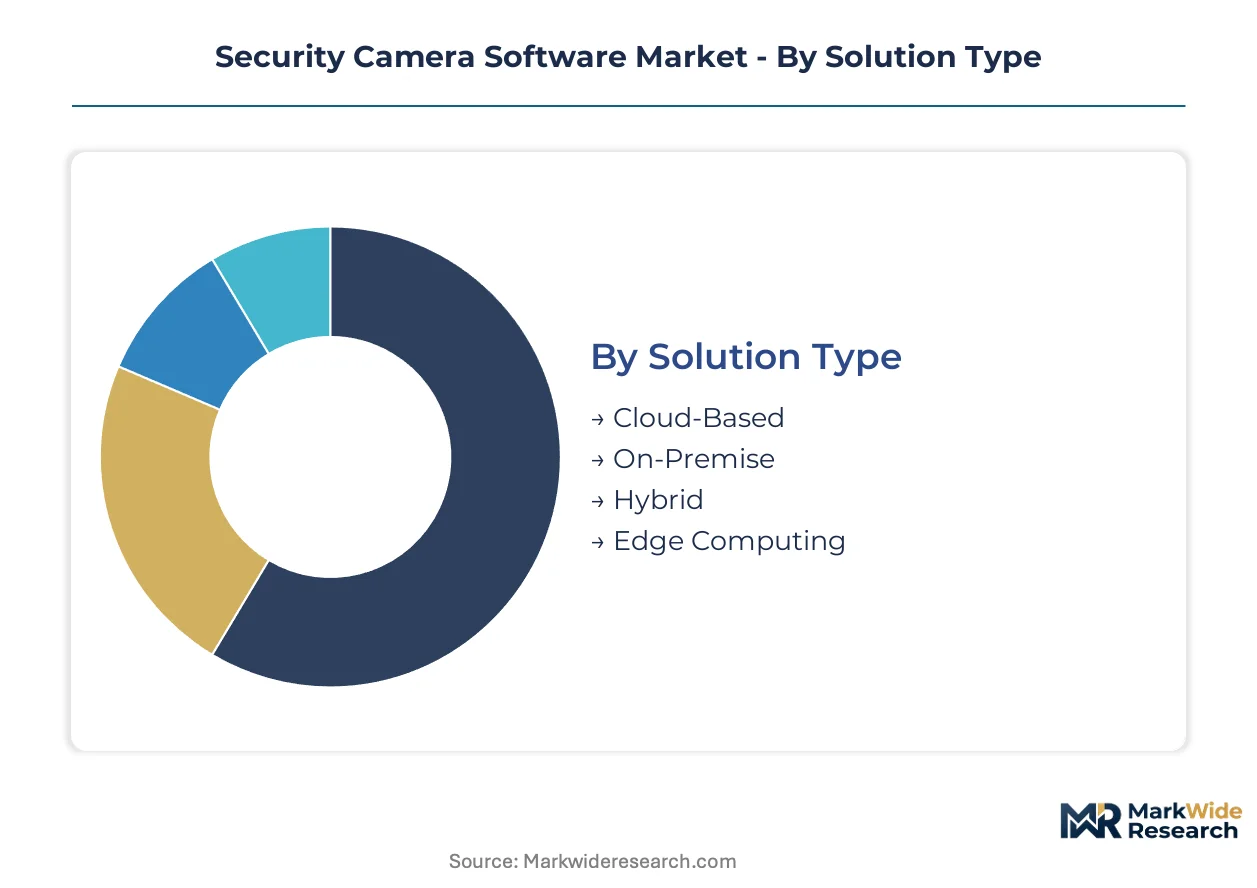
Segmentation in security camera software reflects divergent compliance burdens, infrastructure maturity, and customer technical capabilities. Procurement patterns cluster around deployment complexity and regulatory exposure rather than price alone.
Solution Type:
Certification requirements fragment sharply across this category: cloud deployments face ISO/IEC 27001 audits and SOC 2 attestations, while edge computing solutions trigger CE marking and FCC equipment authorization for on-camera inference silicon.
- Cloud-Based:Centralized video management platforms with subscription billing and automatic firmware distribution. Demand concentrates in United States multi-site retail portfolios where IT staffing constraints favor fully managed infrastructure.
- On-Premise:Dedicated server installations with perpetual licensing and local storage arrays. European critical facilities prefer these configurations to satisfy GDPR data residency mandates and avoid cross-border transfer complications.
- Hybrid:Architectures splitting storage between local NVRs and cloud tiering for archival footage. Airports and logistics hubs deploy these to balance real-time access with long-term retention requirements.
- Edge Computing:On-camera inference engines processing H.265 streams without external compute. NVIDIA Jetson and Ambarella CVflow silicon enable 30fps object classification at the network perimeter.
Leading the category by volume: Cloud-Based. Growing fastest: Edge Computing.
Deployment Model:
Cost tiering separates this category: public cloud offers lowest entry pricing, private cloud commands 3-4x premiums for dedicated infrastructure, while tenant architecture determines scalability limits for channel count expansion.
- Public Cloud:Shared infrastructure with metered bandwidth and storage pricing. Mid-market commercial real estate in United States hospitality sectors favor these for predictable operational expenditure profiles.
- Private Cloud:Isolated compute and storage resources with custom security policies. Government and defense installations mandate these configurations for classified facility monitoring.
- Multi-Tenant:Single platform instance serving multiple organizational units with role-based access separation. Property management firms operating diverse building portfolios standardize on these deployments.
- Single-Tenant:Dedicated software instance per customer with isolated database schemas. Financial services and healthcare providers require these for HIPAA and PCI-DSS audit trails.
Widest deployment: Public Cloud. Steepest expansion trajectory: Private Cloud.
End User:
Application-specific requirements dominate procurement: transportation hubs prioritize sub-100ms latency for real-time alerting, while residential segments trade analytical depth for installation simplicity and mobile app integration.
- Transportation Hubs:Airports, seaports, and rail terminals requiring 99.99% uptime SLAs and integration with access control systems. United States TSA directives and EU aviation security regulations mandate encrypted video retention.
- Enterprises:Corporate campuses and manufacturing facilities with multi-building coverage needs. These deployments emphasize unified command centers and API integration with identity management platforms.
- Retail Stores:Loss prevention and customer flow analytics with POS integration. Franchise operators favor bundled hardware-software subscriptions to minimize capital deployment across distributed locations.
- Residential:Single-family and multi-unit dwellings with cloud-connected cameras and smartphone viewing. DIY installation trends favor battery-powered devices with minimal on-premise infrastructure.
Deepest margin pools: Enterprises. Fastest volume growth: Residential.
Feature Set:
Margin stratification follows analytical sophistication: basic motion detection commands commodity pricing, while intelligent video surveillance with AI-powered classification captures premium licensing tiers and recurring revenue expansion.
- Intelligent Video Surveillance:AI-driven object classification, behavioral analysis, and anomaly detection with automated alerting. These capabilities face EU AI Act conformity assessments when biometric identification is enabled.
- Real-Time Analytics:Live video processing for crowd density, queue length, and perimeter breach detection. Smart city tenders in India under Ministry of Home Affairs mandates specify these requirements.
- Motion Detection:Pixel-change algorithms triggering recording and notification without object classification. Legacy analog-to-IP transition projects preserve these features to minimize retraining costs.
- Remote Access:Browser and mobile application viewing with encrypted streaming protocols. FCC wireless transmission guidelines govern these deployments for municipal and utility sector networks.
Highest revenue concentration: Intelligent Video Surveillance. Expanding most quickly: Real-Time Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for security camera software concentrates in the United States, where federal infrastructure spending and critical facility hardening accelerate procurement cycles. Europe follows with compliance-driven upgrade mandates under biometric regulations. Asia-Pacific growth centers on smart city modernization programs and transportation hub digitization.
United States
Federal infrastructure spending and TSA airport security directives drive enterprise deployments across transportation and government verticals. FCC wireless transmission guidelines clarify standards for municipal and utility sector cloud-connected networks. Dallas-Fort Worth and Atlanta metropolitan clusters anchor demand for multi-site retail and hospitality surveillance platforms with fully managed service models.
Germany
Industrial facility operators prioritize on-premise architectures to satisfy GDPR data residency mandates and avoid cross-border transfer complications. EU AI Act conformity assessments force segmentation of biometric identification features for European market deployments. Munich and Stuttgart manufacturing corridors standardize on unified command centers integrating video with access control and identity management systems.
India
Urban surveillance modernization programs under the Ministry of Home Affairs tender large-scale intelligent video management installations for smart city mandates. BIS certification requirements shape hardware procurement specifications for government security projects. Bangalore and Hyderabad technology clusters concentrate demand for edge-native AI inference in transportation and logistics security applications.
United Kingdom
Corporate campus expansions and financial services compliance requirements sustain demand for single-tenant private cloud deployments with isolated database schemas. GDPR Article 9 restrictions on biometric data processing influence software feature configurations for European accounts. London's Canary Wharf and Square Mile districts anchor premium-tier installations commanding unified physical security suite licensing.
Japan
Transportation hub operators require 99.99% uptime SLAs with sub-100ms latency for real-time alerting in rail terminal and seaport environments. METI industrial security guidelines influence procurement standards for critical infrastructure monitoring systems. Tokyo-Osaka corridor deployments emphasize API integration with legacy building management platforms and minimal-disruption retrofit installations.
Security Camera Software Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors balance edge silicon integration with cloud service expansion. The vendor base separates into three strategic tiers: unified platform providers anchoring enterprise accounts, open-architecture specialists enabling camera-to-cloud flexibility, and vertically integrated subscription vendors minimizing on-premise infrastructure requirements. M&A activity concentrates on analytics engine acquisitions and regional system integrator consolidation. Technology licensing partnerships between camera manufacturers and inference silicon suppliers accelerate feature roadmap convergence.
Within the unified platform tier, Genetec exemplifies the enterprise-anchoring archetype through its security federation architecture. Axis Communications occupies a position representing open-architecture camera-to-cloud integration specialists. Verkada sits within the vertically integrated subscription model, exemplifying hardware-software bundling with minimal on-premise footprint. These three patterns—platform unification, architectural openness, and vertical integration—capture the dominant competitive positioning vectors in current procurement cycles.
| Leading Market Players |
|---|
| Genetec |
| Avigilon |
| Axis Communications |
| Verkada |
| Milestone |
| Lumana |
| Rhombus |
| Eagle Eye Networks |
| Hanwha Vision |
| Others |
Pricing and Supply Chain Analysis
GPU-accelerated inference silicon migration is compressing per-channel analytics economics while concentrating procurement leverage among NVIDIA and AMD fabrication partners. This technology shift simultaneously collapses legacy CPU-bound pricing tiers and tightens supply access for high-density surveillance deployments.
Pricing Analysis
Volume concentrates in cloud-based SaaS subscriptions with predictable monthly fees, while margin pools deepen in edge-native AI tiers with embedded inference engines. Price differentiation rests on certification grade—ISO/IEC 27001 and SOC 2 attestations command 3-4x premiums over uncertified alternatives—and vertical integration depth. Cost compression in mid-market commercial real estate segments is intensifying because property management firms prioritize fully managed solutions over capital-intensive on-premise builds. Franchise operators show highest price sensitivity; government and defense installations show least.
Supply Chain Analysis
CE marking and FCC equipment authorization gate access for on-camera inference silicon, filtering out uncertified component vendors. Fabrication concentrates in Taiwan, South Korea, and the United States for GPU and edge AI chipsets. Raw material dependencies include advanced semiconductor substrates, H.265 codec licensing, and thermal management components. Single-source vulnerability runs through NVIDIA Jetson and Ambarella CVflow silicon concentration. Distribution runs through authorized camera manufacturer channels and regional system integrators with ONVIF certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU fabrication capacity constraints prop pricing power for certified edge AI vendors while limiting supply access for mid-tier competitors. This supply-constrained dynamic favors incumbents with established foundry relationships.
For Market Incumbents: Lock in multi-year foundry allocations for Jetson and CVflow silicon to secure channel supply against fabless entrant competition. Prioritize ISO/IEC 27001 certification investment to sustain premium pricing in European GDPR-mandated deployments. Defensive consolidation through analytics engine acquisitions closes feature gaps with cloud-native challengers. For New Entrants and Emerging Players: Edge-native AI inference with sub-100ms latency specifications offers a technology-first wedge into India smart city tenders and United States transportation hub digitization programs. White-space targets include mid-market hybrid deployments balancing local NVR storage with cloud archival tiering. A channel partnership route through regional system integrators accelerates ONVIF-compliant integration without direct camera manufacturing investment. For Investors and Strategic Acquirers: Exit pathways concentrate in platform unification acquisitions by unified security suite vendors seeking vertical feature expansion. Long-term viability favors vendors with captive edge silicon roadmaps and recurring SaaS revenue concentration above perpetual license exposure. The signal to watch is EU AI Act enforcement intensity triggering compliance-driven upgrade cycles for biometric identification installations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Integration | Embedding NVIDIA Jetson inference engines into camera housings eliminates centralized server failure points for transportation hubs. |
| Compliance Certification Investment | ISO/IEC 27001 and EU AI Act conformity assessments unlock premium pricing in European critical facility markets. |
| Hybrid Cloud-Edge Architecture Launch | Splitting storage between local NVRs and cloud tiers satisfies airport retention requirements without latency penalties. |
| Vertical Integration into Camera Manufacturing | In-house production of thermal-efficient edge devices aligns hardware refresh cycles with EU Green Deal energy directives. |
| Strategic Partnership with System Integrators | ONVIF-certified channel partnerships accelerate unified command center deployments without custom middleware development. |
Research Methodology
Independent corroboration across security technology procurement officers, cloud platform engineers, and regional system integrators underwrites the qualitative findings. Primary fieldwork incorporated CTOs at multi-site retail operators, government facility security directors, and channel partners with ONVIF certification expertise. Secondary validation drew from SEC filings of publicly traded surveillance vendors, FCC equipment authorization databases, and EU AI Act implementation guidance documents. Bottom-up channel count estimates triangulated against top-down market value projections.
Comparable-period anchoring to historical deployment cycles informed the projection horizon across the analysis window. Segmentation dimensions modeled include solution type, deployment model, end-user vertical, and feature set complexity. CAGRs were derived from installation growth rates weighted by average revenue per channel. Industry-specific inputs incorporated GPU silicon lead times, GDPR data retention policy variance, and smart city tender pipeline visibility from Ministry of Home Affairs documentation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden GPU supply disruption or accelerated EU AI Act enforcement timelines. A model refresh is warranted upon material change in NVIDIA foundry allocation policies or biometric regulation fragmentation across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Rugged Thermal Cameras Market