
 Privacy Filters Market | 2026-2036
Privacy Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Privacy Filters Market Analytics
A shortage of optical film engineers is reorganizing how manufacturers scale micro-louver production capacity. 3M Company leverages captive polymer science expertise to sustain its dominance in premium micro-louver formulations. Fellowes Brands anchors North American distribution through office supply channel control. ZAGG Inc. competes in mobile-first privacy accessories with specialized screen protector integration.
Privacy filters are thin optical films engineered with micro-louver technology that restricts viewing angles to approximately 60 degrees, constructed from PET substrates with light-absorbing dyes laminated between precision-etched layers. The primary purpose is preventing visual eavesdropping on sensitive displays in open-plan offices, public transit, and shared workspaces. Screen Privacy Filters occupy the largest margin pool due to enterprise volume procurement and replacement cycles tied to monitor refresh rates. Laptop Privacy Screens represent the fastest-growing application segment as hybrid work policies normalize portable endpoint protection. Webcam Covers remain a mature, low-margin category with commodity competition from unbranded imports.
FDA, SEC, and HIPAA frameworks in the United States elevate privacy filter demand in healthcare and financial services by treating visual data exposure as a reportable security incident. EMA documentation standards and GDPR Article 32 technical measures across Europe compel pharmaceutical and data-processing employers to implement physical display safeguards. Stakeholders must monitor whether NHTSA and FAA extend visual security requirements into connected vehicle and avionics display certifications.
Market Dynamics
Enterprise IT refresh cycles are compressing privacy filter replacement timelines as hybrid work policies institutionalize visual data protection as a standard endpoint security layer rather than an optional accessory.
Growth Catalysts
- EU AI Act enforcement:GDPR Article 32 technical measures now explicitly encompass display-level safeguards in European pharmaceutical and financial workplaces, mandating physical screen protection for AI system operators handling sensitive training data.
- Healthcare endpoint hardening:HIPAA Security Rule audits in the United States treat shoulder-surfing incidents as reportable breaches, driving hospital procurement teams to standardize privacy filters across nursing stations and mobile diagnostic carts.
- Micro-louver precision gains:Advances in PET substrate etching now enable 30-degree viewing angle restriction without luminance degradation, satisfying enterprise buyers who previously rejected filters for color-critical workflows.
Market Restraints
- Optical film engineer scarcity:The specialized skill set combining polymer chemistry and precision optics concentrates in Japan and Germany, constraining how quickly manufacturers can replicate 3M's captive formulation expertise.
- Commodity webcam cover imports:Unbranded Asian suppliers flood retail channels with sub-dollar plastic shutters, compressing margins and diverting procurement attention from premium integrated solutions.
- Touchscreen compatibility friction:Thick multi-layer filters degrade capacitive response on modern 2-in-1 laptops, forcing buyers to choose between privacy and functionality in convertible device deployments.
Strategic Opportunities
- Avionics display certification:FAA and EASA are evaluating visual security requirements for cockpit and cabin crew tablets, opening a specification-driven segment with decade-long replacement cycles.
- India BIS standards alignment:The Bureau of Indian Standards is drafting display privacy guidelines for government and banking sectors, creating first-mover advantages for suppliers establishing local technical partnerships.
- Blue-light filtering convergence:Integration of circadian rhythm management with privacy functionality addresses wellness procurement mandates in Nordic and German enterprise HR policies.
Industry Challenges
- Micro-louver production scale-up:Capital equipment for precision etching lines requires 18-24 month lead times, mismatching capacity expansion with sudden enterprise tender volumes.
- Cross-jurisdictional certification stacking:Filters sold into medical devices must simultaneously satisfy FDA 510(k), MDR CE marking, and ISO 13485 quality systems, extending time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Privacy Filters Market |
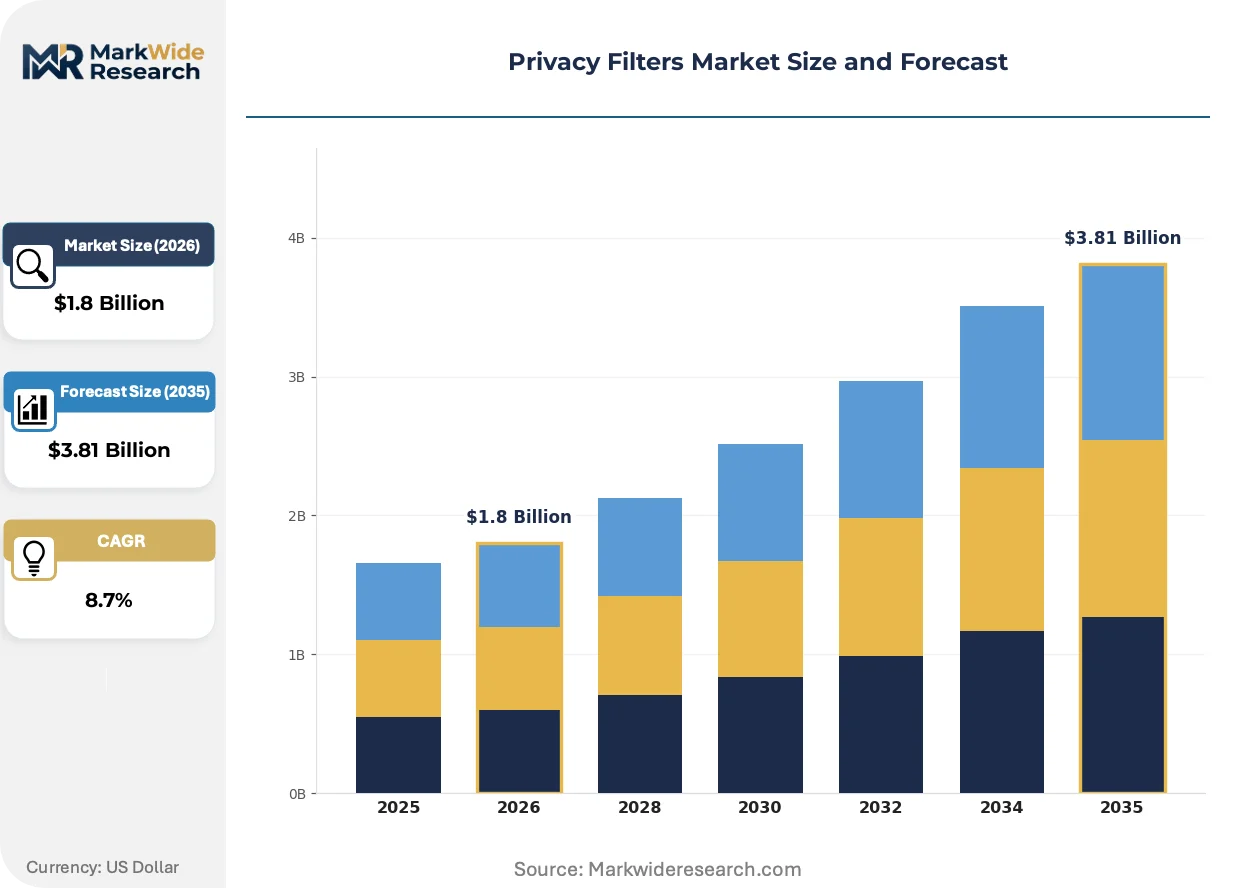
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screen Privacy Filters, Webcam Covers, Laptop Privacy Screens, Anti-Glare Filters Application: Corporate Settings, Educational Institutions, Public Spaces, Home Use End User: Individuals, Small Businesses, Enterprises, Government Agencies Distribution Channel: Online Retail, Offline Retail, Direct Sales, B2B Sales |
| Companies Covered | 3M Company, Targus Inc., Kensington Computer Products Group, HP Inc., Dell Technologies Inc., Fellowes Brands, ZAGG Inc., Lenovo Group Limited, Tech Armor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Privacy Filters Market Evolving Landscape
Privacy filter technology is bifurcating between premium integrated solutions and commoditized aftermarket accessories, with the innovation frontier concentrating on seamless user experience rather than incremental optical performance gains.
Switchable privacy technology using liquid crystal layers is decomposing the traditional static filter market by enabling on-demand viewing angle control through software or physical toggle. Enterprise buyers in legal and consulting verticals are piloting these solutions for conference room and travel scenarios where collaborative screen sharing alternates with confidential work. The technology is decomposing procurement decisions into separate hardware and software budget lines, complicating vendor pricing strategies.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom now explicitly cite visual data exposure in open-plan offices as a technical safeguard failure under Article 32. Pharmaceutical employers with EMA documentation obligations are responding by writing privacy filter specifications into workstation procurement RFPs rather than treating them as aftermarket accessories. This regulatory interpretation is spreading to German and Dutch financial supervisors, compressing compliance timelines for multinational employers.
Enterprise purchasing teams are consolidating endpoint security procurement under CISO authority rather than facilities or office supply managers, elevating privacy filters to strategic vendor relationships with multi-year frameworks. This centralization displaces the fragmented purchasing patterns that previously favored retail channel convenience over technical specification compliance. The shift is most visible in United States healthcare systems and European banking groups undergoing SOC 2 and ISO 27001 certification renewals.
Privacy Filters Market Segmentation
Privacy filter procurement channels diverge sharply between enterprise volume contracts and individual retail purchases. Segmentation reveals how micro-louver technology flows through distinct commercial pathways governed by compliance mandates versus price sensitivity.
Product Type:
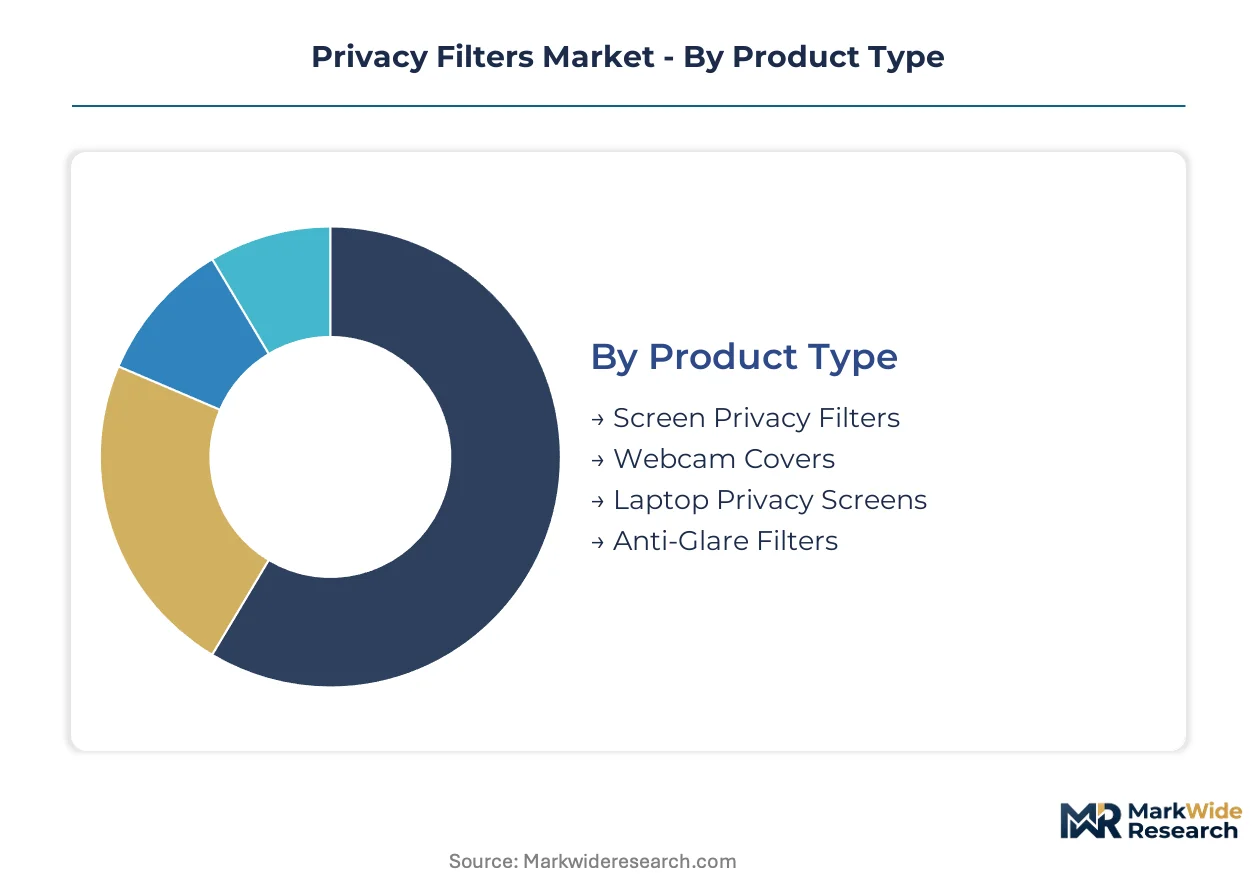
Channel mix varies dramatically: enterprise IT buyers source Screen Privacy Filters and Laptop Privacy Screens through B2B distributors with compliance documentation, while Webcam Covers and Anti-Glare Filters dominate retail and online channels where price transparency rules.
- Screen Privacy Filters:Micro-louver optical films laminated on PET substrates restrict viewing angles to 60 degrees. Hospital procurement teams in the United States specify these under HIPAA Security Rule audits that treat shoulder-surfing as a reportable breach. By volume, Screen Privacy Filters leads. By growth pace, Laptop Privacy Screens is ahead.
- Laptop Privacy Screens:Thinner formulations address portable endpoint protection for hybrid workforces. European pharmaceutical employers with EMA documentation obligations now write specifications into workstation RFPs rather than treating these as aftermarket accessories. Demand concentrates in consulting and legal verticals where travel security alternates with collaborative screen sharing.
- Webcam Covers:Plastic or metal shutters addressing camera-based surveillance concerns. Unbranded Asian suppliers flood retail channels with sub-dollar units, compressing margins and diverting procurement attention from premium integrated solutions.
- Anti-Glare Filters:Matte surface treatments reducing ambient reflection without micro-louver privacy functionality. Popular in home office settings where eye comfort outweighs data security requirements.
Margin concentration follows the compliance burden: products requiring regulatory documentation command pricing premiums through direct sales channels.
Application:
Cost tier segmentation separates specification-driven procurement from discretionary purchasing, with compliance penalties creating irreversible demand at the premium end.
- Corporate Settings:Open-plan offices and shared workspaces mandate visual data protection. GDPR Article 32 enforcement by CNIL and ICO now explicitly cites display-level safeguards as technical measures, compelling standardization across European banking and pharmaceutical employers.
- Educational Institutions:University libraries and testing centers deploy privacy filters to prevent examination cheating and protect student records. Procurement runs through educational cooperative purchasing agreements with extended payment terms.
- Public Spaces:Airport lounges, co-working facilities, and transit hubs present high shoulder-surfing risk. Demand here is fragmented across facilities management budgets with limited technical specification oversight.
- Home Use:Individual consumers prioritize blue-light reduction and anti-glare properties over strict privacy angles. Online retail channels dominate with price-transparent comparison shopping.
Enterprise applications generate the steepest expansion trajectory as hybrid work policies institutionalize visual data protection as standard endpoint security.
End User:
Customer type determines contract structure: annual framework agreements with Enterprises and Government Agencies versus transactional purchases by Individuals and Small Businesses.
- Individuals:Price-sensitive buyers purchasing single units through Amazon and electronics retailers. Replacement cycles tie to device ownership rather than security policy.
- Small Businesses:Owner-operated procurement without dedicated IT security staff. These buyers rely on managed service provider recommendations and often defer privacy investments until after security incidents.
- Enterprises:CISO-led consolidation of endpoint security procurement under multi-year frameworks. United States healthcare systems undergoing SOC 2 certification renewals exemplify this centralized purchasing pattern.
- Government Agencies:Specification-driven procurement with mandatory domestic content requirements and extended compliance documentation. FAA and NHTSA are evaluating visual security requirements for connected vehicle and avionics displays.
Procurement centralization is accelerating fastest among Enterprises, displacing fragmented purchasing that previously favored retail channel convenience.
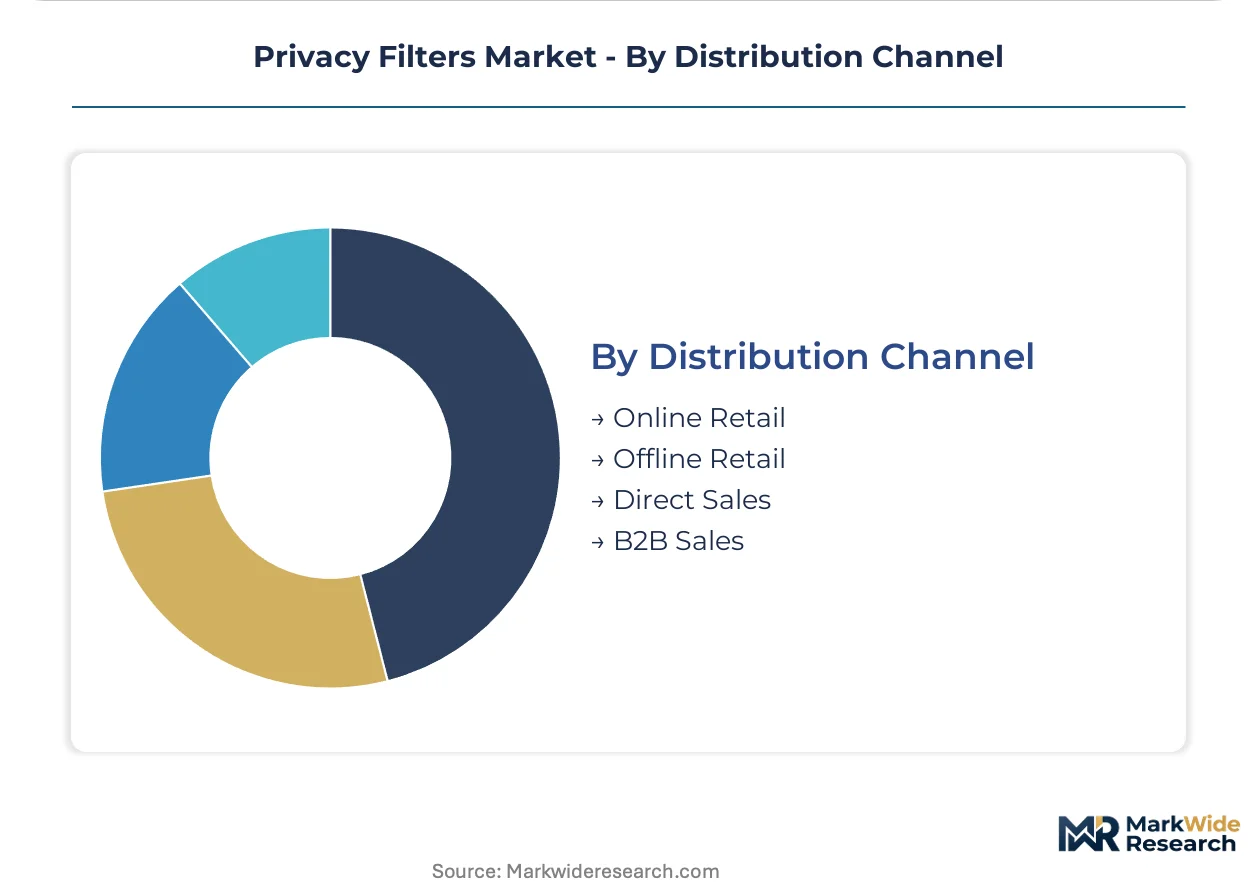
Distribution Channel:
Supply concentration in micro-louver manufacturing shapes channel economics, with premium formulations captive to specialized producers while commodity products flow through mass retail.
- Online Retail:Amazon, Newegg, and direct-to-consumer sites serve Individuals and price-comparison buyers. Webcam Covers and Anti-Glare Filters dominate this channel with minimal technical support.
- Offline Retail:Staples, Best Buy, and office supply stores stock immediate-need purchases. Fellowes Brands anchors North American presence through this channel control.
- Direct Sales:Manufacturer field representatives serve Enterprise and Government accounts with compliance documentation and custom sizing. 3M Company leverages captive polymer science expertise through this high-touch model.
- B2B Sales:Distributors like Ingram Micro and TD Synnex aggregate procurement for Small Businesses and mid-market Enterprises without direct manufacturer relationships.
By transaction volume, Online Retail leads. By revenue per unit, Direct Sales is climbing fastest as enterprise compliance mandates elevate specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and SEC frameworks in the United States elevate privacy filter procurement in healthcare and financial services, while GDPR Article 32 enforcement across Europe compels display-level safeguards. Enterprise IT refresh cycles and hybrid work policies are compressing replacement timelines in both regions.
United States
HIPAA Security Rule audits treat shoulder-surfing as reportable breaches, driving hospital procurement teams to standardize privacy filters across nursing stations and mobile diagnostic carts. The SEC cybersecurity disclosure rules elevate endpoint security investments in financial services. Boston and New York City clusters concentrate consulting and legal verticals where travel security alternates with collaborative screen sharing.
Germany
EMA documentation standards and GDPR Article 32 technical measures compel pharmaceutical employers to implement physical display safeguards. The KBA and federal financial supervisors are extending visual security interpretations to connected vehicle displays. Bavaria and Baden-Württemberg host automotive and precision engineering clusters where micro-louver technology integrates into cockpit certification pipelines.
United Kingdom
ICO enforcement actions explicitly cite visual data exposure in open-plan offices as technical safeguard failures under GDPR Article 32. London's financial services concentration drives specification-driven procurement through CISO-led frameworks. The Southeast corridor anchors enterprise IT distribution channels serving multinational banking groups undergoing ISO 27001 certification renewals.
Japan
METI industrial standards and PMDA quality systems shape medical device display requirements, creating specification-driven demand with extended compliance timelines. Tokyo and Osaka metropolitan areas concentrate electronics manufacturing and corporate headquarters procurement. The Chubu region around Nagoya hosts precision optics and polymer chemistry capabilities supporting micro-louver substrate etching.
India
BIS is drafting display privacy guidelines for government and banking sectors, creating first-mover advantages for suppliers establishing local technical partnerships. RBI cybersecurity circulars elevate endpoint protection priorities across financial institutions. Maharashtra and Karnataka host IT services clusters where hybrid work policies institutionalize visual data protection as standard security layers.
Privacy Filters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with formulation expertise and distribution scale determining competitive position. Three archetypes populate this structure: captive polymer science specialists with in-house substrate capabilities, office supply channel controllers with North American retail presence, and mobile-first accessory integrators targeting portable endpoint protection. Competitive moves concentrate on strategic partnerships with enterprise IT distributors and geographic expansion through local technical compliance partnerships.
Within the integrated formulation tier, 3M Company exemplifies captive polymer science capabilities that sustain premium micro-louver positioning. Fellowes Brands anchors North American presence through office supply channel control, while ZAGG Inc. occupies a position in mobile-first privacy accessories with specialized screen protector integration. These three represent distinct strategic vectors: upstream materials control, retail distribution scale, and portable endpoint specialization.
| Leading Market Players |
|---|
| 3M Company |
| Targus Inc. |
| Kensington Computer Products Group |
| HP Inc. |
| Dell Technologies Inc. |
| Fellowes Brands |
| ZAGG Inc. |
| Lenovo Group Limited |
| Tech Armor |
| Others |
Value Network & Pricing Analysis
FDA 510(k) and MDR CE marking pathways gate both supplier qualification and price stratification in medical-grade privacy filter segments, compressing margins for uncertified commodity producers while amplifying premiums for compliant formulation specialists. Buyers in pharmaceutical and healthcare verticals face dual constraints: technical documentation requirements elevate procurement costs, yet regulatory penalties for non-compliance eliminate price-driven substitution toward uncertified alternatives.
Pricing Analysis
Geographic price spreads separate Japanese and German micro-louver formulations from commodity Asian imports by factors exceeding three-to-one in enterprise tenders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with HIPAA-audited hospital systems paying premiums for documented supply chain traceability. Cost compression in economy tiers intensifies because unbranded webcam cover suppliers flood retail channels with sub-dollar units. Small businesses and individual consumers exhibit highest price sensitivity, while CISO-led enterprise procurement prioritizes specification compliance over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes inject volatility into PET substrate and light-absorbing dye inbound costs for non-integrated manufacturers. Precision etching equipment and optical-grade polymer chemistry concentrate in Japan, Germany, and select United States facilities, drawing from specialized engineering talent pools in Nagoya and Bavaria. Formulation expertise rests on captive polymer science capabilities that 3M and comparable specialists maintain in-house. Single-source vulnerability concentrates in precision etching line equipment where 18-24 month lead times mismatch capacity expansion with tender volumes. Distribution runs through bifurcated pathways: direct sales with compliance documentation for enterprise and government accounts, mass retail for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards captive optical film engineering capabilities that resist rapid replication, with polymer chemistry expertise concentrated in aging specialist workforces across Japan and Germany. Incumbents must compound advantage before talent scarcity erodes formulation differentiation.
For Market Incumbents: Compound formulation expertise through selective backward integration into PET substrate production and precision etching equipment partnerships in Japan or Germany. Switchable privacy technology threatens static filter margins; pilot liquid crystal layer integration with enterprise software vendors before consultancies standardize on-demand specifications. Certification investment in FAA and EASA avionics pathways locks in decade-long replacement cycles against commodity encroachment. For New Entrants and Emerging Players: Post-sales technical support and custom sizing services represent gaps where incumbents under-serve mid-market enterprises lacking dedicated IT security staff. India BIS standardization and RBI cybersecurity circulars create the most penetrable regulatory window for local technical partnerships. Pursue white-label manufacturing for domestic Indian banking and government tenders before multinational suppliers establish compliance documentation. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by mandating display-level safeguards for AI system operators, extending addressable market beyond traditional endpoint security. Five-to-ten year viability hinges on formulation capabilities rather than distribution scale. Target acquisition archetype: mid-tier optical film specialists with captive polymer science and existing FDA or MDR documentation. Monitor FAA and EASA visual security rulemaking as inflection signal for avionics specification premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Substrate Production | Captive polymer science capabilities insulate margin compression from commodity resin volatility. |
| Liquid Crystal Layer Partnership Development | Software-toggle switchable privacy decomposes procurement into recurring license revenue streams. |
| FAA/EASA Avionics Certification Investment | Cockpit display specifications command decade-long replacement cycles with minimal price competition. |
| India BIS Technical Partnership Establishment | First-mover positioning in government and banking procurement before multinational compliance documentation arrives. |
| Blue-Light Filtering Convergence R&D | Nordic and German enterprise HR wellness mandates create bundling premium for circadian rhythm integration. |
Research Methodology
Operator-level perspectives from optical film engineers, enterprise IT procurement managers, hospital biomedical equipment committees, and CISO-led security frameworks anchored the qualitative base. These primary insights combined with secondary validation from FDA 510(k) filings, EMA submission documentation, BIS draft standard publications, and SEC cybersecurity disclosure filings. Bottom-up demand modeling across hospital system refresh cycles, pharmaceutical EMA documentation obligations, and hybrid work policy institutionalization triangulated against top-down macro endpoint security spending patterns.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement intensities and micro-louver production scale-up scenarios. Segmentation dimensions spanned product type, application vertical, end-user procurement authority, and distribution channel structure across the analysis window. CAGRs derived from fitted growth curves incorporating enterprise IT refresh cycle compression, GDPR Article 32 interpretation expansion, and optical film engineer supply constraints. Industry-specific inputs included HIPAA audit frequency trends and FAA visual security rulemaking progression.
Forecasts assume regulatory continuity in FDA, EMA, GDPR, and BIS regimes; material policy shifts would require re-modeling. Specific risks include accelerated EU AI Act enforcement timelines, NHTSA extension of visual security into connected vehicle mandates, and optical film engineer retirement waves constraining production scale-up. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market