
 Middle East and Africa Surveillance Analog Camera Market | 2026-2036
Middle East and Africa Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surveillance Analog Camera Market Insights
CE marking under the EU's Radio Equipment Directive is reorganizing supplier eligibility for Middle East and Africa markets that import heavily from European manufacturers. Bosch Sicherheitssysteme GmbH leverages its German engineering base to sustain certification advantages across Gulf markets. Hanwha Vision anchors its regional position through manufacturing scale in Korea that feeds distribution networks in Dubai and Riyadh. Dahua Technology competes on cost-optimized dome and bullet portfolios tailored to African price sensitivity.
Surveillance analog cameras capture video through charge-coupled device or complementary metal-oxide-semiconductor sensors, transmitting signals via coaxial cable without digital encoding, typically operating at 720p to 1080p resolution with infrared cut filters for low-light performance. Bullet and dome units dominate product type volumes due to their proven reliability in dusty Middle Eastern climates and straightforward installation protocols. Outdoor installation types command structural priority across transportation and government end users where perimeter monitoring requirements resist full IP migration. Wired connectivity persists as the default architecture in African markets where wireless bandwidth remains constrained and power stability fluctuates.
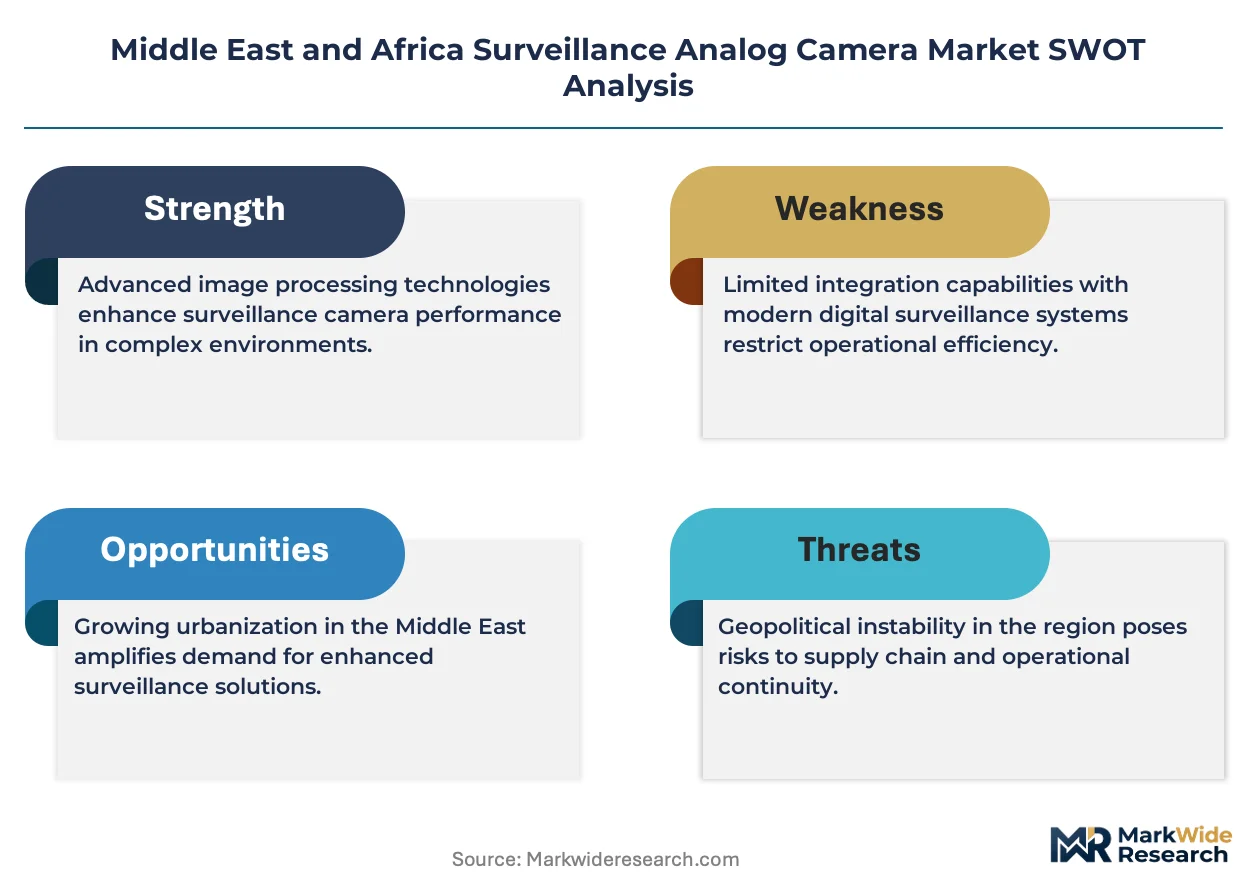
Saudi Arabia's SFDA and the UAE's MOHAP enforce cybersecurity and data protection standards that analog systems partially circumvent through air-gapped coaxial infrastructure, preserving their role in sensitive facility deployments. South Africa's national regulator applies SABS standards that gate product entry and favor established suppliers with local testing relationships. Stakeholders must weigh hybrid connectivity roadmaps against the total cost of coaxial infrastructure replacement as Gulf states accelerate smart city digitization mandates.
Market Dynamics
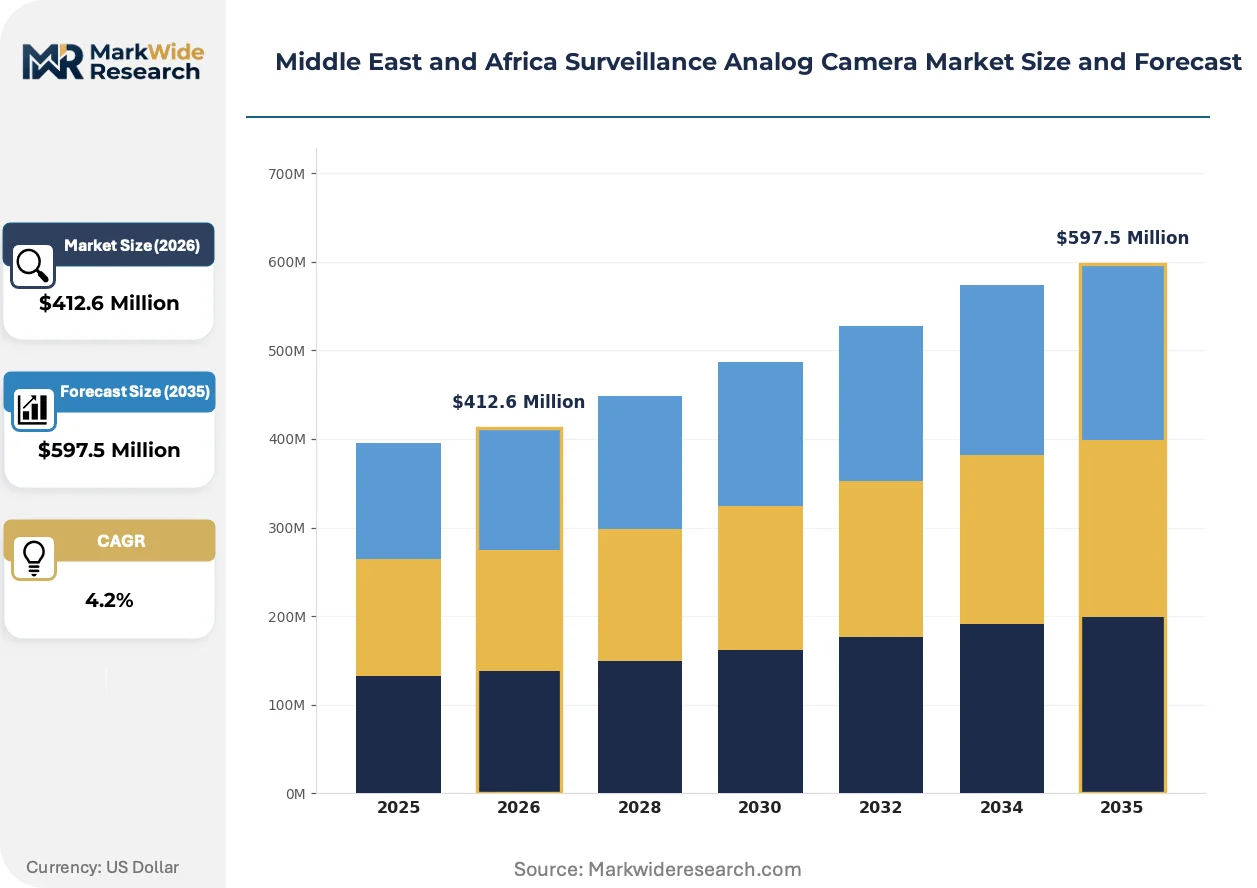
The tension between Gulf states' smart city digitization mandates and the installed base of coaxial infrastructure defines competitive positioning across the Middle East and Africa surveillance analog camera market. System integrators must navigate hybrid upgrade roadmaps while preserving analog reliability in security-critical deployments.
Growth Catalysts
- SFDA Cybersecurity Framework:Saudi Arabia's air-gap compliance requirements for sensitive facilities sustain analog procurement where digital encoding creates vulnerability exposure.
- Border Perimeter Programs:UAE and Saudi coastal and desert surveillance networks favor wired bullet cameras for electromagnetic interference resistance in extreme climates.
- African Power Instability:Nigeria and Kenya's grid volatility preserves demand for coaxial-powered units over PoE-dependent IP alternatives requiring conditioned electrical infrastructure.
Market Restraints
- Copper Cable Cost Volatility:Fluctuating raw material prices for RG-59 and RG-6 coaxial cable compress margins on large-scale government tenders across Gulf Cooperation Council states.
- Korean Manufacturing Concentration:Sensor module supply chains cluster around Seoul-Incheon manufacturing corridors, creating single-geography exposure for regional distributors.
- Resolution Ceiling:1080p maximum output limits analog competitiveness against 4K IP alternatives in UAE retail and banking verticals where facial recognition accuracy requirements tighten.
Strategic Opportunities
- Ethiopian Infrastructure Buildout:Addis Ababa's transportation hub expansion and Chinese-financed railway corridors create greenfield analog deployment potential before IP infrastructure matures.
- Hybrid Encoder Convergence:Analog-to-IP bridge devices enable coaxial cable reuse while delivering H.265 streaming, extending equipment lifecycle in Saudi educational facility upgrades.
- SABS Certification Pathways:South Africa's standards body offers first-mover advantage for suppliers establishing local testing relationships ahead of regional competitors.
Industry Challenges
- Coaxial Splicing Expertise Gap:Gulf installation contractors face shortages of technicians proficient in BNC connector termination and impedance matching for long-distance outdoor runs.
- Legacy Matrix Switch Integration:Dubai's commercial real estate sector struggles to synchronize new DVR deployments with existing multiplexed coaxial architectures without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surveillance Analog Camera Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $597.5 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet, Dome, PTZ, Cooled Installation Type: Indoor, Outdoor, Wall-mounted, Ceiling-mounted End User: Retail, Transportation, Healthcare, Government Connectivity: Wired, Wireless, IP-enabled, Hybrid |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Bosch Sicherheitssysteme GmbH, Hanwha Vision, Teledyne FLIR LLC, ACTi Corporation, Dahua Technology, Axis Communications AB, Honeywell Security Group, Panasonic Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surveillance Analog Camera Market Trends and Innovations
Sensor architecture evolution and regulatory compliance pathways are compressing the analog-to-digital transition timeline across Middle Eastern and African security deployments. Vendors must balance backward compatibility with performance tier advancement.
Starlight low-light CMOS sensors with 0.001 lux sensitivity are supplanting traditional CCD arrays in Saudi perimeter applications. Ministry of Interior procurement specifications now prioritize color night vision capability over infrared-cut filter switching. This sensor migration enables longer cable runs without signal degradation, preserving coaxial infrastructure investment while matching IP camera low-light benchmarks.
MOHAP's critical infrastructure cybersecurity mandates in the UAE create regulatory friction for full IP migration in healthcare and energy facilities. The policy requires network segmentation documentation that analog air-gapped systems inherently satisfy. Dubai's hospital consortiums increasingly specify hybrid architectures with analog front-ends and localized encoding to meet compliance without exposure to ransomware vectors.
Consolidated procurement through Saudi Arabia's National Unified Procurement Company is concentrating buyer power and compressing vendor margins. System integrators in Riyadh and Jeddah now compete on total cost of ownership rather than equipment differentiation. This behavioral shift favors suppliers with regional logistics hubs capable of 48-hour replacement part availability across the Kingdom's vast geography.
Middle East and Africa Surveillance Analog Camera Market Segmentation
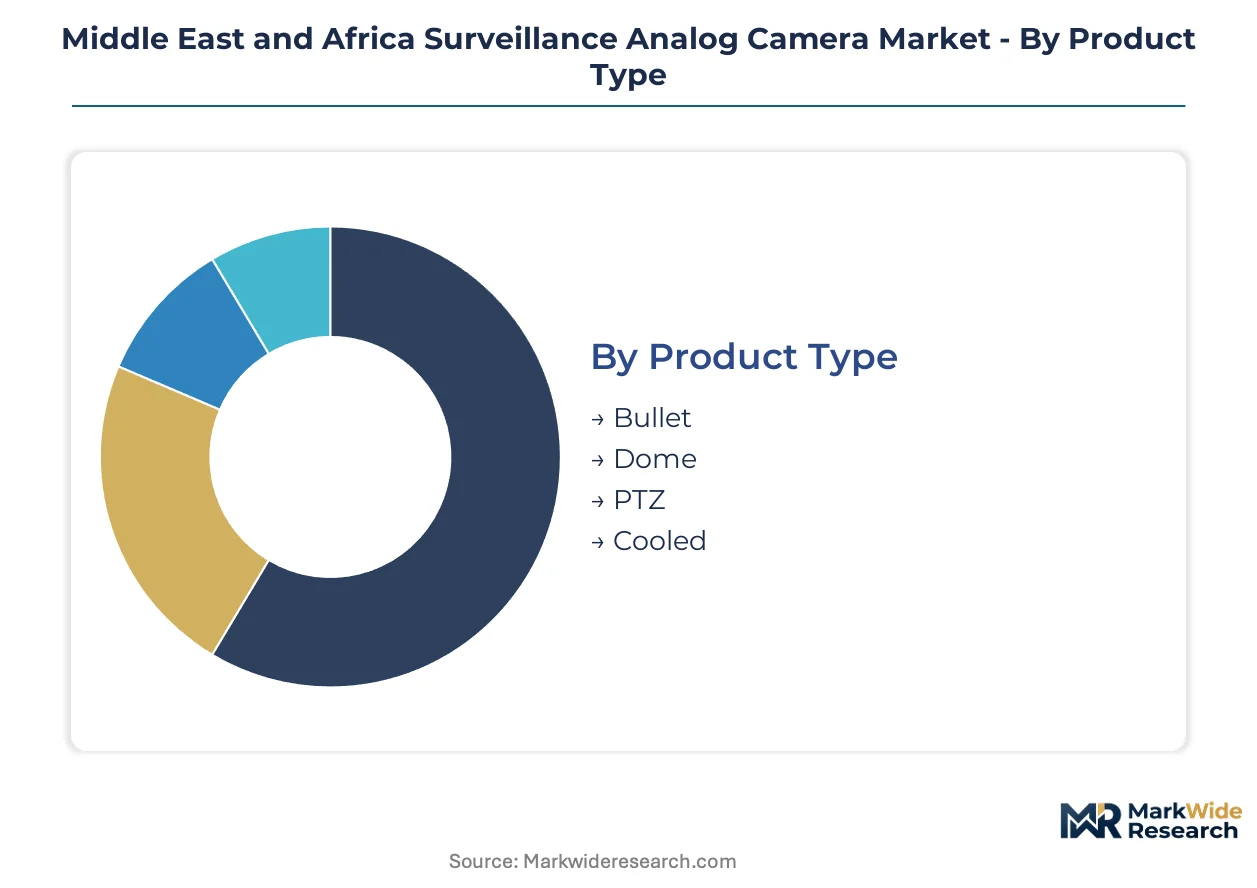
Segmentation across the Middle East and Africa surveillance analog camera market reveals how procurement channels diverge between Gulf government tenders and African commercial distribution. Each dimension carries distinct margin structures and technical requirements that reshape supplier positioning.
Product Type:
Channel flow splits sharply: dome and bullet units move through systems integrators serving Saudi and UAE government contracts, while PTZ and cooled variants concentrate in specialized security distributors for African mining and energy clients.
- Bullet:Cylindrical housings with fixed or varifocal lenses deliver dust-sealed operation rated at IP66 and above. Saudi border security programs and UAE coastal surveillance networks specify these units for electromagnetic interference resistance in desert and maritime environments where coaxial cable runs exceed 500 meters.
- Dome:Vandal-resistant hemispherical enclosures with three-axis gimbal positioning suit indoor retail and banking deployments across Dubai and Riyadh. MOHAP healthcare facility mandates favor dome form factors for patient privacy zones where camera visibility must remain discreet.
- PTZ:Motorized pan-tilt-zoom mechanisms enable operator-controlled coverage of large perimeters. Nigerian oil facility operators specify these for flare stack and pipeline monitoring.
- Cooled:Thermoelectrically stabilized sensor housings maintain image clarity across extreme temperature swings. South African platinum mining operations deploy these for subterranean ventilation shaft monitoring.
By volume, bullet configurations lead across government procurement. By growth pace, cooled variants are gaining share fastest in African extractive industries.
Installation Type:
Cost tier stratification separates premium outdoor-rated enclosures from economy indoor mounts, with wall and ceiling variants occupying distinct contractor skill bands.
- Indoor:Lightweight polycarbonate housings without IP sealing reduce unit cost for climate-controlled environments. Kenyan banking halls and UAE hospital corridors specify these for lobby and corridor coverage where environmental stress remains minimal.
- Outdoor:Die-cast aluminum chassis with gasket-sealed cable entry points withstand sand infiltration and thermal cycling. Saudi Aramco facility standards mandate these for above-ground tank farm perimeter coverage.
- Wall-mounted:Cantilever bracket assemblies with conduit integration simplify retrofit installation in existing structures. Ethiopian railway station projects favor these for platform edge surveillance.
- Ceiling-mounted:Recessed or surface pendant configurations preserve sightlines in crowded retail environments. South African supermarket chains specify these for aisle loss prevention.
Outdoor installations command the highest average selling prices. Ceiling-mounted units are climbing the fastest as Gulf retail modernization accelerates.
End User:
Application requirements reshape specification priorities: transportation demands vibration resistance, healthcare prioritizes air-gapped security, retail focuses on cost per channel.
- Retail:Multi-channel DVR architectures with synchronized timestamping support loss prevention investigations. Dubai mall operators and Johannesburg shopping centers deploy dome-heavy configurations at checkout and entry points.
- Transportation:Ruggedized housings with anti-corrosion coating survive exhaust exposure and thermal shock. Riyadh metro construction and Addis Ababa light rail projects specify bullet cameras for tunnel and platform coverage.
- Healthcare:SFDA and MOHAP cybersecurity frameworks favor analog air-gapped systems for patient data protection. Saudi hospital networks specify coaxial-only architectures in radiology and pharmacy zones.
- Government:Ministry of Interior procurement through NUPC concentrates demand for standardized bullet and dome portfolios. UAE critical infrastructure protection programs sustain wired-only specifications for electromagnetic pulse resilience.
Government verticals absorb the largest absolute unit volumes. Healthcare applications are expanding most quickly as cybersecurity compliance tightens.
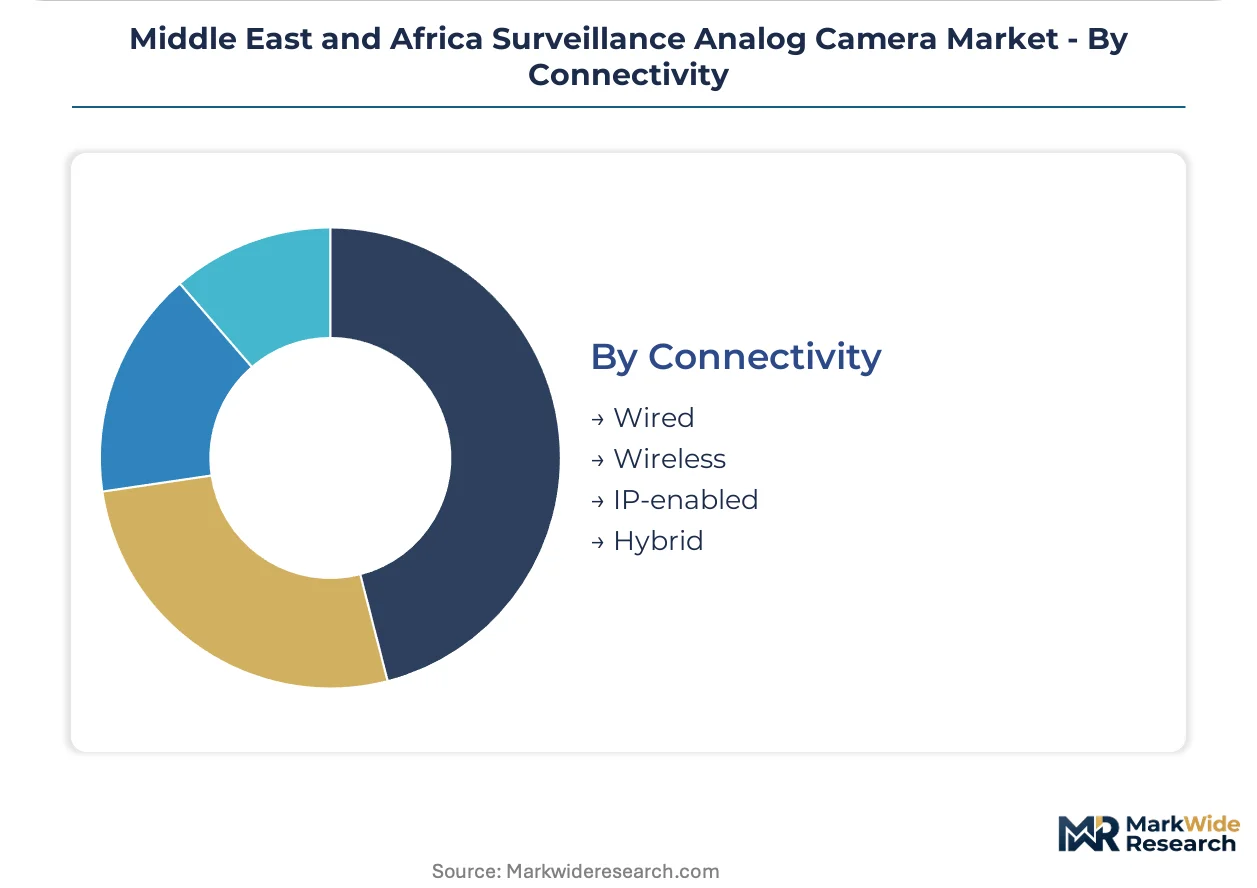
Connectivity:
Supply concentration in Korean sensor module production creates channel bottlenecks for hybrid and IP-enabled variants, while wired analog maintains diversified sourcing.
- Wired:Coaxial transmission via RG-59 or RG-6 cable without intermediate encoding preserves signal integrity across long distances. Nigerian and Kenyan grid instability sustains preference for locally powered coaxial systems over PoE-dependent alternatives.
- Wireless:2.4 GHz and 5.8 GHz radio links with analog video transmission suit temporary deployments or heritage structures where cable routing proves impractical. South African game reserve operators use these for seasonal migration monitoring.
- IP-enabled:On-camera H.264/H.265 encoding enables direct network attachment while retaining analog sensor architecture. UAE hybrid upgrade roadmaps specify these for phased infrastructure transition.
- Hybrid:Dual-output devices simultaneously feed analog DVRs and IP VMS platforms. Saudi educational facility renovations favor these to preserve existing coaxial investment while enabling future digital migration.
Wired connectivity dominates unit shipments. Hybrid configurations are gaining share fastest as Gulf states balance legacy preservation against digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council smart city mandates and African infrastructure buildouts are redistributing procurement volumes across distinct regulatory environments. SFDA and MOHAP cybersecurity frameworks in Saudi Arabia and the UAE preserve analog deployment in sensitive facilities. Border security programs and transportation expansions sustain coaxial infrastructure investment despite digitization pressures.
Saudi Arabia
Ministry of Interior procurement through the National Unified Procurement Company concentrates demand for bullet and dome configurations in Riyadh and Jeddah. SFDA cybersecurity mandates for healthcare and energy facilities favor air-gapped coaxial systems over network-attached alternatives. The Eastern Province's Aramco facility standards mandate outdoor-rated enclosures for above-ground tank farm perimeter coverage.
United Arab Emirates
MOHAP critical infrastructure protection programs sustain wired-only specifications for electromagnetic pulse resilience in Dubai and Abu Dhabi. Hospital consortiums specify hybrid architectures with analog front-ends to meet compliance without ransomware exposure. Coastal surveillance networks favor wired bullet cameras for electromagnetic interference resistance in maritime environments.
South Africa
SABS standards gate product entry and favor established suppliers with local testing relationships in Johannesburg and Cape Town. Platinum mining operations in the North West Province deploy cooled variants for subterranean ventilation shaft monitoring. Supermarket chains specify ceiling-mounted dome configurations for aisle loss prevention.
Nigeria
Grid volatility preserves demand for coaxial-powered units over PoE-dependent IP alternatives in Lagos and Port Harcourt. Oil facility operators specify PTZ mechanisms for flare stack and pipeline monitoring in the Niger Delta. Chinese-financed railway corridors create greenfield analog deployment potential before IP infrastructure matures.
Kenya
Power instability sustains preference for locally powered coaxial systems in Nairobi and Mombasa. Banking halls specify lightweight indoor dome configurations for lobby and corridor coverage. Transportation hub expansion in Addis Ababa's regional network creates cross-border deployment opportunities for bullet cameras in platform edge surveillance.
Middle East and Africa Surveillance Analog Camera Market Competitive Landscape
Player mix skews toward diversified security conglomerates with regional logistics hubs and specialized imaging technology firms with sensor module supply chain control. Market structure concentrates procurement influence through Gulf government tender consolidation while African commercial distribution retains fragmentation. Three archetypes dominate: Korean manufacturing-scale suppliers feeding Dubai and Riyadh distribution networks, German engineering-base firms leveraging CE marking certification advantages, and Chinese cost-optimized portfolio specialists targeting price-sensitive African verticals. Competitive moves center on hybrid encoder convergence for coaxial cable reuse and SABS certification pathway establishment ahead of regional rivals.
Among Korean manufacturing-scale suppliers, Hanwha Vision anchors regional distribution through Seoul-Incheon production corridors feeding Gulf markets. Bosch Sicherheitssysteme GmbH exemplifies the German engineering-base archetype with certification advantages under EU Radio Equipment Directive eligibility. Dahua Technology occupies the cost-optimization position for African mining and energy price sensitivity. These three represent distinct strategic vectors: manufacturing scale, regulatory compliance, and portfolio cost engineering.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Bosch Sicherheitssysteme GmbH |
| Hanwha Vision |
| Teledyne FLIR LLC |
| ACTi Corporation |
| Dahua Technology |
| Axis Communications AB |
| Honeywell Security Group |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Starlight CMOS sensor migration replacing legacy CCD arrays simultaneously shifts procurement geography toward Seoul-Incheon manufacturing corridors and compresses pricing premiums for low-light performance tiers across Gulf government tenders.
Pricing Analysis
Cost-plus contracts with copper LME indexation dominate Saudi National Unified Procurement Company tenders, insulating integrators from RG-59 and RG-6 cable volatility while squeezing vendor margins. Three-tier pricing structure across SFDA-certified, CE-marked, and uncertified equipment separates Ministry of Interior specifications from African commercial distribution. Pricing pressure stems from NUPC consolidated buying power concentrating Riyadh and Jeddah demand. African mining operators exhibit highest price sensitivity, while UAE healthcare cybersecurity compliance mandates sustain premium tiers for air-gapped architectures.
Supply Chain Analysis
Strategic stockpiling of Korean sensor modules prevails over just-in-time approaches given Seoul-Incheon corridor concentration and Gulf tender volatility. Manufacturing gravity centers on South Korea, China, and Germany for module fabrication, lens assemblies, and precision machining respectively. Raw material dependencies span copper concentrates for coaxial cable, rare earth elements for sensor doping, and aluminum alloys for outdoor housings. Single-source vulnerability in Korean CMOS foundries threatens regional distributors. Distribution runs through Dubai and Riyadh logistics hubs feeding systems integrators and specialized security distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics driven by Gulf smart city infrastructure refresh cycles replacing first-generation coaxial deployments installed during the 2010-2015 oil revenue peak.
For Market Incumbents: Fortify hybrid encoder portfolios to capture Saudi educational facility upgrade cycles where coaxial reuse extends equipment lifecycle. Deepen backward integration into Korean sensor module sourcing to offset Seoul-Incheon supply concentration risk. Prioritize SABS certification investment ahead of South African regulatory tightening that favors established testing relationships.
For New Entrants and Emerging Players: Anchor in Ethiopian railway and transportation hub greenfield deployments before IP infrastructure maturity closes analog windows. Target Nigerian oil facility PTZ specifications where grid instability preserves coaxial preference over PoE alternatives. Pursue Chinese-financed infrastructure projects with cost-optimized bullet portfolios.
For Investors and Strategic Acquirers: The market sits at a late-cycle analog phase that favors hybrid technology bridge providers with installed base conversion capabilities. Long-term viability hinges on 5-10 year infrastructure replacement timelines across Gulf Cooperation Council states. Acquisition targets should demonstrate regional logistics hub control and SFDA or MOHAP certification pathways. Watch for Saudi Aramco facility standard revisions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Encoder Portfolio Expansion | Enables coaxial cable reuse in Saudi educational upgrades while preserving analog reliability. |
| SABS Certification Establishment | Gates South African mining and retail procurement ahead of regulatory tightening. |
| Seoul-Incheon Sensor Module Sourcing | Secures Starlight CMOS supply for Gulf low-light specification compliance. |
| Dubai Logistics Hub Capacity Addition | Supports 48-hour replacement part availability across Kingdom geography. |
| Ethiopian Railway Corridor Partnership | Captures greenfield analog deployment before IP infrastructure maturation. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented procurement patterns. System integrators in Riyadh and Dubai, Ministry of Interior specification officers, SABS testing laboratory personnel, and African mining security directors provided operational perspective. Secondary sources include SFDA cybersecurity framework documentation, MOHAP critical infrastructure mandates, NUPC tender disclosures, and SABS standards publications. Bottom-up channel checks triangulate against top-down Gulf Cooperation Council security spending estimates.
Sensitivity analysis around copper price volatility, Korean manufacturing lead times, and Saudi procurement consolidation intensity frames the projection envelope. Segmentation dimensions span product type, installation environment, end-user vertical, and connectivity architecture across the modeling period. CAGRs derive from installed base replacement curves and greenfield infrastructure buildout pacing. Starlight sensor adoption rates and hybrid encoder penetration serve as industry-specific demand drivers.
Material uncertainties — commodity price swings, regulatory framework revisions, and technology substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about Gulf smart city digitization timelines and African power grid stabilization trajectories. Revision becomes warranted when IP camera price parity crosses analog total-cost-of-ownership thresholds in UAE retail and banking verticals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Canada Surveillance Storage Market