
 Pulmonary Fibrosis Treatment Market | 2026-2036
Pulmonary Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Fibrosis Treatment Market Outlook
The pulmonary fibrosis treatment landscape is recalibrating around a widening split between premium biologic antifibrotics and commoditized corticosteroid regimens. Boehringer Ingelheim leverages its nintedanib franchise to anchor the premium tier with extensive real-world evidence programs. F. Hoffmann-La Roche Ltd competes through pirfenidone formulations and sustained investment in biomarker-guided patient selection. FibroGen, Inc. differentiates via its connective tissue disease-linked fibrosis pipeline, targeting underserved indication subsets with novel mechanism candidates.
Pulmonary fibrosis treatment encompasses pharmacological and supportive interventions designed to slow progressive scarring of lung parenchyma, with antifibrotic agents like nintedanib and pirfenidone functioning as tyrosine kinase inhibitors that attenuate fibroblast proliferation and extracellular matrix deposition. The primary purpose is to preserve forced vital capacity and extend survival in patients with declining lung function. Antifibrotic agents command the dominant revenue share due to their disease-modifying label and premium pricing architecture, while oxygen therapy represents the fastest-expanding delivery segment as home-based pulse-flow systems reduce hospital dependency. Injectable biologics occupy concentrated margin pools where specialty pharmacy networks control distribution, though oral formulations sustain broader patient access across geography and payer type.
The FDA maintains stringent efficacy benchmarks for antifibrotic approvals through forced vital capacity decline endpoints, while the EMA's orphan drug framework in Europe accelerates market access for rare fibrosis variants. HIPAA compliance requirements in the United States shape how real-world data from hospital systems and homecare providers can feed post-market surveillance and label expansion efforts. Stakeholders must monitor how CMS national coverage determinations for emerging antifibrotic combinations will reshape prescribing economics across Medicare Advantage and traditional fee-for-service channels.
Market Dynamics
The pulmonary fibrosis treatment market is restructuring around Medicare reimbursement policies that tie antifibrotic prescribing to forced vital capacity monitoring protocols, creating tiered access patterns across hospital systems and specialty pharmacies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses clinical trial timelines for novel antifibrotic compounds, enabling earlier commercialization of mechanism-differentiated candidates.
- Home-based oxygen delivery systems:Pulse-flow technology adoption is reducing hospital readmission rates and expanding addressable patient populations beyond tertiary care centers.
- Interstitial lung disease program expansion:Hospital systems in the United States are consolidating pulmonology services into dedicated ILD centers, concentrating prescribing volume and streamlining prior authorization workflows.
Market Restraints
- Biologic API supply concentration:Tyrosine kinase inhibitor raw material production clusters in specific Asian manufacturing hubs, exposing formulators to single-source dependency risks.
- CMS National Coverage Determination delays:Emerging antifibrotic combination therapies face extended reimbursement review timelines that stall physician adoption.
- Generic corticosteroid substitution:Commoditized immunosuppressant regimens retain substantial prescribing share due to cost differentials versus premium antifibrotics.
Strategic Opportunities
- Connective tissue disease-linked fibrosis subsets:Systemic sclerosis-associated ILD represents an underserved indication with distinct biomarker profiles and unmet medical need.
- Biomarker-guided patient selection:KL-6 and SP-D serum markers enable enrichment strategies that improve trial efficiency and label differentiation.
- Specialty pharmacy direct distribution:Hub-and-spoke models bypass traditional wholesale channels, capturing margin and improving adherence monitoring.
Industry Challenges
- Real-world evidence generation capacity:HIPAA-compliant data extraction from hospital EHR systems requires specialized infrastructure that stretches mid-tier developers.
- Forced vital capacity endpoint standardization:Variability in spirometry protocol execution across clinical sites introduces noise into registrational trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Fibrosis Treatment Market |
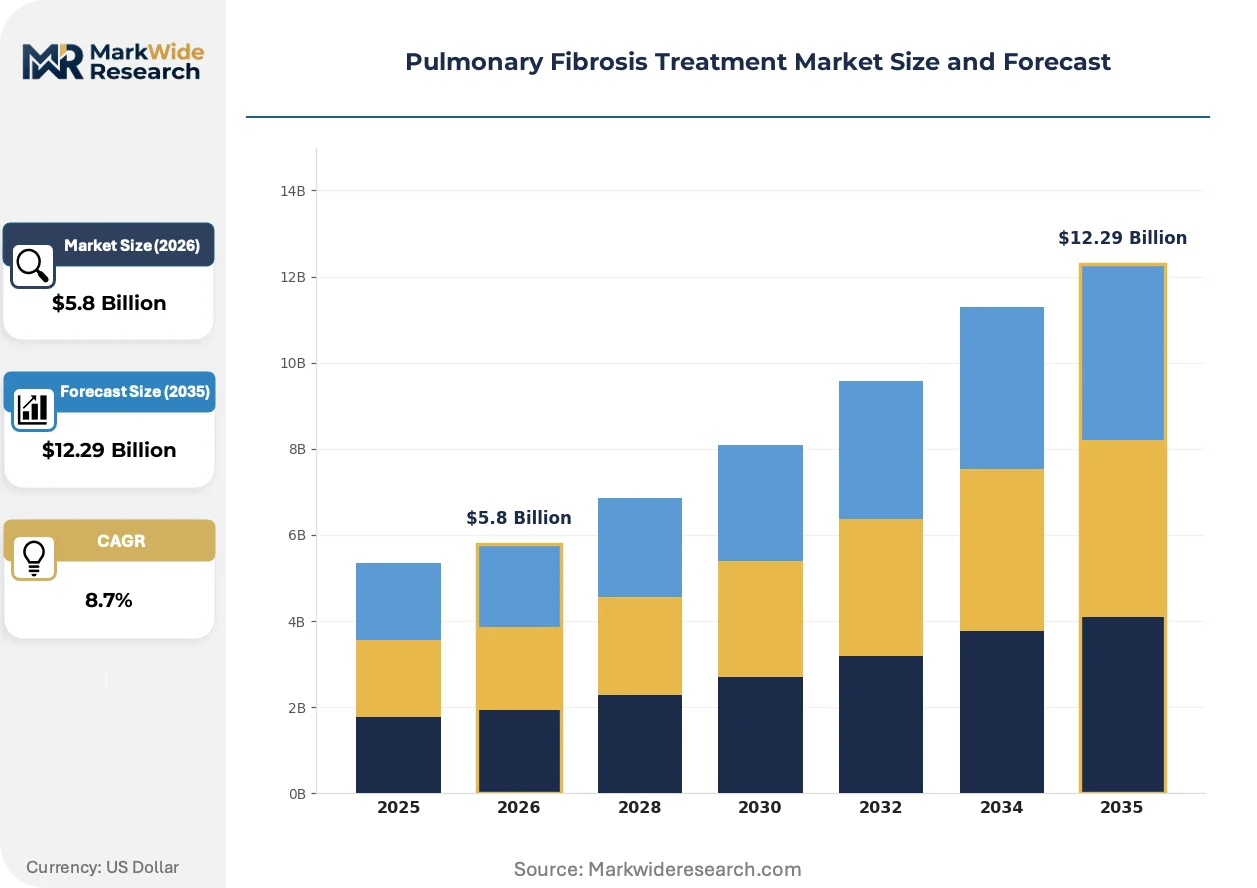
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Immunosuppressants, Oxygen Therapy Delivery Mode: Oral, Injectable, Inhalation, Intravenous End User: Hospitals, Homecare, Specialty Clinics, Long-term Care Facilities Indication: Idiopathic Pulmonary Fibrosis, Connective Tissue Disease, Drug-induced, Others |
| Companies Covered | Boehringer Ingelheim, F. Hoffmann-La Roche Ltd, FibroGen, Inc., Bristol-Myers Squibb Company, Galapagos NV, United Therapeutics, Pliant Therapeutics, AstraZeneca plc, Gilead Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Fibrosis Treatment Market Strategic Shifts
Antifibrotic development is converging on mechanism-based patient stratification, with biomarker integration and digital respiratory monitoring reshaping how efficacy is measured and reimbursed.
Multiplex biomarker panels combining KL-6, SP-D, and matrix metalloproteinase concentrations are unifying diagnostic and prognostic workflows into single blood-draw protocols. Academic medical centers and large ILD programs are adopting these panels to streamline patient enrollment into mechanism-matched trials. The technology is unifying previously fragmented referral pathways between community pulmonologists and tertiary centers.
The FDA's orphan drug exclusivity framework for rare fibrosis variants is extending market protection periods for developers targeting limited prevalence subtypes. This policy creates incentive structures that favor indication-specific development over broad IPF labels. Developers are responding by fragmenting pipelines into discrete connective tissue disease-linked programs.
Hospital procurement committees are consolidating antifibrotic purchasing through integrated delivery network contracts that bundle nintedanib and pirfenidone with oxygen therapy services. Specialty pharmacy networks are displacing independent distributors in these arrangements. The United States exhibits the most pronounced concentration, with Medicare Advantage plans driving bundled reimbursement models.
Pulmonary Fibrosis Treatment Market Segmentation
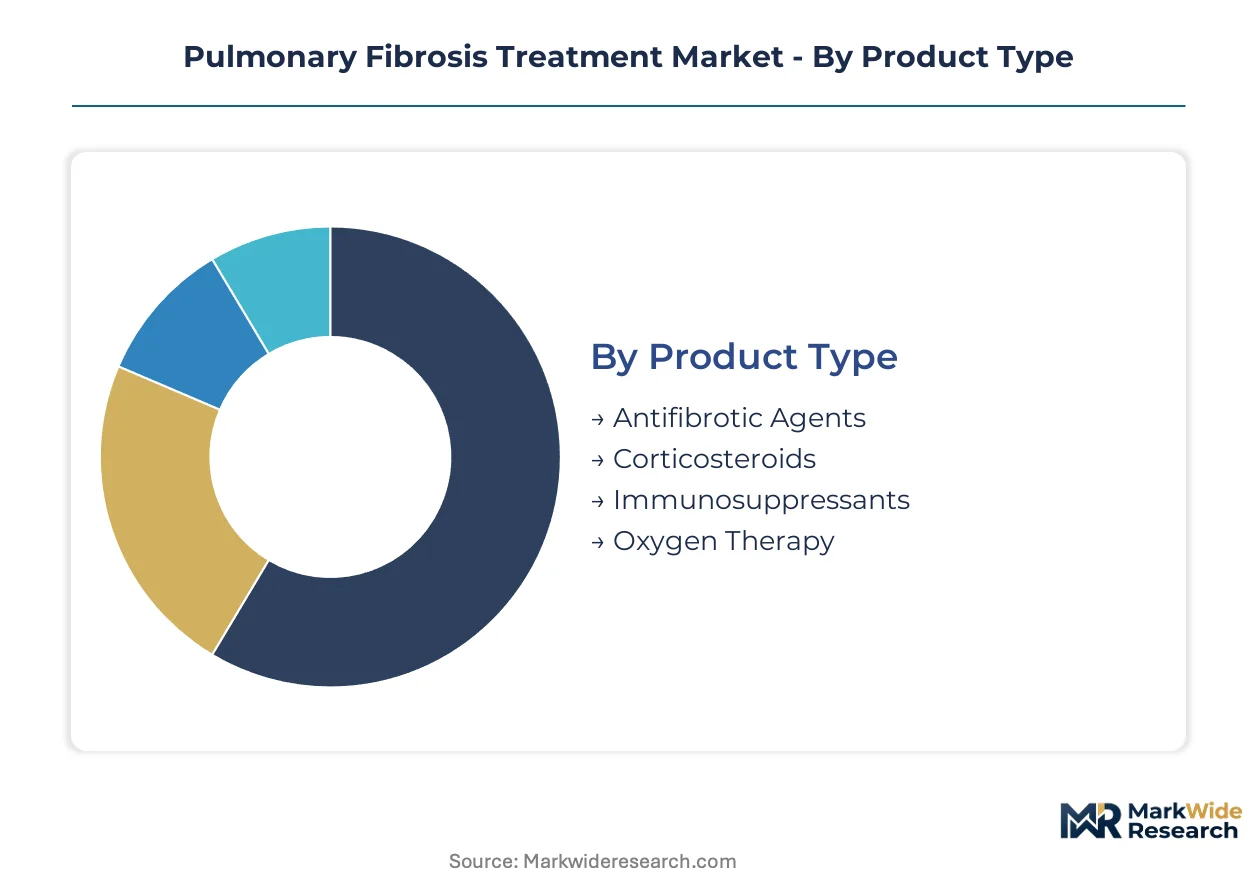
Segmentation in the pulmonary fibrosis treatment market determines how antifibrotic agents integrate into care pathways versus standalone supportive interventions. Product type and delivery mode classifications shape reimbursement tiers, while end-user and indication splits govern prescribing concentration across hospital systems and homecare networks.
Product Type:
Standalone pharmacological interventions anchor premium revenue pools, whereas embedded supportive therapies expand through bundled reimbursement contracts.
- Antifibrotic Agents:Tyrosine kinase inhibitors and pyridone derivatives that attenuate fibroblast proliferation and extracellular matrix deposition. Demand concentrates in United States Medicare Advantage networks where prior authorization workflows favor disease-modifying labels over symptomatic management.
- Oxygen Therapy:Pulse-flow and continuous-flow delivery systems supporting hypoxemic patients with declining forced vital capacity. Homecare providers in Germany and Japan are embedding these systems into chronic care management contracts that reduce hospital readmission penalties.
- Corticosteroids:Commoditized anti-inflammatory regimens deployed as bridging therapy or in combination protocols.
- Immunosuppressants:Agents targeting autoimmune-mediated fibrosis progression in connective tissue disease subsets.
Volume placements concentrate in antifibrotic agents; the faster expansion belongs to oxygen therapy.
Delivery Mode:
Route of administration determines patient access geography, with oral formulations penetrating rural markets and injectable biologics concentrating in tertiary center catchments.
- Oral:Capsule and tablet formulations of nintedanib and pirfenidone enabling home-based administration without infusion infrastructure. United States specialty pharmacies and Australian community pulmonology practices drive volume through mail-order distribution networks that bypass hospital markup.
- Injectable:Subcutaneous and intramuscular biologics requiring cold-chain logistics and clinical monitoring. Concentrated demand in French and Italian academic medical centers with dedicated interstitial lung disease infusion suites.
- Inhalation:Nebulized and dry-powder antifibrotic candidates in development pipelines.
- Intravenous:Hospital-administered formulations for acute exacerbation management.
Oral delivery captures the dominant prescription volume; injectable modes are climbing the fastest as biologic pipelines mature.
End User:
Care setting segmentation tracks the shift from inpatient diagnosis toward longitudinal outpatient management.
- Hospitals:Tertiary centers with dedicated interstitial lung disease programs performing diagnostic bronchoscopy and initiating antifibrotic therapy. United States academic medical centers in Boston and San Francisco anchor prescriber training networks that shape community practice patterns.
- Homecare:Medicare-certified agencies delivering oxygen equipment and remote monitoring for ambulatory patients. Expansion fastest in Japanese long-term care insurance frameworks and German disease management programs.
- Specialty Clinics:Pulmonology-focused outpatient facilities managing stable patients on maintenance therapy.
- Long-term Care Facilities:Skilled nursing settings managing oxygen-dependent patients with comorbid mobility limitations.
Hospitals retain the highest antifibrotic prescribing intensity; homecare is gaining share fastest as pulse-flow technology enables discharge planning.
Indication:
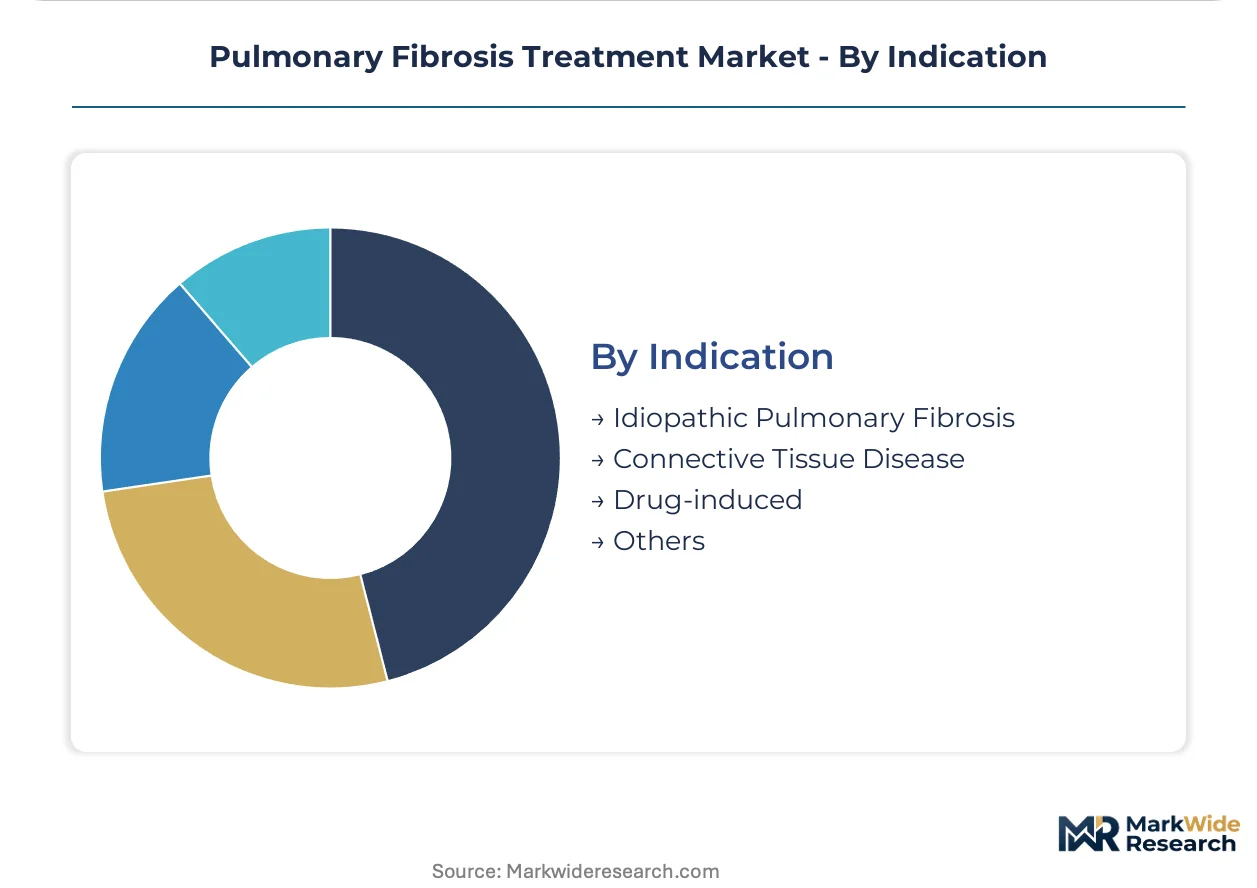
Disease etiology segmentation separates idiopathic presentations with established antifibrotic labels from systemic disease-linked variants with evolving evidence bases.
- Idiopathic Pulmonary Fibrosis:The reference indication with full regulatory approval for nintedanib and pirfenidone across FDA and EMA jurisdictions. United States pulmonologists in Florida and Arizona retirement corridors manage the largest diagnosed prevalence pools.
- Connective Tissue Disease:Systemic sclerosis-associated and rheumatoid arthritis-linked interstitial lung disease with emerging trial data. United Kingdom and Netherlands rheumatology-pulmonology collaborative networks are driving enrollment in mechanism-stratified studies.
- Drug-induced:Fibrosis secondary to chemotherapy, amiodarone, or occupational exposures.
- Others:Hypersensitivity pneumonitis and unclassifiable interstitial pneumonia variants.
Idiopathic pulmonary fibrosis commands the deepest formulary coverage; connective tissue disease-linked fibrosis shows the steepest expansion trajectory as biomarker enrichment strategies improve trial efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the United States pulmonary fibrosis treatment infrastructure through Massachusetts General Hospital's interstitial lung disease center and affiliated specialty pharmacy networks.
United States
Medicare Advantage plans in Florida and Arizona retirement corridors drive antifibrotic prescribing volume through bundled reimbursement models. The FDA's breakthrough therapy designation pathway accelerates novel compound approvals while CMS national coverage determinations shape physician adoption timelines. Mayo Clinic in Rochester, Minnesota anchors prescriber training networks that standardize forced vital capacity monitoring protocols across community pulmonology practices.
Germany
Homecare providers embed pulse-flow oxygen systems into disease management contracts that reduce hospital readmission penalties under statutory health insurance frameworks. The EMA's orphan drug framework accelerates market access for rare fibrosis variants while national reference pricing constrains premium antifibrotic reimbursement. Heidelberg University Hospital's ILD program concentrates clinical trial enrollment for connective tissue disease-linked fibrosis subsets.
Japan
Long-term care insurance frameworks expand home-based oxygen therapy eligibility for ambulatory patients with declining lung function. The PMDA maintains stringent efficacy benchmarks aligned with FDA forced vital capacity endpoints while METI supports domestic manufacturing of tyrosine kinase inhibitor raw materials. Tokyo Medical and Dental University Hospital anchors biomarker-guided patient selection research using KL-6 and SP-D serum panels.
United Kingdom
Rheumatology-pulmonology collaborative networks in London and Manchester drive enrollment in mechanism-stratified studies for systemic sclerosis-associated interstitial lung disease. NHS England's specialized commissioning framework concentrates antifibrotic prescribing within designated interstitial lung disease centers. The Royal Brompton Hospital anchors real-world evidence generation through HIPAA-equivalent data governance compliant with NHS Digital standards.
France
Academic medical centers in Paris maintain dedicated interstitial lung disease infusion suites for injectable biologic administration. ANSM oversees post-market surveillance of antifibrotic agents while national health insurance reimbursement favors oral formulations for home-based administration. Hôpital Bichat-Claude Bernard anchors the French reference network for rare pulmonary diseases and biomarker validation studies.
Pulmonary Fibrosis Treatment Market Competitive Environment
Capital-heavy pharmaceutical manufacturers compete with asset-light biotech developers for antifibrotic pipeline positioning. The market structure consolidates around established tyrosine kinase inhibitor franchises and emerging mechanism-differentiated candidates. Three archetypes dominate: integrated multinational pharmas with real-world evidence infrastructure, mid-cap biotechs with orphan indication focus, and specialty generics firms commoditizing corticosteroid bridging therapies. Competitive moves center on biomarker-guided patient selection partnerships and specialty pharmacy direct distribution arrangements.
Within the integrated multinational tier, Boehringer Ingelheim and F. Hoffmann-La Roche Ltd exemplify divergent antifibrotic anchoring strategies—one through extensive nintedanib real-world evidence programs, the other through pirfenidone formulation refinement. FibroGen, Inc. occupies a position among mechanism-focused biotechs targeting connective tissue disease-linked fibrosis subsets with novel candidates. These three entities collectively represent the spectrum from mature franchise defense to indication-specific pipeline expansion.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| F. Hoffmann-La Roche Ltd |
| FibroGen, Inc. |
| Bristol-Myers Squibb Company |
| Galapagos NV |
| United Therapeutics |
| Pliant Therapeutics |
| AstraZeneca plc |
| Gilead Sciences, Inc. |
| Others |
Value Chain & Pricing Dynamics
Tyrosine kinase inhibitor raw material costs cascade through antifibrotic pricing tiers, with API production concentration in Asian manufacturing hubs feeding premium markups for nintedanib and pirfenidone formulations sold through United States Medicare Advantage networks and European statutory health insurance frameworks.
Pricing Analysis
Value-based pricing anchored to forced vital capacity preservation outcomes separates premium antifibrotic agents from commoditized corticosteroid regimens. Three-tier pricing structure across premium disease-modifying labels, standard immunosuppressant combinations, and economy corticosteroid bridging therapies reflects reimbursement tier differentiation. Price differentiation hinges on FDA breakthrough therapy designation status and bundled oxygen therapy service inclusion. Cost compression in the corticosteroid tier is intensifying because generic substitution protocols favor immunosuppressant cost containment. Community pulmonology practices exhibit highest price sensitivity; academic medical centers with dedicated interstitial lung disease programs demonstrate lowest sensitivity due to formulary lock-in.
Supply Chain Analysis
Cold-chain logistics costs for injectable biologics concentrate distribution planning around tertiary center catchments in the United States, Germany, and Japan. Tyrosine kinase inhibitor API production draws from manufacturing hubs in China, India, and South Korea, with downstream formulation and packaging resting on facilities in the United States and Western Europe. Single-source vulnerability for pirfenidone precursor chemicals creates exposure to regulatory inspection delays. Distribution runs through specialty pharmacy hub-and-spoke networks that bypass traditional wholesale channels, capturing margin and enabling adherence monitoring for oral antifibrotic agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA forced vital capacity endpoint requirements and CMS national coverage determination protocols erect substantial compliance moats that protect entrenched antifibrotic developers while raising capital barriers for mechanism-differentiated challengers.
For Market Incumbents: Lock in real-world evidence generation partnerships with Massachusetts General Hospital and Mayo Clinic to defend against biosimilar entry threats. Deepen backward integration into tyrosine kinase inhibitor API production to reduce single-source dependency risks from Asian manufacturing concentration. Prioritize biomarker-guided patient selection infrastructure investments that reinforce formulary positioning against corticosteroid substitution pressures.
For New Entrants and Emerging Players: Capture connective tissue disease-linked fibrosis subsets where KL-6 and SP-D serum marker enrichment strategies enable trial efficiency gains against established IPF labels. Target United Kingdom rheumatology-pulmonology collaborative networks as the most penetrable entry channel given NHS England's specialized commissioning framework concentration. Deploy mechanism-differentiated positioning through academic medical center investigator-initiated studies rather than head-to-head commercial trials.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards to novel antifibrotic compounds are the leading indicator that reimbursement velocity will accelerate for mechanism-differentiated candidates over the next decade. Acquisition targets should prioritize mid-cap biotechs with orphan indication focus and biomarker-guided patient selection platforms. Watch CMS national coverage determination timelines for antifibrotic combination therapies as the critical signal for prescribing economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Guided Patient Selection Platform | KL-6 and SP-D serum marker integration streamlines enrollment into mechanism-matched trials at Heidelberg University Hospital. |
| Specialty Pharmacy Direct Distribution | Hub-and-spoke models bypass wholesale markup and enable adherence monitoring for Medicare Advantage beneficiaries. |
| Real-World Evidence Infrastructure Partnership | HIPAA-compliant EHR extraction capabilities anchor post-market surveillance and label expansion at Royal Brompton Hospital. |
| Orphan Drug Indication Fragmentation | EMA exclusivity extensions for systemic sclerosis-associated ILD variants create protected revenue pools beyond crowded IPF labels. |
| Pulse-Flow Oxygen Technology Integration | Home-based delivery systems reduce hospital readmission penalties under Japanese long-term care insurance frameworks. |
Study Parameters
Multi-period observation of antifibrotic prescribing volume, forced vital capacity monitoring protocol adoption, and Medicare Advantage bundled reimbursement penetration anchored the trend analysis, supplemented by interviews with drug development executives at mechanism-focused biotechs, regulatory affairs leads navigating FDA breakthrough therapy pathways, formulary directors at United States payers, hospital procurement managers within integrated delivery networks, and payer access specialists shaping prior authorization workflows. Secondary validation drew from FDA filings, EMA submission documents, ClinicalTrials.gov enrollment data, and CMS national coverage determination records. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Input-output matrix framing connected tyrosine kinase inhibitor API production volumes to finished antifibrotic agent demand across oral and injectable delivery modes, treatment line positioning, patient population severity strata, and regional regulatory clusters throughout the projection horizon. CAGRs were derived from epidemiological prevalence projections, diagnosis rate assumptions, and antifibrotic penetration curves by indication. Forecast inputs incorporated biomarker-guided patient selection adoption timelines and specialty pharmacy network expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement policy shifts, generic corticosteroid substitution protocol intensification, and biologic API supply disruption events. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market