
 Respiratory Antiviral Treatment Market | 2026-2036
Respiratory Antiviral Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Antiviral Treatment Market Analytics
The EU Green Deal is rebalancing pharmaceutical procurement criteria across European hospital networks, favoring suppliers with verified carbon footprints in active pharmaceutical ingredient production. Gilead Sciences leverages its nucleoside analog expertise to sustain manufacturing scale across multiple respiratory indications. Pfizer anchors its position through integrated supply chains spanning API synthesis to finished dose packaging. F. Hoffmann-La Roche Ltd. differentiates via diagnostic-treatment pairing strategies that lock in hospital formulary placement.
Respiratory antiviral treatments comprise synthetic small-molecule inhibitors targeting viral replication machinery, formulated for systemic or local delivery with bioavailability parameters dictating dosing frequency and tissue penetration profiles. These agents serve to reduce disease severity, hospitalization duration, and transmission risk in seasonal and pandemic respiratory infections. The oral delivery mode dominates current prescribing patterns due to outpatient compatibility and pharmacy dispensability, while inhalation formulations command premium positioning in severe acute cases requiring rapid pulmonary drug deposition. Baloxavir's single-dose mechanism is gaining fastest among influenza applications, displacing multi-day oseltamivir regimens in convenience-sensitive segments.
The FDA's Emergency Use Authorization framework and EMA's adaptive pathway programs are reshaping trial design requirements and post-market surveillance obligations for respiratory antivirals, directly influencing development cost structures and market access timelines. WHO prequalification standards and national essential medicines lists determine procurement eligibility across low- and middle-income markets, fragmenting commercial strategies between premium and access-tier geographies. Stakeholders must monitor resistance surveillance networks and variant-tracking databases to anticipate therapeutic obsolescence cycles and portfolio reallocation needs.
Market Dynamics
Federal stockpiling mandates in the United States and EU Green Deal procurement criteria are restructuring hospital formulary decisions, compressing supplier qualification timelines while elevating carbon-verified active pharmaceutical ingredient sourcing as a threshold requirement for contract eligibility.
Growth Catalysts
- Accelerated Approval Frameworks:The FDA's Emergency Use Authorization pathway compresses clinical trial phases for respiratory antivirals, enabling faster market entry for therapies targeting novel viral variants.
- Hospital Preparedness Mandates:Post-pandemic institutional requirements in the United States sustain bulk procurement volumes for antiviral stockpiles, anchoring demand through multi-year supply agreements.
- Single-Dose Formulation Advances:Mechanisms reducing treatment duration from multi-day regimens to single-administration protocols are capturing preference share in outpatient influenza management.
Market Restraints
- API Supply Concentration:Nucleoside analog precursor manufacturing concentrates in Asian chemical hubs, exposing formulators to geopolitical disruption and shipping volatility.
- Resistance Surveillance Burden:Viral mutation tracking requirements impose ongoing post-market study obligations that extend development cost recovery periods.
- Oral Formulation Dominance:Inhalation delivery platforms face reimbursement friction against established pill-based prescribing patterns in primary care settings.
Strategic Opportunities
- Diagnostic-Treatment Pairing:Integrated point-of-care viral detection with same-session antiviral dispensing is unlocking formulary lock-in through bundled hospital procurement.
- EMA Adaptive Pathways:Conditional marketing authorization based on surrogate endpoints is shortening European market access timelines for pandemic-preparedness candidates.
- Low-Income Country Access Tiers:WHO prequalification pathways enable volume-based pricing models for generic antiviral supply to national essential medicines programs.
Industry Challenges
- Manufacturing Scale-Up Complexity:Sterile inhalation device production requires dedicated filling lines that strain capital allocation across multi-indication portfolios.
- Cross-Border Regulatory Divergence:Differences between FDA post-market surveillance and EMA pharmacovigilance reporting formats fragment compliance resource deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Antiviral Treatment Market |
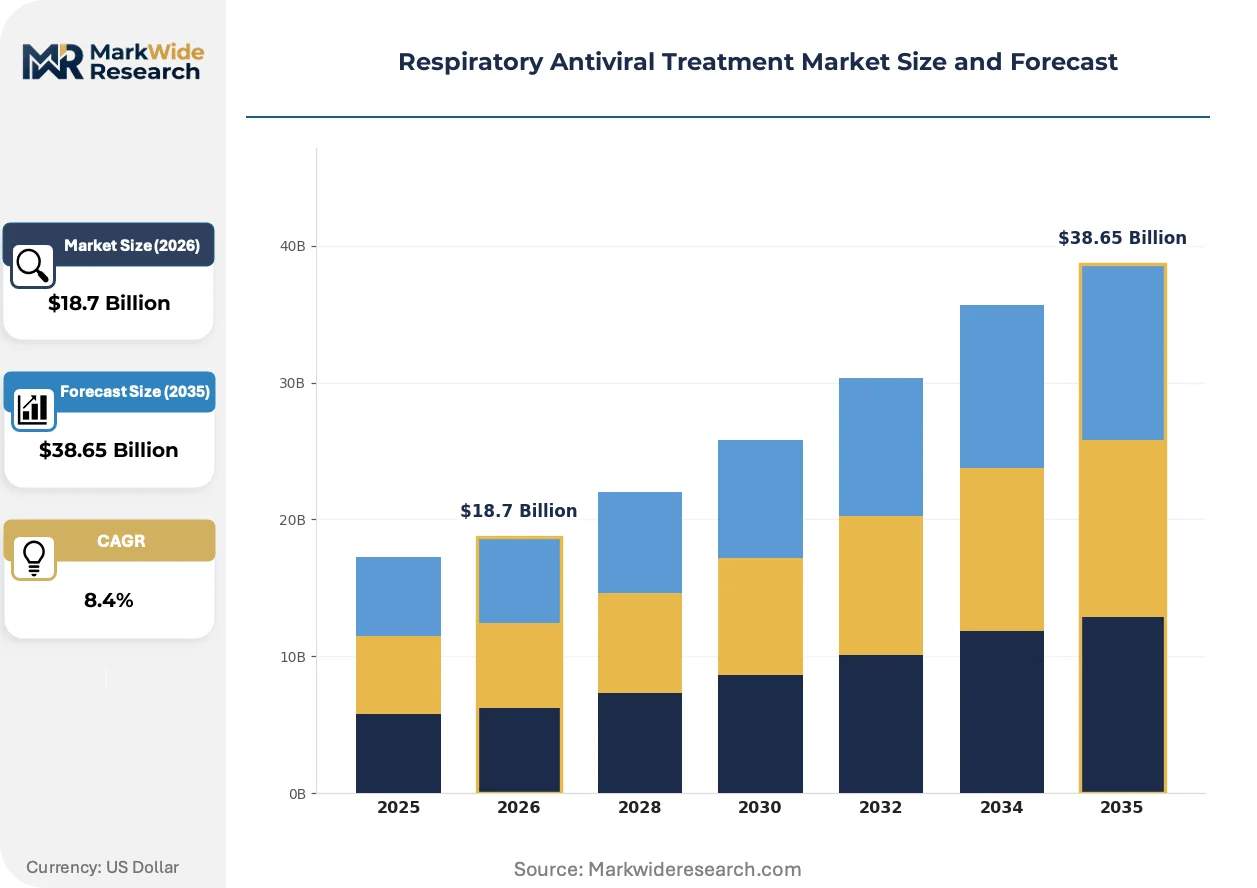
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oseltamivir, Zanamivir, Baloxavir, Favipiravir End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Oral, Injectable, Inhalation, Nasal Spray Application: Influenza, COVID-19, RSV, Others |
| Companies Covered | Gilead Sciences, Pfizer, F. Hoffmann-La Roche Ltd., Novartis AG, GSK, Merck, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Antiviral Treatment Market Evolving Landscape
Respiratory antiviral development is pivoting toward mechanism-based differentiation and delivery innovation, with replication-targeting small molecules and host-directed therapies competing for formulary positioning against established neuraminidase inhibitors.
Host-directed immunomodulation is decentralizing therapeutic development away from pathogen-specific targets toward broadly acting cellular pathways. Large hospital systems and government procurement agencies are piloting these platforms for pandemic preparedness stockpiles. The approach is decentralizing R&D risk by reducing dependency on strain-matched vaccine and antiviral development cycles.
EMA's adaptive pathway program is compressing conditional approval timelines for respiratory antivirals demonstrating efficacy against surrogate biomarkers. Pharmaceutical developers are restructuring Phase II/III trial designs to accommodate rolling data submission requirements. European hospital networks are responding by establishing early-access procurement frameworks for therapies receiving positive scientific opinion.
Hospital procurement departments are consolidating antiviral purchasing through centralized therapeutic category management, displacing physician-driven formulary requests with committee-based value assessments. Group purchasing organizations are capturing greater influence over brand selection through sole-source contracting for single-dose influenza therapies. This concentration is most pronounced in United States integrated delivery networks managing seasonal surge capacity.
Respiratory Antiviral Treatment Market Segmentation
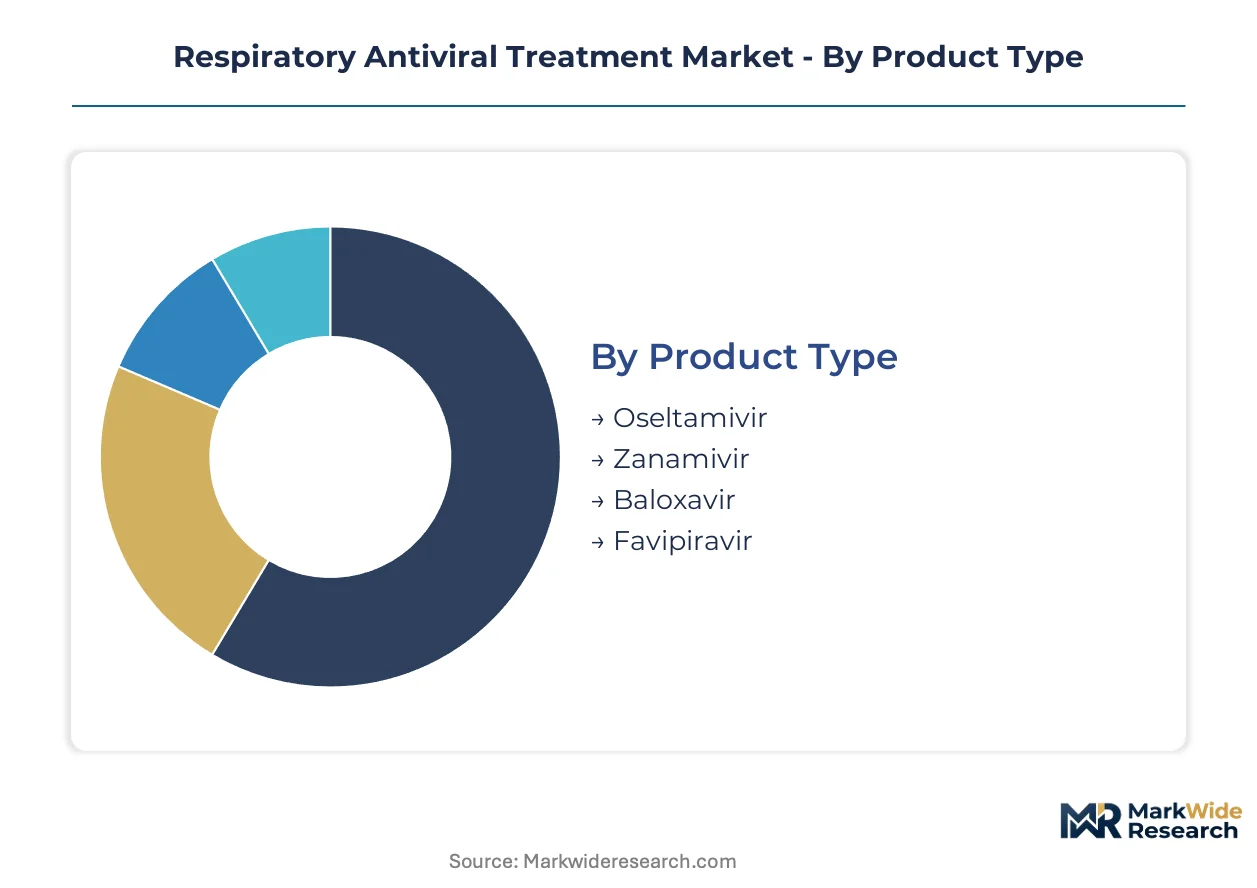
Respiratory antiviral treatment segmentation reveals divergent commercial logics across product chemistry, care setting economics, and disease-specific reimbursement pathways. Manufacturers must align formulation investments with procurement channel requirements and pandemic preparedness stockpiling mandates.
Product Type:
Standardization dominates neuraminidase inhibitors while polymerase-targeting mechanisms command premium positioning through differentiated dosing convenience.
- Oseltamivir:The neuraminidase inhibitor standard with established generic supply chains serving seasonal influenza protocols across United States hospital networks. Procurement concentrates through federal stockpile contracts and seasonal retail pharmacy dispensing.
- Baloxavir:Cap-dependent endonuclease inhibitor enabling single-dose influenza treatment with superior compliance profiles. United States outpatient prescribing is shifting fastest toward this mechanism as integrated delivery networks prioritize reduced pharmacy callbacks and adherence monitoring costs.
- Zanamivir:Inhaled neuraminidase inhibitor retaining niche hospital formulary placement for severe influenza with gastrointestinal intolerance to oral alternatives.
- Favipiravir:Purine nucleoside analog with broad RNA virus coverage deployed primarily in pandemic preparedness stockpiles outside established influenza protocols.
Leading the category by volume: Oseltamivir through generic substitution and seasonal prescribing scale. Growing fastest: Baloxavir via single-dose convenience and hospital formulary preference.
End User:
Channel economics fragment procurement authority between centralized hospital purchasing and decentralized retail pharmacy reimbursement.
- Hospitals:Centralized therapeutic category management governs antiviral selection with multi-year supply agreements anchoring volume. United States integrated delivery networks and European hospital consortia prioritize single-source contracting for surge capacity preparedness.
- Pharmacies:Seasonal influenza dispensing concentrates in retail chains with vaccination-adjacent prescribing and insurance formulary tier placement driving brand selection.
- Clinics:Urgent care and primary care settings balance convenience against cost through limited formularies with rapid diagnostic pairing.
- Home Care:Post-acute and long-term care facilities source through distributor networks with emphasis on storage stability and caregiver administration simplicity.
Dominant procurement channel: Hospitals through pandemic stockpiling mandates. Expanding most quickly: Pharmacies via outpatient influenza management decentralization.
Delivery Mode:
Patient-administered oral formats compete against clinician-delivered alternatives on reimbursement simplicity and adherence economics.
- Oral:Tablet and suspension formulations dominate outpatient influenza management with pharmacy dispensability and patient self-administration enabling scale. United States retail channels and European community pharmacy networks anchor volume through insurance reimbursement familiarity.
- Inhalation:Dry powder and nebulized delivery achieves rapid pulmonary deposition for severe hospitalized cases. Device manufacturing complexity and sterile filling requirements limit supplier base.
- Injectable:Intravenous formulations reserve for intensive care settings with bioavailability-critical severe disease.
- Nasal Spray:Limited commercial presence with formulation stability challenges constraining widespread adoption.
Highest volume format: Oral through outpatient compatibility. Premium positioning: Inhalation for acute hospital deployment.
Application:
Disease-specific development programs and regulatory pathways create portfolio segmentation between seasonal endemic markets and pandemic preparedness investments.
- Influenza:Established seasonal market with annual strain surveillance driving formulation updates. United States CDC and EMA coordinate with WHO on vaccine strain matching that indirectly shapes antiviral resistance monitoring priorities.
- COVID-19:Emergency use authorization frameworks compressed development timelines while post-market surveillance obligations extended. Regulatory divergence between FDA and EMA post-authorization study requirements fragmented compliance resource deployment.
- RSV:Pediatric and geriatric prophylaxis markets with monoclonal antibody competition reshaping antiviral development targets.
- Others:Emerging respiratory virus indications including metapneumovirus and parainfluenza with limited approved therapeutics.
Commercial maturity leader: Influenza through decades of surveillance infrastructure. Steepest expansion trajectory: COVID-19 via pandemic investment legacy and variant-adaptive development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis concentrates in Asian chemical manufacturing hubs while formulation and commercialization gravitate toward North American and European pharmaceutical markets. Consumption patterns diverge between seasonal outpatient prescribing in developed economies and pandemic stockpiling mandates driving institutional procurement.
United States
Federal stockpiling programs through the Strategic National Stockpile sustain multi-year antiviral procurement contracts with integrated delivery networks. FDA Emergency Use Authorization frameworks compress development timelines for novel respiratory therapeutics. Boston-Cambridge biotech clusters anchor nucleoside analog R&D alongside North Carolina's Research Triangle manufacturing infrastructure.
Germany
Hospital consortia procurement centralization elevates carbon-verified API sourcing as a contract eligibility threshold under EU Green Deal implementation. EMA adaptive pathway programs enable conditional marketing authorization based on surrogate efficacy endpoints. Baden-Württemberg's pharmaceutical manufacturing corridor hosts sterile filling operations for inhalation device production.
Japan
PMDA accelerated review pathways for pandemic preparedness candidates align with METI industrial policy supporting domestic antiviral manufacturing capacity. Seasonal influenza surveillance infrastructure through the National Institute of Infectious Diseases shapes resistance monitoring priorities. Kansai region pharmaceutical clusters specialize in polymerase-targeting mechanism development.
India
CDSCO streamlined approval processes for WHO prequalified generic antivirals enable volume-based supply to national essential medicines programs. PLI scheme incentives attract API manufacturing investment away from pure formulation operations. Hyderabad-Visakhapatnam chemical hubs concentrate nucleoside analog precursor production for export markets.
Switzerland
Swissmedic regulatory efficiency supports early-access frameworks for therapies receiving EMA positive scientific opinion. Basel-region pharmaceutical headquarters coordinate diagnostic-treatment pairing strategies across European hospital networks. Geneva-based WHO prequalification programs determine procurement eligibility for low-income country access tiers.
Respiratory Antiviral Treatment Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with captive API manufacturing and diagnostic-treatment bundling capabilities. Market concentration reflects high barriers to sterile inhalation device production and multi-year hospital procurement contract lock-in. Three archetypes dominate: nucleoside analog specialists leveraging manufacturing scale, diagnostic-anchored integrators securing formulary placement, and generic manufacturers serving WHO prequalification pathways. Competitive moves center on diagnostic-treatment pairing alliances and backward integration into API precursor supply.
Within the nucleoside analog specialist tier, Gilead Sciences and Pfizer exemplify manufacturing-scale defenders with multi-indication portfolio breadth. F. Hoffmann-La Roche Ltd. occupies a distinct position as a diagnostic-treatment integrator leveraging point-of-care viral detection platforms to anchor hospital formulary placement. These three entities represent the dominant competitive archetypes structuring procurement negotiations across United States integrated delivery networks and European hospital consortia.
| Leading Market Players |
|---|
| Gilead Sciences |
| Pfizer |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| GSK |
| Merck |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Synthetic organic chemist concentrations in Hyderabad and Shanghai chemical parks feed directly into nucleoside analog precursor cost structures, with labor-cost differentials between these Asian manufacturing hubs and Basel-region headquarters widening the spread between economy-tier generic API and premium branded finished dose pricing.
Pricing Analysis
Cost-down pressure on polymerase-targeting mechanisms accelerates because single-dose convenience claims face reimbursement scrutiny against established multi-day generic regimens. Three-tier pricing structure across premium, standard, and economy levels separates patented endonuclease inhibitors from branded neuraminidase standards and WHO-prequalified generic oseltamivir. Price differentiation hinges on FDA approval tier and volume procurement scale. Hospital procurement committees exhibit highest price sensitivity through sole-source contracting mandates, while federal stockpiling programs demonstrate lowest sensitivity due to pandemic preparedness urgency.
Supply Chain Analysis
India's PLI scheme and China's bulk chemical subsidies are reshaping API sourcing decisions for European and North American formulators. Nucleoside analog precursor manufacturing concentrates in India, China, and South Korea, with sterile inhalation device assembly tethered to Switzerland and Germany. Active pharmaceutical ingredients, specialized packaging components, and diagnostic pairing hardware constitute critical input dependencies. Single-source vulnerability in Asian chemical hub concentration exposes formulators to shipping volatility and geopolitical disruption. Distribution runs through hospital GPOs and federal stockpile procurement channels in developed markets, with WHO prequalification pathways serving low-income country access tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile inhalation device production capacity constraints prop pricing premiums for rapid-deployment hospital formats, sustaining margin pools for manufacturers with dedicated filling line investments.
For Market Incumbents: Deploy diagnostic-treatment bundling to lock in hospital formulary placement against generic substitution threats. Secure backward integration into nucleoside analog precursor supply through contract manufacturing alliances with Hyderabad-Visakhapatnam chemical hubs. Prioritize EMA adaptive pathway qualification to compress European market access timelines ahead of polymerase-targeting mechanism competitors. For New Entrants and Emerging Players: Begin with WHO prequalification pathway navigation for generic antiviral supply to national essential medicines programs in low-income markets. Target pediatric RSV prophylaxis adjacencies where monoclonal antibody competition has displaced incumbent antiviral development priorities. Pursue point-of-care diagnostic pairing as the fastest formulary entry mechanism for hospital procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with nucleoside analog specialists given FDA accelerated approval pathway expansion for pandemic preparedness candidates. Five-to-ten year viability favors manufacturers with captive API synthesis and multi-indication respiratory portfolio breadth. Watch resistance surveillance network alerts for therapeutic obsolescence signals triggering portfolio reallocation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Treatment Pairing | Integrates Roche's point-of-care platforms with antiviral dispensing to secure hospital formulary lock-in. |
| EMA Adaptive Pathway Qualification | Enables conditional marketing authorization based on surrogate endpoints for pandemic preparedness candidates. |
| API Precursor Backward Integration | Captures Hyderabad-Visakhapatnam chemical hub capacity to reduce nucleoside analog supply disruption exposure. |
| WHO Prequalification Pathway | Unlocks volume-based pricing models for generic antiviral supply to national essential medicines programs. |
| Sterile Inhalation Device Scale-Up | Addresses Baden-Württemberg manufacturing corridor capacity constraints for acute hospital deployment formats. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists underwrites the qualitative findings. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases provide secondary validation. Bottom-up demand modeling across treatment lines and administration routes triangulates against top-down market sizing.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product chemistry, care setting economics, delivery mode, and disease-specific reimbursement pathways. CAGRs derive from epidemiological trend extrapolation, regulatory approval probability weighting, and procurement contract renewal analysis. Resistance surveillance frequency and variant emergence patterns inform therapeutic lifecycle assumptions.
Regulatory pathway delays, resistance mutation emergence, and API supply disruption are the dominant revision risks. Forecasts reflect documented assumptions regarding approval timelines, formulary placement rates, and stockpiling mandate continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market