
 Brazil Therapeutic Respiratory Devices Market | 2026-2036
Brazil Therapeutic Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Therapeutic Respiratory Devices Market Insights
Connected sensor integration is rewriting how therapeutic respiratory devices monitor patient adherence and titrate therapy automatically. Koninklijke Philips NV anchors its Brazil position through extensive homecare service networks that bundle device leasing with remote monitoring. Fisher & Paykel Healthcare Limited differentiates via humidification technology leadership that extends across its invasive and non-invasive ventilation portfolios. ResMed Inc. dominates the sleep apnea segment through direct-to-patient digital platforms that bypass traditional distributor markups.
Therapeutic respiratory devices encompass electromechanical and digital systems engineered to deliver measured gas flows, aerosolized medications, or positive airway pressure within specified pressure ranges and particle size distributions for treating obstructed or compromised pulmonary function. These systems incorporate flow sensors, microprocessor-controlled valves, and filtration media to maintain therapeutic precision across acute hospital, subacute rehabilitation, and domiciliary environments. Among product types, oxygen concentrators command the largest installed base due to chronic COPD prevalence, while CPAP machines generate the fastest replacement cycle as sleep apnea diagnosis expands through Brazil's private health networks. By application, asthma and COPD together absorb the majority of inhaler and nebulizer volumes, though sleep apnea now captures disproportionate margin pools through subscription-style resupply models.
ANVISA governs medical device registration and post-market surveillance, requiring clinical evidence for Class III respiratory devices that limits import speed and favors established suppliers with regulatory infrastructure already in place. The Brazilian Health Regulatory Agency's alignment with MERCOSUR technical standards further shapes which manufacturers can achieve streamlined multi-country approval. ANVISA's pending updates to software-as-a-medical-device guidance will determine how AI-enabled respiratory diagnostics enter the market. Stakeholders must weigh whether to build local technical service capabilities or partner with Brazilian distributors capable of navigating evolving inspection and adverse-event reporting obligations.
Market Dynamics
Homecare migration is compressing hospital-based respiratory device procurement while ANVISA's tightened Class III registration requirements extend import timelines and favor incumbent suppliers with established Brazilian regulatory infrastructure.
Growth Catalysts
- ANVISA's MERCOSUR alignment:Streamlined multi-country approval pathways reduce redundant technical documentation for manufacturers already certified in Argentina or Uruguay.
- Portable oxygen concentrator miniaturization:Battery chemistry advances enable same-day discharge protocols for COPD patients across São Paulo's private hospital networks.
- Sleep apnea diagnosis expansion:Brazilian private health insurance mandates now cover polysomnography, driving CPAP machine volumes through diagnostic clinic partnerships.
Market Restraints
- Imported component dependency:Pressure sensors and microprocessor-controlled valves concentrate in Southeast Asian manufacturing, exposing Brazilian assemblers to currency volatility and extended lead times.
- ANVISA software-as-medical-device uncertainty:Pending guidance on AI-enabled respiratory diagnostics creates investment paralysis for algorithm developers awaiting classification clarity.
- Stationary oxygen concentrator saturation:Legacy installed base in urban centers limits replacement demand compared to first-time penetration in northern states.
Strategic Opportunities
- Amazon basin domiciliary expansion:Riverine communities with limited hospital access represent unserved demand for solar-compatible portable concentrators with telemedicine linkage.
- Remote monitoring platform bundling:Leasing models that integrate cellular-connected adherence tracking capture recurring revenue streams beyond device sale margins.
- Humidification technology cross-selling:High-flow nasal cannula adoption in post-acute facilities creates pull-through for compatible heated humidifier systems.
Industry Challenges
- Biomedical engineering talent scarcity:São Paulo and Rio de Janeiro face acute shortages of technicians qualified to service microprocessor-controlled ventilation systems outside warranty periods.
- Adverse event reporting infrastructure:ANVISA's mandatory post-market surveillance obligations demand localized quality management systems that distributor partners often lack.
- Legacy CPAP device integration:Proprietary data protocols from earlier-generation machines block seamless migration to cloud-connected platforms without hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Therapeutic Respiratory Devices Market |
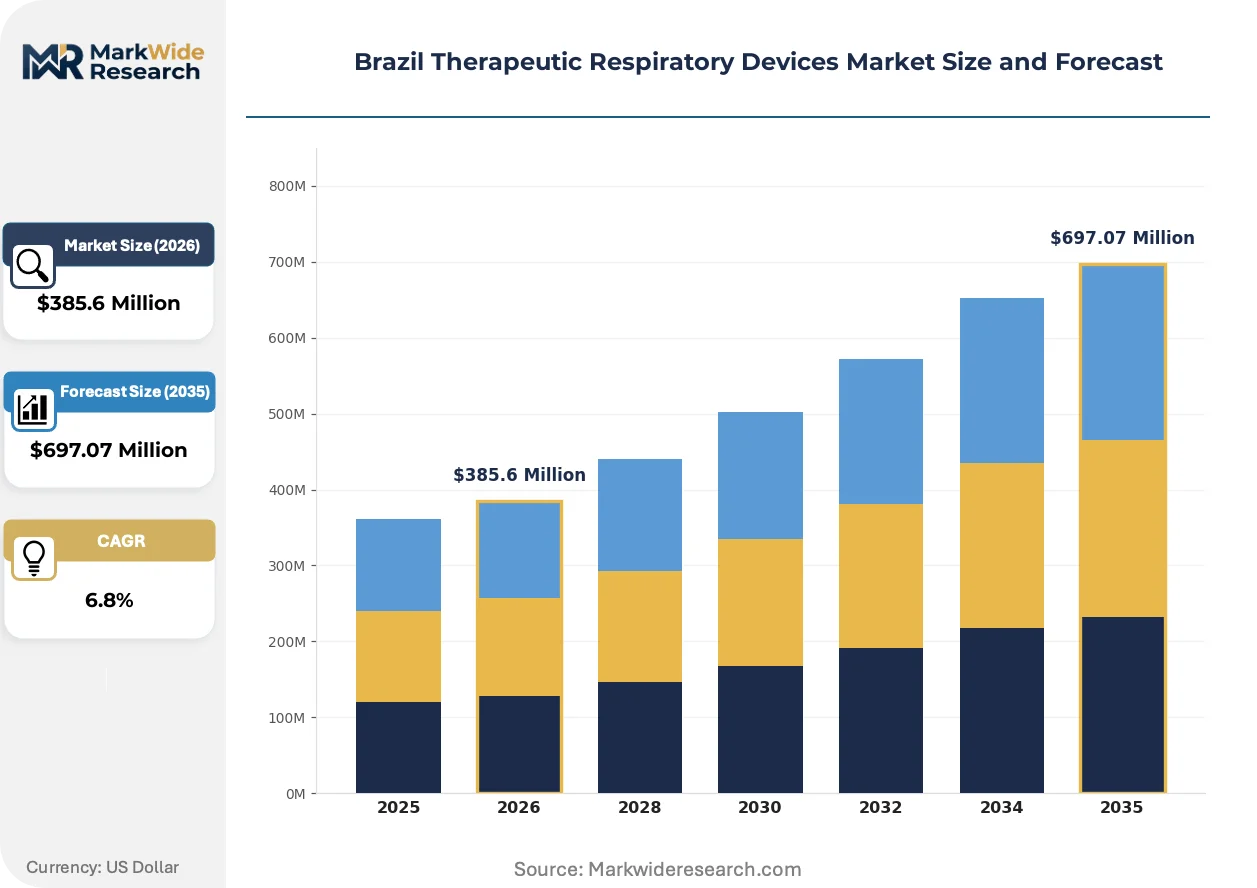
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Machines End User: Hospitals, Homecare, Rehabilitation Centers, Clinics Technology: Electromechanical, Manual, Digital, Hybrid Application: Asthma, COPD, Sleep Apnea, Cystic Fibrosis |
| Companies Covered | General Electric Company (GE HealthCare), Fisher & Paykel Healthcare Limited, Koninklijke Philips NV, Hamilton Medical, Masimo, Medtronic, Drägerwerk AG & Co. KGaA, BD (Becton, Dickinson and Company), ResMed Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Therapeutic Respiratory Devices Market Trends and Innovations
Digital respiratory ecosystems are reconfiguring how therapy adherence is measured, billed, and optimized across Brazilian care settings. Three converging developments are compressing traditional device economics.
Integrated pulse oximetry and airflow sensors with embedded machine learning algorithms enable real-time apnea-hypopnea index adjustment without manual titration. Sleep clinics in São Paulo and Curitiba are deploying these systems to reduce overnight technician staffing. Continuous autotitration is rendering obsolete the scheduled in-lab polysomnography follow-ups that previously dominated revenue models.
ANVISA's pending software-as-medical-device guidance will determine whether algorithm-driven diagnostic outputs require standalone registration or piggyback on hardware approvals. Manufacturers with existing Class III respiratory registrations are pre-positioning technical files to capture fast-track status. This regulatory evolution most directly affects startups developing cloud-based COPD exacerbation prediction tools.
Brazilian private health networks are unbundling device procurement from resupply logistics, awarding multi-year service contracts to third-party homecare specialists. Hospital purchasing departments now specify minimum adherence reporting thresholds rather than equipment brands. This contractual shift is most advanced in Minas Gerais, where respiratory therapy management companies have displaced traditional distributor relationships.
Brazil Therapeutic Respiratory Devices Market Segmentation
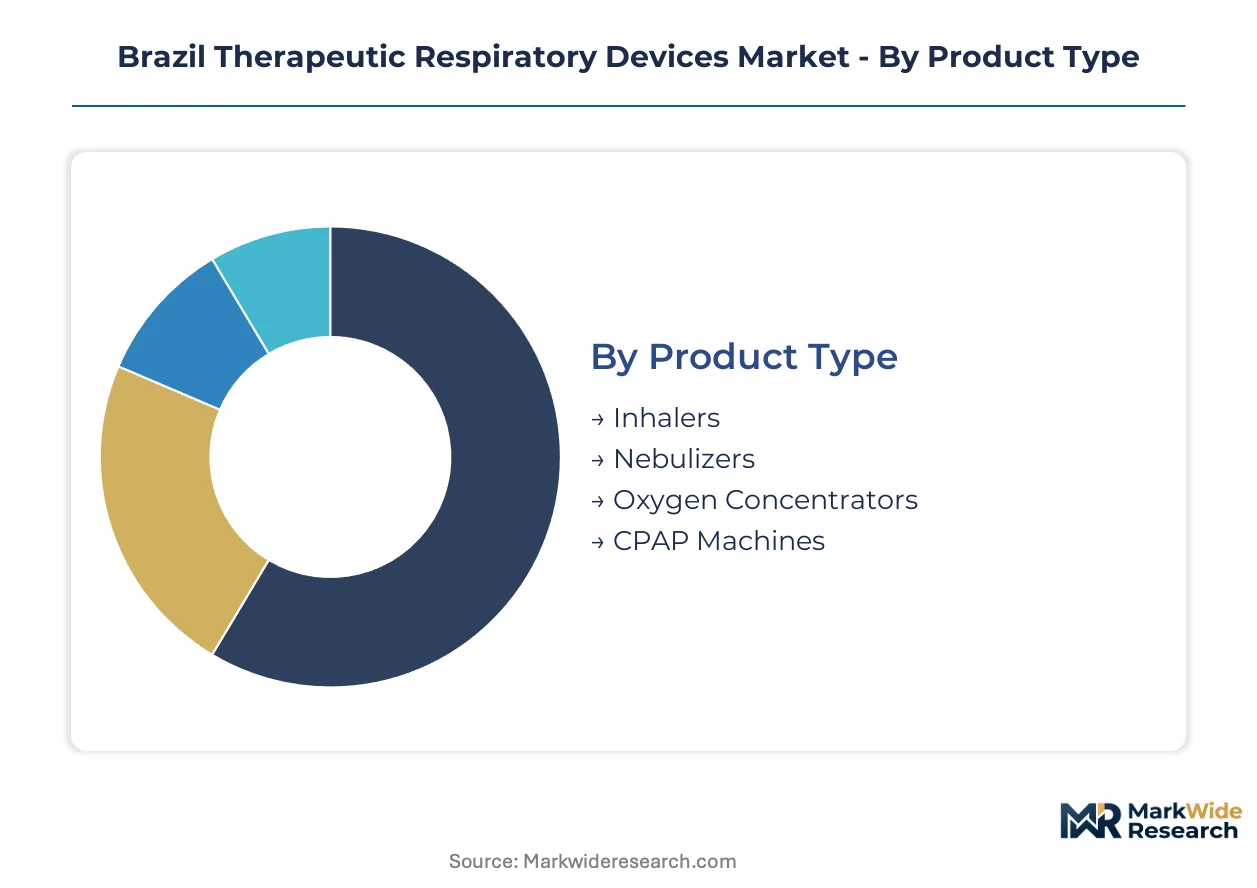
Brazil's therapeutic respiratory device landscape fragments across multiple technical and clinical dimensions, each commanding distinct procurement channels and regulatory pathways. Understanding these segment boundaries clarifies where ANVISA registration investments concentrate and which patient populations drive replacement cycles versus first-time penetration.
Product Type:
Oxygen concentrators and CPAP machines anchor opposite ends of the use-case spectrum — chronic domiciliary oxygen therapy versus episodic sleep-disordered breathing intervention — with diverging margin structures and service intensity requirements.
- Oxygen Concentrators:These electromechanical systems separate nitrogen from ambient air through pressure swing adsorption or membrane filtration, delivering continuous flow rates from 1-10 LPM. São Paulo's private hospital networks deploy portable units for same-day COPD discharge protocols, though stationary concentrators still dominate legacy installed bases in urban centers where power grid reliability supports 24-hour operation.
- CPAP Machines:Microprocessor-controlled blowers generate continuous positive airway pressure between 4-20 cm H2O through nasal or oronasal interfaces, with heated humidification and ramp functions standard. Brazilian private health insurance mandates now cover polysomnography, driving diagnostic clinic partnerships in Curitiba and Belo Horizonte that funnel patients toward auto-titrating devices with cellular adherence tracking.
- Inhalers:Pressurized metered-dose and dry-powder devices deliver bronchodilators and corticosteroids with particle sizes optimized for lower respiratory deposition. São Paulo state asthma programs procure these in volume through public tenders.
- Nebulizers:Jet, ultrasonic, and mesh technologies aerosolize liquid medications for patients unable to coordinate breath-actuated inhaler use. Pediatric and geriatric homecare applications concentrate demand in Minas Gerais.
Established volume favors oxygen concentrators; emerging adoption favors CPAP machines.
End User:
Procurement authority and reimbursement mechanics split distinctly across institutional purchasers versus patient-directed acquisition channels.
- Hospitals:Acute care facilities in São Paulo and Rio de Janeiro specify high-flow nasal cannula systems and invasive ventilation platforms for ICU respiratory failure management, with purchasing committees prioritizing ANVISA-registered suppliers with local technical service capabilities.
- Homecare:Domiciliary oxygen and sleep therapy patients increasingly lease rather than purchase devices, with third-party respiratory therapy management companies in Minas Gerais unbundling equipment provision from resupply logistics and adherence monitoring.
- Rehabilitation Centers:Post-acute facilities in southern Brazil integrate ventilator weaning protocols with high-flow nasal cannula step-down, creating pull-through for compatible heated humidifier systems.
- Clinics:Private pulmonology and sleep medicine practices in Curitiba function as diagnostic gatekeepers, directing patients toward specific device categories based on polysomnography or spirometry findings.
Institutional procurement concentrates in hospitals; margin expansion concentrates in homecare.
Technology:
Cost tier and regulatory classification diverge sharply between mechanical simplicity and algorithm-enabled automation.
- Digital:Cloud-connected platforms with embedded machine learning for autotitration and adherence prediction face ANVISA software-as-medical-device uncertainty, though manufacturers with existing Class III respiratory registrations pre-position technical files for fast-track status.
- Electromechanical:Microprocessor-controlled valves and flow sensors dominate oxygen concentrator and CPAP architectures, with pressure sensor supply concentrating in Southeast Asian manufacturing that exposes Brazilian assemblers to currency volatility.
- Manual:Basic inhaler actuation and simple jet nebulizer compression require no powered components, minimizing regulatory burden but limiting reimbursement rates in Brazilian public health programs.
- Hybrid:Systems combining mechanical aerosol generation with digital dose counters or Bluetooth connectivity occupy intermediate regulatory territory, with ANVISA classification pending on software functionality thresholds.
Regulatory clarity favors electromechanical; innovation investment favors digital.
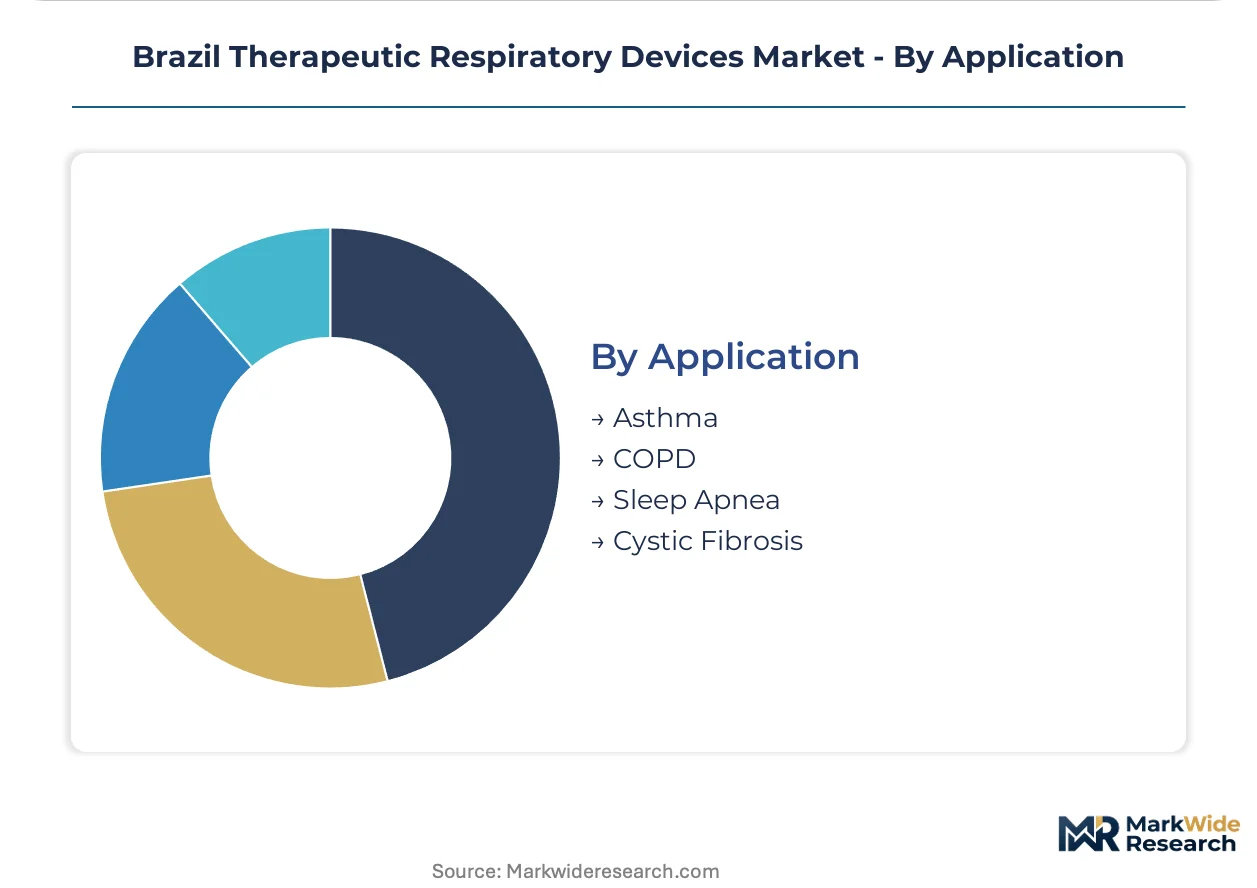
Application:
Disease prevalence and diagnostic infrastructure penetration determine addressable population and therapy reimbursement levels across Brazil's federated health system.
- COPD:Chronic obstructive pulmonary disease drives the largest installed base of oxygen concentrators and nebulizers, with São Paulo's aging population and historical smoking rates sustaining replacement demand despite stationary concentrator saturation in urban centers.
- Sleep Apnea:Obstructive sleep apnea diagnosis expansion through Brazilian private health networks generates the steepest expansion trajectory for CPAP and bilevel positive airway pressure devices, with subscription-style resupply models capturing recurring revenue beyond hardware margins.
- Asthma:Pediatric and adult allergic asthma populations absorb the majority of inhaler volumes, though generic medication substitution limits device premium capture in public sector procurement.
- Cystic Fibrosis:Small but high-acuity patient cohorts require specialized airway clearance devices and high-frequency chest wall oscillation systems, with care concentrating in referral centers in São Paulo and Rio de Janeiro.
Volume concentration sits with COPD; margin concentration sits with sleep apnea.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss ventilator manufacturers export precision-engineered respiratory platforms to Brazilian hospital networks, with São Paulo's private health infrastructure serving as the primary import destination for high-acuity critical care equipment.
São Paulo
São Paulo state concentrates Brazil's therapeutic respiratory device demand through private hospital networks and respiratory clinics that drive premium device procurement. ANVISA's updated medical device classification rules tighten quality requirements for imported respiratory equipment entering through this corridor. The São Paulo metropolitan area anchors homecare adoption as patients shift from institutional settings toward portable oxygen concentrators and CPAP machines.
Minas Gerais
Minas Gerais hosts advanced respiratory therapy management companies that unbundle equipment provision from resupply logistics and adherence monitoring. State-level procurement policies favor third-party homecare specialists over traditional distributor relationships. Belo Horizonte functions as a diagnostic gateway city where private pulmonology practices direct patients toward specific device categories based on polysomnography findings.
Rio de Janeiro
Rio de Janeiro's acute care facilities specify high-flow nasal cannula systems and invasive ventilation platforms for ICU respiratory failure management. ANVISA registration requirements favor suppliers with established Brazilian regulatory infrastructure and local technical service capabilities. The city faces acute shortages of biomedical engineering technicians qualified to service microprocessor-controlled ventilation systems outside warranty periods.
Paraná
Paraná's sleep medicine practices in Curitiba drive diagnostic clinic partnerships that funnel patients toward auto-titrating CPAP devices with cellular adherence tracking. Brazilian private health insurance mandates covering polysomnography generate steep expansion trajectories for positive airway pressure equipment. The Curitiba cluster exemplifies how continuous autotitration systems reduce overnight technician staffing requirements in sleep clinics.
Rio Grande do Sul
Rio Grande do Sul's post-acute rehabilitation facilities integrate ventilator weaning protocols with high-flow nasal cannula step-down, creating pull-through for compatible heated humidifier systems. Regional purchasing committees prioritize ANVISA-registered suppliers capable of navigating adverse-event reporting obligations. Porto Alegre's private health networks specify minimum adherence reporting thresholds rather than equipment brands in multi-year service contracts.
Brazil Therapeutic Respiratory Devices Market Competitive Landscape
On the supply side, the industry is structured around three tiers: multinational healthcare conglomerates with full respiratory portfolios, specialized ventilation and sleep therapy firms, and regional distributors with regulatory navigation capabilities. Strategic archetypes include integrated device-and-service providers, technology-focused humidification specialists, and direct-to-patient digital platform operators. Dominant competitive moves center on leasing model expansion that bundles device provision with remote monitoring, and partnerships with Brazilian distributors capable of managing ANVISA inspection protocols.
Within the integrated healthcare technology tier, Koninklijke Philips NV and General Electric Company represent archetypes of conglomerate-scale players with established Brazilian regulatory infrastructure. Fisher & Paykel Healthcare Limited occupies a position exemplifying specialized technology leadership, while ResMed Inc. anchors the direct-to-patient digital platform segment. These three firms collectively illustrate how ANVISA's tightened Class III registration requirements extend import timelines and favor incumbents with localized quality management systems already in place.
| Leading Market Players |
|---|
| General Electric Company (GE HealthCare) |
| Fisher & Paykel Healthcare Limited |
| Koninklijke Philips NV |
| Hamilton Medical |
| Masimo |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| BD (Becton, Dickinson and Company) |
| ResMed Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Southeast Asian pressure sensor fabrication is compressing margin structures for Brazilian oxygen concentrator assemblers while simultaneously elevating procurement premiums for ANVISA-registered Class III device suppliers with established local technical service networks.
Pricing Analysis
Current-generation auto-titrating CPAP devices with embedded cellular modems command substantial premiums over prior-generation machines lacking cloud connectivity, while next-generation AI-enabled diagnostic platforms face pricing paralysis pending ANVISA software-as-medical-device classification clarity. Three-tier pricing structure across premium, standard, and economy levels stratifies by ANVISA registration tier and after-sales bundling intensity. Cost compression in the standard tier is intensifying because Brazilian private health networks now specify minimum adherence reporting thresholds rather than equipment brands. Public sector procurement through São Paulo state tenders exhibits the highest price sensitivity, whereas sleep clinic direct-to-patient channels absorb premium markups for remote monitoring integration.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk calculations for microprocessor-controlled valves and lithium-ion battery packs that power portable oxygen concentrators. Manufacturing concentration in China, Vietnam, and Malaysia for pressure sensors, flow meters, and filtration media leaves Brazilian assemblers vulnerable to currency volatility and extended lead times. Component sourcing draws from Southeast Asian electronics clusters and German precision engineering hubs for high-acuity ventilation platforms. Single-source vulnerability concentrates in semiconductor-dependent control boards. Distribution runs through São Paulo-based medical device distributors with ANVISA regulatory navigation capabilities, though Minas Gerais respiratory therapy management companies are displacing traditional channel relationships with direct homecare logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's therapeutic respiratory device market requires substitution defense against low-cost portable oxygen concentrator imports from unregistered suppliers that bypass ANVISA quality requirements and undercut established pricing floors.
For Market Incumbents: Build regulatory moat through preemptive ANVISA software-as-medical-device technical file submissions that capture fast-track status for AI-enabled diagnostics before classification guidance finalizes. Deepen backward integration into humidification technology manufacturing to differentiate high-flow nasal cannula systems from commodity competitors. Channel control through exclusive respiratory therapy management partnerships in Minas Gerais and São Paulo defends margin pools against direct-to-patient digital platforms. For New Entrants and Emerging Players: Build out solar-compatible portable concentrator distribution networks targeting Amazon basin riverine communities where hospital access constraints create unserved demand for telemedicine-linked domiciliary oxygen therapy. White-space concentration sits with pediatric cystic fibrosis airway clearance devices in Rio de Janeiro and São Paulo referral centers. Go-to-market execution should anchor in diagnostic clinic partnerships that funnel polysomnography-confirmed sleep apnea patients toward bundled device-and-monitoring subscriptions. For Investors and Strategic Acquirers: Capital is best deployed toward respiratory therapy management companies with established ANVISA adverse-event reporting infrastructure and multi-year service contracts with Brazilian private health networks. Long-term viability across the projection horizon hinges on recurring revenue capture through adherence monitoring platforms rather than transactional device margins. Acquisition target archetype: regional distributors with dormant Class III registration capabilities awaiting activation. Watch ANVISA software-as-medical-device guidance publication as the inflection signal for algorithm-driven diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Software-as-Medical-Device Pre-Positioning | Fast-track classification capture ahead of AI diagnostic guidance finalization secures competitive entry timing. |
| Homecare Service Network Expansion | Third-party respiratory therapy management contracts in Minas Gerais displace traditional distributor economics. |
| Remote Monitoring Platform Integration | Cellular-connected adherence tracking transforms device sales into recurring subscription revenue streams. |
| Humidification Technology Backward Integration | In-house heated humidifier production protects margin pools in high-flow nasal cannula system sales. |
| Amazon Basin Domiciliary Penetration | Solar-compatible portable concentrators with telemedicine linkage address unserved riverine community demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA medical device registration databases, hospital procurement records from São Paulo state health secretariats, and Brazilian private health insurance reimbursement schedules. Primary interviews engaged biomedical engineering directors at private hospital networks, respiratory therapy management company executives, ANVISA regulatory affairs consultants, and pulmonology clinic purchasing coordinators. Secondary validation drew from MERCOSUR technical standards harmonization documents, GPO contract disclosures, and customs import data for respiratory device components. Bottom-up installed base estimates and top-down reimbursement flow analysis were triangulated to anchor volume projections.
Forecast inputs span product type segmentation across oxygen concentrators, CPAP machines, inhalers, and nebulizers; end-user channels including hospitals, homecare, rehabilitation centers, and diagnostic clinics; and technology tiers from manual actuation through cloud-connected algorithmic platforms. CAGRs were derived from patient population epidemiology, diagnostic infrastructure expansion trajectories, and reimbursement policy evolution across the analysis window. Industry-specific modeling incorporated ANVISA registration pipeline velocity, sleep apnea diagnosis rates through private insurance mandates, and portable oxygen concentrator battery chemistry improvement curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unregistered low-cost concentrator importers or preemptive AI diagnostic platform launches by multinational healthcare conglomerates would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Global Hypoxia Treatment Market