
 Nicotine De-Addiction Products Market | 2026-2036
Nicotine De-Addiction Products Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotine De-Addiction Products Market Analysis
Modular dosing kits that combine patches with behavioral coaching apps is realigning how employers and health systems purchase cessation programs. Johnson & Johnson leverages its consumer health infrastructure to sustain pharmacy shelf presence across multiple continents. Pfizer Inc. anchors its position through prescription-grade varenicline formulations that differentiate it from over-the-counter competitors. GlaxoSmithKline Plc specializes in gum and lozenge formats that dominate European retail channels.
Nicotine de-addiction products encompass pharmacological and therapeutic interventions designed to reduce dependence on nicotine through controlled delivery or receptor modulation, typically formulated as transdermal patches releasing 7-21 mg of nicotine over 24 hours or as polacrilex gum providing 2-4 mg per piece to manage withdrawal symptoms. These products serve clinical and commercial purposes by lowering relapse rates among tobacco users undergoing cessation protocols. Transdermal patches occupy the largest revenue share among delivery methods due to sustained plasma levels and patient compliance advantages. Oral formulations including gum and lozenges represent the fastest-expanding category as convenience-store distribution and private-label competition intensify. Prescription medications command premium pricing pools where physician oversight and insurance reimbursement create higher barriers to entry than over-the-counter alternatives.
FDA oversight of nicotine labeling and child-resistant packaging shapes product design requirements for all manufacturers seeking US market access, while EMA pharmacovigilance frameworks govern adverse-event reporting thresholds across European member states. REACH chemical registration mandates affect nicotine sourcing transparency for firms importing active pharmaceutical ingredients into the European Union. India's CDSCO and BIS standards create parallel compliance tracks for generic manufacturers such as Dr. Reddy's Laboratories and Cipla exporting to regulated markets. Stakeholders must monitor evolving reimbursement criteria from national health technology assessment bodies, as coverage decisions for combination therapy protocols will determine which formulation categories achieve scalable adoption.
Market Dynamics
Employer-sponsored cessation programs are restructuring procurement toward bundled behavioral-pharmacological solutions, compressing standalone product margins while elevating integrated service contracts.
Growth Catalysts
- Workplace wellness mandates:Large North American employers now bundle nicotine cessation with chronic disease management, creating institutional demand channels that bypass retail pharmacy distribution.
- EMA pharmacovigilance harmonization:Standardized adverse-event reporting across EU member states accelerates cross-border product registration, reducing time-to-market for patch and gum formulations.
- Transdermal polymer advances:New adhesive chemistries extend wear time to 24 hours, improving patient compliance metrics that determine formulary placement in health system purchasing.
Market Restraints
- Nicotine API concentration:Active pharmaceutical ingredient production clusters in India and China, creating single-source dependency risks for European and North American finished goods manufacturers.
- REACH registration costs:ECHA compliance expenses for novel nicotine salt formulations exceed €200,000 per substance, blocking mid-tier entrants from European commercialization.
- Heat-not-burn substitution:Tobacco industry heated aerosol products capture price-sensitive smokers who might otherwise initiate NRT protocols, eroding the addressable cessation population.
Strategic Opportunities
- Germany reimbursement expansion:Statutory health insurance now covers combination therapy (patch plus behavioral app), opening premium-priced bundled service models previously restricted to private payers.
- Digital therapeutic convergence:Prescription-grade software delivering cognitive behavioral therapy alongside pharmacological intervention qualifies for FDA breakthrough device designation, creating new reimbursement codes.
- Convenience store private label:Retailers in Canada and the United Kingdom are launching store-brand lozenges at 40% price discounts to branded equivalents, capturing switchers from higher-margin gum formats.
Industry Challenges
- Behavioral health integration:Manufacturers lack in-house clinical psychology expertise to design evidence-based coaching protocols that meet health technology assessment standards in France and the United Kingdom.
- Child-resistant packaging redesign:FDA's updated Poison Prevention Packaging Act requirements force reformulation of blister packs and bottles, triggering 18-month recertification timelines for existing stock-keeping units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotine De-Addiction Products Market |
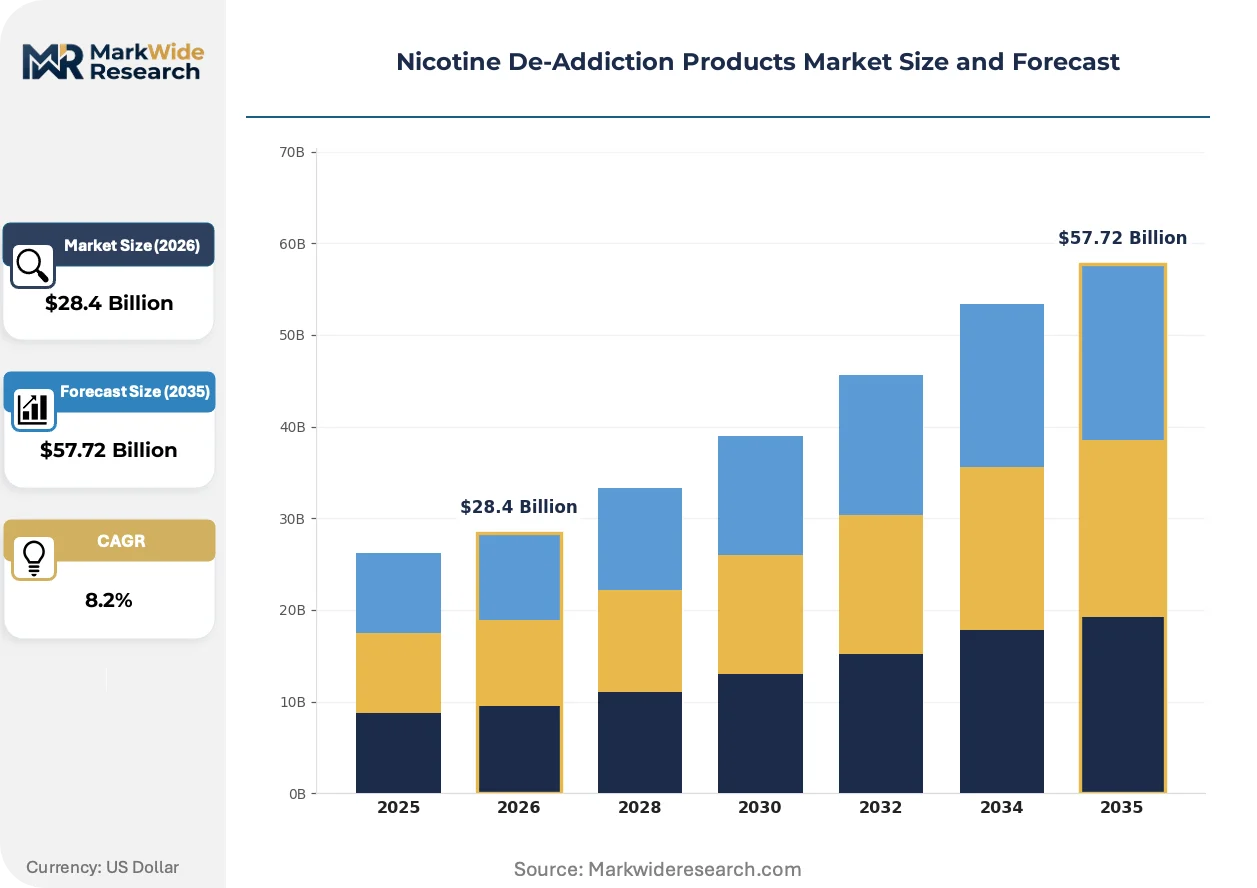
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gum, Patch, Inhaler, Lozenges Formulation: Nicotine Replacement, Prescription Medications, Behavioral Therapy, Alternative Therapies Delivery Method: Transdermal, Oral, Inhalation, Injectable Consumer Type: Adult Smokers, Young Adults, Pregnant Women, Heavy Smokers |
| Companies Covered | GlaxoSmithKline Plc, Pfizer Inc., Johnson & Johnson, British American Tobacco Plc, Imperial Brands Plc, Perrigo Company Plc, Dr. Reddy’s Laboratories Ltd, Cipla Ltd, Haleon Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotine De-Addiction Products Market Emerging Trajectories
Digital biomarkers and real-time adherence monitoring are displacing static dosing protocols, enabling dynamic nicotine tapering algorithms that adjust to individual withdrawal trajectories.
Smart transdermal patches incorporating Bluetooth-enabled sensors is converging with mobile health platforms to transmit plasma nicotine estimates and craving intensity scores directly to prescribing physicians. Large self-insured employers in the United States are piloting these connected devices for remote therapeutic monitoring. The data streams enable outcome-based contracting where manufacturers share financial risk for relapse events.
REACH Annex XVII restrictions on skin-sensitizing adhesive compounds are forcing reformulation of extended-wear patches across European manufacturing facilities. The regulatory pressure accelerates migration to silicone-based adhesives previously reserved for premium hospital-grade applications. German and Dutch contract manufacturers are investing in cleanroom coating capacity to serve this compliance-driven specification upgrade.
Direct-to-patient subscription models are bypassing traditional pharmacy distribution for maintenance-phase cessation support. Smokers completing initial 12-week protocols now receive automated refill shipments of tapering-dose gum paired with app-based counseling. The channel shift concentrates in the United Kingdom and Australia where postal pharmacy regulations permit remote prescribing by cessation specialists.
Nicotine De-Addiction Products Market Segmentation
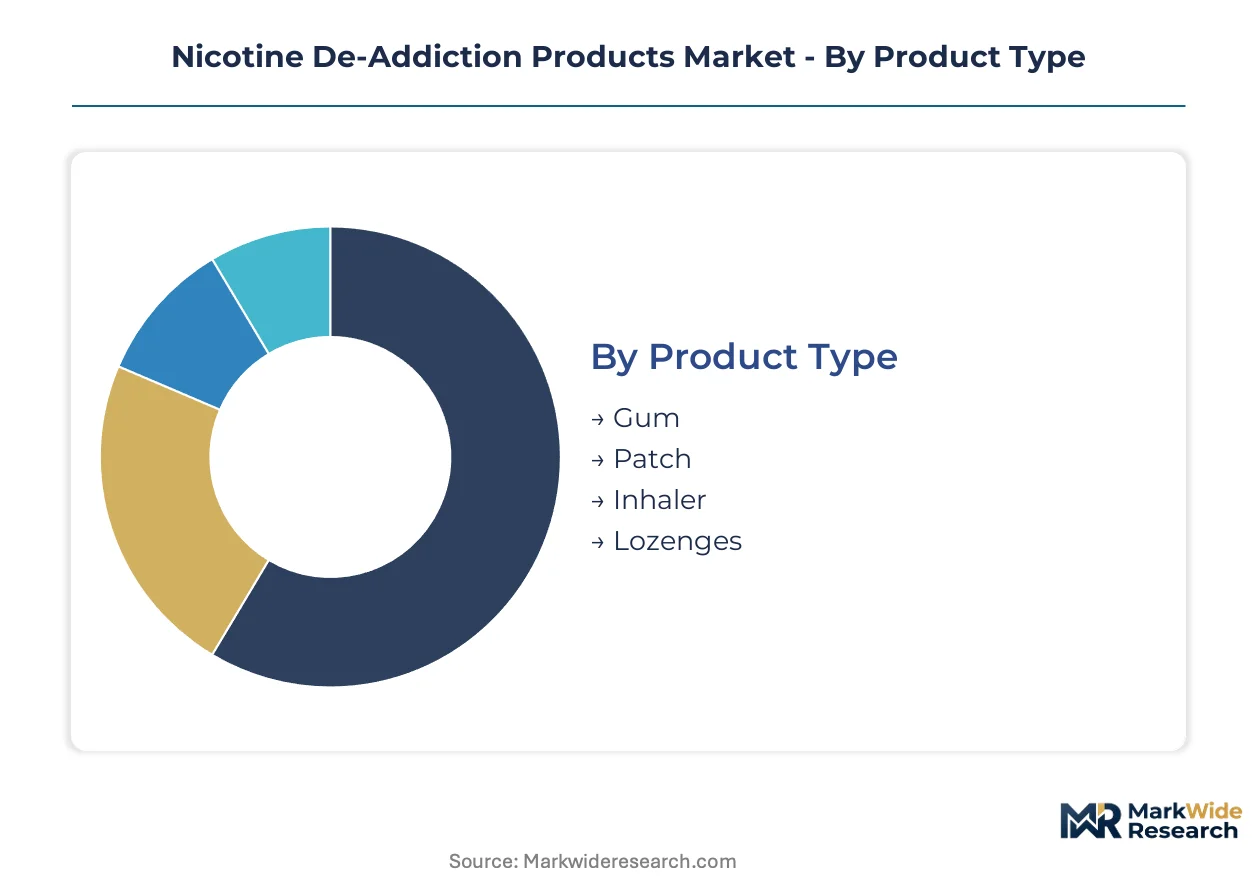
Segmentation in nicotine de-addiction products reveals how formulation science, delivery mechanics, and patient risk profiles determine reimbursement pathways and procurement decisions across health systems and retail channels.
Product Type:
Volume leaders command pharmacy shelf space while convenience formats capture impulse-driven switching behavior.
- Patch:Transdermal systems delivering 7-21 mg nicotine over 24 hours through polymer adhesive matrices. Demand concentrates in Germany where statutory health insurance reimbursement for combination therapy has expanded patient access beyond private payers. FDA child-resistant packaging mandates drive 18-month recertification cycles for existing stock-keeping units.
- Gum:Polacrilex-based chewable delivering 2-4 mg per piece with buccal absorption kinetics. Convenience-store distribution in Canada and the United Kingdom intensifies as retailers launch private-label variants at 40% discounts to branded equivalents, compressing margin structures.
- Inhaler:Cartridge-based vaporization systems mimicking hand-to-mouth behavioral rituals. Workplace wellness programs in US corporations pilot these for behavioral substitution protocols.
- Lozenges:Slow-dissolving oral matrices for craving management without chewing mechanics. Australian postal pharmacy regulations enable direct-to-patient subscription models bypassing traditional retail.
Today's leader: Patch. Tomorrow's challenger: Lozenges.
Formulation:
Prescription-grade modalities extract premium pricing through physician gatekeeping while over-the-counter channels optimize volume throughput.
- Nicotine Replacement:Controlled-dose pharmacological interventions including transdermal, oral, and inhalation delivery. REACH Annex XVII restrictions on skin-sensitizing adhesives force silicone-based reformulation across European manufacturing.
- Prescription Medications:Varenicline and bupropion formulations requiring physician oversight and insurance preauthorization. EMA pharmacovigilance harmonization accelerates cross-border registration, reducing time-to-market.
- Behavioral Therapy:Cognitive behavioral protocols delivered through app-based coaching and telehealth counseling. FDA breakthrough device designation for prescription-grade software creates new reimbursement codes in US markets.
- Alternative Therapies:Acupuncture, hypnotherapy, and herbal supplementation outside pharmacological pathways. India's CDSCO and BIS standards create parallel compliance tracks for manufacturers exporting to regulated markets.
Prescription Medications currently dominate revenue pools; Behavioral Therapy is gaining share fastest through digital therapeutic convergence.
Delivery Method:
Patient compliance metrics determine formulary placement, with sustained plasma levels outperforming episodic dosing in health system purchasing.
- Transdermal:Adhesive patches providing steady-state nicotine levels without dosing frequency demands. New polymer chemistries extending wear time to 24 hours improve compliance metrics that influence health technology assessment outcomes.
- Oral:Gum and lozenge formats enabling patient-controlled dosing in response to acute cravings. German and Dutch contract manufacturers invest in cleanroom coating capacity for silicone-adhesive migration.
- Inhalation:Aerosolized delivery mimicking pulmonary nicotine absorption from combustible cigarettes. Heat-not-burn tobacco products capture price-sensitive smokers who might otherwise initiate NRT protocols.
- Injectable:Subcutaneous depot formulations for severe dependence cases under clinical supervision. Limited distribution through specialized cessation clinics in France and the United Kingdom.
Transdermal maintains the largest revenue share; Oral formats are expanding most quickly through convenience retail penetration.
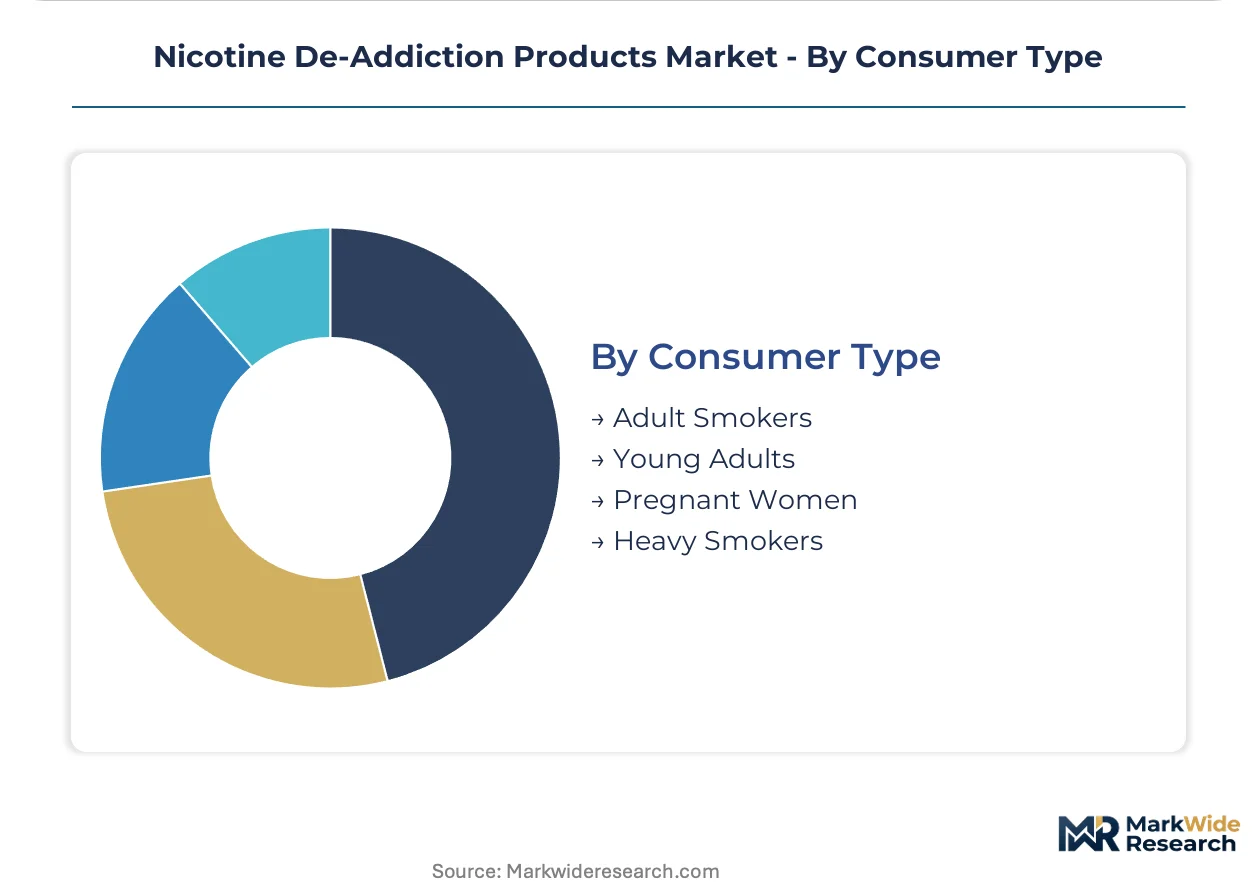
Consumer Type:
Risk stratification determines intervention intensity, with heavy dependence profiles justifying combination therapy reimbursement.
- Heavy Smokers:Patients consuming 20+ cigarettes daily requiring high-dose initiation protocols and extended tapering schedules. Employer-sponsored programs in North America bundle pharmacological and behavioral interventions for this cohort.
- Adult Smokers:General population tobacco users aged 25-64 representing baseline demand for over-the-counter cessation aids. India's generic manufacturers serve price-sensitive segments through export channels.
- Young Adults:18-24 demographic with shorter dependence histories and higher digital engagement. Mobile health platforms and Bluetooth-enabled patches target remote therapeutic monitoring for this group.
- Pregnant Women:High-risk population requiring non-pharmacological first-line protocols due to teratogenic concerns. Specialized prenatal cessation programs in Australia and Canada prioritize behavioral interventions.
Adult Smokers anchor current volume; Heavy Smokers represent the steepest expansion trajectory as combination therapy gains reimbursement traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nicotine de-addiction products industry traces its commercial origins to transdermal patch development in the United States during the 1980s, with subsequent regulatory harmonization spreading formulation standards across European and Asia-Pacific markets. Market development now reflects divergent reimbursement architectures and tobacco control intensities across major economies.
United States
Large self-insured employers pilot Bluetooth-enabled patches for remote therapeutic monitoring, creating outcome-based contracting channels. FDA child-resistant packaging mandates under the Poison Prevention Packaging Act trigger 18-month recertification cycles for existing stock-keeping units. Workplace wellness programs in Texas and California corporations bundle pharmacological and behavioral interventions, bypassing traditional retail pharmacy distribution.
Germany
Statutory health insurance reimbursement for combination therapy has broadened patient access beyond private payers, anchoring European demand. EMA pharmacovigilance harmonization accelerates cross-border product registration for patch and gum formulations. Contract manufacturers in North Rhine-Westphalia invest in cleanroom coating capacity for silicone-adhesive migration driven by REACH Annex XVII restrictions.
United Kingdom
Postal pharmacy regulations enable direct-to-patient subscription models for maintenance-phase cessation support, concentrating channel shift in England and Scotland. Retailers launch private-label lozenges at 40% price discounts to branded equivalents, compressing margin structures. The Medicines and Healthcare products Regulatory Agency oversees adverse-event reporting thresholds for combination therapy protocols.
India
Generic manufacturers export nicotine replacement formulations to regulated markets through parallel compliance tracks established by CDSCO and BIS standards. Active pharmaceutical ingredient production clusters in Hyderabad and Mumbai create single-source dependency risks for European and North American finished goods manufacturers. Price-sensitive segments drive volume throughput for gum and lozenge formats.
Australia
Prenatal cessation programs prioritize behavioral interventions for pregnant women, creating specialized demand channels outside pharmacological pathways. TGA oversight governs product registration timelines for transdermal and oral formulations. Direct-to-patient subscription models bypass traditional pharmacy distribution, with automated refill shipments paired with app-based counseling gaining traction in New South Wales and Victoria.
Nicotine De-Addiction Products Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reimbursement access and formulation complexity. The market structures around three tiers: multinational pharmaceutical conglomerates with prescription-grade portfolios, consumer health specialists with over-the-counter retail presence, and generic manufacturers serving price-sensitive export markets. Strategic archetypes include integrated behavioral-pharmacological service providers, pure-play nicotine replacement formulators, and API-to-finished-goods vertical consolidators. Dominant competitive moves encompass portfolio diversification into digital therapeutics and geographic expansion through regulatory harmonization leverage.
Within the multinational pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions defined by prescription infrastructure and consumer health distribution respectively. GlaxoSmithKline Plc exemplifies the over-the-counter specialist archetype through its European retail channel dominance. Among generic manufacturers, Dr. Reddy's Laboratories Ltd and Cipla Ltd represent the API-forward export model serving regulated markets from Indian production bases. British American Tobacco Plc and Imperial Brands Plc sit within a contested positioning, leveraging combustible tobacco distribution networks while diversifying into reduced-risk nicotine delivery. Haleon Plc and Perrigo Company Plc anchor the consumer health pure-play segment.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| Pfizer Inc. |
| Johnson & Johnson |
| British American Tobacco Plc |
| Imperial Brands Plc |
| Perrigo Company Plc |
| Dr. Reddy's Laboratories Ltd |
| Cipla Ltd |
| Haleon Plc |
| Others |
Supply Flow & Price Mechanics
Prescription-grade varenicline and behavioral app bundles command 3-4x premiums over private-label gum formats, a bifurcation that concentrates manufacturing investment in FDA-registered facilities while relegating commodity production to contract manufacturers in India and China. REACH registration costs exceeding €200,000 per novel nicotine salt formulation erect barriers that preserve margin structures for incumbents with established EMA dossiers, even as convenience-store distribution erodes pricing power at the economy tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with prescription medications and connected patches extracting value through physician gatekeeping and remote monitoring capabilities while private-label lozenges compete on shelf price. Price differentiation rests on FDA breakthrough device designation for digital therapeutics and silicone-adhesive compliance with REACH Annex XVII. Cost compression in oral formats intensifies as Canadian and British retailers launch store-brand variants at 40% discounts. Heavy smokers enrolled in employer-sponsored programs exhibit lowest price sensitivity; young adults purchasing convenience-store gum show highest.
Supply Chain Analysis
Freight cost volatility from Indian and Chinese API clusters to European and North American finished goods manufacturers has prompted inventory repositioning near formulation facilities in Germany and the Netherlands. Active pharmaceutical ingredient production concentrates in Hyderabad and Mumbai, with polymer adhesive matrices for transdermal patches sourcing from German and Dutch cleanroom coating operations. Single-source dependency risk looms where nicotine API supply rests on concentrated South Asian manufacturing. Distribution runs through pharmacy retail, direct-to-patient postal pharmacy, and workplace wellness procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement expansion in Germany signals demand migration toward premium bundled interventions that combine pharmacological and behavioral specifications.
For Market Incumbents: Cement formulary placement through silicone-adhesive reformulation investments that anticipate REACH Annex XVII enforcement timelines. Deepen backward integration into nicotine API production to offset single-source concentration in Indian manufacturing clusters. Defend against heat-not-burn substitution by accelerating FDA breakthrough device designation for connected patch platforms that enable outcome-based contracting with self-insured employers.
For New Entrants and Emerging Players: Bluetooth-enabled sensor integration for real-time adherence monitoring offers the most penetrable wedge against established patch manufacturers lacking digital infrastructure. Target direct-to-patient subscription models in Australia and the United Kingdom where postal pharmacy regulations permit remote prescribing bypass. Lead with app-based cognitive behavioral therapy modules that qualify for prescription-grade software reimbursement codes.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier generic manufacturers face REACH registration cost barriers blocking European commercialization. Long-term viability favors API-to-finished-goods vertical consolidators with cleanroom coating capacity and EMA pharmacovigilance infrastructure. Watch for inflection signals in German statutory health insurance reimbursement decisions for combination therapy protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Adhesive Reformulation | REACH Annex XVII compliance secures European manufacturing continuity for extended-wear patches. |
| Digital Therapeutic Convergence | FDA breakthrough device designation unlocks prescription-grade reimbursement for app-based behavioral coaching. |
| API Vertical Consolidation | Captive nicotine supply reduces single-source dependency exposure from Indian manufacturing clusters. |
| Workplace Wellness Partnership | Employer-sponsored procurement channels bypass retail pharmacy margin compression. |
| Direct-to-Patient Subscription | Postal pharmacy regulations in Australia and Britain enable automated refill shipments with app counseling. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with regulatory affairs leads at multinational pharmaceutical firms, formulary directors at German statutory health insurers, and procurement managers at self-insured US employers. Secondary validation draws from FDA 510(k) filings, EMA pharmacovigilance databases, ClinicalTrials.gov cessation intervention records, and REACH Annex XVII substance restriction updates. Bottom-up patient population modeling and top-down health expenditure triangulation anchor volume and value estimates.
Rate-of-change decomposition across the analysis window segments demand by product type, formulation complexity, delivery method mechanics, and consumer dependence severity. CAGRs derive from modeled adoption curves for connected patches, reimbursement expansion scenarios in Germany, and substitution effects from heat-not-burn tobacco products. Forecast inputs include employer wellness program penetration rates, EMA harmonization timelines for cross-border registration, and polymer chemistry advancement cycles.
The model holds under stable regulatory reimbursement conditions; deviation in FDA digital therapeutic designation criteria or German statutory insurance coverage decisions would shift growth trajectories. Forecasts reflect assumptions about silicone-adhesive migration timelines and workplace wellness procurement acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Methadone Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Opioid Induced Constipation Treatment Market