
 Respiratory Trainer Market | 2026-2036
Respiratory Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Trainer Market Analytics
Home care settings are rotating toward electronic and mobile app-enabled respiratory trainers as post-acute care shifts outside institutional walls. Koninklijke Philips N.V. leverages its sleep and respiratory therapy infrastructure to dominate connected home delivery systems. POWERbreathe International Limited specializes in pressure-threshold inspiratory muscle trainers for athletic and clinical segments. Medline Industries, Inc. anchors hospital and clinic procurement through extensive distribution networks across North America.
A respiratory trainer is a mechanical or electronic device designed to strengthen inspiratory and expiratory muscles through calibrated resistance, typically adjustable between 10-150 cmH₂O depending on patient capacity and rehabilitation stage. These devices serve to improve lung function, reduce dyspnea, and accelerate recovery following surgery or chronic respiratory illness. Inhalers and electronic delivery modes command the deepest margin pools as digital connectivity enables remote monitoring and subscription-style adherence programs. Peak flow meters retain stable volume in pediatric asthma management but face substitution by integrated electronic coaches in adult populations.
FDA 510(k) clearance and ISO 13485 certification shape product development timelines and international market access for device manufacturers. The EU Medical Device Regulation imposes additional clinical evidence requirements on electronic trainers with diagnostic claims. Stakeholders must monitor reimbursement code evolution for remote respiratory monitoring as payers recalibrate home-based chronic disease management policies.
Market Dynamics
Post-acute care decentralization is compressing device procurement cycles as hospitals discharge patients earlier into monitored home environments, forcing manufacturers to revalidate products for unsupervised use and remote data transmission.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited review for predicate-based respiratory trainers accelerates commercialization timelines for incremental hardware improvements, reducing regulatory capital requirements for mid-tier manufacturers.
- Home care infrastructure:Medicare reimbursement expansion for remote patient monitoring creates direct revenue channels outside institutional purchasing, pulling device deployment into domestic settings.
- Pressure-threshold calibration advances:Microelectromechanical sensors enable real-time resistance adjustment, extending therapeutic utility from elite athletic conditioning to post-surgical pulmonary rehabilitation.
Market Restraints
- Semiconductor input volatility:MEMS pressure sensor supply concentrates in Taiwan and South Korea foundries, exposing production schedules to geopolitical disruption and foundry allocation constraints.
- EU MDR clinical evidence escalation:Electronic trainers with diagnostic claims now require prospective studies under Medical Device Regulation, extending validation timelines and freezing marginal product variants.
- Peak flow meter substitution:Integrated smartphone spirometry applications eliminate standalone mechanical devices from adult asthma management protocols, eroding legacy revenue pools.
Strategic Opportunities
- Germany DiGA fast-track:Digital Health Applications approval pathway reimburses app-connected trainers through statutory health insurance, creating precedent for software-enabled device monetization.
- Pediatric gamification:Breath-controlled mobile games convert compliance monitoring into engagement mechanics, opening adherence-program subscription models for cystic fibrosis and asthma cohorts.
- Japan METI Silver ICT:Subsidized procurement of home medical devices for aging-in-place initiatives funds respiratory trainer deployment through municipal long-term care insurance.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints delay quality management system audits, freezing manufacturing transfers and new facility qualifications.
- Legacy EMR integration friction:Proprietary data formats from connected trainers require custom HL7 FHIR mapping for hospital information system compatibility, inflating implementation costs.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face contracted laboratory queue times exceeding twelve months for novel polymer mouthpiece materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Trainer Market |
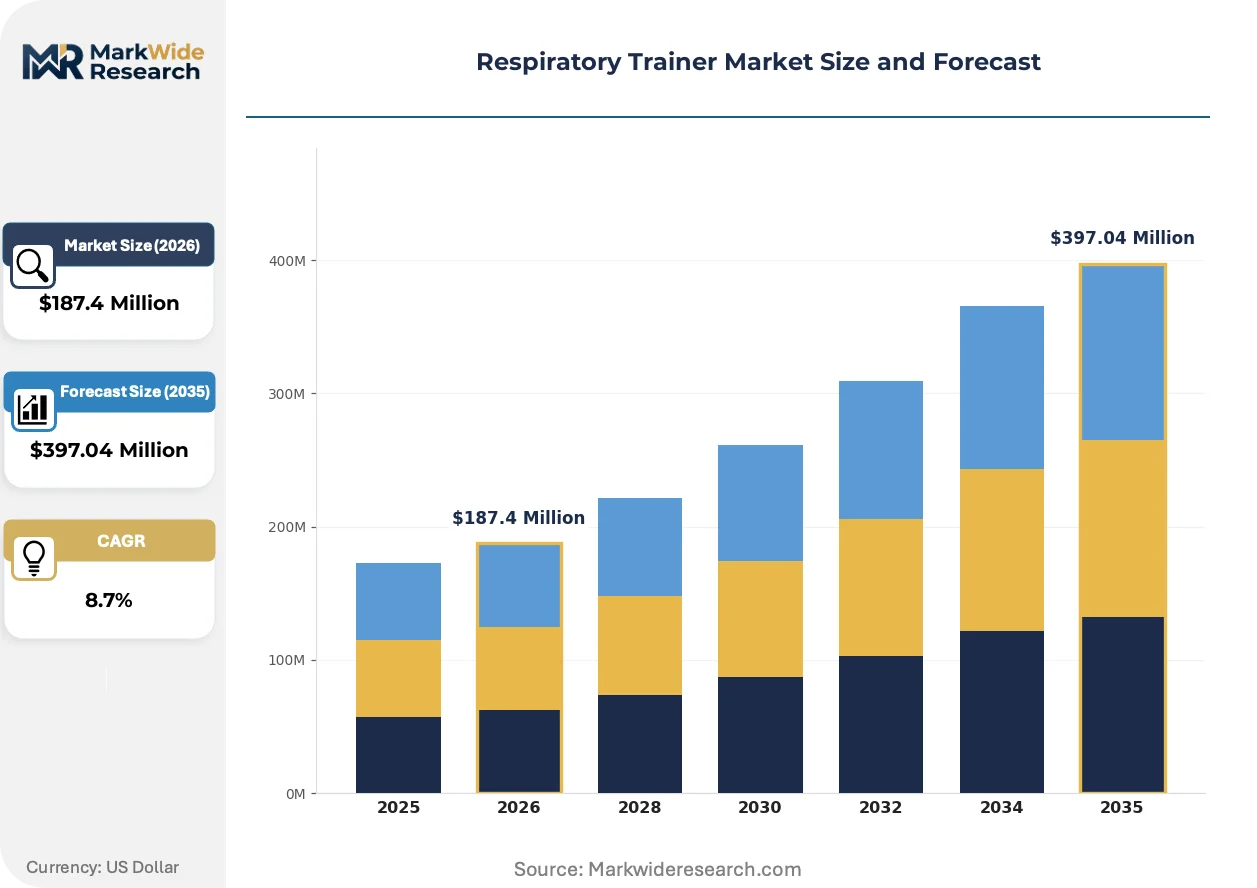
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Peak Flow Meters, Coaches Therapy Area: Asthma, COPD, Cystic Fibrosis, Lung Rehabilitation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Manual, Electronic, Mobile App, Remote Monitoring |
| Companies Covered | Vyaire Medical, Inc., POWERbreathe International Limited, Medline Industries, Inc., PN Medical, Airofit, Koninklijke Philips N.V., IngMar Medical, Besmed Health Business Corp, Smiths Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Trainer Market Evolving Landscape
Connected respiratory hardware is converging with software-enabled care delivery, transforming standalone mechanical devices into data-generating nodes within distributed chronic disease management networks.
Cloud-resident pulmonary function algorithms are displacing bedside diagnostic interpretation, enabling automated severity stratification without specialist consultation. Pulmonology departments at academic medical centers in the United States and Germany are deploying these systems to extend monitoring capacity across dispersed patient populations. The shift compresses clinical labor requirements while expanding addressable patient volumes beyond traditional clinic capacity constraints.
EU Medical Device Regulation Annex XVI expansion reclassifies certain software-enabled trainers with diagnostic outputs as Class IIa or IIb devices, mandating notified body intervention for products previously self-certified under the Medical Devices Directive. Manufacturers with predicate devices grandfathered under MDD face sunset deadlines forcing technical file reconstruction and clinical evaluation report updates. German and French notified bodies report eighteen-month backlogs for initial conformity assessments, advantaging firms with early MDR transition completion.
Subscription adherence programs are consolidating procurement authority away from individual clinicians toward health system pharmacy and therapeutics committees. United States integrated delivery networks now negotiate enterprise licenses covering device hardware, connectivity infrastructure, and patient coaching services under single contracts. The bundled model displaces unit-based capital equipment purchasing, compressing vendor margins while locking in multi-year revenue visibility and patient data access rights.
Respiratory Trainer Market Segmentation
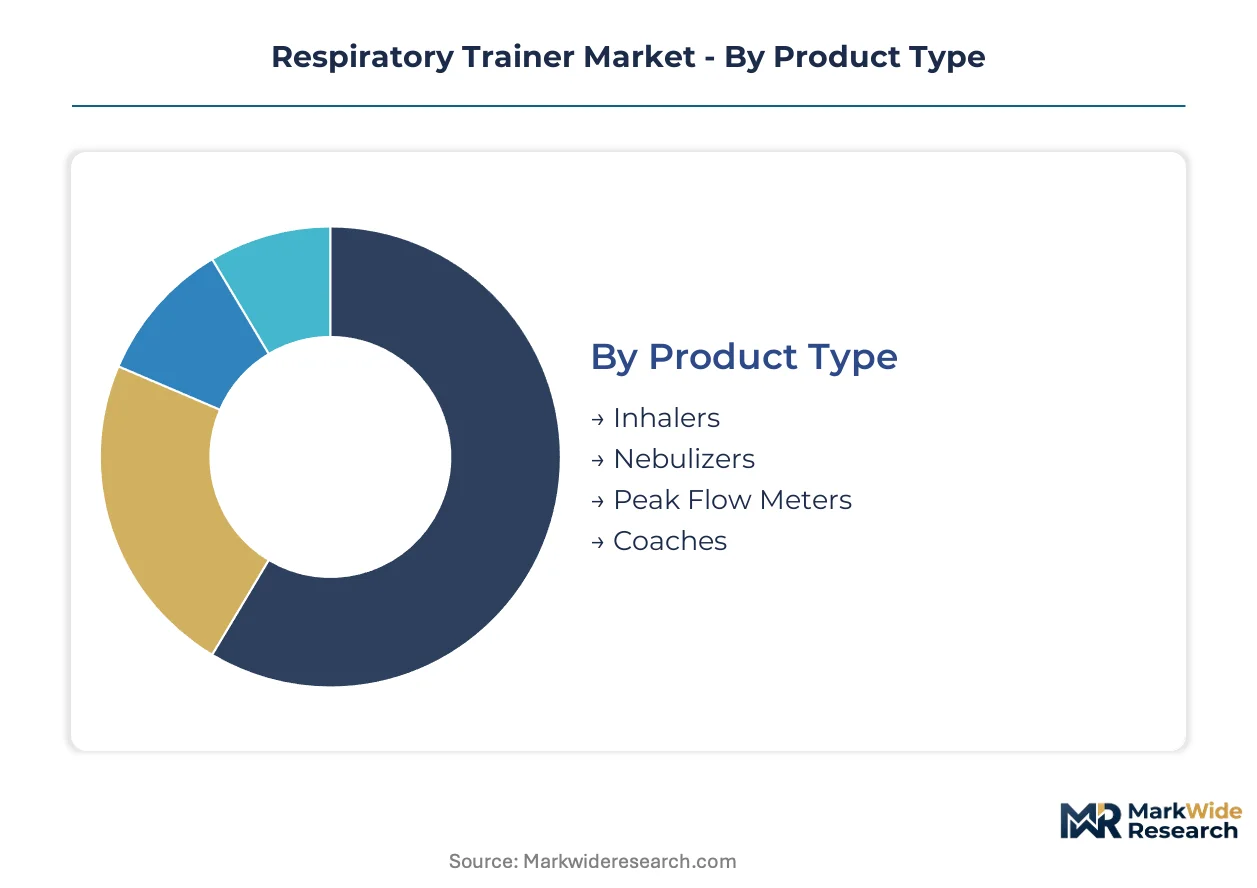
Respiratory trainer procurement patterns diverge sharply across clinical versus domestic channels, with reimbursement pathways and patient acuity determining which configurations dominate each setting. Manufacturers must align product portfolios to these channel-specific requirements to capture margin pools effectively.
Product Type:
Channel mix varies by therapeutic intensity: hospitals favor calibrated electronic systems, while home care gravitates toward portable mechanical units with basic resistance adjustment.
- Inhalers:Metered-dose and dry-powder delivery systems integrate with electronic trainers for synchronized medication administration. Demand concentrates in United States integrated delivery networks where bundled reimbursement covers device-hardware combinations for COPD management.
- Coaches:Breath-controlled gaming interfaces and visual feedback systems convert pulmonary exercises into adherence mechanics. Germany's DiGA fast-track pathway reimburses these through statutory health insurance, accelerating deployment in pediatric asthma protocols.
- Nebulizers:Jet and mesh nebulization systems attach to inspiratory trainers for combined aerosol and resistance therapy in cystic fibrosis centers.
- Peak Flow Meters:Mechanical and electronic spirometry devices face substitution pressure from smartphone-integrated alternatives in adult populations.
By volume, peak flow meters lead due to decades of pediatric asthma protocol embedding. By growth pace, coaches are expanding most quickly on software-enabled reimbursement tailwinds.
Therapy Area:
Cost tier alignment shapes segment access: premium electronic trainers dominate cystic fibrosis and post-surgical rehabilitation, while basic mechanical units serve stable asthma maintenance.
- COPD:Chronic obstructive pulmonary disease requires graduated resistance protocols from acute exacerbation through maintenance phases. United States Medicare remote patient monitoring expansion pulls these devices into home settings with reimbursement covering connectivity infrastructure.
- Cystic Fibrosis:High-frequency oscillating positive expiratory pressure integrates with inspiratory muscle training for airway clearance. Germany and United States academic medical centers deploy these in specialized centers with dedicated respiratory therapy staff.
- Asthma:Pediatric and adult maintenance protocols favor simple mechanical trainers with adherence tracking through mobile applications.
- Lung Rehabilitation:Post-thoracic surgery and COVID-19 recovery programs utilize calibrated electronic systems with telehealth integration.
By patient volume, asthma dominates due to population prevalence. By technology upgrade intensity, cystic fibrosis sits ahead on specialized clinical requirements.
End User:
Customer type determines purchasing authority: hospital procurement committees negotiate enterprise contracts, while home care involves patient self-selection with insurance pre-authorization.
- Home Care:Unsupervised use environments demand fail-safe mechanical designs or electronic systems with remote clinician oversight. Japan's METI Silver ICT subsidies fund municipal procurement through long-term care insurance for aging-in-place initiatives.
- Hospitals:Acute care and step-down units require ISO 13485-certified devices with EMR integration capability through HL7 FHIR protocols.
- Clinics:Outpatient pulmonary practices balance capital equipment costs against per-procedure reimbursement rates.
- Rehabilitation Centers:Post-acute facilities prioritize durable mechanical units with high patient throughput capacity.
By device shipment volume, hospitals lead through concentrated purchasing power. By expansion trajectory, home care is gaining share fastest on post-acute decentralization policies.
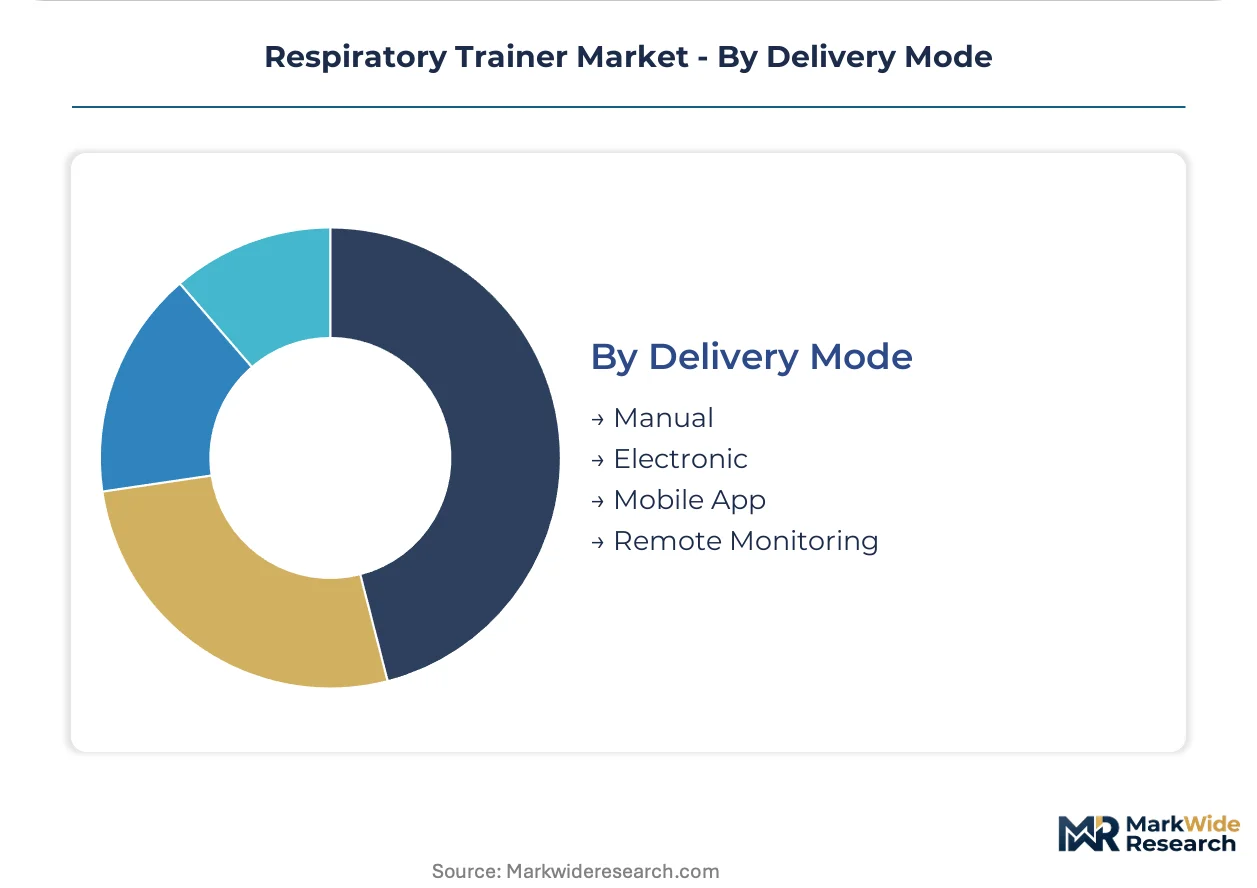
Delivery Mode:
Technology maturity stratifies margin capture: established manual devices compete on price, while connected electronic systems command subscription revenue streams.
- Electronic:MEMS sensor-enabled resistance adjustment with real-time feedback displays and data logging. FDA 510(k) clearance requirements and EU MDR Class IIa reclassification for diagnostic claims extend validation timelines for new entrants.
- Mobile App:Smartphone-tethered sensors replace dedicated hardware for basic spirometry and adherence tracking. Germany's DiGA pathway and United States FDA enforcement discretion for wellness-grade applications create divergent regulatory exposure.
- Manual:Spring-loaded or pressure-threshold mechanical devices with fixed or adjustable resistance settings.
- Remote Monitoring:Cloud-connected systems with automated severity alerts and clinician dashboard integration.
By installed base, manual devices dominate on low cost and zero connectivity infrastructure requirements. By revenue growth slope, electronic systems are climbing the fastest on recurring software subscription attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care settings concentrate purchasing authority in the United States, Germany, and Japan as post-acute care decentralizes. Hospital procurement committees in these markets negotiate enterprise contracts while municipal programs fund aging-in-place deployment.
United States
Medicare remote patient monitoring expansion pulls electronic respiratory trainers into domestic settings with reimbursement covering connectivity infrastructure. FDA 510(k) clearance pathways streamline predicate-based hardware improvements, reducing regulatory capital requirements for mid-tier manufacturers. Academic medical centers in Boston and Philadelphia deploy cloud-resident pulmonary function algorithms to extend monitoring capacity.
Germany
The DiGA fast-track pathway reimburses app-connected trainers through statutory health insurance, accelerating pediatric asthma protocol adoption. EU Medical Device Regulation Annex XVI reclassifies software-enabled diagnostic devices as Class IIa or IIb, mandating notified body intervention. Notified bodies in Berlin and Munich report eighteen-month backlogs for initial conformity assessments.
Japan
METI Silver ICT subsidies fund municipal procurement of home medical devices through long-term care insurance for aging-in-place initiatives. PMDA regulatory frameworks govern electronic trainer approval timelines for diagnostic claims. Tokyo and Osaka clusters concentrate respiratory therapy device distribution networks serving super-aging prefectures.
United Kingdom
NHS integrated care systems negotiate enterprise licenses covering device hardware, connectivity infrastructure, and patient coaching services under single contracts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards for market continuity. London and Manchester pulmonary rehabilitation centers prioritize EMR-integrated electronic systems.
South Korea
MFDS regulatory pathways for software-enabled medical devices accelerate approval for smartphone-tethered respiratory monitoring applications. National health insurance reimbursement expansion for chronic disease management pulls device deployment into home environments. Seoul Capital Area medical device clusters concentrate MEMS sensor integration capabilities.
Respiratory Trainer Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates with respiratory therapy infrastructure and specialized pressure-threshold device manufacturers. Market structure exhibits tiered consolidation with three to five dominant participants controlling hospital procurement channels while mid-tier specialists capture athletic and pediatric niches. Strategic archetypes include sleep-and-respiratory therapy platform owners, inspiratory muscle training specialists, and hospital distribution network anchors. Competitive moves concentrate on EMR integration partnerships and subscription-based adherence program bundling.
Within the diversified health technology tier, Koninklijke Philips N.V. occupies a position exemplifying connected home delivery system integration, while Medline Industries, Inc. anchors North American hospital and clinic procurement through extensive distribution infrastructure. POWERbreathe International Limited represents the specialized pressure-threshold archetype, serving athletic conditioning and clinical rehabilitation segments with calibrated resistance protocols.
| Leading Market Players |
|---|
| Vyaire Medical, Inc. |
| POWERbreathe International Limited |
| Medline Industries, Inc. |
| PN Medical |
| Airofit |
| Koninklijke Philips N.V. |
| IngMar Medical |
| Besmed Health Business Corp |
| Smiths Medical, Inc. |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month component lead times for MEMS pressure sensors concentrate pricing power with Taiwan and South Korea foundries, while downstream device manufacturers absorb inventory carrying costs through extended production schedules. Electronic respiratory trainers command premium positioning against mechanical alternatives as semiconductor input scarcity reinforces tiered margin structures across the value chain.
Pricing Analysis
Current-generation electronic trainers with cloud connectivity and real-time feedback displays price at multiples of prior-generation mechanical spring-loaded devices, while next-generation AI-enabled adaptive resistance systems are entering pilot deployment. Three-tier pricing structure across premium electronic, standard portable, and economy mechanical levels stratifies by certification grade and connectivity capability. Pricing pressure stems from Medicare reimbursement compression for remote patient monitoring hardware, forcing manufacturers to absorb connectivity infrastructure costs. Home care patients exhibit highest price sensitivity, while hospital procurement committees prioritize EMR integration over unit cost.
Supply Chain Analysis
Inventory buffers for MEMS pressure sensors and medical-grade polymers stretch to six-to-nine months as foundry allocation constraints propagate through assembly schedules. Component sourcing concentrates in Taiwan, South Korea, and China for semiconductor inputs, with medical-grade silicone mouthpiece production anchored in Germany and the United States. Raw material dependencies include MEMS sensors, lithium-ion cells for portable units, and ISO 10993-certified polymer compounds. Single-source vulnerability for Taiwan-based MEMS foundries exposes production schedules to geopolitical disruption. Distribution runs through hospital GPO contracts, direct-to-clinic sales forces, and DME supplier networks for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
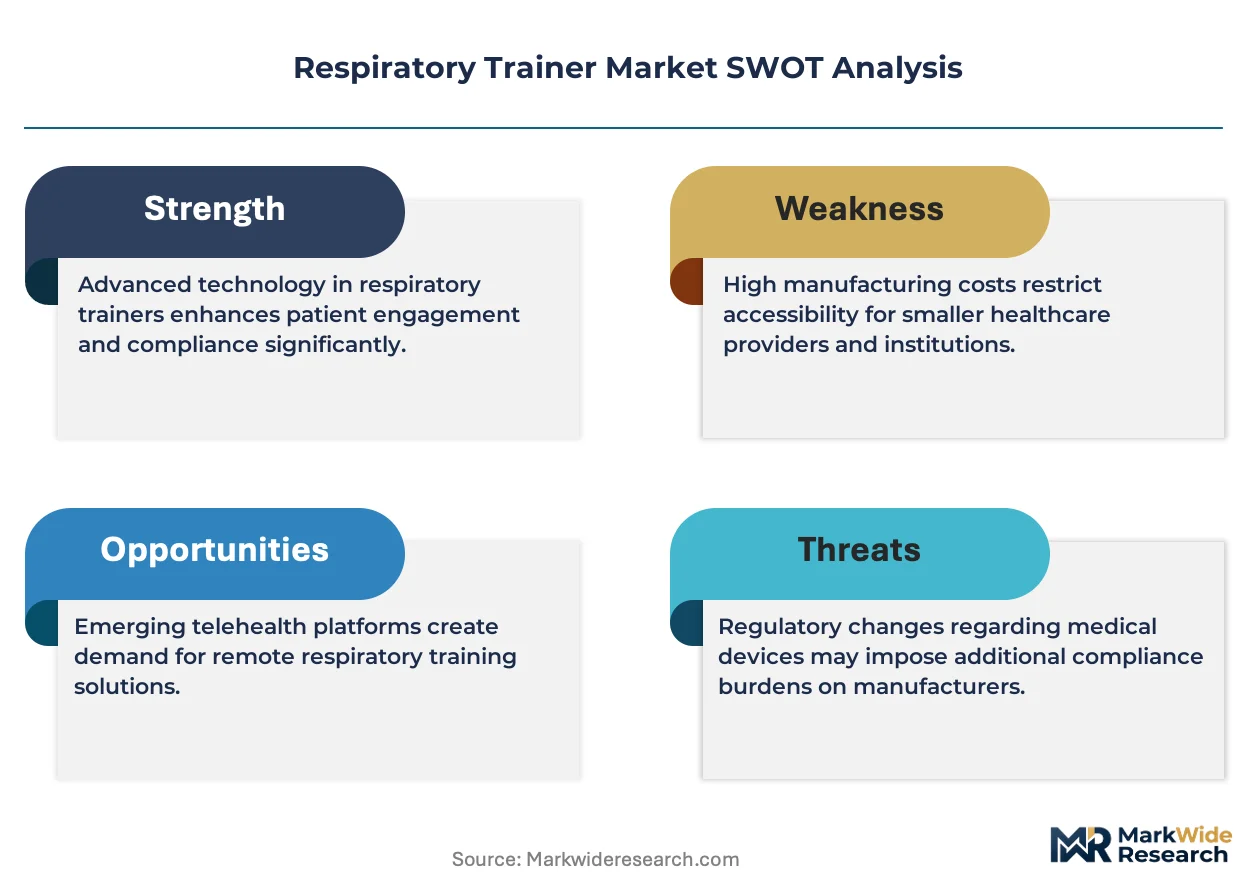
Respiratory trainer incumbents face substitution defense against smartphone-integrated spirometry applications that eliminate standalone hardware from adult asthma protocols. Market positioning requires navigating software-enabled diagnostic claims regulation while preserving hardware revenue attachment.
For Market Incumbents: Secure FDA 510(k) clearance for predicate-based electronic trainers ahead of EU MDR Class IIa reclassification deadlines, locking market access before notified body backlogs extend validation timelines. Anchor hospital procurement relationships through HL7 FHIR EMR integration investments that raise switching costs against emerging software-only competitors. Priority rests on backward integration into MEMS sensor sourcing to buffer Taiwan foundry concentration risk. For New Entrants and Emerging Players: Differentiate on pediatric gamification mechanics that convert breath-controlled exercises into adherence programs, exploiting Germany's DiGA reimbursement pathway for software-enabled devices. White-space targets include Japan's METI Silver ICT municipal procurement channels for aging-in-place respiratory therapy and cystic fibrosis center specialized deployments. Go-to-market execution should prioritize direct contracting with integrated delivery network pharmacy and therapeutics committees over individual clinician sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates with undermonetized respiratory therapy divisions lacking subscription revenue infrastructure. Long-term viability hinges on software-enabled care delivery transformation within a five-to-ten year reimbursement evolution window. Acquisition focus should center on electronic trainer specialists with completed EU MDR technical files and established cloud-resident pulmonary function algorithms. Signal to monitor: CMS remote patient monitoring code expansion or contraction as home-based chronic disease management policy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited predicate-based review accelerates commercialization timelines for MEMS-enabled resistance adjustment systems. |
| EU MDR Technical File Completion | Early notified body engagement bypasses eighteen-month Berlin and Munich assessment backlogs for diagnostic claim devices. |
| Hospital System Partnership | Enterprise license bundling with integrated delivery networks locks multi-year revenue visibility and patient data access. |
| Software Companion Development | DiGA-compliant mobile applications unlock German statutory health insurance reimbursement for breath-controlled adherence mechanics. |
| Reimbursement Strategy | Medicare remote patient monitoring code alignment pulls electronic trainer deployment into domestic settings with connectivity coverage. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with respiratory therapy device executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body registers, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, therapy area, end user, and delivery mode segmentation dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through patient population prevalence projections, reimbursement policy evolution scenarios, and technology substitution elasticity parameters. Segmentation dimensions included product configuration, clinical indication, purchasing channel authority, and connectivity sophistication tier. CAGRs derived from fitted growth curves applied to baseline penetration rates, adjusted for regulatory approval timeline risk and foundry capacity constraints.
Material uncertainties — MEMS sensor supply disruption, EU MDR notified body capacity constraints, CMS reimbursement code recalibration — sit outside the modeled envelope and could materially revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
China Topical Oxygen Therapy Market